
 Platelet Rich Plasma Market | 2026-2036
Platelet Rich Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Rich Plasma Market Intelligence
A capital-intensity divergence between automated system manufacturers and manual kit suppliers is redrawing competitive boundaries in platelet rich plasma. Stryker leverages its orthopedic implant installed base to bundle PRP preparation systems with surgical hardware. Arthrex, Inc. sustains R&D intensity across leukocyte-poor formulations and point-of-care automation. Zimmer Biomet anchors geographic presence through dedicated biologics sales teams aligned with sports medicine surgeons.
Platelet rich plasma comprises an autologous concentrate of platelets suspended in plasma, typically achieving platelet counts four to eight times baseline peripheral blood levels through gradient centrifugation. The preparation serves as a regenerative therapeutic in tissue repair, leveraging secreted growth factors including PDGF and TGF-beta to modulate inflammation and accelerate healing. Orthopedic applications dominate procedure volume, driven by tendon and ligament repair protocols, while dermatology segments expand fastest as cosmetic surgery centers adopt activated PRP for hair restoration and facial rejuvenation. Leukocyte-poor PRP commands premium positioning in intra-articular injections where inflammation control determines reimbursement.
FDA 510(k) clearance requirements govern automated preparation systems and point-of-care devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking of PRP kits. The FDA's Center for Biologics Evaluation and Research monitors autologous blood product claims, creating compliance complexity for manufacturers spanning device and biologic regulatory pathways. Stakeholders must track evolving reimbursement codes for PRP procedures across orthopedic and dermatology specialties to align portfolio investments with payor coverage decisions.
Market Dynamics
Automated centrifugation systems are fragmenting the platelet rich plasma market by collapsing preparation time from laboratory-grade protocols to point-of-care workflows, forcing manual kit suppliers to defend reimbursement positioning against capital equipment bundling.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for automated PRP preparation devices accelerate orthopedic clinic adoption in the United States. Device manufacturers leverage predicate approvals to compress regulatory review cycles.
- Sports medicine protocol integration:Professional athletic franchises and collegiate programs embed autologous biologics into tendon and ligament repair standards. Team physicians drive kit procurement through bundled surgical supply contracts.
- Gradient centrifugation optimization:Double-spin protocols achieve leukocyte-poor platelet concentrates with reproducible platelet counts. Clinical outcomes data supports premium positioning for intra-articular injection applications.
Market Restraints
- Reimbursement code fragmentation:Inconsistent CPT coding across orthopedic and dermatology specialties creates payment uncertainty. Payer coverage decisions vary by indication and preparation method.
- Autologous blood supply constraint:Patient-specific sourcing limits batch production economics. Each procedure requires fresh venipuncture and immediate processing.
- Hyaluronic acid substitution:Viscosupplementation maintains stronger payer coverage for knee osteoarthritis. Competing biologics capture overlapping patient populations.
Strategic Opportunities
- Cosmetic surgery center expansion:Hair restoration and facial rejuvenation protocols drive dermatology segment acceleration. Aesthetic practices seek activated PRP systems with minimal technician training requirements.
- EU MDR clinical evidence pathways:Stricter CE marking requirements under the Medical Device Regulation create competitive moats for manufacturers with robust clinical data. First-movers capture premium positioning.
- Point-of-care automation convergence:Integration of optical sensors with microfluidic separation enables real-time platelet concentration verification. Ambulatory surgical centers adopt closed-system devices to reduce processing variability.
Industry Challenges
- Biologics-device regulatory boundary navigation:Manufacturers face dual oversight from FDA's Center for Devices and Radiological Health and Center for Biologics Evaluation and Research. Claim substantiation requires specialized regulatory expertise.
- Technician training standardization:Variability in blood handling and centrifugation parameters affects therapeutic consistency. Certification programs for clinic staff remain institution-specific without unified standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Rich Plasma Market |
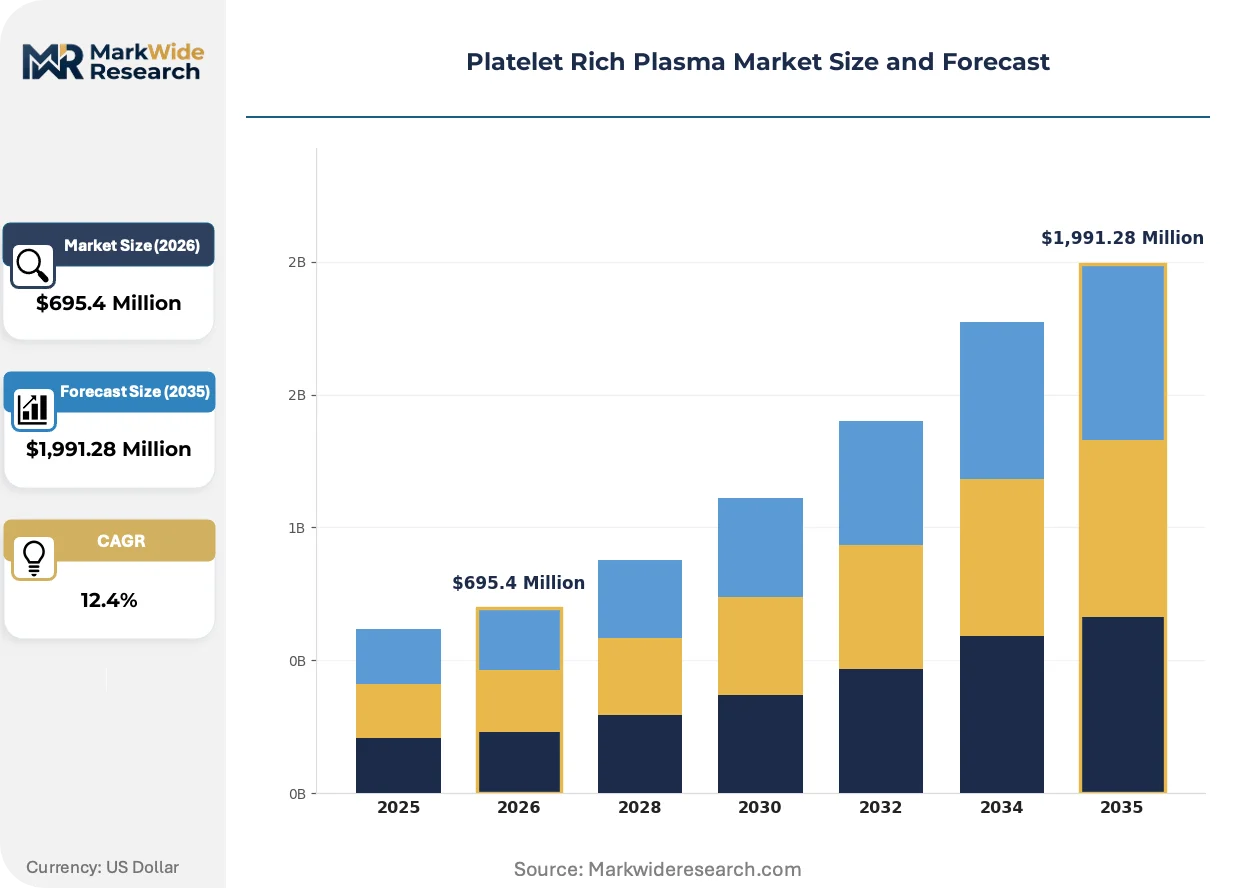
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $1,991.28 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leukocyte-rich PRP, Leukocyte-poor PRP, Activated PRP, Non-activated PRP Application: Orthopedics, Dermatology, Dentistry, Ophthalmology, Urology End User: Ambulatory Surgical Centers, Research Institutes, Specialty Clinics, Cosmetic Surgery Centers Delivery Mode: Manual Preparation Kits, Automated Preparation Systems, Mixed Preparation Techniques, Point-of-Care Devices |
| Companies Covered | Johnson & Johnson Services, Inc., Arthrex, Inc., EmCyte Corporation, Dr. PRP USA LLC, Zimmer Biomet, Stryker, Terumo Corporation, Apex Biologix, Celling Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Rich Plasma Market Strategic Shifts & Innovations
Regulatory convergence and automation economics are compressing traditional preparation workflows while expanding addressable procedure settings beyond hospital-based orthopedic suites.
Microfluidic separation technology is decomposing the capital barrier between laboratory-grade PRP preparation and office-based deployment. Dermatology clinics and aesthetic surgery centers adopt benchtop devices that eliminate manual pipetting steps. The technology is decomposing the historical divide between high-volume hospital labs and low-throughput private practices.
EU MDR Annex XIV clinical evaluation requirements impose prospective data collection obligations on PRP kit manufacturers seeking CE marking renewal. Post-market surveillance mandates extend across the product lifecycle. Orthopedic device suppliers with existing notified body relationships capture timeline advantages over pure-play biologics entrants.
Ambulatory surgical centers now specify outcome-based supply agreements that tie PRP kit pricing to measurable healing metrics. Procurement committees demand platelet concentration verification protocols from vendors. This restructuring concentrates buying power among multi-site ASC networks in the United States.
Platelet Rich Plasma Market Segmentation
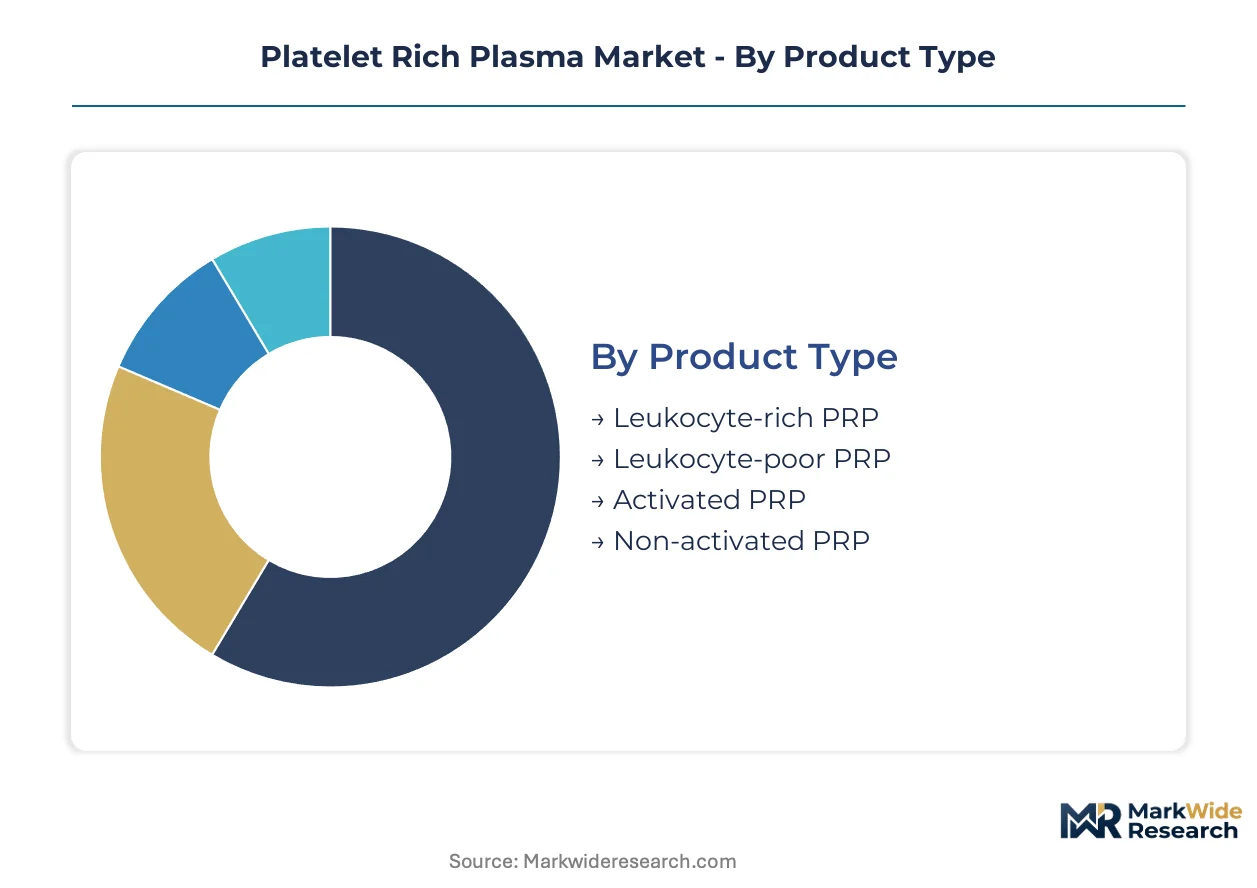
PRP market segmentation reveals distinct procurement patterns across preparation technologies and clinical settings. Product type and delivery mode determine reimbursement positioning, while application and end-user categories dictate regulatory pathway selection and sales force deployment.
Product Type:
Leukocyte-rich and leukocyte-poor formulations flow through divergent channels, with leukocyte-poor commanding premium positioning in orthopedic clinics while leukocyte-rich serves cost-sensitive dermatology practices.
- Leukocyte-rich PRP:Contains elevated white blood cell concentrations alongside platelets, producing inflammatory cytokine profiles suited for chronic wound healing protocols. Demand concentrates in United States wound care centers where Medicare reimbursement favors lower-cost autologous options over engineered biologics.
- Leukocyte-poor PRP:Achieves platelet concentrations four to eight times baseline with minimal leukocyte contamination through optimized gradient centrifugation. Intra-articular injection applications in United States sports medicine clinics drive procurement, with payers requiring inflammation-control documentation for coverage authorization.
- Activated PRP:Thrombin or calcium chloride triggering releases growth factor payloads immediately pre-injection. Cosmetic surgery centers favor activated formulations for facial rejuvenation protocols requiring visible same-day results.
- Non-activated PRP:Relies on endogenous collagen contact for platelet degranulation, extending therapeutic release windows. Dentistry applications in periodontal regeneration favor slower growth factor kinetics.
By volume, leukocyte-rich PRP leads due to lower production costs. By growth pace, leukocyte-poor PRP is ahead as orthopedic clinics standardize intra-articular protocols.
Application:
Cost tier stratification separates high-reimbursement orthopedic procedures from self-pay cosmetic applications, with dentistry and ophthalmology occupying intermediate positions.
- Orthopedics:Tendon, ligament, and cartilage repair protocols dominate procedural volume. United States ambulatory surgical centers bundle PRP preparation with arthroscopic hardware, compressing standalone kit margins.
- Dermatology:Hair restoration and facial rejuvenation drive fastest segment expansion. Aesthetic practices in United States metropolitan markets adopt activated PRP systems with minimal technician training requirements.
- Dentistry:Periodontal regeneration and implant site preparation utilize PRP for bone graft augmentation. Specialty oral surgery clinics in Germany and Switzerland lead European adoption.
- Ophthalmology:Corneal repair and ocular surface regeneration represent emerging applications. Academic medical centers in Japan pilot PRP eye drops for dry eye syndrome.
- Urology:Peyronie's disease and erectile dysfunction protocols remain investigational. United States urology practices await definitive clinical trial outcomes for reimbursement expansion.
Orthopedics generates the highest absolute revenue. Dermatology posts the steepest expansion trajectory as aesthetic procedure volume climbs.
End User:
Customer type determines automation investment thresholds, with ambulatory surgical centers demanding capital equipment integration while cosmetic surgery centers prioritize benchtop simplicity.
- Ambulatory Surgical Centers:Multi-site networks in United States specify outcome-based supply agreements tying kit pricing to healing metrics. Procurement committees mandate platelet concentration verification protocols.
- Research Institutes:Academic medical centers drive protocol standardization and clinical evidence generation. NIH-funded trials in United States establish efficacy benchmarks influencing payor coverage decisions.
- Specialty Clinics:Orthopedic and sports medicine practices represent fastest-growing procurement channel. Bundled contracts with device manufacturers compress standalone kit economics.
- Cosmetic Surgery Centers:Aesthetic practices seek minimal-training PRP systems for hair restoration and facial protocols. Self-pay pricing insulates segment from reimbursement volatility.
Specialty clinics lead by procedure volume. Cosmetic surgery centers are expanding most quickly as aesthetic biologics penetrate mainstream dermatology.
Delivery Mode:
Maturity differentiation separates established manual preparation from emerging point-of-care automation, with mixed techniques serving transition-phase adopters.
- Manual Preparation Kits:Gradient centrifugation with pipette-based platelet isolation dominates cost-sensitive settings. United States dermatology clinics favor manual kits for low-throughput aesthetic applications.
- Automated Preparation Systems:Closed-system centrifugation with optical sensor verification collapses preparation variability. United States orthopedic device suppliers bundle automated systems with surgical hardware.
- Mixed Preparation Techniques:Combines automated centrifugation with manual platelet isolation steps. European clinics under EU MDR transition adopt mixed approaches pending full automation validation.
- Point-of-Care Devices:Microfluidic separation enables real-time concentration verification in office settings. Benchtop deployment expands addressable settings beyond hospital-based laboratories.
Manual kits retain volume leadership. Point-of-care devices are gaining share fastest as microfluidic technology decomposes capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in platelet rich plasma tilt toward net importing in markets with concentrated orthopedic device manufacturing, while production-autonomous regions serve regional demand through domestic kit assembly. Trade flows track regulatory approval timelines, with CE-marked European products penetrating Middle Eastern markets ahead of FDA-cleared alternatives.
United States
Ambulatory surgical centers and specialty orthopedic clinics drive kit procurement through bundled contracts with device manufacturers. FDA 510(k) clearance pathways for automated preparation systems compress regulatory review cycles through predicate approvals. The Dallas-Fort Worth metroplex anchors concentration of sports medicine practices adopting point-of-care PRP protocols.
Germany
Specialty oral surgery clinics in Munich and Stuttgart lead European adoption of PRP for periodontal regeneration and implant site preparation. EU MDR Annex XIV clinical evaluation requirements impose prospective data collection obligations on kit manufacturers seeking CE marking renewal. The Baden-Württemberg cluster concentrates notified body relationships that accelerate regulatory timeline advantages.
Japan
Academic medical centers in Tokyo pilot PRP eye drops for dry eye syndrome and corneal repair applications. PMDA oversight of autologous blood products creates parallel regulatory pathways for device and biologic claims. The Kanto region concentrates ophthalmology research institutes driving protocol standardization for emerging indications.
Switzerland
Swissmedic requirements for clinical evidence support premium positioning of leukocyte-poor formulations in intra-articular injection markets. Geneva and Zurich aesthetic practices adopt activated PRP systems for facial rejuvenation protocols requiring minimal technician training. The country's medical device export infrastructure serves adjacent EU markets under mutual recognition agreements.
Australia
TGA regulation of PRP preparation systems aligns with EU MDR convergence trends, creating pathway efficiencies for multinational manufacturers. Sydney and Melbourne dermatology clinics expand hair restoration procedure volume through self-pay cosmetic applications. Research institutes in New South Wales generate clinical outcomes data influencing regional payor coverage decisions.
Platelet Rich Plasma Market Key Industry Players
Concentration sits with diversified orthopedic device manufacturers bundling PRP systems with surgical hardware portfolios. The vendor base spans three tiers: capital equipment suppliers with installed base leverage, pure-play biologics specialists, and manual kit assemblers serving cost-sensitive settings. Dominant competitive moves include strategic partnerships with ambulatory surgical center networks and technology licensing for microfluidic separation capabilities.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet exemplify capital-intensity advantages through biologics sales team deployment aligned with sports medicine surgeons. Arthrex, Inc. occupies a position bridging device manufacturing and autologous biologics specialization. Among pure-play PRP specialists, EmCyte Corporation and Dr. PRP USA LLC represent kit suppliers defending reimbursement positioning against automated system bundling.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Arthrex, Inc. |
| EmCyte Corporation |
| Dr. PRP USA LLC |
| Zimmer Biomet |
| Stryker |
| Terumo Corporation |
| Apex Biologix |
| Celling Biosciences |
| Others |
Cost & Logistics Intelligence
Batch production economics in autologous blood processing create steep scale advantages for automated system manufacturers, compressing unit costs at high-throughput orthopedic clinics while manual kit suppliers defend price floors through reimbursement bundling in cost-sensitive dermatology settings. This scale divergence concentrates supply relationships around capital equipment vendors in United States ambulatory surgical centers and fragments procurement across low-volume aesthetic practices.
Pricing Analysis
ASC procurement committees anchor pricing stratification across premium automated systems, standard mixed-preparation platforms, and economy manual kits. Price differentiation rests on FDA 510(k) clearance tier and optical sensor verification capability, with premium positioning commanding higher per-procedure fees. Pricing pressure stems from hyaluronic acid substitution in knee osteoarthritis protocols, squeezing mid-tier PRP margins. Dermatology clinics exhibit highest price sensitivity due to self-pay patient bases, while orthopedic bundled contracts show lowest sensitivity through hardware integration.
Supply Chain Analysis
Centrifuge rotor manufacturing and optical sensor calibration create chokepoints tethering production to Germany, United States, and Japan precision component suppliers. Raw material dependencies include medical-grade polycarbonate consumables, anticoagulant reagents, and thrombin activation agents. Single-source vulnerability concentrates in gradient media formulations subject to EU MDR supply documentation requirements. Distribution runs through orthopedic device supplier direct sales forces and biologics specialty distributors serving cosmetic surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics in PRP favor vendors capturing recurring consumable revenue through locked preparation systems, with reagent kit replacement cycles expanding faster than capital equipment replacement in United States ambulatory surgical centers.
For Market Incumbents: Consolidate installed base leverage through backward integration into anticoagulant and activation reagent manufacturing, reducing supplier dependency while capturing consumable margin pools. Deepen point-of-care automation R&D to defend against microfluidic entrants threatening benchtop simplicity. Bundle outcome-based pricing guarantees with multi-site ASC networks to lock procurement relationships against pure-play biologics specialists. For New Entrants and Emerging Players: FDA 510(k) predicate pathway acceleration offers fastest regulatory clearance for automated preparation devices targeting orthopedic clinic expansion. White-space concentration sits in EU MDR-compliant systems for German and Swiss oral surgery clinics awaiting validated automation. Dermatology point-of-care devices with minimal technician training requirements represent the most penetrable segment. Go-to-market through aesthetic distributor partnerships bypasses entrenched orthopedic sales force blockades. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated system vendors with locked reagent supply contracts, generating predictable cash flow streams across replacement cycles. Long-term viability favors manufacturers with dual FDA-EU regulatory capabilities spanning device and biologic claim boundaries. Acquisition targets should demonstrate notified body relationships under EU MDR and established ASC network procurement contracts. The signal to watch is CPT code consolidation across orthopedic and dermatology specialties as payor coverage standardization determines addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Notified body relationships in Baden-Württemberg accelerate German market access timelines. |
| Point-of-Care Automation Development | Microfluidic sensor integration collapses preparation variability for dermatology clinic adoption. |
| ASC Network Partnership | Multi-site procurement committees demand platelet concentration verification protocols from vendors. |
| Reimbursement Strategy Investment | CPT code standardization across orthopedic indications determines United States payor coverage expansion. |
| Backward Integration into Reagents | In-house anticoagulant production captures consumable margins and reduces supplier dependency risk. |
Research Approach
Initial hypotheses were tested against primary input from orthopedic surgeons, ASC procurement managers, biologics regulatory consultants, and cosmetic surgery center operators and refined through secondary validation against FDA 510(k) device databases, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and GPO contract pricing archives. Bottom-up procedure volume estimates triangulated with top-down market sizing across preparation technology tiers.
Variance decomposition across product type, application specialty, end-user facility category, and geographic regulatory cluster shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated ambulatory surgical center expansion rates, EU MDR transition timeline assumptions, and sports medicine protocol standardization trajectories.
Underlying assumptions cover reimbursement code stability, anticoagulant supply continuity, and centrifuge component manufacturing capacity, with deviation risk concentrated in FDA biologics-device regulatory boundary enforcement and EU MDR clinical evidence requirement evolution. Practitioners should keep alternative scenarios live as payer coverage determination methodologies and microfluidic technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market