
 Global Breast Reconstruction Market | 2026-2036
Global Breast Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Reconstruction Market Foresight
Demand from ambulatory surgical centers is shifting upward as payers approve same-day discharge protocols for implant-based procedures. Johnson & Johnson sustains broad channel coverage across hospital systems and outpatient settings. Mentor Worldwide LLC leverages its long-standing silicone gel portfolio to anchor premium positioning. AbbVie Inc. competes through integrated aesthetics platforms spanning facial and body contouring segments.
Breast reconstruction encompasses surgical restoration of breast form following mastectomy, trauma, or congenital absence, typically employing silicone gel or saline-filled implants, autologous tissue transfer from abdominal or gluteal donor sites, or staged expansion with temporary tissue expanders prior to permanent device placement. Implant-based procedures dominate procedural volume due to shorter operative times and reduced donor-site morbidity, while autologous tissue techniques command premium reimbursement for complex cases requiring natural tissue durability. Material composition differentiates competitive positioning: silicone gel implants offer superior aesthetic outcomes in thin-tissue patients, whereas acellular dermal matrix adjuncts expand surgical indications for direct-to-implant reconstruction.
The FDA's ongoing post-approval studies for silicone gel implants mandate long-term safety surveillance, elevating compliance costs for manufacturers while strengthening barriers against unproven entrants. Europe's MDR transition requires renewed clinical evidence for legacy devices, compressing margin pools for firms lacking robust trial infrastructure. Stakeholders must monitor evolving payer policies on pre-pectoral implant placement and fat grafting adjuncts, as coverage determinations will reshape procedure mix and device selection criteria.
Market Dynamics
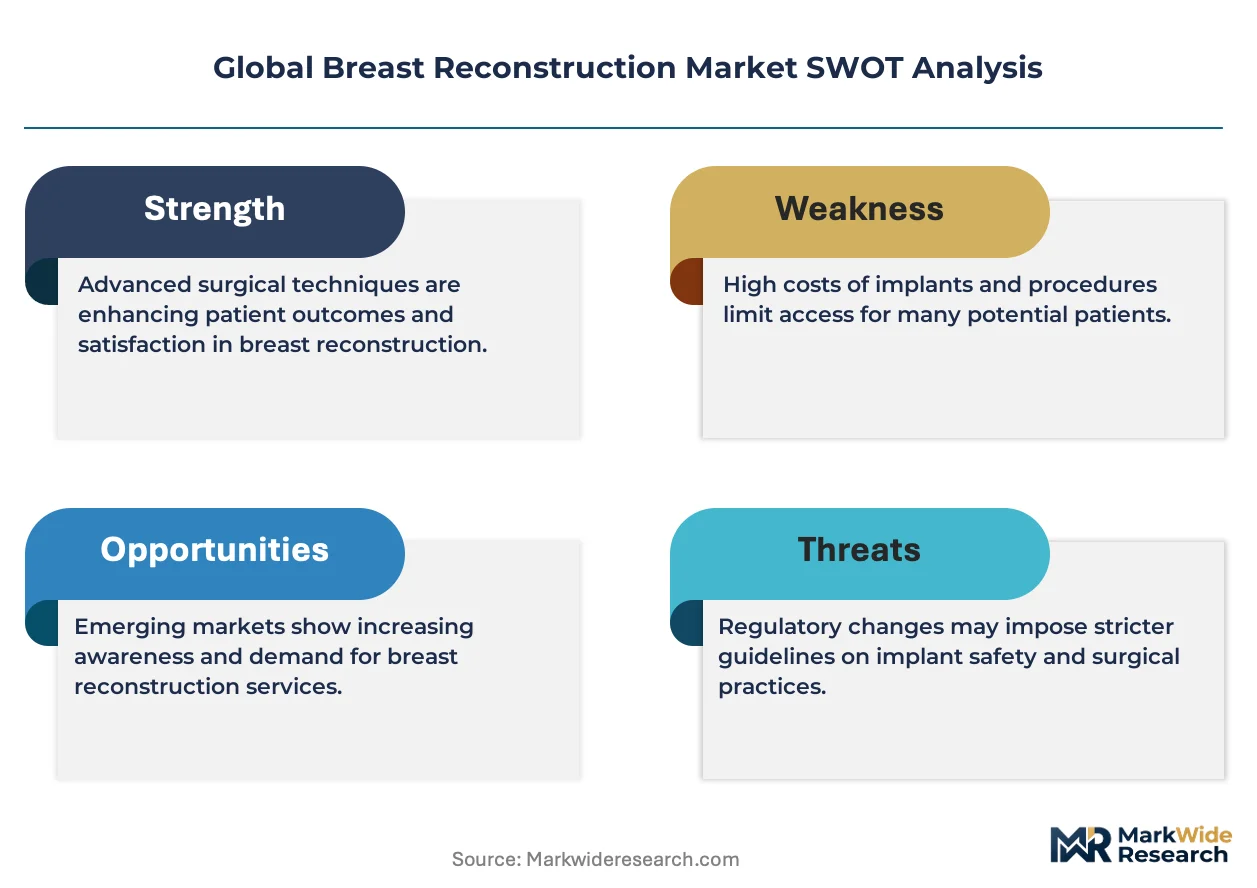
Pre-pectoral implant placement is compressing operative timelines and reshaping surgeon training curricula, while FDA-mandated post-approval surveillance elevates compliance burdens for silicone gel device manufacturers.
Growth Catalysts
- Same-day discharge protocols:Payers in the United States now approve ambulatory surgical center reimbursement for implant-based procedures, shifting volume from inpatient settings.
- MDR clinical evidence requirements:Europe's Medical Device Regulation mandates renewed trials for legacy devices, favoring manufacturers with established trial infrastructure.
- Direct-to-implant techniques:Acellular dermal matrix adjuncts enable single-stage reconstruction, expanding surgical indications for thin-tissue patients.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply concentrates among a handful of chemical suppliers, exposing device makers to input cost volatility.
- FDA post-approval study mandates:Long-term safety surveillance requirements compress margin pools for manufacturers lacking dedicated regulatory affairs divisions.
- Autologous tissue durability premium:Complex microsurgical flap procedures command higher reimbursement but face surgeon capacity constraints, limiting volume scalability.
Strategic Opportunities
- Fat grafting adjunct coverage expansion:Evolving payer policies on lipofilling techniques create white space for combined implant-autologous hybrid procedures.
- Brazil's private insurance market:Post-mastectomy reconstruction penetration remains below OECD averages, presenting volume expansion potential.
- 3D-printed patient-specific implants:Convergence of additive manufacturing and biocompatible polymers enables anatomically matched device geometries.
Industry Challenges
- Microsurgical fellowship pipeline:The extended training timeline for perforator flap techniques constrains autologous reconstruction capacity.
- CE marking transition timelines:Legacy device recertification under MDR creates backlog risks for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Reconstruction Market |
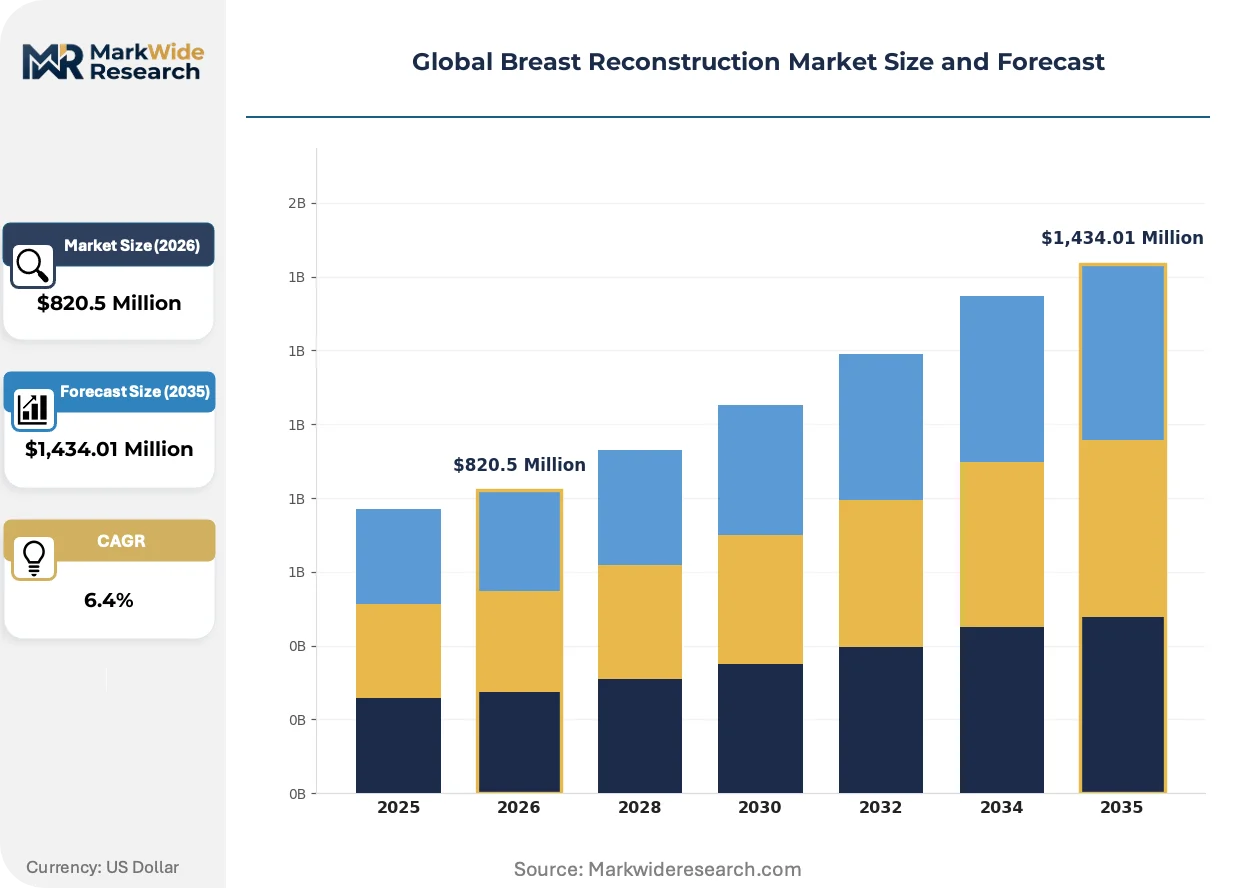
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Implant-Based, Autologous Tissue, Combination Techniques, Nipple Reconstruction, Fat Grafting Material Used: Silicone Gel, Saline, Acellular Dermal Matrix, Muscle Flaps, Tissue Expanders End User: Plastic Surgeons, Reconstructive Clinics, Specialized Hospitals, Ambulatory Surgical Centers Application: Post-Mastectomy, Congenital Deformities, Trauma Correction, Cosmetic Enhancement |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Mentor Worldwide LLC, Sientra Inc., Establishment Labs S.A., GC Aesthetics, POLYTECH Health & Aesthetics GmbH, Integra LifeSciences, Sebbin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Reconstruction Market Shifts & Advancements
Digital surgical planning and bioresorbable scaffold materials are compressing the gap between oncologic resection and aesthetic restoration, while patient-specific implants challenge standardized device portfolios.
Bioresorbable synthetic scaffolds for pre-pectoral tissue support are rewriting operative workflows by eliminating the need for permanent mesh fixation. Academic medical centers in Germany and the United States are piloting these materials in direct-to-implant cases, accelerating adoption curves beyond traditional staged expansion protocols. The technology is compressing the traditional two-year reconstruction timeline into single-procedure outcomes for select patient cohorts.
Europe's MDR transition requires legacy silicone gel implants to submit renewed clinical evidence through notified body review, compressing approval timelines for incremental device modifications. Manufacturers with pre-existing large-scale safety databases retain market access while smaller competitors face portfolio rationalization. The regulation most acutely affects textured surface devices, where long-term follow-up data gaps trigger non-renewal decisions.
Patient advocacy networks now drive surgeon selection through online outcome databases, fragmenting referral patterns previously controlled by hospital system affiliations. Independent plastic surgery practices in Australia and Canada invest in direct-to-consumer educational content to capture these informed patients. This channel shift rewards transparency on complication rates and revision surgery frequencies.
Global Breast Reconstruction Market Segmentation
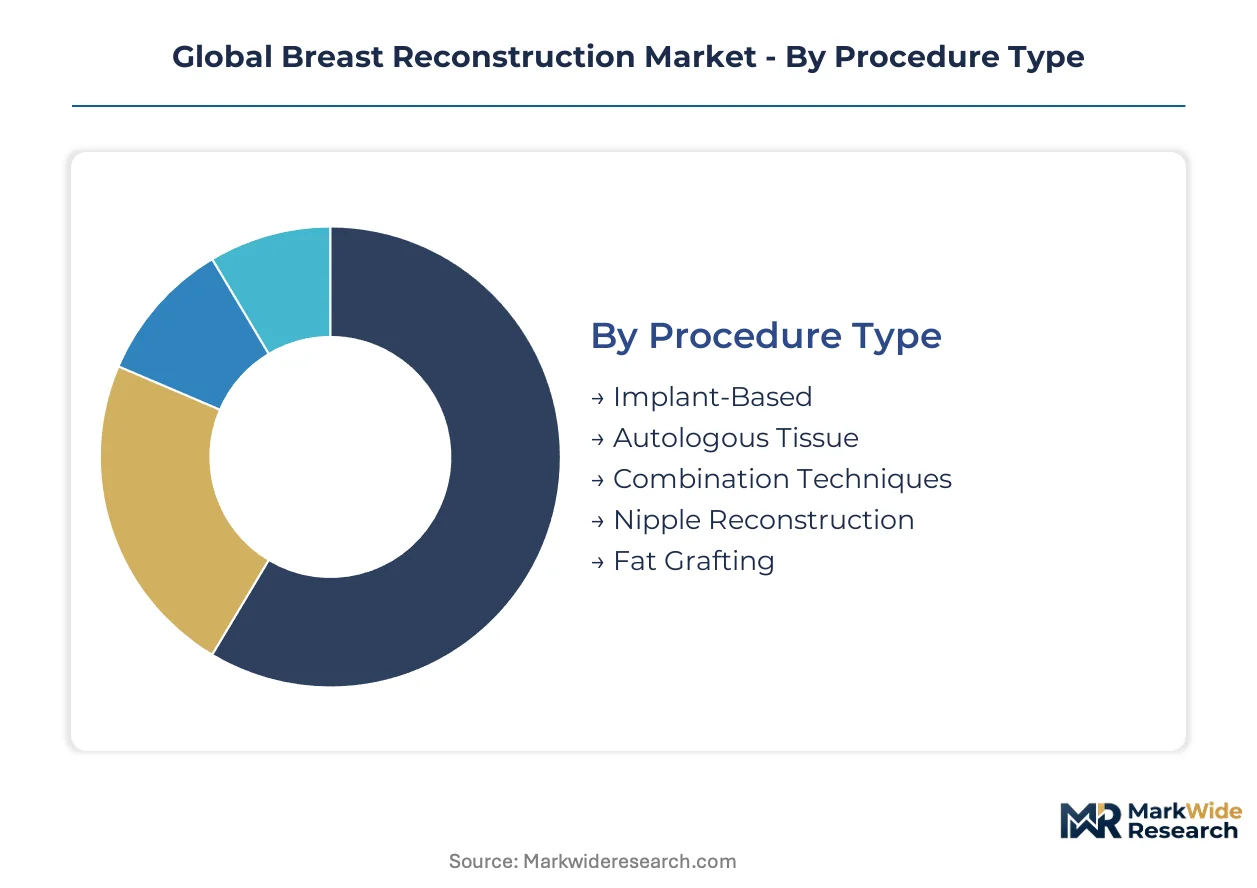
Segmentation in breast reconstruction reveals how procedure economics, material specifications, and care delivery models intersect to determine market access and reimbursement pathways. Manufacturers align product portfolios to specific procedure types and end-user capabilities, while regulatory frameworks vary across material categories.
Procedure Type:
Supply concentration in implant manufacturing favors high-volume, standardized techniques over customized microsurgical approaches requiring extended training pipelines.
- Implant-Based:Silicone gel or saline devices inserted beneath pectoral or pre-pectoral tissue planes dominate procedural volume due to shorter operative times and established surgeon familiarity. United States ambulatory surgical centers now absorb the majority of these cases as same-day discharge protocols expand.
- Autologous Tissue:Microsurgical transfer of abdominal (DIEP), gluteal, or thigh tissue flaps delivers superior long-term durability for thin-tissue patients and radiation-compromised chest walls. Germany and South Korea maintain the deepest specialist capacity, though fellowship training bottlenecks constrain volume scalability.
- Combination Techniques:Hybrid approaches pairing implant placement with fat grafting or acellular dermal matrix support address complex aesthetic requirements.
- Nipple Reconstruction:Local tissue rearrangement or grafting procedures typically follow mound completion, with tattooing adjuncts gaining preference for color matching.
- Fat Grafting:Lipofilling techniques refine contour irregularities and augment implant outcomes, though payer coverage remains variable across OECD markets.
Implant-based procedures absorb the bulk of installed capacity; combination techniques are expanding most quickly as hybrid protocols gain surgical acceptance.
Material Used:
Cost tier differentiation separates premium silicone formulations from commodity saline alternatives, with biologic scaffolds occupying a narrow high-value niche.
- Silicone Gel:Cohesive polymer formulations deliver superior aesthetic outcomes in thin-tissue patients through natural feel and reduced rippling. FDA-mandated post-approval surveillance elevates compliance burdens for manufacturers, compressing margin pools for smaller competitors lacking dedicated regulatory infrastructure.
- Saline:Sterile saltwater-filled devices offer lower unit costs and simpler explantation, retaining share in price-sensitive segments and markets with restricted silicone access.
- Acellular Dermal Matrix:Processed human or porcine dermal scaffolds enable direct-to-implant reconstruction, eliminating staged expansion protocols.
- Muscle Flaps:Vascularized autologous tissue transfers provide durable, radiation-resistant coverage without permanent implant placement.
- Tissue Expanders:Temporary saline devices progressively stretch skin and muscle prior to permanent implant exchange, though pre-pectoral techniques are displacing their necessity.
Silicone gel captures the dominant revenue share; acellular dermal matrix applications are climbing the fastest as single-stage protocols proliferate.
End User:
Customer type stratification reflects divergent capital requirements, with high-acuity settings commanding premium pricing for complex autologous cases.
- Plastic Surgeons:Board-certified specialists in private practice or hospital employment perform the majority of elective reconstructions, with independent Australian and Canadian practices investing in direct-to-consumer channels.
- Reconstructive Clinics:Dedicated facilities co-locating surgical and oncologic services streamline patient pathways in urban United States and German markets.
- Specialized Hospitals:Academic medical centers in the United States and Germany pilot bioresorbable scaffold materials and 3D planning technologies.
- Ambulatory Surgical Centers:Outpatient facilities capture shifting implant-based volume as Medicare and commercial payers approve same-day reimbursement.
Specialized hospitals retain the deepest case complexity; ambulatory surgical centers are gaining share fastest on payer policy alignment.
Application:
Maturity variation across indications creates divergent growth trajectories, with oncologic reconstruction commanding established reimbursement while cosmetic segments face elective spending sensitivity.
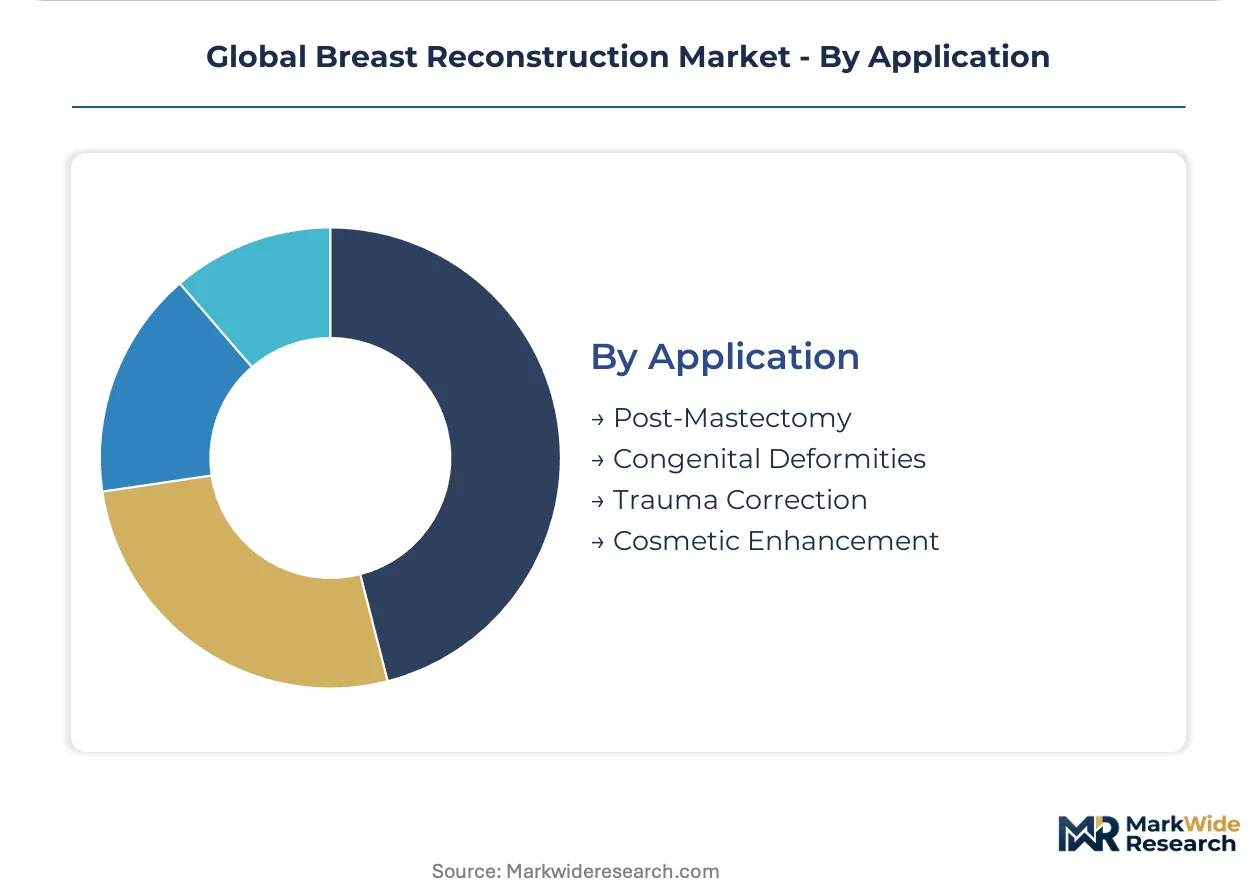
- Post-Mastectomy:Surgical restoration following breast cancer resection represents the foundational indication, with United States penetration rates highest among OECD markets. Patient advocacy networks now drive surgeon selection through online outcome databases.
- Congenital Deformities:Poland syndrome and tuberous breast correction address developmental absence or asymmetry, typically requiring customized surgical planning.
- Trauma Correction:Reconstructive repair following accident or burn injury demands flexible procedural approaches adapted to tissue loss patterns.
- Cosmetic Enhancement:Elective aesthetic procedures outside oncologic pathways face greater price elasticity and discretionary spending constraints.
Post-mastectomy applications anchor procedural volume; congenital deformity correction is expanding most quickly as diagnostic awareness and surgical techniques advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates among US and European chemical suppliers, while procedural demand clusters in high-income markets with established post-mastectomy reimbursement frameworks.
United States
Ambulatory surgical centers now capture the majority of implant-based procedural volume as Medicare and commercial payers approve same-day discharge protocols. The FDA mandates long-term post-approval surveillance for silicone gel implants, elevating compliance costs for manufacturers. Major academic medical centers in Boston and Houston pilot bioresorbable scaffold materials for direct-to-implant reconstruction.
Germany
University hospitals in Heidelberg and Berlin maintain Europe's deepest specialist capacity for complex autologous flap techniques. The MDR transition requires renewed clinical evidence submissions for legacy silicone devices, compressing approval timelines. Notified body backlogs in Munich and Tübingen create market access risks for smaller manufacturers lacking robust trial infrastructure.
Brazil
Private insurance penetration for post-mastectomy reconstruction remains below OECD averages, presenting volume expansion potential for implant-based procedures. ANVISA regulates medical device registration through a risk-based classification system. São Paulo's private hospital networks are expanding dedicated breast reconstruction units to capture underserved demand.
South Korea
Seoul's academic medical centers advance 3D-printed patient-specific implant technologies alongside established silicone gel portfolios. The MFDS maintains stringent premarket review pathways for permanent implantable devices. Gangnam district clinics specialize in aesthetic reconstruction, attracting medical tourism flows from Southeast Asia.
Australia
Independent plastic surgery practices in Sydney and Melbourne invest in direct-to-consumer educational content to capture patients researching surgeon outcomes online. The TGA's post-market surveillance framework aligns with international harmonization initiatives. Patient advocacy networks now drive referral patterns previously controlled by hospital system affiliations.
Global Breast Reconstruction Market Competitive Landscape
Top-tier vendors anchor premium silicone gel portfolios, while mid-scale specialists compete through regional distribution density and price-accessible saline alternatives. The vendor base stratifies across three tiers: diversified medical device conglomerates with aesthetics platforms, dedicated breast implant manufacturers with focused R&D pipelines, and regional fabricators serving price-sensitive markets. Two dominant competitive moves are reshaping positioning: regulatory-driven portfolio consolidation as MDR deadlines compress legacy device recertification timelines, and ambulatory channel expansion as outpatient reimbursement approvals shift procedural volume from inpatient settings.
Within the diversified conglomerate tier, Johnson & Johnson and AbbVie Inc. exemplify integrated aesthetics strategies spanning facial and body contouring segments alongside breast reconstruction. Mentor Worldwide LLC occupies a position as a dedicated silicone gel specialist with established surgeon training infrastructure. These three entities represent contrasting archetypes for navigating FDA post-approval surveillance burdens and European MDR transition costs.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Mentor Worldwide LLC |
| Sientra Inc. |
| Establishment Labs S.A. |
| GC Aesthetics |
| POLYTECH Health & Aesthetics GmbH |
| Integra LifeSciences |
| Sebbin |
| Others |
Supply & Pricing Matrix
Academic medical centers and ambulatory surgical centers command divergent pricing models for breast reconstruction devices, with hospital procurement committees extracting volume discounts while outpatient facilities negotiate bundled procedure rates. This buyer bifurcation rewards manufacturers with flexible contracting infrastructure across care settings.
Pricing Analysis
Price erosion across silicone gel portfolios traces to FDA-mandated post-approval surveillance costs compressing margin pools for smaller competitors. Three-tier pricing structure across premium cohesive gel, standard silicone formulations, and economy saline alternatives separates reimbursement tiers by aesthetic outcome durability. Cost-down pressure on acellular dermal matrix products accelerates because bioresorbable synthetic scaffolds threaten permanent mesh positioning. Ambulatory surgical centers exhibit highest price sensitivity; specialized hospitals prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Explant return flows and device revision logistics create reverse-logistics complexity for silicone gel portfolios, with explanted devices requiring specialized disposal protocols. Medical-grade silicone polymer production concentrates in the United States, Germany, and Japan, with precursor chemical supply anchored in Texas and Bavaria manufacturing clusters. Device assembly draws from platinum-cured silicone elastomers, sterilization packaging films, and patient-specific 3D-printed surgical guides. Single-source vulnerability in medical-grade silicone precursor supply exposes manufacturers to petrochemical feedstock volatility. Distribution runs through hospital system GPO contracts, specialty distributor networks, and direct-to-facility consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breast reconstruction is transitioning from staged expansion protocols to direct-to-implant techniques, with bioresorbable scaffolds displacing permanent mesh fixation and compressing traditional reconstruction timelines.
For Market Incumbents: Acquire regulatory affairs infrastructure capable of managing FDA post-approval surveillance and MDR clinical evidence submissions. Consolidate position by deepening surgeon training partnerships in pre-pectoral placement techniques to defend against bioresorbable scaffold entrants. Lock in ambulatory surgical center GPO contracts before reimbursement policy shifts fully favor outpatient settings. For New Entrants and Emerging Players: Begin with Brazil's private insurance market, where post-mastectomy reconstruction penetration remains below OECD averages and ANVISA registration pathways offer faster market access than FDA or MDR routes. Target hybrid implant-autologous combination techniques as the most penetrable white space, leveraging fat grafting adjunct coverage expansion. Deploy direct-to-consumer educational content through patient advocacy network partnerships to bypass entrenched hospital referral systems. For Investors and Strategic Acquirers: The window for entry favors manufacturers with pre-existing large-scale safety databases capable of MDR legacy device recertification. Long-term viability hinges on portfolio breadth spanning silicone gel, bioresorbable scaffolds, and patient-specific implant technologies. Monitor CE marking transition timelines and notified body backlog resolution as inflection indicators for European market access rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Submission | Legacy silicone device recertification under Europe's MDR preserves market access for established trial infrastructure holders. |
| Bioresorbable Scaffold Development | Elimination of permanent mesh fixation in direct-to-implant cases rewrites operative workflows and reimbursement coding. |
| Ambulatory Surgical Center Partnership | Same-day discharge protocol alignment captures shifting procedural volume from inpatient settings. |
| Surgeon Training Infrastructure | Pre-pectoral placement technique certification creates switching costs and loyalty lock-in. |
| Fat Grafting Adjunct Reimbursement Strategy | Payer coverage expansion for lipofilling techniques opens hybrid procedure billing codes. |
Research Methodology
Document review covered FDA premarket notification filings, EMA MDR transition guidance, and hospital procurement database extracts, complemented by interviews with plastic surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary sources included CMS Medicare reimbursement schedules, ANVISA registration databases, and academic medical center surgical outcome registries. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data.
Historical procedural growth patterns cross-referenced against expert panel input on technique adoption curves and payer policy trajectories. Segmentation modeling spanned procedure type, material composition, end-user facility category, and geographic regulatory cluster across the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for MDR transition friction and ambulatory reimbursement expansion timelines. Forecast inputs incorporated silicone raw material cost indices and microsurgical fellowship pipeline capacity constraints.
Underlying measurement precision varies by segment; implant-based procedural volume carries tighter precision than autologous tissue techniques due to manufacturer shipment transparency. Forecasts reflect documented assumptions regarding MDR notified body capacity and FDA surveillance requirement stability. Practitioners should monitor payer coverage determinations on pre-pectoral placement and fat grafting adjuncts for early signals of procedure mix shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Cytokine Storm Therapy Market