
 Botulinum Toxin Market | 2026-2036
Botulinum Toxin Market Size, Share, and Industry Trends Forecast 2026-2036
Botulinum Toxin Market Analysis
Precision fermentation and recombinant protein engineering is reshaping how botulinum toxin serotypes are manufactured at commercial scale. AbbVie Inc. leverages its Allergan heritage to sustain brand loyalty among aesthetic practitioners worldwide. Hugel Inc. anchors its competitive position through aggressive expansion across Asia-Pacific medical tourism markets. Ipsen Biopharmaceuticals Inc. differentiates via therapeutic neurology applications beyond cosmetic use.
Botulinum toxin comprises neurotoxic proteins produced by Clostridium botulinum bacteria, with Type A and Type B serotypes commercially purified for clinical use through anaerobic fermentation followed by chromatographic refinement to achieve specific potency measured in units per vial. The biologic blocks acetylcholine release at neuromuscular junctions, enabling controlled muscle paralysis for therapeutic and cosmetic indications. Botulinum Type A occupies the dominant revenue position due to its longer duration of effect and broader approved indications across cosmetic and therapeutic segments. Neurological Disorders represents the fastest-expanding therapy area as payers expand coverage for chronic migraine and spasticity management. Aesthetic Centers within the end-user dimension command premium pricing through direct-to-consumer marketing and bundled service offerings.
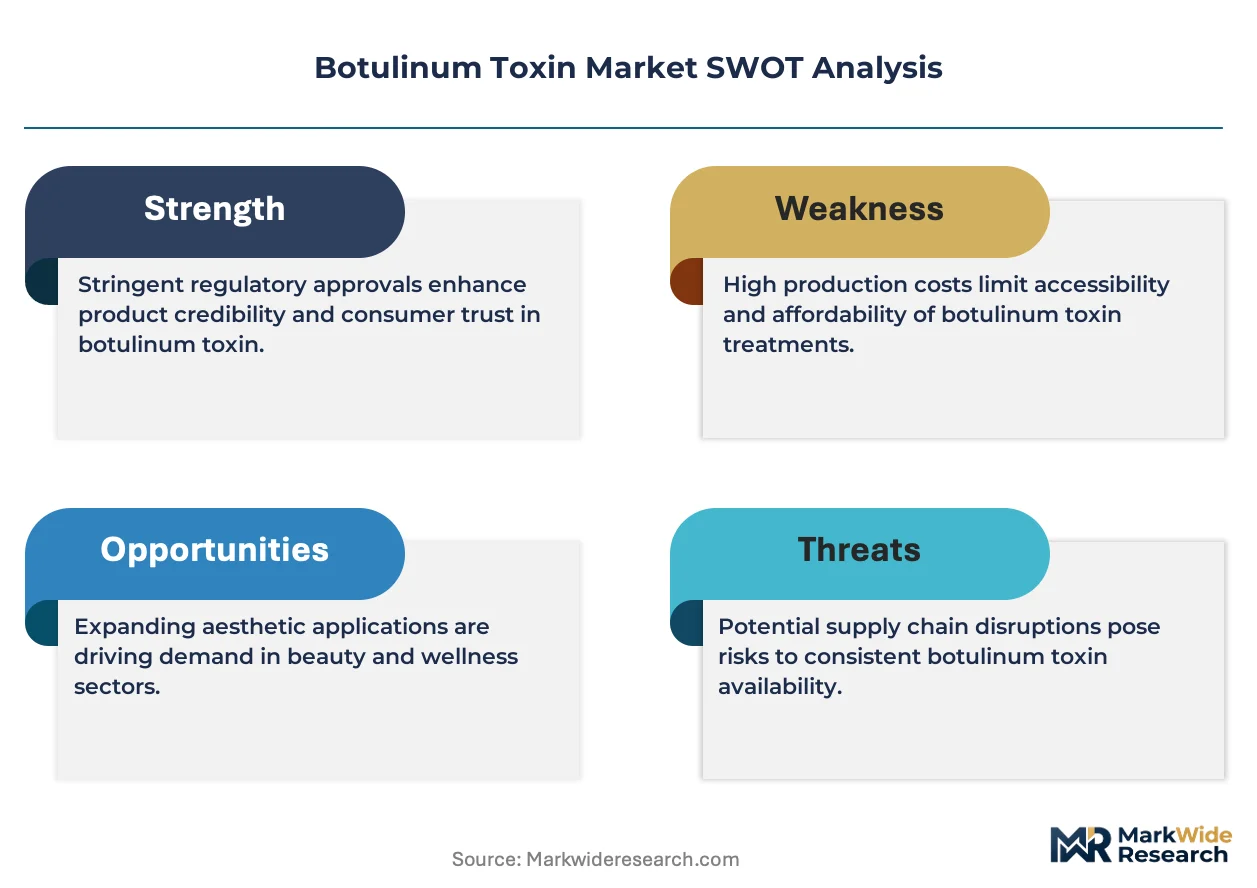
FDA biologics licensing requirements and the EU MDR framework impose stringent purity and potency validation protocols that elevate manufacturing barriers for new entrants. Health Canada and Australia's TGA enforce comparable batch-release testing standards that limit import flexibility. South Korea's MFDS maintains accelerated approval pathways for locally manufactured products, creating asymmetric market access conditions. Stakeholders must monitor regulatory divergence between cosmetic and therapeutic classification pathways as reimbursement policies tighten across major economies.
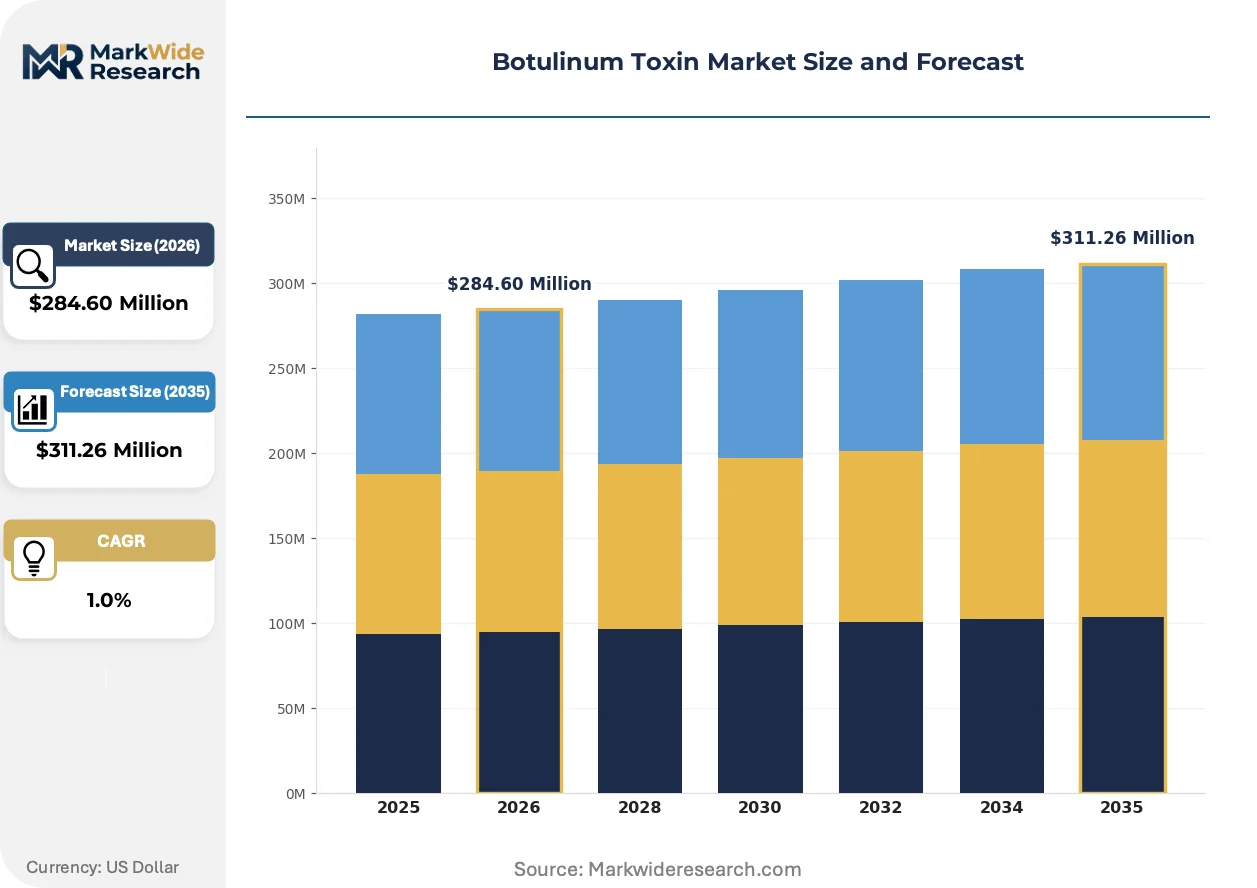
Market Dynamics
Precision fermentation and recombinant protein engineering are compressing manufacturing timelines for botulinum toxin serotypes, while FDA and EU MDR batch-release protocols are elevating purity validation costs for new market entrants.
Growth Catalysts
- EU MDR framework:Harmonized device classification across European member states reduces redundant clinical testing burdens for therapeutic indications, accelerating cross-border commercialization.
- Medical tourism corridors:South Korea's MFDS accelerated approval pathways attract foreign patients seeking cosmetic procedures at price points below US aesthetic centers.
- Neurological disorder prevalence:Expanded payer coverage for chronic migraine and spasticity management in Germany's statutory health insurance system drives therapeutic volume.
Market Restraints
- Biologics manufacturing concentration:Anaerobic fermentation capacity clusters among established producers, limiting supply elasticity during demand surges.
- Chromatographic refinement input costs:Resin and buffer material volatility compresses gross margins for high-potency unit production.
- FDA biologics licensing:Extended potency stability testing timelines delay market entry for novel serotype formulations by 18-24 months versus cosmetic device pathways.
Strategic Opportunities
- Underpenetrated therapeutic verticals:Overactive bladder and hyperhidrosis indications in Japan's aging demographic present reimbursement expansion potential.
- Direct-to-consumer channel innovation:Subscription-based maintenance programs for aesthetic patients reduce clinic acquisition costs and improve lifetime value metrics.
- MFDS local manufacturing incentives:South Korean domestic production requirements create captive supply advantages for Asia-Pacific distribution.
Industry Challenges
- Specialized fermentation technician scarcity:Anaerobic culture maintenance and contamination control expertise concentrates among legacy biologics facilities.
- Legacy cold chain infrastructure:Temperature excursion risks during last-mile distribution to aesthetic centers in tropical climates degrade product potency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botulinum Toxin Market |
| Market Size in 2026 | $284.60 Million |
| Market Size in 2035 | $311.26 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Type A, Botulinum Type B, Botulinum Type C, Botulinum Type E Therapy Area: Cosmetic Applications, Neurological Disorders, Gastroenterology, Pain Management End User: Hospitals, Clinics, Home Care Settings, Aesthetic Centers Administration Route: Intramuscular, Intradermal, Subcutaneous, Others |
| Companies Covered | Merz Pharmaceuticals, Hugel Inc., AbbVie Inc., Medytox Inc., Revance Therapeutics Inc., Ipsen Biopharmaceuticals Inc., Evolus Inc., Daewoong Pharmaceutical Co., Ltd., Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botulinum Toxin Market Emerging Trajectories
Digital integration across manufacturing execution systems and patient-facing platforms is compressing cycle times from batch release to clinic administration, while regulatory divergence between cosmetic and therapeutic pathways is forcing portfolio segmentation strategies.
Recombinant protein engineering platforms are digitizing serotype characterization workflows through high-throughput screening and in-silico binding affinity modeling. Aesthetic center chains in the United States are adopting these tools to customize dosing algorithms for individual musculature patterns. The structural consequence is a compression of formulation development timelines from 36 months to under 18 months for line extensions.
The EU MDR framework's Unique Device Identification requirements are mandating end-to-end traceability for botulinum toxin vials distributed as medical devices. Manufacturers must now integrate serialization infrastructure across packaging lines serving European aesthetic clinics. Therapeutic indications classified as biologics under EMA oversight face less stringent tracking, creating dual compliance architectures within single product families.
Patient self-scheduling through integrated practice management platforms is displacing traditional phone-based appointment coordination at high-volume aesthetic centers. Bundled service packages combining toxin injection with dermal filler or laser procedures now dominate revenue mix in Germany's dermatology clinic networks. This behavioral shift is most visible in metropolitan clusters where direct-to-consumer advertising spend concentrates.
Botulinum Toxin Market Segmentation
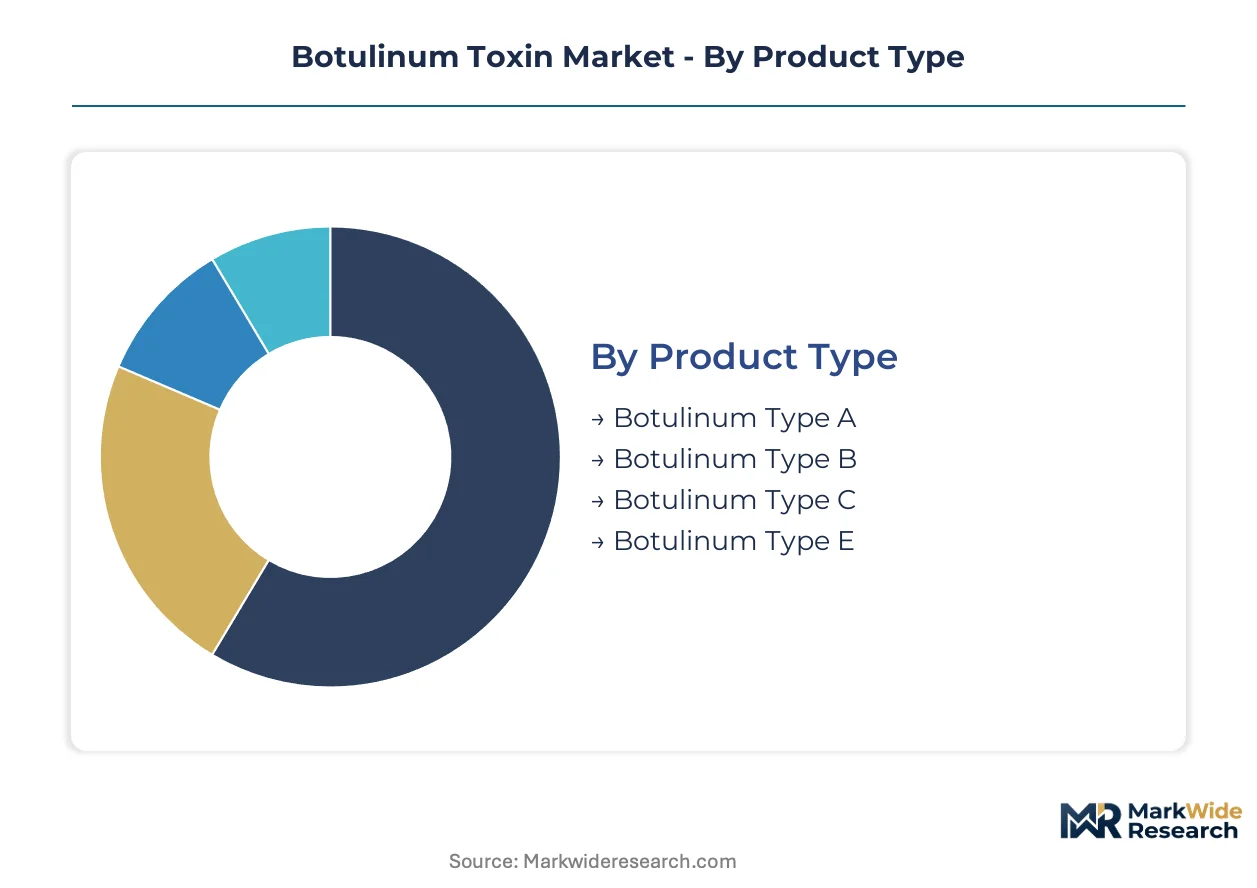
Botulinum toxin manufacturers configure after-sales support networks around potency stability monitoring and cold chain integrity verification. Segment-specific service intensity varies sharply between therapeutic biologics requiring batch traceability and cosmetic devices with simpler compliance needs.
Product Type:
After-sales service intensity peaks with Type A formulations due to extended duration monitoring and repeat dosing calibration requirements.
- Botulinum Type A:Purified neurotoxin complex with 900 kDa molecular weight dominates commercial production through anaerobic fermentation. Demand concentrates in United States aesthetic centers where direct-to-consumer marketing drives premium unit pricing and loyalty program enrollment.
- Botulinum Type B:Smaller 700 kDa protein structure offers faster onset for cervical dystonia with shorter therapeutic window. Germany's statutory health insurance system reimburses Type B for spasticity cases where Type A antibodies have developed, creating a defined therapeutic niche.
- Botulinum Type C:Experimental serotype under preclinical investigation for neuropathic pain modulation.
- Botulinum Type E:Rare serotype with accelerated onset profile reserved for specialized research protocols.
Botulinum Type A holds the largest share; momentum sits with Type B in antibody-resistant patient populations.
Therapy Area:
Application-specific margin structures diverge between elective cosmetic procedures and reimbursed therapeutic indications.
- Cosmetic Applications:Glabellar line and crow's foot treatments command out-of-pocket payment with minimal payer interference. South Korea's medical tourism corridor bundles cosmetic toxin injections with hotel recovery packages, compressing per-procedure margins while scaling volume.
- Neurological Disorders:Chronic migraine prophylaxis and spasticity management require prior authorization and step therapy protocols. Germany's dermatology clinic networks are expanding therapeutic neurology units to capture expanded statutory coverage for chronic migraine.
- Gastroenterology:Achalasia and gastroparesis applications face limited payer familiarity and extended reimbursement negotiation timelines.
- Pain Management:Myofascial pain and neuropathic indications lack standardized dosing protocols across clinical sites.
Cosmetic Applications command the dominant revenue position; Neurological Disorders are climbing the fastest as payer coverage expands.
End User:
Customer type determines procurement sophistication, with hospital systems demanding integrated inventory management versus aesthetic center spot purchasing.
- Hospitals:Integrated delivery networks negotiate formulary placement through group purchasing organizations with strict cold chain documentation. United States health systems are consolidating toxin procurement under pharmacy benefit managers to capture volume discounts.
- Clinics:Independent dermatology and neurology practices purchase through distributor networks with limited storage infrastructure. Germany's clinic networks favor multi-brand stocking to mitigate supply disruption risk.
- Home Care Settings:Self-administration remains restricted due to neurotoxin handling protocols and adverse event liability.
- Aesthetic Centers:High-volume injection facilities prioritize rapid inventory turnover and patient scheduling density over bulk pricing.
Aesthetic Centers generate the highest per-unit margins; Hospitals are gaining procurement leverage through consolidation.
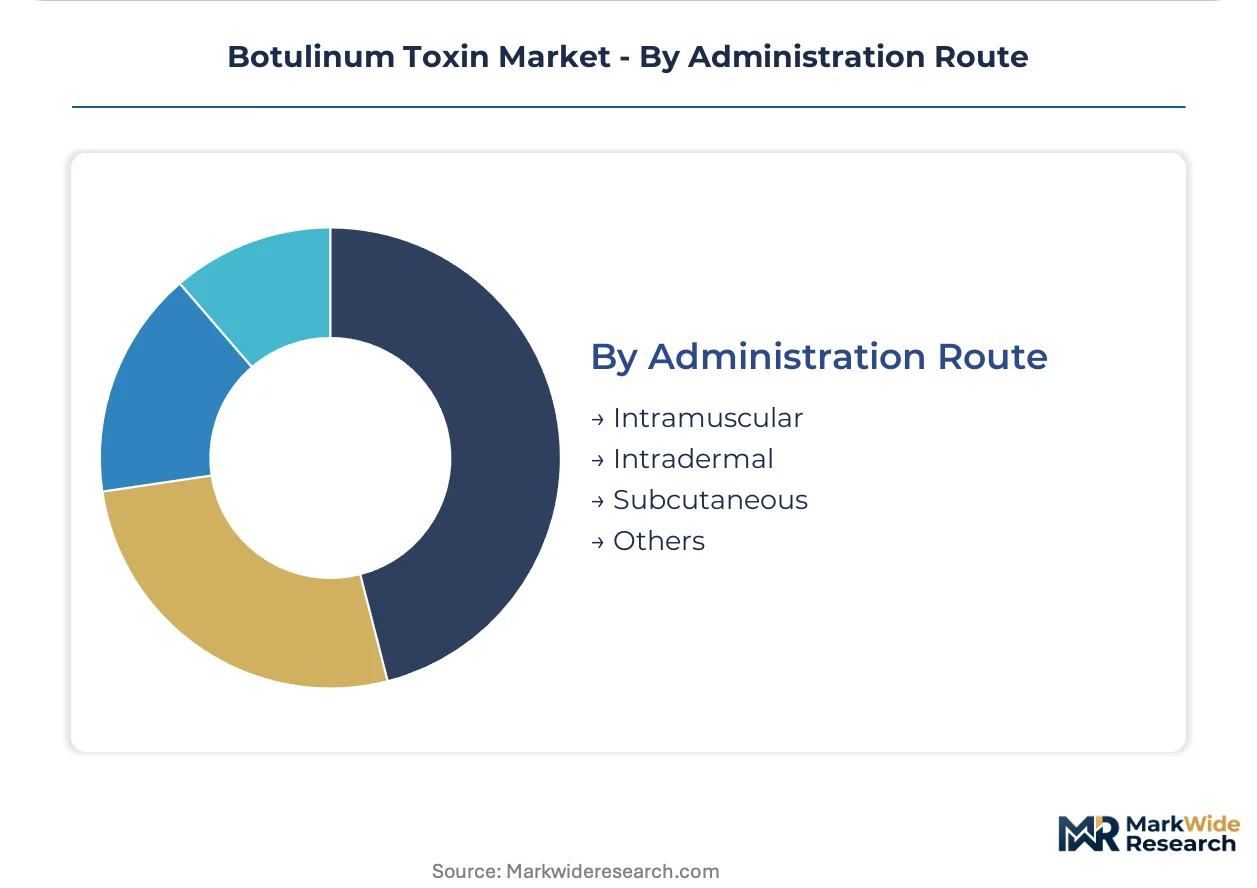
Administration Route:
Route selection drives needle specification, clinician training requirements, and adverse event monitoring protocols.
- Intramuscular:Deep injection technique for large muscle groups in spasticity and cervical dystonia requires electromyography guidance in therapeutic settings. United States neurology clinics are adopting ultrasound-guided intramuscular delivery to improve targeting precision.
- Intradermal:Superficial placement for hyperhidrosis and micro-botox techniques demands specialized micro-needle inventory. South Korean aesthetic centers pioneered intradermal micro-dosing for pore reduction and skin texture improvement.
- Subcutaneous:Intermediate depth placement for facial contouring and platysmal band treatment.
- Others:Investigational routes including intravesical for overactive bladder and intraglandular for sialorrhea.
Intramuscular delivery retains the largest procedure volume; Intradermal techniques are expanding most quickly in cosmetic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports botulinum toxin formulations to medical tourism corridors across Southeast Asia and the Middle East, while Germany supplies therapeutic-grade products to statutory health insurance networks throughout Central Europe.
United States
Aesthetic centers in Los Angeles and Miami drive cosmetic procedure volumes through direct-to-consumer marketing channels. FDA biologics licensing requirements enforce potency stability testing that extends batch-release timelines. The Dallas-Fort Worth metroplex anchors distribution hubs serving independent dermatology practices across the Southwest.
Germany
Statutory health insurance expansion for chronic migraine prophylaxis accelerates therapeutic neurology unit growth in Berlin and Hamburg. EMA oversight harmonizes device classification for cross-border commercialization into neighboring Benelux markets. Bavaria's dermatology clinic networks stock multi-brand inventories to mitigate supply disruption risk from single-source dependencies.
South Korea
MFDS accelerated approval pathways for locally manufactured products attract foreign patients seeking price-competitive cosmetic procedures. Seoul's Gangnam district concentrates high-volume injection facilities bundled with hotel recovery packages. Busan-Ulsan corridor manufacturers supply captive production advantages for Asia-Pacific distribution networks.
Japan
Aging demographics expand reimbursement negotiation potential for overactive bladder and hyperhidrosis indications in Tokyo and Osaka metropolitan areas. PMDA maintains stringent batch-release testing standards that limit import flexibility from non-domestic manufacturers. Kansai region clinics pioneer ultrasound-guided intramuscular delivery for improved targeting precision.
Australia
TGA enforces comparable purity validation protocols to FDA standards, restricting supply elasticity during demand surges in Sydney and Melbourne aesthetic markets. Temperature excursion risks during last-mile distribution to tropical climate clinics in Queensland degrade product potency. Perth's isolated geography creates captive regional supply arrangements with limited import competition.
Botulinum Toxin Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base separates into legacy biologics manufacturers with anaerobic fermentation heritage, mid-scale specialists leveraging recombinant protein engineering, and emerging entrants pursuing MFDS local manufacturing incentives. Two dominant competitive moves define current positioning: geographic expansion through medical tourism corridor partnerships, and portfolio diversification into therapeutic neurology applications beyond cosmetic use.
Within the legacy heritage tier, AbbVie Inc. and Ipsen Biopharmaceuticals Inc. exemplify established anaerobic fermentation operators with extended duration monitoring capabilities. Hugel Inc. anchors the Asia-Pacific medical tourism vector through aggressive corridor expansion. Merz Pharmaceuticals occupies a position bridging German statutory reimbursement networks with aesthetic center procurement. Daewoong Pharmaceutical Co., Ltd. represents the MFDS local manufacturing archetype with captive supply advantages. Revance Therapeutics Inc. and Evolus Inc. sit within the challenger tier targeting direct-to-consumer channel innovation.
| Leading Market Players |
|---|
| Merz Pharmaceuticals |
| Hugel Inc. |
| AbbVie Inc. |
| Medytox Inc. |
| Revance Therapeutics Inc. |
| Ipsen Biopharmaceuticals Inc. |
| Evolus Inc. |
| Daewoong Pharmaceutical Co., Ltd. |
| Galderma |
| Others |
Supply Flow & Price Mechanics
Anaerobic fermentation capacity clusters in South Korea and Germany concentrate upstream margin capture among legacy biologics manufacturers, while downstream pricing power fragments across aesthetic center spot purchasing and hospital formulary negotiations. Chromatographic resin volatility and cold chain integrity costs compress mid-tier producer margins, pushing value toward serotype engineering specialists with captive purification infrastructure.
Pricing Analysis
Current-generation Type A formulations command premium positioning against prior-generation Type B alternatives and next-generation recombinant protein platforms still in clinical validation. Three-tier pricing structure across premium, standard, and economy levels separates Allergan-origin heritage brands from Korean MFDS-approved entrants and emerging local manufacturers. Pricing pressure stems from South Korean medical tourism corridor compression, where bundled hotel-recovery packages erode per-procedure yields. Aesthetic centers in the United States exhibit lowest price sensitivity due to direct-to-consumer marketing premiums, while independent German clinics negotiate aggressively on multi-brand stocking terms.
Supply Chain Analysis
Contract manufacturing concentration rests with AbbVie's Allergan heritage facilities in Ireland, Ipsen's Wrexham anaerobic fermentation site, and Hugel's Busan-Ulsan corridor plants. Geographic supply concentration draws from South Korea, Germany, and the United States for active pharmaceutical ingredient production. Raw material dependencies center on chromatographic resins, anaerobic culture media, and pharmaceutical-grade buffer systems. Single-source vulnerability concentrates in specialized fermentation technician pools and legacy contamination control expertise. Distribution runs through cold chain logistics networks serving aesthetic center chains in metropolitan clusters and hospital pharmacy benefit managers in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where FDA biologics licensing and EU MDR batch-release protocols create 18-24 month entry barriers that protect incumbent position.
For Market Incumbents: Build regulatory data exclusivity moats through extended potency stability testing investments that exceed baseline FDA requirements. Deepen backward integration into chromatographic resin supply through long-term offtake agreements with specialty chemical producers. Capacity expansion in South Korea's Busan-Ulsan corridor captures MFDS local manufacturing incentives and medical tourism volume. Threat response focuses on emerging recombinant protein engineering entrants with compressed development timelines. For New Entrants and Emerging Players: Build out therapeutic neurology white-space targeting antibody-resistant patient populations where Type B reimbursement pathways remain underpenetrated. Japan's aging demographic presents accessible overactive bladder and hyperhidrosis indication expansion with less entrenched incumbent presence. Direct-to-consumer subscription maintenance programs for aesthetic patients offer channel innovation angles that bypass established clinic distributor relationships. Geographic focus on Southeast Asia medical tourism corridors leverages price-competitive positioning against Seoul-centric premium providers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with recombinant protein engineering platforms and existing MFDS manufacturing approvals. Long-term viability across the analysis window favors assets with dual cosmetic-therapeutic portfolio balance and Asia-Pacific distribution infrastructure. Acquisition target archetype combines anaerobic fermentation heritage with digitized serotype characterization capabilities. Signal to watch is MFDS accelerated approval pathway utilization rates as indicator of competitive manufacturing cost positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA biologics licensing accelerates cross-border commercialization into German statutory reimbursement networks. |
| Manufacturing Scale-Up | Anaerobic fermentation capacity expansion in South Korea captures medical tourism corridor demand. |
| Pipeline Diversification | Therapeutic neurology applications beyond cosmetic use access Germany's chronic migraine coverage expansion. |
| Strategic Partnership | Aesthetic center chain alliances in Los Angeles and Miami secure direct-to-consumer channel control. |
| Reimbursement Strategy | Japan's statutory health insurance negotiation for overactive bladder indications opens aging demographic access. |
Methodological Framework
The analysis maps Type A and Type B serotype production, cosmetic versus therapeutic application segments, and intramuscular versus intradermal administration routes, each validated through fermentation facility managers, regulatory affairs leads at biologics manufacturers, aesthetic center procurement directors, and hospital pharmacy benefit managers. Primary interview intelligence combines with secondary validation from FDA biologics licensing databases, EMA centralized procedure filings, MFDS approval registries, and South Korean medical tourism statistics. Bottom-up volume modeling triangulates against top-down market sizing across potency unit production and end-user consumption patterns.
Assumption sets held regulatory pathway timelines and reimbursement policy trajectories fixed while varying medical tourism corridor expansion rates and recombinant protein engineering adoption curves across the projection horizon. Segmentation dimensions modeled include serotype type, therapy area classification, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from unit demand elasticity functions calibrated to payer coverage expansion in neurological disorders and aesthetic procedure frequency in metropolitan clusters. Industry-specific forecast inputs incorporate anaerobic fermentation capacity utilization and chromatographic refinement yield rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Korean challengers or accelerated FDA approval for recombinant platforms would shift outcomes beyond modeled ranges. Regulatory divergence between cosmetic device and therapeutic biologics pathways, plus temperature excursion risks in tropical distribution, constitute primary revision triggers. Quarterly review of MFDS approval velocity and German statutory insurance coverage expansion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Prescription Drugs Market