
 Soft Tissue Repair Market | 2026-2036
Soft Tissue Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tissue Repair Market Analysis
Buyer concentration among hospital procurement networks is pivoting toward centralized value analysis committees that bundle soft tissue repair contracts across orthopedic, general surgery, and cardiovascular service lines. Stryker Corporation leverages its integrated trauma and extremities portfolio to anchor large-system agreements. Smith & Nephew Plc competes through specialized sports medicine anchoring systems that dominate outpatient arthroscopy settings. Arthrex, Inc. differentiates by sustaining direct-to-physician education programs that bypass traditional distributor markups.
Soft tissue repair encompasses surgical restoration of tendons, ligaments, fascia, and dermal layers through implantable scaffolds, mechanical fixation devices, and biologic grafts manufactured from porcine dermis, bovine pericardium, or polylactic acid polymers with pore sizes engineered between 100 and 500 microns to enable fibrovascular ingrowth. The primary commercial purpose centers on restoring mechanical load-bearing capacity while minimizing foreign body response and recurrence rates in hernia, rotator cuff, and anterior cruciate ligament procedures. Sutures and anchors claim the largest revenue share due to their universal application across open and arthroscopic techniques, while allografts represent the fastest-expanding margin pool as processing technologies improve immunogenicity profiles. Knee reconstruction applications generate the highest absolute procedure volumes, though hernia repair commands superior mesh pricing power in ambulatory settings.
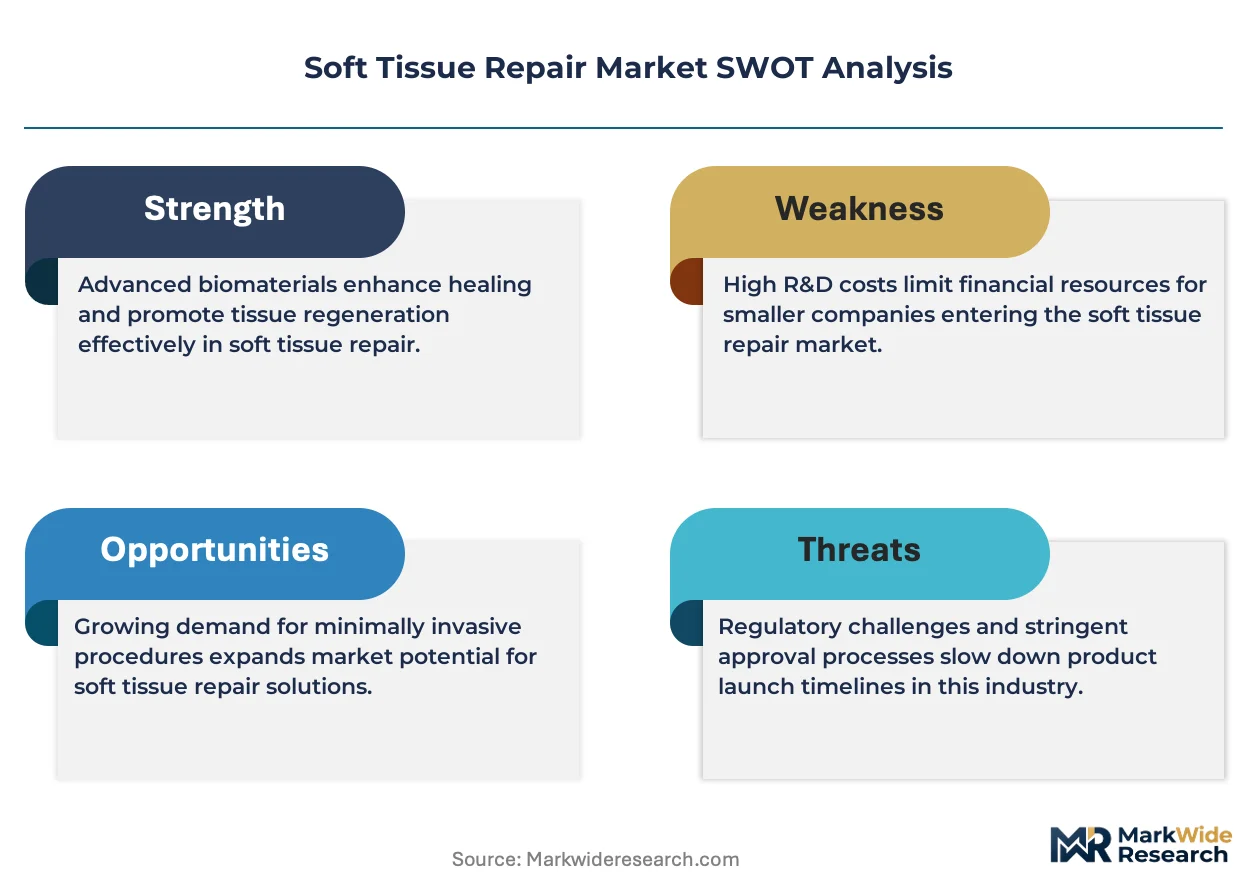
The FDA's 510(k) premarket notification framework and the EU MDR's clinical evaluation requirements impose divergent evidence standards that fragment product launch sequencing across the Atlantic. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification by hospital group purchasing organizations. Stakeholders must monitor evolving reimbursement coding for biologic versus synthetic mesh materials as payers tighten prior authorization criteria.
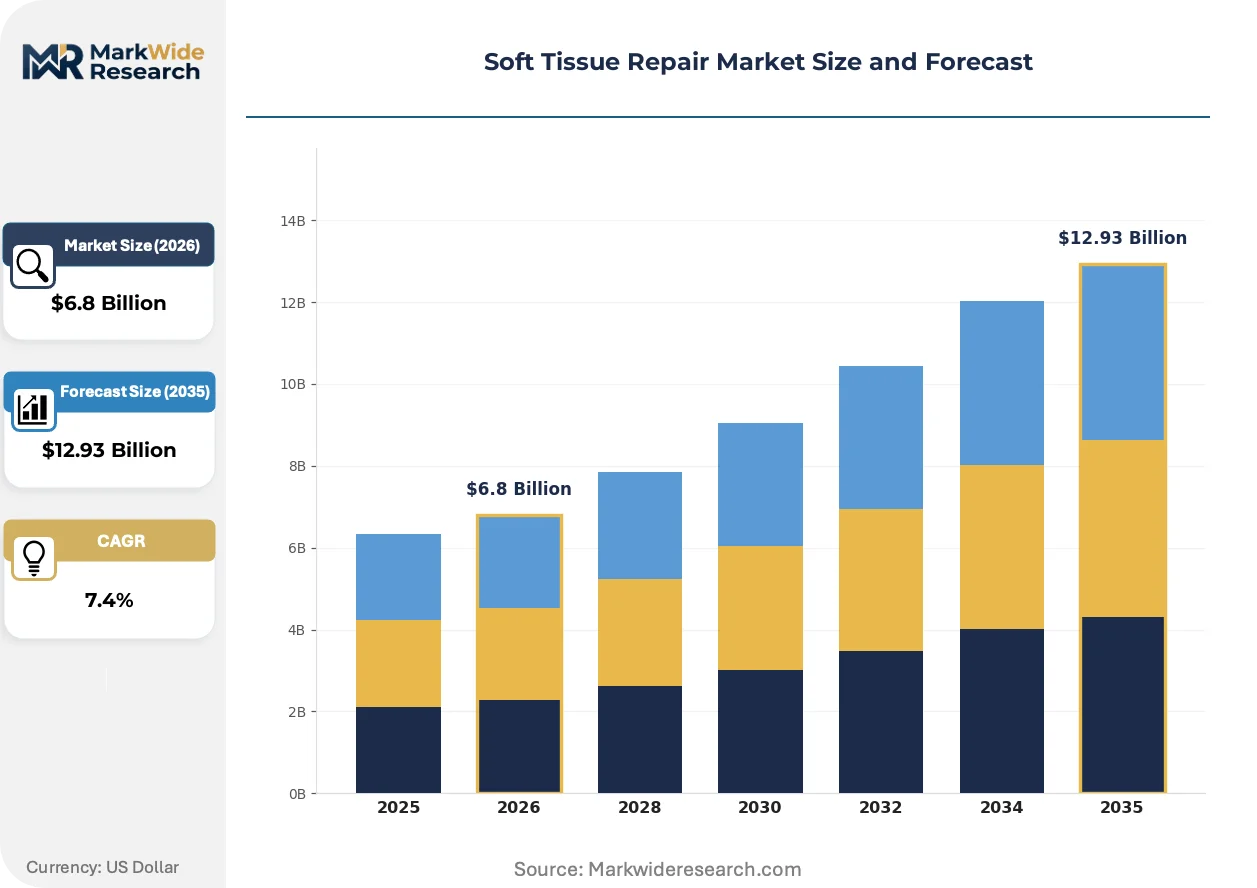
Market Dynamics
Centralized hospital procurement networks are consolidating soft tissue repair purchasing across service lines, compressing vendor margins while elevating biologic mesh suppliers with integrated fixation portfolios. This buyer-side concentration is accelerating qualification barriers and reshaping competitive access.
Growth Catalysts
- Aging surgical populations:Expanding Medicare-eligible cohorts in the United States are driving rotator cuff and hernia procedure volumes, sustaining implant demand through ambulatory surgical centers.
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates for biologic devices are filtering marginal competitors and rewarding manufacturers with robust clinical data packages.
- Arthroscopic technique diffusion:Outpatient sports medicine facilities in Japan are adopting all-suture anchor systems that reduce operative time and accelerate patient turnover.
Market Restraints
- Porcine dermis supply volatility:Tissue bank processing capacity constraints and livestock disease surveillance protocols create raw material intermittency for biologic mesh manufacturers.
- Reimbursement compression:United States commercial payers are narrowing prior authorization criteria for biologic versus synthetic mesh, constraining pricing power in hernia repair.
- Technical fixation limitations:Suture anchor pull-out strength in osteoporotic bone remains a failure mode that limits indication expansion in geriatric populations.
Strategic Opportunities
- Germany's outpatient migration:Bundled payment pilots for ambulatory hernia repair are creating channel openings for disposable fixation kits with simplified instrumentation.
- 3D-printed scaffold convergence:Patient-specific polylactic acid implants with engineered pore architectures are enabling personalized ACL reconstruction workflows in academic medical centers.
- FDA 510(k) pathway streamlining:Predicate device clarity for biologic meshes is shortening time-to-market for processed allograft products with improved immunogenicity profiles.
Industry Challenges
- ISO 13485 audit backlog:Notified body capacity constraints are extending quality management certification timelines and delaying supplier qualification for hospital group purchasing organizations.
- Biologics processing talent scarcity:Aseptic tissue processing technicians with decellularization expertise command premium wages, constraining manufacturing scale-up for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tissue Repair Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repair Patches, Sutures, Anchors, Allografts Application: Knee Reconstruction, Hernia Repair, Shoulder Surgery, Cardiovascular Repair End User: Hospitals, Ambulatory Surgical Centers, Outpatient Clinics, Medical Device Companies Material: Biodegradable Polymers, Synthetic Mesh, Biological Tissue, Composite Materials |
| Companies Covered | Stryker Corporation, Smith & Nephew Plc, Arthrex, Inc., Medtronic Plc, Becton, Dickinson and Company, Johnson & Johnson, Zimmer Biomet, Integra LifeSciences, Baxter International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tissue Repair Market Emerging Trajectories
Biologic-synthetic hybrid scaffolds are displacing pure allograft and synthetic alternatives, creating new performance tiers that reward processing innovation. Material science advances and regulatory clarity are converging to reshape product development pipelines.
Decellularized extracellular matrix coatings on polylactic acid anchors are converging with mechanical fixation to reduce foreign body response while maintaining pull-out strength. Sports medicine surgeons in United States academic centers are adopting these hybrid constructs for revision rotator cuff repairs. The technology is converging with value analysis committee preferences for differentiated products that command premium reimbursement coding.
FDA's updated 510(k) predicate guidance for biologic devices is clarifying equivalence pathways for processed allografts with modified decellularization protocols. Manufacturers are restructuring clinical trial designs to capture longitudinal recurrence data that satisfies emerging evidentiary standards. Small and mid-tier suppliers face disproportionate compliance burdens as predicate device portfolios concentrate among integrated strategics.
Direct-to-physician education platforms are displacing traditional distributor-led training for arthroscopic technique certification. Specialized sports medicine practices in Japan and Germany are accessing virtual surgical simulation modules that reduce learning curves for all-suture anchor deployment. This channel shift is most visible in high-volume outpatient settings where surgeon preference drives implant selection ahead of procurement committee mandates.
Soft Tissue Repair Market Segmentation
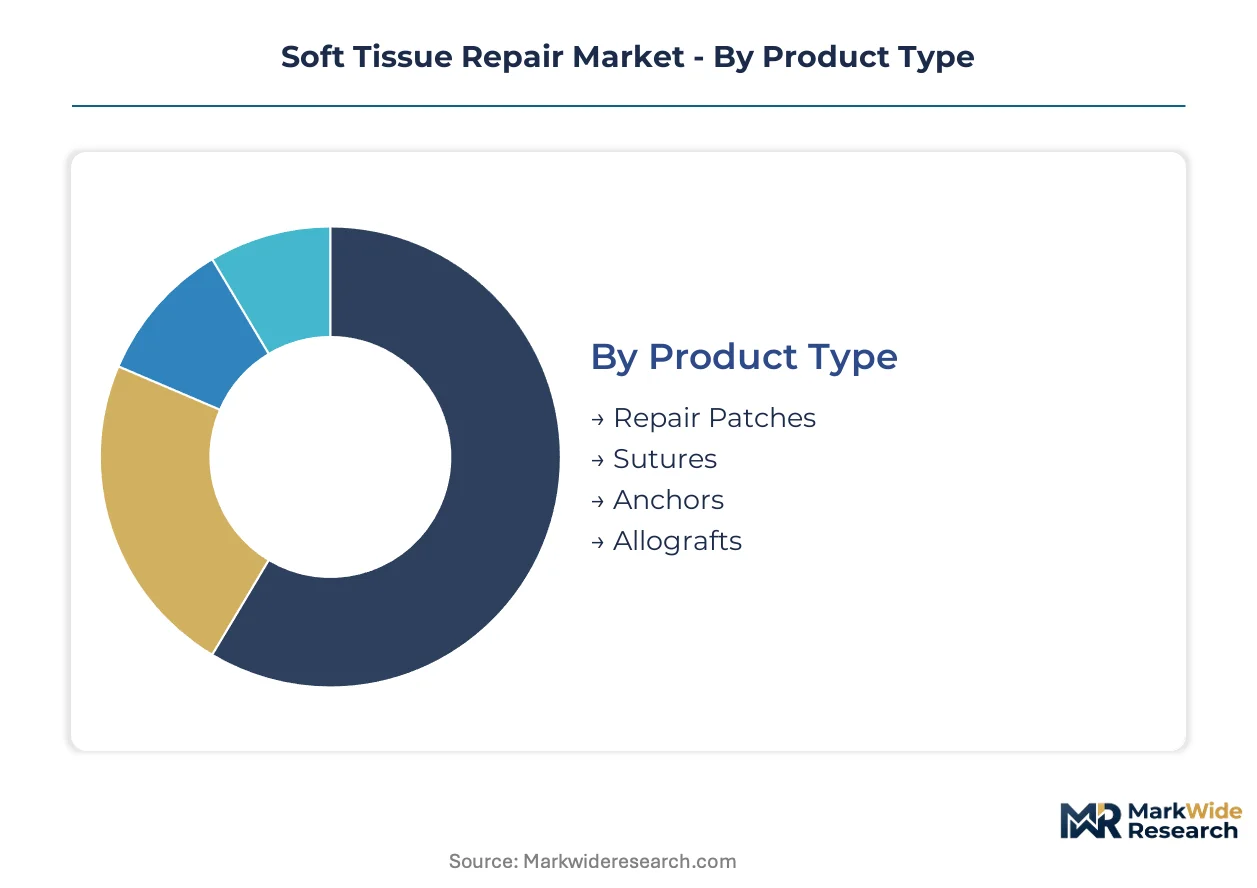
Procurement committees in hospital networks evaluate soft tissue repair portfolios across product, application, and material dimensions to optimize contract bundling. Segmentation clarity enables suppliers to align R&D investment with procedure volume concentration and reimbursement coding trajectories.
Product Type:
Hospital value analysis committees weight fixation reliability and suture inventory consolidation as primary contract determinants.
- Sutures:Absorbable and non-absorbable monofilament and braided configurations serve universal application across open and arthroscopic techniques. Demand concentrates in ambulatory surgical centers in the United States where high-volume hernia and sports medicine procedures sustain bulk purchasing agreements.
- Anchors:Suture anchors fabricated from polyetheretherketone, biocomposite polymers, or allograft bone provide mechanical fixation for tendon-to-bone reattachment. Japanese outpatient facilities are adopting all-suture anchor variants that reduce operative time and instrument sterilization burden.
- Repair Patches:Synthetic and biologic mesh scaffolds reinforce fascial defects in hernia and abdominal wall reconstruction.
- Allografts:Processed human donor tissue provides osteoinductive and osteoconductive properties for ligament and tendon augmentation.
Volume sits with Sutures; growth tilts toward Allografts.
Application:
Procedure reimbursement rates and site-of-service migration reshape demand distribution across anatomical targets.
- Hernia Repair:Mesh-based tension-free techniques address inguinal, ventral, and incisional hernias using synthetic polypropylene or biologic scaffolds. Ambulatory surgical centers in Germany command premium pricing power through bundled payment pilots that favor disposable fixation systems.
- Knee Reconstruction:Anterior cruciate ligament reconstruction and meniscal repair procedures utilize interference screws, suture anchors, and tendon allografts. United States sports medicine volumes sustain the highest absolute implant consumption through dedicated orthopedic surgery centers.
- Shoulder Surgery:Rotator cuff repair and labral reconstruction address tendon avulsions and instability patterns.
- Cardiovascular Repair:Pericardial patches and vascular grafts reconstruct cardiac and peripheral vessel integrity.
Revenue concentrates in Hernia Repair; expansion accelerates fastest in Shoulder Surgery.
End User:
Channel structure fragmentation between inpatient and outpatient settings drives divergent product configuration requirements.
- Hospitals:Integrated health systems perform complex revision surgeries and multi-quadrant hernia repairs requiring advanced biologic mesh portfolios. Centralized procurement networks in the United States are consolidating vendor contracts across orthopedic, general surgery, and cardiovascular service lines.
- Ambulatory Surgical Centers:Medicare-certified outpatient facilities perform low-acuity hernia and arthroscopic procedures with simplified instrumentation kits. Germany's DRG-based bundled payment pilots are accelerating channel migration for routine soft tissue repairs.
- Outpatient Clinics:Office-based settings handle minor wound closure and superficial soft tissue procedures.
- Medical Device Companies:OEM suppliers purchase raw mesh materials and processed allografts for private-label product manufacturing.
Procurement volume flows through Hospitals; ambulatory migration shifts fastest toward Ambulatory Surgical Centers.
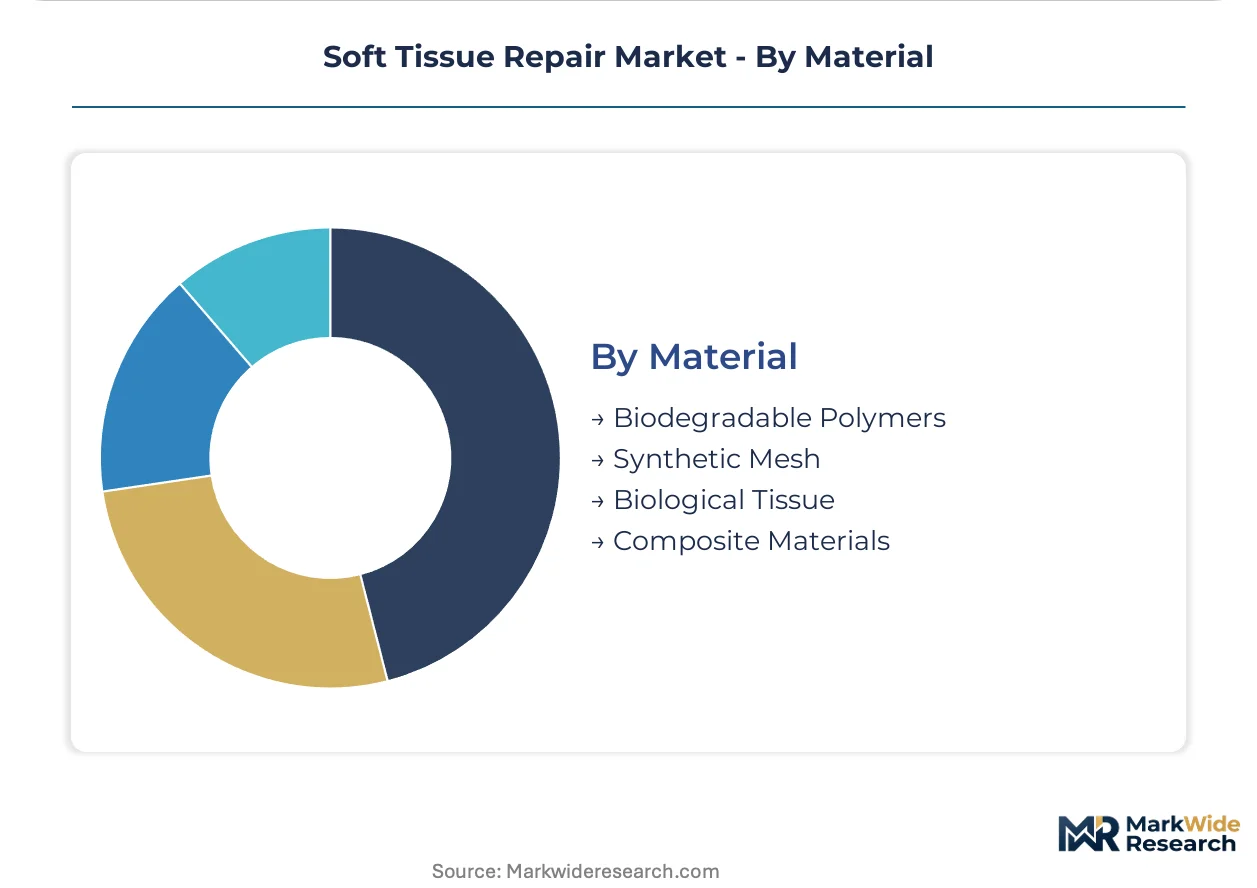
Material:
Foreign body response profiles and degradation kinetics determine clinical indication suitability and pricing tier placement.
- Biological Tissue:Decellularized porcine dermis, bovine pericardium, and human allograft provide extracellular matrix scaffolds that remodel into host tissue. United States academic medical centers are adopting these materials for contaminated or high-risk hernia environments where synthetic mesh contraindications apply.
- Synthetic Mesh:Polypropylene, polyester, and expanded polytetrafluoroethylene constructs offer permanent tensile strength for clean surgical fields. Commercial payers in the United States are narrowing prior authorization criteria, compressing pricing power relative to biologic alternatives.
- Biodegradable Polymers:Polylactic acid, polyglycolic acid, and polycaprolactone resorb over 6-24 months as neotissue organizes.
- Composite Materials:Hybrid constructs combine synthetic strength with biologic coating to modulate inflammatory response.
Clinical utilization favors Synthetic Mesh; biologic substitution expands most quickly in Biological Tissue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine dermis and bovine pericardium sourcing networks concentrate in Midwestern United States livestock processing corridors and Bavarian agricultural zones, anchoring raw material flows for biologic mesh manufacturers serving hospital procurement networks across three continents.
United States
Medicare-eligible cohort expansion and sports medicine procedure migration to ambulatory surgical centers sustain implant demand. FDA's updated 510(k) pathway for biologic devices clarifies predicate equivalence standards for processed allografts. Academic medical centers in Boston and Stanford anchor hybrid scaffold adoption for revision rotator cuff repairs.
Germany
DRG-based bundled payment pilots accelerate outpatient hernia repair migration from inpatient settings. EU MDR clinical evidence requirements filter marginal competitors lacking robust post-market surveillance infrastructure. Medical technology clusters in Tübingen and Leipzig concentrate biologic mesh processing capabilities for Central European hospital networks.
Japan
Aging demographics and outpatient arthroscopy volume expansion drive all-suture anchor adoption. PMDA consultation pathways for novel biologic devices streamline regulatory navigation for processed tissue products. Sports medicine facilities in Osaka and Nagoya deploy virtual surgical simulation modules for technique certification.
United Kingdom
NHS procurement consolidation across orthopedic and general surgery service lines compresses vendor margins while elevating suppliers with integrated portfolios. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for biologic device registration. London teaching hospitals pilot patient-specific 3D-printed scaffolds for ACL reconstruction workflows.
China
Domestic tissue bank capacity expansion and private hospital chain growth reshape biologic graft availability. NMPA medical device classification rules for animal-derived implants impose documentation requirements that favor established processors. Shanghai and Beijing medical centers import decellularization expertise through international clinical partnerships.
Soft Tissue Repair Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid scaffold and 3D-printed construct niches. The vendor base concentrates around integrated strategics with predicate device portfolios and specialized sports medicine pure-plays. Three archetypes dominate: diversified orthopedic conglomerates anchoring multi-service-line contracts, sports medicine specialists commanding outpatient arthroscopy preference, and tissue processors with captive biologics supply. Competitive moves center on portfolio bundling across fixation and mesh categories and direct-to-physician education platform deployment.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet represent integrated strategics with trauma and extremities portfolios that anchor large-system agreements. Smith & Nephew Plc exemplifies the sports medicine specialist archetype, occupying a position in outpatient arthroscopy settings where surgeon preference drives implant selection ahead of procurement mandates. These three entities sit within distinct competitive vectors—scale-driven contracting, technique-driven preference formation, and biologics processing integration—that collectively define market access conditions.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew Plc |
| Arthrex, Inc. |
| Medtronic Plc |
| Becton, Dickinson and Company |
| Johnson & Johnson |
| Zimmer Biomet |
| Integra LifeSciences |
| Baxter International, Inc. |
| Others |
Supply Flow & Price Mechanics
Decellularization protocol standardization is compressing processing cost differentials between biologic mesh tiers while simultaneously concentrating supply among tissue banks with validated quality systems. This production-method transition forces mid-tier manufacturers to absorb margin compression or surrender hospital procurement network qualification.
Pricing Analysis
Warranty and clinical outcome guarantees are increasingly bundled into premium biologic mesh contracts while synthetic alternatives trade on unbundled per-unit pricing. Three-tier pricing structure across premium, standard, and economy levels separates predicate-device portfolios with longitudinal recurrence data from unvalidated alternatives. Pricing pressure stems from United States commercial payers narrowing prior authorization criteria for biologic versus synthetic materials. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with value analysis committees demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Midwestern United States livestock corridors and Bavarian agricultural zones anchor hub-and-spoke patterns for processed tissue feedstocks. Raw material flows draw from porcine dermis harvesting networks, bovine pericardium collection points, and human tissue bank partnerships. Single-source vulnerability concentrates in aseptic processing technicians with decellularization expertise. Distribution runs through hospital group purchasing organization consolidated contracts with direct-to-facility logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic tissue processing technician scarcity props pricing across biologic mesh tiers, constraining manufacturing scale-up regardless of raw material availability.
For Market Incumbents: Anticipate EU MDR post-market surveillance mandates filtering marginal competitors and accelerating predicate-device portfolio consolidation. Defend hospital system anchoring by deepening captive biologics supply through tissue bank partnerships. Prioritize ISO 13485 quality system investments that exceed notified body audit backlogs and compress competitor qualification timelines. For New Entrants and Emerging Players: Virtual surgical simulation platforms offer route-to-market independence from distributor markups and procurement committee gatekeeping. Target Germany's outpatient bundled payment pilots with disposable fixation kits designed for simplified ambulatory instrumentation. Penetrate through direct-to-physician education that bypasses traditional channel structures in Japanese sports medicine facilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated orthopedic conglomerates seeking biologics processing integration. Long-term viability favors tissue processors with validated decellularization protocols and predicate device portfolios spanning hernia and shoulder applications. Monitor FDA 510(k) predicate guidance clarity as inflection indicator for processed allograft product timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements reward manufacturers with robust post-market surveillance infrastructure in Tübingen and Leipzig clusters. |
| Hospital System Partnership | Centralized value analysis committees in United States integrated health systems bundle contracts across orthopedic and general surgery service lines. |
| Backward Integration into Tissue Processing | Captive supply of decellularized porcine dermis insulates against livestock disease surveillance protocol disruptions and raw material intermittency. |
| Software Companion Development | Virtual surgical simulation modules reduce learning curves for all-suture anchor deployment in Osaka and Nagoya outpatient facilities. |
| Reimbursement Strategy | Payer prior authorization criteria differentiation between biologic and synthetic mesh materials shapes pricing power in ambulatory hernia repair. |
Methodological Framework
Multi-period observation of hospital procurement contract structures, regulatory submission timelines, and tissue bank processing capacity anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body audit disclosures, hospital procurement databases, and CMS Medicare reimbursement coding updates. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Segment-weighting across product type, application, end user, and material dimensions informed the analytical framework throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to arthroscopic technique adoption rates and ambulatory surgical center migration patterns. Forecast inputs incorporated biologic mesh pricing trajectories and synthetic mesh reimbursement compression indicators.
The model holds under stable regulatory equivalence pathways and predictable tissue bank processing capacity; deviation in FDA predicate device guidance or livestock disease outbreaks would shift supply-side constraints. Forecasts reflect documented assumptions regarding payer prior authorization evolution and EU notified body audit throughput. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market