
 Atrophic Scar Treatment Market | 2026-2036
Atrophic Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Atrophic Scar Treatment Market Outlook
Clinical-grade efficacy thresholds is rotating the competitive baseline upward, forcing mid-tier offerings to demonstrate equivalence through controlled outcome studies. Lumenis leverages its installed base of fractional laser platforms to sustain recurring consumable revenue across dermatology networks. Merz Pharma anchors European market access through its dermal filler portfolio, while Cynosure competes on speed-to-treat metrics with multi-wavelength workstation designs.
Atrophic scar treatment encompasses modalities that remodel dermal collagen architecture through controlled thermal injury, biostimulation, or volumetric replacement, with fractional laser systems typically operating at 1540 nm or 1550 nm wavelengths to achieve tunable penetration depths up to 1400 micrometers. Laser therapy and RF microneedling command premium positioning due to superior histologic outcomes in deep boxcar and ice-pick scar morphologies. Topical treatments occupy volume leadership through direct-to-consumer channels, though margin pools concentrate in minimally invasive delivery modes administered within dermatology clinics.
The US FDA and the EU MDR impose divergent evidentiary requirements on energy-based aesthetic devices, with the MDR's stricter clinical evaluation reports lengthening approval timelines for fractional laser and RF microneedling platforms. Health Canada's PMRA and Japan's PMDA maintain additional jurisdiction-specific labeling standards that shape product configuration for North American and Asian launches. Stakeholders must monitor regulatory harmonization progress between FDA 510(k) pathways and MDR technical documentation to anticipate which technology categories will face compressed go-to-market cycles versus prolonged conformity assessment.
Market Dynamics
The FDA's tightening predicate-device pathways for energy-based aesthetic equipment is compressing approval timelines and forcing manufacturers toward de novo classification routes with heavier clinical burdens.
Growth Catalysts
- EU MDR Clinical Evaluation Requirements:Stricter technical documentation for fractional laser platforms is filtering out marginal competitors and consolidating share among established CE-marked portfolios.
- Combination Protocol Adoption:Dermatology clinics are pairing laser resurfacing with biologic adjuncts, expanding per-patient revenue and treatment efficacy thresholds.
- Out-of-Pocket Aesthetic Spending:United States consumers demonstrate sustained willingness to pay premium prices for minimally invasive scar revision procedures.
Market Restraints
- Capital Equipment Intensity:Fractional laser and RF microneedling platforms require substantial upfront investment, limiting clinic penetration in price-sensitive secondary markets.
- Input Supply Concentration:Erbium-doped and thulium fiber laser sources concentrate among a handful of German and Japanese optical component suppliers.
- Technical Efficacy Ceiling:Deep ice-pick scar morphologies remain refractory to non-ablative modalities, constraining addressable scar severity segments.
Strategic Opportunities
- Underpenetrated Indian Metro Markets:Tier-1 cities show nascent demand for aesthetic dermatology with limited installed base of fractional laser systems.
- Home-Use Device Channel:Direct-to-consumer microneedling pens and LED masks are capturing maintenance-phase patients between clinic visits.
- Biologic-Stimulator Convergence:Platelet-rich plasma and exosome adjuncts are creating combination therapy protocols with differentiated positioning.
Industry Challenges
- Laser Safety Certification Bottlenecks:Certified laser safety officers remain scarce in expanding clinic networks, constraining treatment room utilization rates.
- 510(k) Predicate Device Erosion:FDA's narrowing acceptable predicate pool for new fractional laser submissions is extending regulatory timelines and legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrophic Scar Treatment Market |
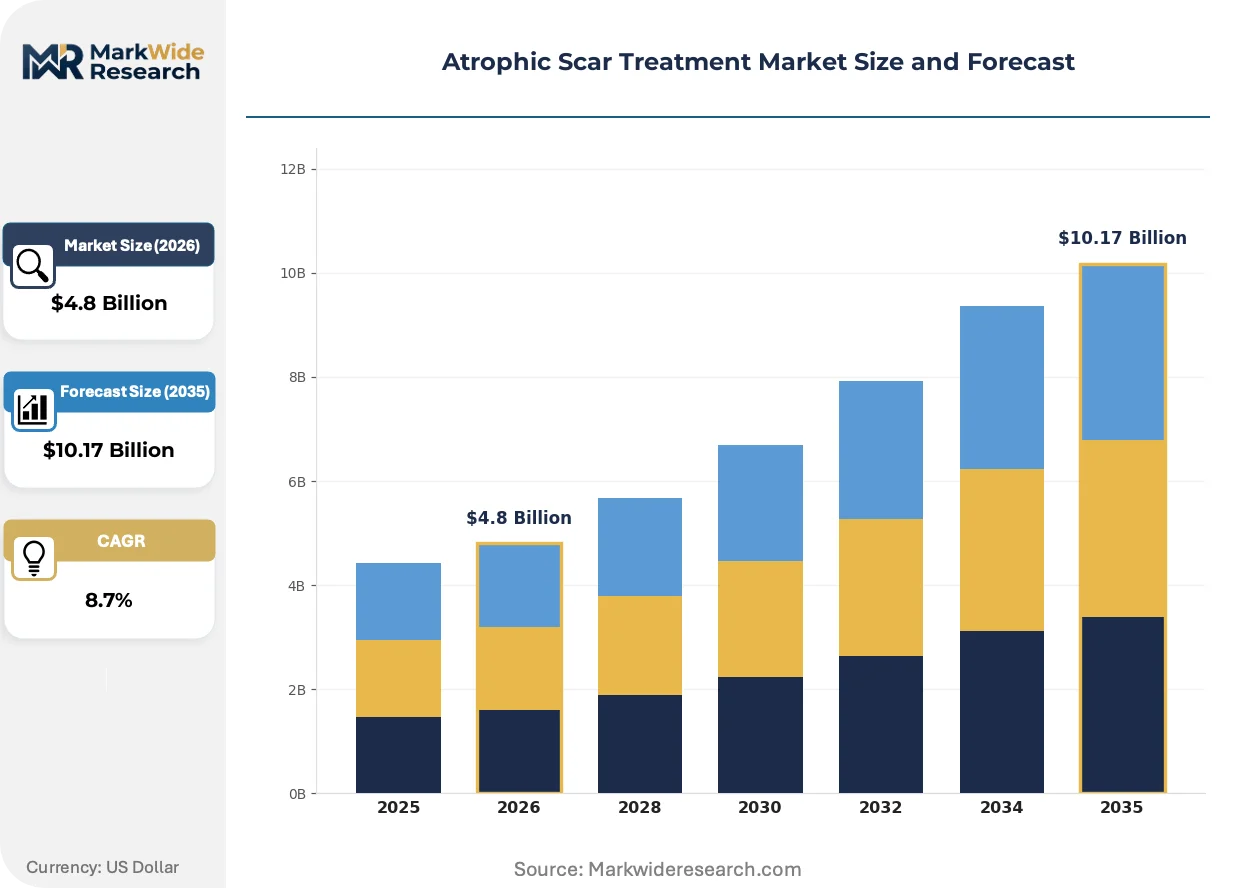
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Laser Therapy, Chemical Peels, Microneedling Technology: RF Microneedling, Fractional Laser, Dermal Fillers, Platelet-Rich Plasma End User: Dermatology Clinics, Hospitals, Home Care, Spa Centers Delivery Mode: Invasive, Minimally Invasive, Non-Invasive, Injectable |
| Companies Covered | Smith & Nephew plc, Lumenis, Merz Pharma, Cynosure, Bausch Health Companies, Mölnlycke Health Care AB, Cutera, Sonoma Pharmaceuticals, CCA Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrophic Scar Treatment Market Strategic Shifts
Device miniaturization and biologic adjuvant integration are reshaping treatment protocols across dermatology practices, while regulatory divergence between FDA and EU MDR pathways is fragmenting product development roadmaps.
Fractional laser technology is miniaturizing through fiber-coupled diode arrays and compact cooling systems that enable tabletop footprints without sacrificing 1540 nm wavelength precision. Mid-sized dermatology groups in suburban United States markets are adopting these platforms at accelerated replacement cycles. The form-factor reduction is compressing capital barriers for clinic entry and expanding addressable site counts beyond traditional hospital-affiliated centers.
EU MDR technical documentation requirements for energy-based aesthetic devices are lengthening conformity assessment timelines and forcing manufacturers to generate new clinical evidence rather than leveraging grandfathered predicate studies. Fractional laser and RF microneedling platforms face the heaviest evidentiary burdens under this framework. Manufacturers are responding by prioritizing United States FDA 510(k) clearances first, then parallel-tracking MDR submissions with dedicated European clinical cohorts.
Patient acquisition patterns are shifting from physician-referral networks toward social media-driven discovery and direct booking platforms. Instagram and TikTok content creators in the aesthetic dermatology space are displacing traditional continuing medical education channels for patient awareness. This behavioral pivot is most visible in United States coastal metropolitan markets where influencer partnerships now drive substantial new-patient volume for combination scar treatment protocols.
Atrophic Scar Treatment Market Segmentation
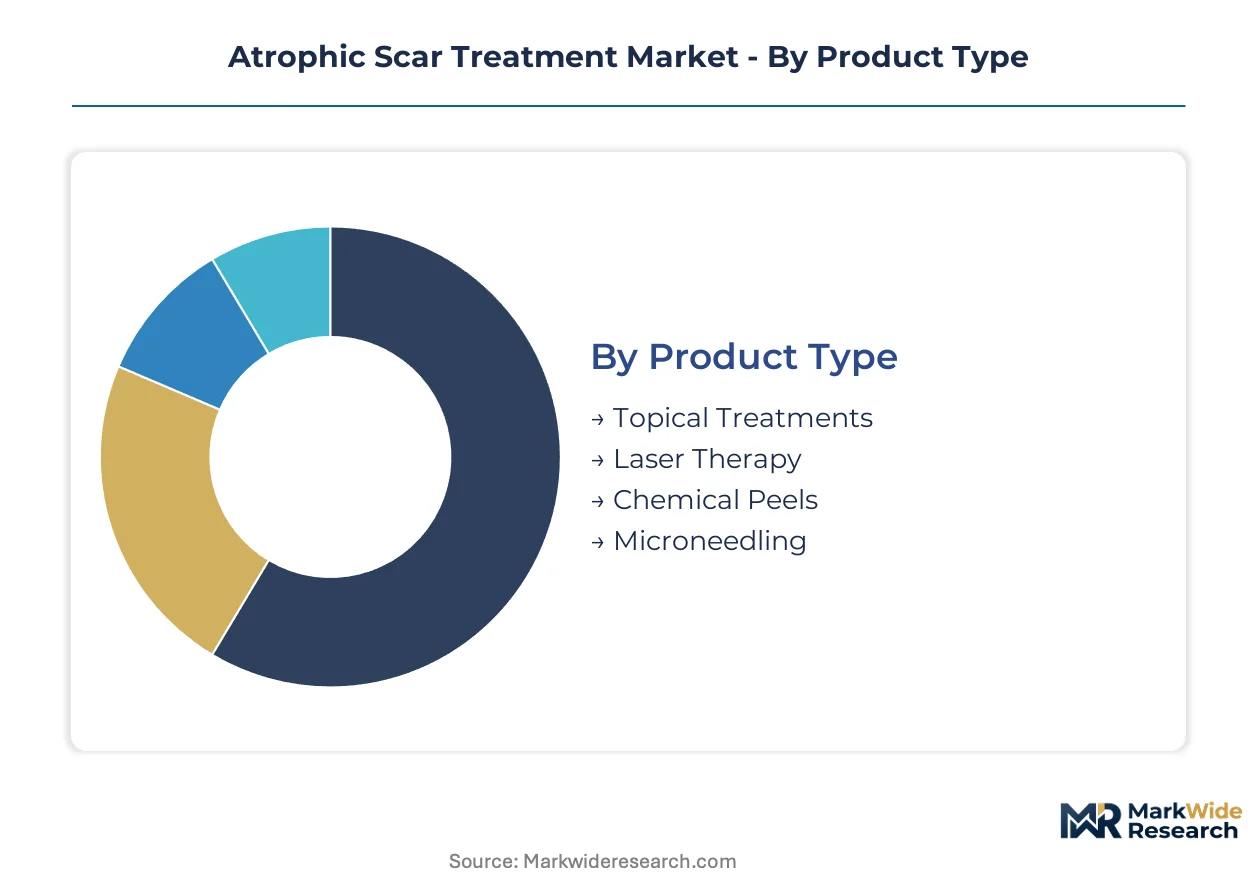
Atrophic scar treatment modalities fragment across technology intensity, clinical setting, and patient accessibility tiers. Understanding where margin pools concentrate versus where volume accumulates shapes portfolio allocation and channel strategy for manufacturers and service providers.
Product Type:
Margin pools concentrate in device-mediated treatments where consumable attachment and maintenance contracts generate recurring revenue streams.
- Laser Therapy:Fractional laser systems operating at 1540 nm and 1550 nm wavelengths deliver tunable thermal injury to depths reaching 1400 micrometers. United States dermatology clinics command premium pricing for these procedures, though capital equipment intensity limits penetration in price-sensitive secondary markets.
- Microneedling:Percutaneous collagen induction triggers dermal remodeling through controlled micro-injury without thermal damage. Demand concentrates in suburban United States dermatology groups adopting tabletop RF-integrated platforms at accelerated replacement cycles.
- Topical Treatments:Silicone gels, retinoids, and growth factor serums dominate direct-to-consumer channels with lower per-unit margins but substantial volume throughput.
- Chemical Peels:Acid-based exfoliation protocols address superficial atrophic scarring through controlled epidermal injury, primarily administered in medical spa settings.
Laser Therapy holds installed capacity. Microneedling is rotating up the share rankings.
Technology:
Volume leadership sits with established modalities, while fastest expansion occurs at the convergence of biologic adjuvants and energy-based delivery.
- Fractional Laser:Erbium-doped and thulium fiber sources generate microthermal zones with precise depth control. EU MDR clinical evaluation requirements are filtering out marginal competitors and consolidating share among established CE-marked portfolios.
- RF Microneedling:Bipolar radiofrequency energy delivered through insulated microneedles achieves deep dermal heating with reduced epidermal disruption. United States coastal metropolitan markets show strongest uptake where influencer partnerships drive new-patient volume for combination protocols.
- Dermal Fillers:Hyaluronic acid and collagen-stimulating injectables provide immediate volumetric correction for rolling scar morphologies.
- Platelet-Rich Plasma:Autologous growth factor concentrates are gaining traction as biologic adjuncts paired with energy-based resurfacing procedures.
Fractional Laser anchors current revenue. RF Microneedling is climbing the fastest among emerging modalities.
End User:
Channel configuration determines pricing power, with physician-supervised settings commanding multiples over direct-to-consumer alternatives.
- Dermatology Clinics:Physician-directed settings capture premium positioning through combination protocols pairing laser resurfacing with biologic adjuncts. Instagram and TikTok content creators now displace traditional CME channels for patient acquisition in United States coastal metropolitan markets.
- Home Care:Direct-to-consumer microneedling pens and LED masks serve maintenance-phase patients between professional treatments, though efficacy thresholds remain below clinical-grade outcomes.
- Hospitals:Academic medical centers concentrate complex scar revision cases requiring multidisciplinary coordination.
- Spa Centers:Non-physician supervised settings compete on accessibility and price point for superficial treatment protocols.
Dermatology Clinics concentrate margin capture. Home Care is expanding most quickly in patient touchpoint frequency.
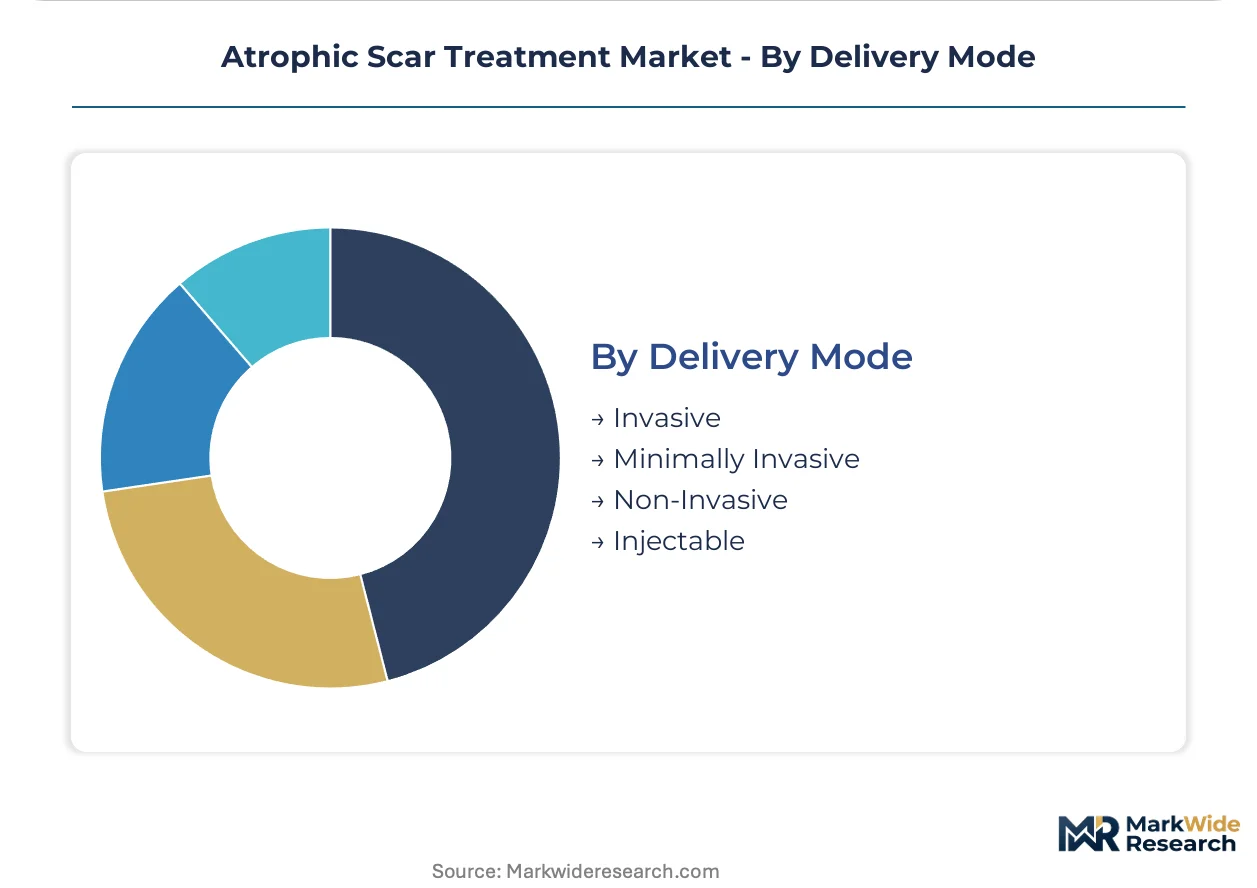
Delivery Mode:
Regulatory burden escalates with tissue penetration depth, fragmenting competitive dynamics across clearance pathways.
- Minimally Invasive:Microneedling and fractional laser platforms occupy the commercial sweet spot between efficacy demonstration and regulatory accessibility. FDA 510(k) predicate device erosion is extending timelines for new fractional laser submissions.
- Injectable:Dermal fillers and biologic concentrates require stricter safety profiling but achieve immediate patient satisfaction metrics.
- Non-Invasive:Topical and light-based modalities face lighter regulatory scrutiny but confront efficacy ceilings in deep scar morphologies.
- Invasive:Surgical subcision and punch excision address refractory ice-pick scars beyond the reach of energy-based devices.
Minimally Invasive dominates current procedure volumes. Injectable is gaining share fastest through biologic-stimulator convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of fractional laser systems and RF microneedling platforms concentrate from Germany and Japan toward United States dermatology networks, while India and Brazil represent net importers of capital equipment with nascent domestic manufacturing capabilities. Trade balances reflect divergent regulatory sophistication, with FDA-cleared devices commanding premium pricing in destination markets.
United States
Aesthetic procedure volumes and out-of-pocket willingness sustain the highest per-capita spending on combination scar treatment protocols. FDA's evolving guidance on energy-based devices tightens predicate-device pathways, compressing approval timelines for new fractional laser entrants. Coastal metropolitan clusters in California and New York drive influencer-mediated patient acquisition for biologic-laser combination therapies.
Germany
Erbium-doped and thulium fiber laser source manufacturing anchors European supply chains for optical components. EU MDR clinical evaluation requirements filter marginal competitors from CE-marked portfolios, consolidating share among established device manufacturers. Bavarian and Baden-Württemberg industrial clusters concentrate precision optics fabrication for export to North American and Asian markets.
Japan
PMDA jurisdiction-specific labeling standards shape product configuration for Asian launches beyond domestic consumption. Domestic demand for minimally invasive scar revision concentrates in Tokyo and Osaka metropolitan dermatology networks. Japanese optical component suppliers maintain critical input concentration for fractional laser systems deployed globally.
India
Tier-1 cities demonstrate nascent demand for aesthetic dermatology with limited installed base of fractional laser systems. CDSCO medical device regulations are harmonizing with international standards to accelerate import clearance for capital equipment. Maharashtra and Karnataka metropolitan clusters show earliest adoption of RF microneedling platforms among dermatology groups.
Brazil
ANVISA regulatory pathways for energy-based aesthetic devices require substantial technical documentation, extending market entry timelines for foreign manufacturers. São Paulo and Rio de Janeiro concentrate private dermatology clinic networks with capacity for premium scar treatment protocols. Import dependence for laser and microneedling platforms creates pricing premiums versus North American or European procedure costs.
Atrophic Scar Treatment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions, with publicly traded dermatology device manufacturers commanding valuation premiums tied to recurring consumable revenue streams. The vendor base organizes around three strategic archetypes: integrated laser platform manufacturers with installed base leverage, biologic-stimulator specialists pursuing combination protocol positioning, and regional distributors with service-network moats. Dominant competitive moves include M&A activity targeting optical component suppliers and strategic partnerships pairing device manufacturers with biologic adjunct developers.
Within the integrated platform tier, Lumenis and Cynosure exemplify archetypes leveraging installed base scale to sustain recurring consumable revenue across dermatology networks. Merz Pharma occupies a position bridging European market access through dermal filler portfolios with emerging combination therapy positioning. Smith & Nephew plc represents the diversified medical technology conglomerate archetype, anchoring competitive dynamics through wound care and aesthetic device cross-selling capabilities.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Lumenis |
| Merz Pharma |
| Cynosure |
| Bausch Health Companies |
| Mölnlycke Health Care AB |
| Cutera |
| Sonoma Pharmaceuticals |
| CCA Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term consumable service contracts lock dermatology networks into predictable cost structures while securing manufacturers' recurring revenue visibility across fractional laser and RF microneedling platforms. These arrangements tether clinic procurement decisions to installed base loyalty, amplifying pricing power for vendors with established CE-marked and FDA-cleared portfolios.
Pricing Analysis
Dermatology clinic groups anchor procedure pricing through three-tier structures across premium, standard, and economy levels. Price differentiation rests on certification grade (FDA 510(k) versus CE-marked tiers) and bundled after-sales service intensity. Cost compression in mid-tier tabletop platforms is intensifying because suburban United States groups accelerate replacement cycles. Price-sensitive secondary markets in India and Brazil resist capital equipment premiums, while coastal United States metropolitan clusters absorb premium positioning for combination protocols.
Supply Chain Analysis
Strategic stockpiling of erbium-doped and thulium fiber laser sources dominates manufacturer procurement given concentrated German and Japanese optical component supply. Geographic supply concentration centers on Bavarian precision optics clusters and Osaka-based fiber manufacturing. Raw material dependencies include rare-earth dopants, specialized fused silica substrates, and RF generator subassemblies. Single-source vulnerability in thulium fiber supply creates exposure to export licensing delays. Distribution runs through authorized service networks with direct-to-clinic installation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dermatology group consolidation across suburban United States markets is shifting procurement leverage toward larger buying entities, fragmenting vendor pricing power and favoring manufacturers with scale economics.
For Market Incumbents: Compound installed base advantages through captive supply of consumable handpieces and maintenance contracts that raise switching costs for dermatology networks. Prioritize backward integration into erbium-doped fiber sources to mitigate Japanese supplier concentration risk. Defend against RF microneedling entrants by accelerating tabletop platform refresh cycles. For New Entrants and Emerging Players: Post-treatment maintenance-phase service gaps expose incumbents' underinvestment in home-use device channels. Penetrate direct-to-consumer microneedling pen segments in United States coastal markets where influencer partnerships drive discovery. Pursue regulatory arbitrage by securing FDA 510(k) clearance ahead of EU MDR submissions to compress initial revenue timelines. For Investors and Strategic Acquirers: Capital is best deployed toward biologic-stimulator specialists with exosome or platelet-rich plasma portfolios that enable combination protocol positioning. Long-term viability hinges on convergence plays that merge energy-based delivery with autologous growth factor concentrates. Watch FDA predicate-device pathway narrowing as inflection signal for regulatory timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Parallel-Track Submission | Dedicated European clinical cohorts accelerate CE-marking timelines for fractional laser platforms. |
| Optical Component Backward Integration | Captive erbium-doped fiber production mitigates German and Japanese supplier concentration risk. |
| Biologic Adjunct Partnership | Exosome developer alliances create differentiated combination therapy protocols for dermatology clinics. |
| Home-Use Device Channel Launch | Direct-to-consumer microneedling pens capture maintenance-phase patients between professional treatments. |
| Influencer Partnership Program | TikTok and Instagram content creator networks displace traditional CME channels for patient acquisition. |
Study Parameters
Desk research of FDA 510(k) clearances, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with dermatology clinic operators, biomedical engineers, GPO contracts managers, and laser safety officers. Secondary validation drew from CMS Medicare procedure data, customs import records for optical components, and SEC filings of listed device manufacturers. Bottom-up procedure volume estimates triangulated against top-down market sizing across the analysis window.
Variance decomposition across product type, technology modality, end-user channel, and delivery mode segmentation anchored the analytical framework. CAGRs were derived from modeled procedure volume trajectories and average selling price evolution. Forecast inputs incorporated regulatory pathway timelines for fractional laser platforms and biologic adjuvant adoption curves in combination protocols.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR conformity assessment; material policy shifts would require re-modeling. Revision becomes warranted when predicate-device pool erosion or MDR clinical evaluation requirement changes cross thresholds that alter manufacturer competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
US Scar Treatment Market