
 Global Dermatology EMR Software Market | 2026-2036
Global Dermatology EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatology EMR Software Market Foresight
The direct sales channel for dermatology EMR vendors is narrowing as cloud distribution and SaaS marketplaces capture larger contract flows. Modernizing Medicine leverages specialty-specific clinical content to dominate ambulatory dermatology workflows. Nextech Systems sustains its position through deep integration with cosmetic procedure modules and practice management tools. AdvancedMD competes aggressively on pricing flexibility for independent dermatology groups seeking bundled billing and scheduling platforms.
Dermatology EMR software constitutes a specialized electronic medical record system engineered for skin, hair, and nail care documentation, incorporating lesion mapping tools, pathology integration, and photography management with DICOM compatibility. Its primary commercial purpose centers on streamlining clinical workflows for high-volume visual diagnosis while ensuring interoperability with laboratory and pharmacy systems. Cloud-based deployment leads segment adoption by reducing capital expenditure burdens for small and mid-sized dermatology practices. AI Integration represents the fastest-expanding technology dimension as automated lesion classification and diagnostic decision support reshape clinical documentation priorities. Telemedicine Support has matured rapidly following pandemic-era regulatory flexibilities, though margin pools remain thinner compared to core patient management modules.
FDA oversight of clinical decision support tools and HIPAA security rule enforcement shape product development roadmaps for US-focused vendors. GDPR compliance requirements in Europe and emerging data localization mandates from China's NMPA and SAMR constrain cross-border hosting architectures and complicate vendor expansion strategies. Stakeholders must monitor evolving interoperability standards from HL7 FHIR and regional certification bodies to anticipate which platform investments will retain long-term compliance viability.
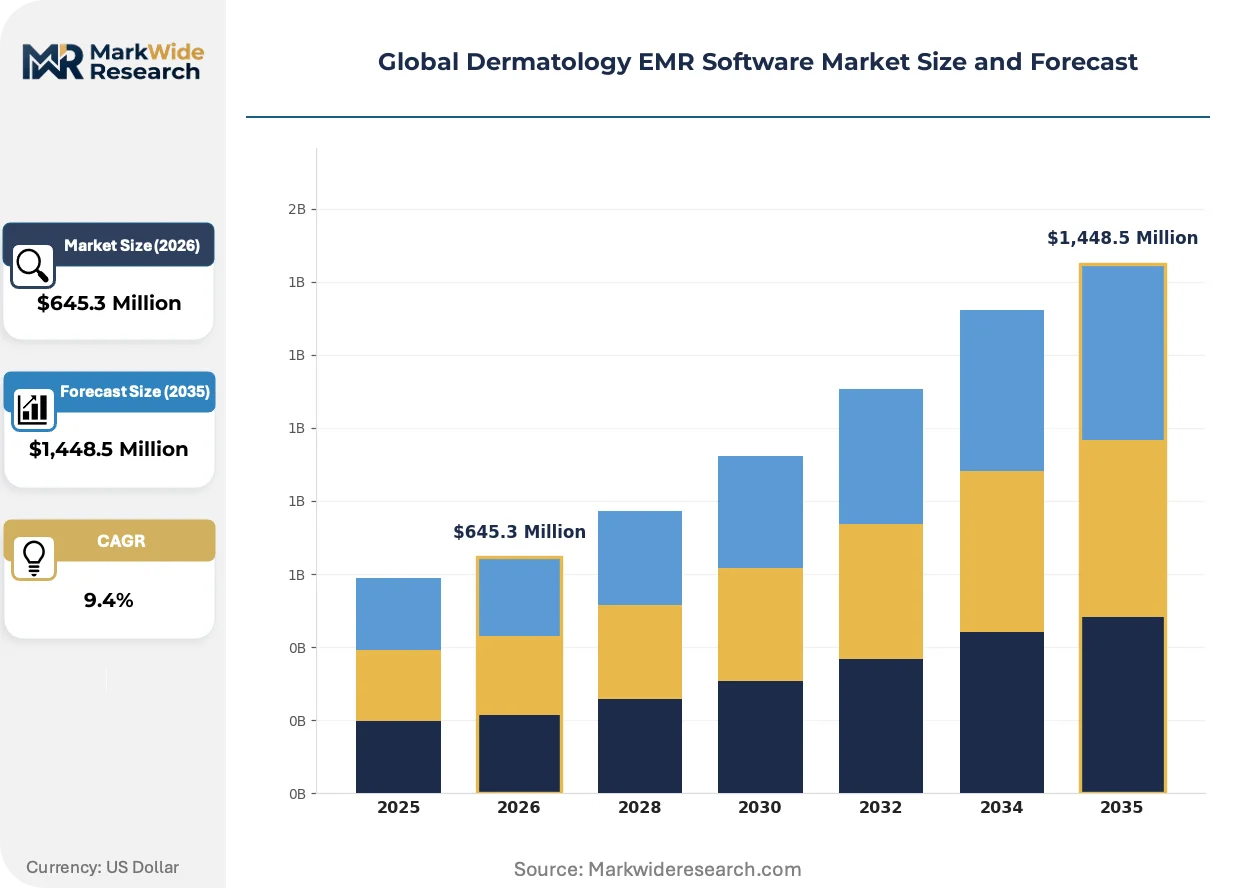
Market Dynamics
Cloud-based EMR deployment is virtualizing dermatology practice infrastructure, compressing capital requirements for lesion mapping and pathology integration while expanding vendor addressable markets beyond metropolitan hospital systems.
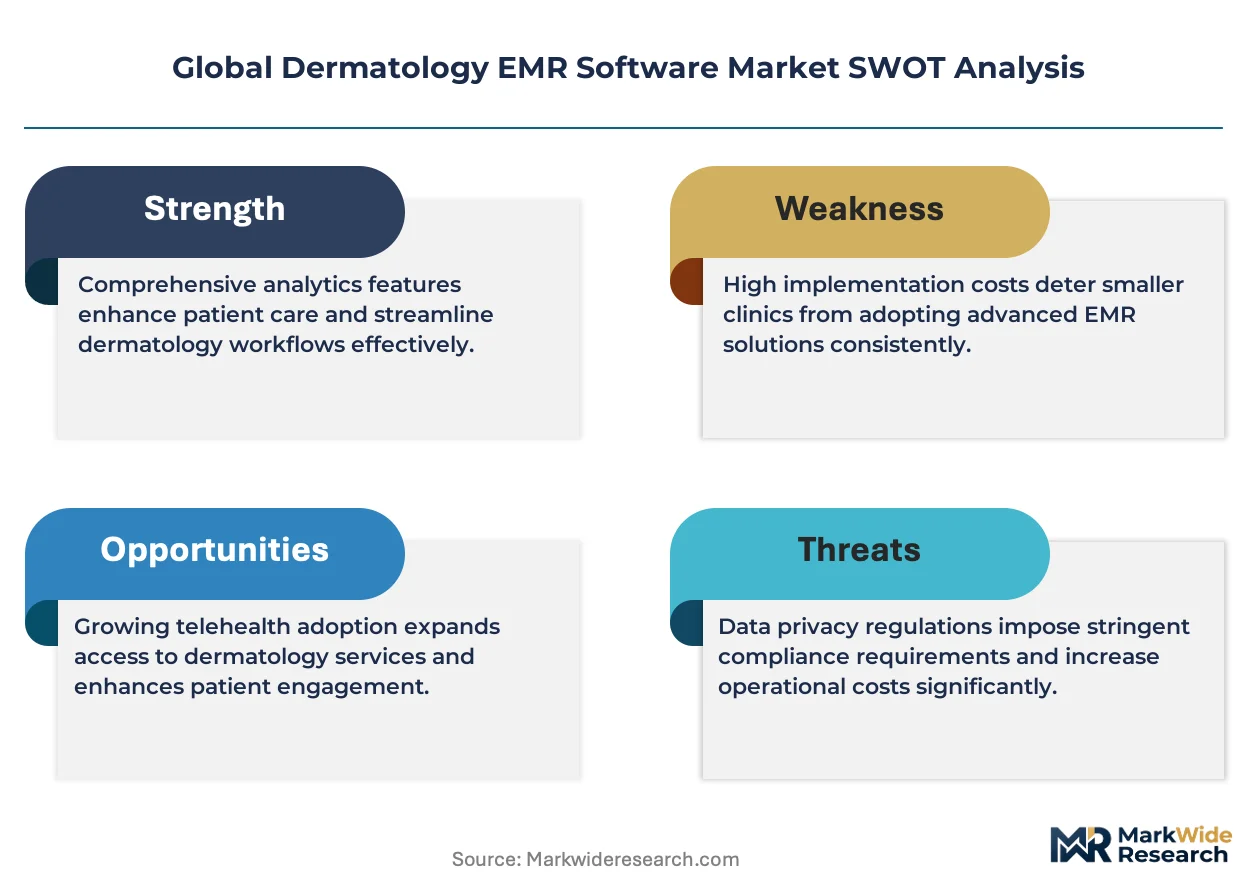
Growth Catalysts
- HIPAA Security Rule Enforcement:US dermatology practices accelerate cloud migration to meet technical safeguard mandates for ePHI protection, reducing on-premise infrastructure liability.
- Cosmetic Procedure Volume Concentration:Aesthetic dermatology clinics in Germany and South Korea drive demand for integrated photography management and DICOM-compatible imaging workflows.
- AI-Powered Lesion Classification:Machine learning diagnostic tools reduce documentation burden for high-volume visual diagnosis, improving clinician throughput in ambulatory settings.
Market Restraints
- GDPR Data Localization:European hosting requirements fragment vendor architectures, raising compliance costs for cross-border patient data management.
- Legacy System Interoperability:HL7 FHIR implementation gaps between established pathology labs and cloud-native EMR platforms create integration friction.
- Specialized Dermatology IT Talent Scarcity:Shortage of clinical informaticists with DICOM and dermatology-specific workflow expertise constrains rollout velocity.
Strategic Opportunities
- Telemedicine Regulatory Tailwinds:Post-pandemic reimbursement permanency for remote dermatology consultations in the US expands addressable service lines.
- China NMPA Certification Pathway:Domestic software registration requirements create protected market space for localized EMR variants.
- Convergence of 3D Body Mapping and AI:Integration of spatial imaging with automated diagnostic support opens premium pricing tiers for cosmetic and surgical dermatology.
Industry Challenges
- Multi-Jurisdiction Compliance Engineering:Vendors must architect simultaneous HIPAA, GDPR, and NMPA compliance, extending product development timelines.
- Interoperability Certification Backlogs:Regional HL7 FHIR certification body capacity constraints delay market entry for new platform releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatology EMR Software Market |
| Market Size in 2026 | $645.3 Million |
| Market Size in 2035 | $1,448.5 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Web-Based Technology: AI Integration, Mobile Compatibility, Telemedicine Support, Data Analytics, Voice Recognition Application: Patient Management, Appointment Scheduling, Clinical Documentation, Billing & Invoicing, Inventory Tracking End User: Dermatology Clinics, Specialty Hospitals, Cosmetic Surgery Centers, Telehealth Providers |
| Companies Covered | Modernizing Medicine, Nextech Systems, AdvancedMD, athenahealth, Compulink Healthcare Solutions, Kareo, Practice Fusion, eClinicalWorks, DrChrono, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatology EMR Software Market Shifts & Advancements
Diagnostic workflow automation and regulatory data governance are converging to redefine platform architecture priorities, shifting vendor investment from feature breadth to compliance-embedded AI delivery.
Computer vision algorithms trained on annotated lesion databases are virtualizing the initial screening layer of dermatology consultations. Community health centers and retail clinic chains deploy these tools to extend dermatological reach into primary care settings. The technology is virtualizing traditional referral pathways, compressing time-to-diagnosis for pigmented lesion concerns.
The EU AI Act's risk classification framework for medical decision support tools imposes conformity assessment obligations on automated diagnostic features. Vendors must now document algorithmic transparency and clinical validation for CE marking of AI-integrated EMR modules. European dermatology software procurement is prioritizing MDR-compliant platforms with embedded algorithmic audit trails.
Subscription-based SaaS procurement is displacing perpetual license models among independent dermatology group practices. Vendor sales cycles now concentrate on annual recurring revenue metrics rather than upfront implementation fees. This shift is most pronounced in North American metropolitan markets where private equity-backed practice aggregations standardize technology stacks across acquired clinics.
Global Dermatology EMR Software Market Segmentation
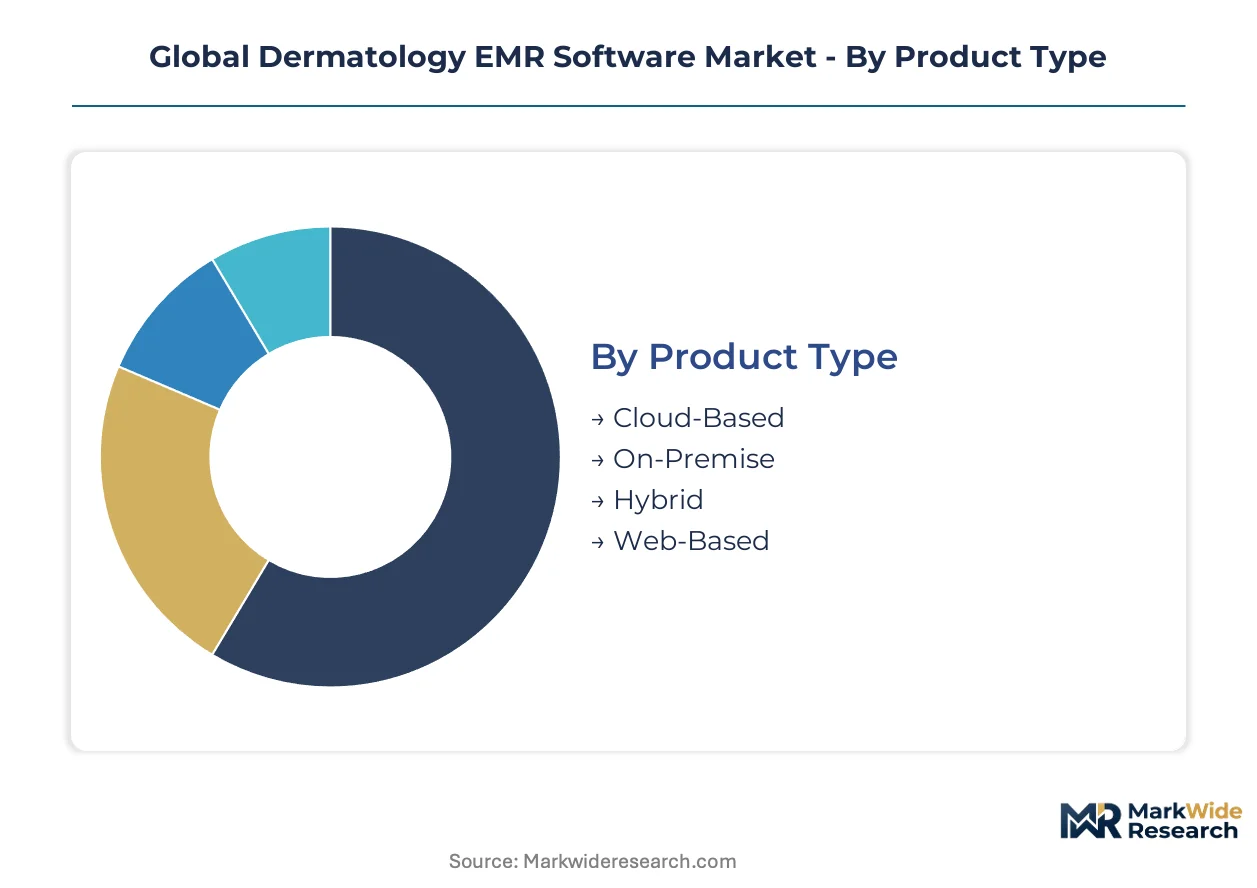
Dermatology EMR software segments diverge sharply by infrastructure burden, clinical workflow depth, and regulatory exposure. Vendors architect product lines around these fractures, with deployment model and AI capability emerging as the primary axes of competitive differentiation.
Product Type:
Deployment architecture determines capital intensity, compliance posture, and vendor addressability across practice sizes and geographies.
- Cloud-Based:Multi-tenant SaaS architecture eliminates server maintenance overhead while embedding automated HIPAA technical safeguard updates. Demand concentrates in US metropolitan private practice aggregations where private equity standardization mandates cloud-native stacks. HIPAA Security Rule enforcement accelerates migration from legacy on-premise systems.
- On-Premise:Local server installation retains full data custody within facility firewalls, appealing to German dermatology networks navigating GDPR localization requirements and Chinese clinics awaiting NMPA cloud certification pathways. Capital expenditure barriers limit penetration among independent ambulatory practices.
- Hybrid:Split architecture keeps sensitive imaging data on local DICOM servers while routing scheduling and billing through cloud interfaces. German university hospital networks deploy this model to satisfy both GDPR residency mandates and interoperability demands.
- Web-Based:Browser-accessible platforms without dedicated mobile applications serve cost-constrained South Korean cosmetic clinics prioritizing photography management over full workflow integration.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Technology:
Capability layers stack from basic accessibility through predictive automation, with each tier commanding distinct pricing and implementation timelines.
- AI Integration:Machine learning modules for lesion classification and diagnostic decision support reduce documentation burden in high-volume US ambulatory settings. FDA oversight of clinical decision support tools shapes algorithmic transparency requirements for US market entry.
- Mobile Compatibility:Native iOS and Android applications enable point-of-care image capture and asynchronous consult review. Demand clusters among US telehealth providers and South Korean cosmetic surgery centers with high patient throughput.
- Telemedicine Support:Integrated video consultation, e-prescribing, and remote lesion monitoring modules. Post-pandemic reimbursement permanency in the US expands service line viability despite thinner margin pools.
- Data Analytics:Population health dashboards and outcome tracking for practice management optimization. US specialty hospital systems leverage these tools for quality reporting to CMS.
- Voice Recognition:Natural language processing for hands-free clinical documentation during examinations. German dermatology clinics adopt this capability to reduce clinician administrative burden.
AI Integration commands premium pricing. Mobile Compatibility is climbing the fastest.
Application:
Functional modules align with revenue cycle position, from patient acquisition through clinical service delivery to back-office operations.
- Patient Management:Core demographic tracking, allergy documentation, and longitudinal record maintenance. Every deployment includes this foundation, with differentiation around DICOM imaging integration and pathology lab connectivity.
- Appointment Scheduling:Calendar optimization, automated reminders, and waitlist management. US dermatology clinics prioritize this module to minimize no-show rates in high-volume cosmetic and medical practices.
- Clinical Documentation:Structured templates for lesion mapping, biopsy tracking, and treatment planning. EU AI Act conformity assessment obligations now apply to automated diagnostic features embedded here.
- Billing & Invoicing:Claims submission, prior authorization, and revenue cycle management. Independent US group practices seek bundled platforms combining this with scheduling to reduce vendor fragmentation.
- Inventory Tracking:Cosmetic product, pharmaceutical, and consumable management for aesthetic dermatology. South Korean and German cosmetic surgery centers drive specialized demand here.
Clinical Documentation anchors R&D investment. Billing & Invoicing is gaining share fastest.
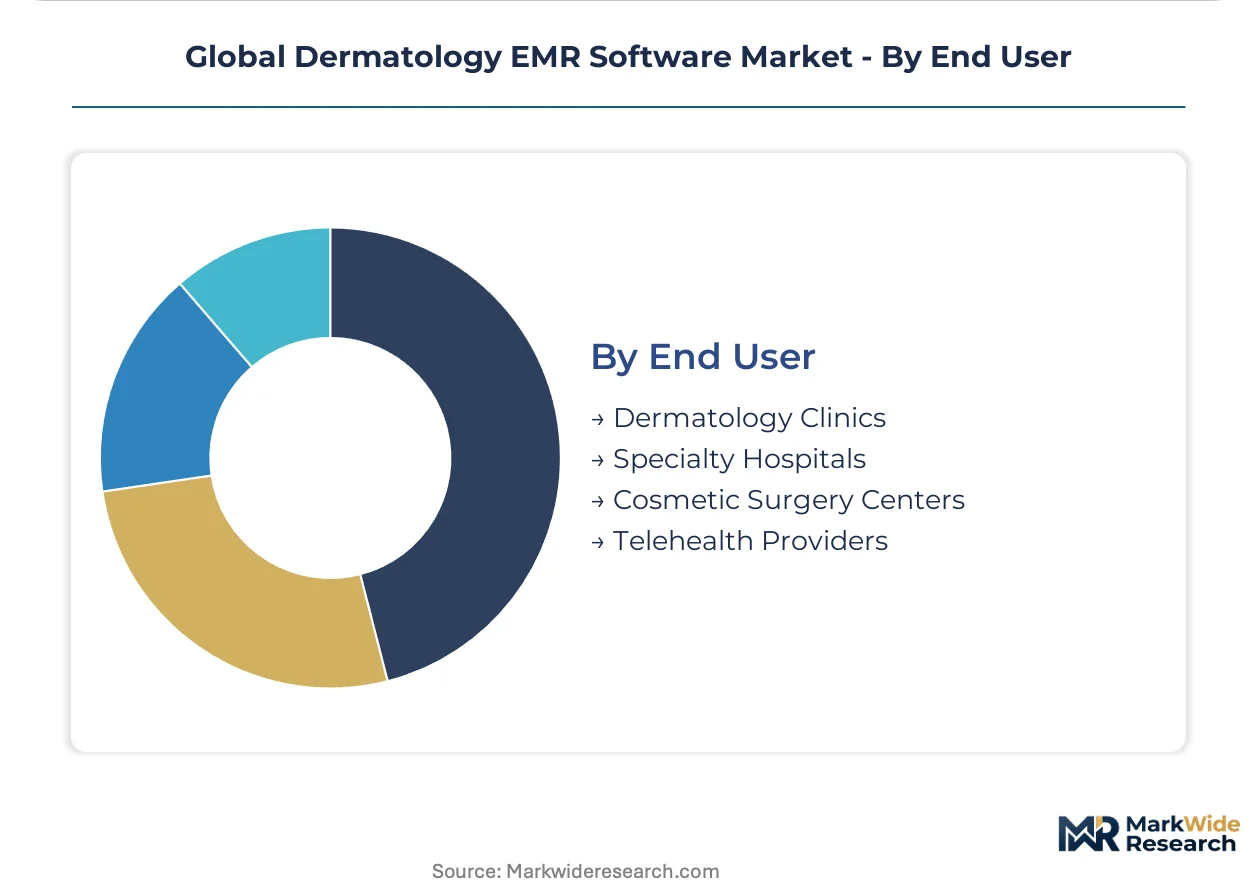
End User:
Customer type dictates workflow complexity, regulatory exposure, and procurement authority structure.
- Dermatology Clinics:Single-specialty ambulatory practices ranging from solo practitioners to multi-site groups. US metropolitan aggregations standardize on cloud-based platforms with integrated practice management.
- Specialty Hospitals:Dermatology departments within larger hospital systems requiring enterprise interoperability and EHR integration. HL7 FHIR certification gaps with pathology labs create implementation friction.
- Cosmetic Surgery Centers:Aesthetic-focused facilities in Germany and South Korea demanding photography management, 3D body mapping, and procedure-specific documentation workflows.
- Telehealth Providers:Virtual-first dermatology services relying on asynchronous image submission and AI-assisted triage. US reimbursement permanency for remote consultations expands this segment.
Dermatology Clinics hold installed capacity. Telehealth Providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic corridors linking Frankfurt to New York and London underwrite Europe's data governance leadership in dermatology EMR hosting, while submarine cable landing stations in Singapore and Los Angeles anchor Asia-Pacific cloud distribution for medical imaging workloads.
United States
Metropolitan healthcare corridors in Boston and Houston drive cloud EMR adoption among dermatology practice aggregations. HIPAA Security Rule enforcement accelerates technical safeguard investments for ePHI protection. Private equity-backed clinic networks in Miami standardize on SaaS platforms with integrated practice management.
Germany
Cosmetic dermatology volume in Munich and Düsseldorf propels demand for DICOM-compatible photography management. GDPR data localization requirements fragment vendor architectures for cross-border patient management. University hospital networks in Berlin deploy hybrid cloud models to satisfy residency mandates.
China
Domestic software registration pathways from NMPA and SAMR create protected market space for localized EMR variants. Data localization mandates constrain cross-border hosting architectures for international vendors. Shanghai dermatology chains await cloud certification clarity before full SaaS migration.
South Korea
Cosmetic surgery centers in Seoul and Busan prioritize photography management and 3D body mapping capabilities. MFDS medical device regulations shape software validation requirements for diagnostic modules. Gangnam district clinics drive premium pricing for aesthetic-focused workflow integration.
United Kingdom
NHS digital transformation programs accelerate EMR procurement for dermatology departments in London and Manchester. MHRA oversight of clinical decision support tools shapes algorithmic transparency requirements. Cambridge health tech clusters incubate AI-integrated diagnostic platforms for export markets.
Global Dermatology EMR Software Market Competitive Landscape
On the supply side, the industry is consolidating around specialty-specific clinical content and cloud-native architectures. Three strategic archetypes dominate: vertically integrated health IT conglomerates with broad ambulatory portfolios, pure-play dermatology specialists with lesion mapping expertise, and telehealth-native platforms with asynchronous consultation infrastructure. Competitive moves concentrate on M&A for practice management capabilities and strategic partnerships for AI diagnostic licensing.
Among US-based health IT specialists, Modernizing Medicine and Nextech Systems exemplify the specialty-focused archetype with deep clinical content libraries, while AdvancedMD occupies a position within the pricing-flexibility tier targeting independent group practices. These three entities anchor the competitive spectrum from premium workflow depth to bundled affordability.
| Leading Market Players |
|---|
| Modernizing Medicine |
| Nextech Systems |
| AdvancedMD |
| athenahealth |
| Compulink Healthcare Solutions |
| Kareo |
| Practice Fusion |
| eClinicalWorks |
| DrChrono |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud infrastructure across US metropolitan healthcare corridors compresses hosting costs for dermatology EMR vendors while simultaneously intensifying competition for annual recurring revenue contracts, forcing pricing discipline that feeds back into leaner supply chain configurations favoring multi-tenant SaaS architectures over on-premise hardware procurement.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and solo-practitioner levels, with annual seat commitments above 50 licenses triggering 15-25% standard reductions. Price differentiation hinges on AI module inclusion and HIPAA Security Rule attestation tier. Pricing pressure stems from private equity-backed practice aggregations demanding standardized, bundled platforms. Independent dermatology groups in the US exhibit highest price sensitivity, while German cosmetic surgery centers prioritize DICOM workflow depth over cost.
Supply Chain Analysis
Upstream feedstock for cloud-native EMR platforms draws from hyperscaler data center capacity concentrated in the United States, Germany, and Singapore, with compute and storage resources increasingly sourced through reserved instance commitments rather than spot markets. Software development labor pools concentrate in India, Poland, and Vietnam for quality assurance and FHIR interoperability engineering. Single-source vulnerability around DICOM imaging libraries from limited certified vendors creates supply chain risk. Distribution runs through direct SaaS marketplaces and specialty health IT value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in dermatology EMR are approaching an inflection where HL7 FHIR interoperability becomes the primary moat, as ecosystem lock-in through integrated pathology lab connectivity displaces standalone feature competition.
For Market Incumbents: Pre-empt AI diagnostic module commoditization by deepening pathology lab integration through exclusive FHIR certification partnerships. Acquire telehealth-native platforms before reimbursement permanency fully matures, as asynchronous consultation infrastructure represents the fastest-eroding differentiation window. Vertical integration into 3D body mapping hardware preserves premium pricing tiers against cloud-native challengers. For New Entrants and Emerging Players: Build out niche specialization in GDPR-compliant hybrid deployment architectures for German university hospital networks, where incumbent cloud-native vendors face data localization friction. Target South Korean cosmetic surgery centers with photography-first, mobile-native workflows that bypass full EMR replacement cycles. Pursue channel partnerships with existing DICOM imaging equipment distributors rather than direct sales buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty-focused vendors with lesion mapping clinical content libraries and established practice management integration. Long-term viability over the next decade hinges on AI diagnostic validation pathways and MDR conformity assessment completion for European market access. Acquisition targets should demonstrate embedded algorithmic audit trails and CE marking progress. The signal to watch is NMPA cloud certification clarity in China, which would trigger SaaS migration acceleration and vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Module Certification | FDA clinical decision support oversight and EU AI Act conformity assessment embed compliance into product architecture. |
| Pathology Lab FHIR Integration | HL7 FHIR certification gaps with legacy lab systems create exclusive partnership opportunities for workflow lock-in. |
| Hybrid Cloud Architecture Development | GDPR data localization requirements in Germany and NMPA mandates in China fragment hosting strategies. |
| Telehealth Platform Acquisition | US reimbursement permanency for remote dermatology consultations expands addressable service lines. |
| 3D Body Mapping Convergence | Integration of spatial imaging with automated diagnostic support opens premium pricing for cosmetic dermatology. |
Research Methodology
A standing panel of dermatology clinic IT directors, hospital system CMIOs, health IT procurement officers, and GPO contracts managers provided ongoing calibration throughout the primary research phase. This stakeholder input was cross-referenced against secondary sources including FDA 510(k) filings for clinical decision support tools, CMS Medicare reimbursement databases, hospital procurement records, and HL7 FHIR certification registries. Bottom-up sizing of vendor-installed bases was triangulated against top-down healthcare IT expenditure estimates from national statistical agencies.
Scenario-bracketing framed the analytical approach across the analysis window, with deployment model, practice size tier, AI capability level, and regional regulatory cluster serving as the core segmentation dimensions for volume and value modeling. CAGRs were derived from S-curve adoption pattern fitting against historical EMR replacement cycles and cloud migration trajectories. Forecast inputs included HIPAA enforcement intensity indices, EU AI Act implementation timelines, and private equity dermatology practice aggregation velocity.
Stress conditions across GDPR enforcement escalation, NMPA cloud certification delays, and AI diagnostic reimbursement rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and interoperability standard adoption curves. Cross-checking against hospital IT budget allocation surveys and health system capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Epharmacy Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market