
 North America Scar Treatment Market | 2026-2036
North America Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Scar Treatment Market Analytics
Aesthetic centers is recalibrating the end-use mix as outpatient scar revision procedures shift away from hospital settings. Smith & Nephew PLC leverages its wound care heritage to dominate silicone sheet distribution across dermatology channels. Mölnlycke Health Care AB anchors its position through advanced wound management portfolios that extend into post-surgical scar protocols. Lumenis competes on laser technology leadership, particularly in fractional and pulsed-dye systems for hypertrophic and keloid indications.
Scar treatment encompasses topical, procedural, and device-based interventions designed to improve the aesthetic and functional properties of fibrous tissue replacement following dermal injury. Silicone gel and sheets function through hydration and occlusion mechanisms, while laser devices target collagen remodeling via selective photothermolysis at specific wavelengths. Laser therapy commands premium pricing due to capital equipment intensity and clinician training requirements, whereas topical silicone products represent the highest-volume segment driven by homecare accessibility. Injectable treatments, including corticosteroids and emerging biologics, occupy a specialized niche for keloid and hypertrophic scar management where surgical recurrence rates remain elevated.
FDA 510(k) clearance pathways govern laser device market entry, while the EPA regulates volatile organic compounds in topical formulations, shaping reformulation costs for manufacturers. Health Canada and PMRA standards in the Canadian market create additional compliance layers for cross-border product registration. Stakeholders must monitor reimbursement code evolution for laser-based scar revision as private payers reassess coverage criteria for cosmetic-adjacent procedures.
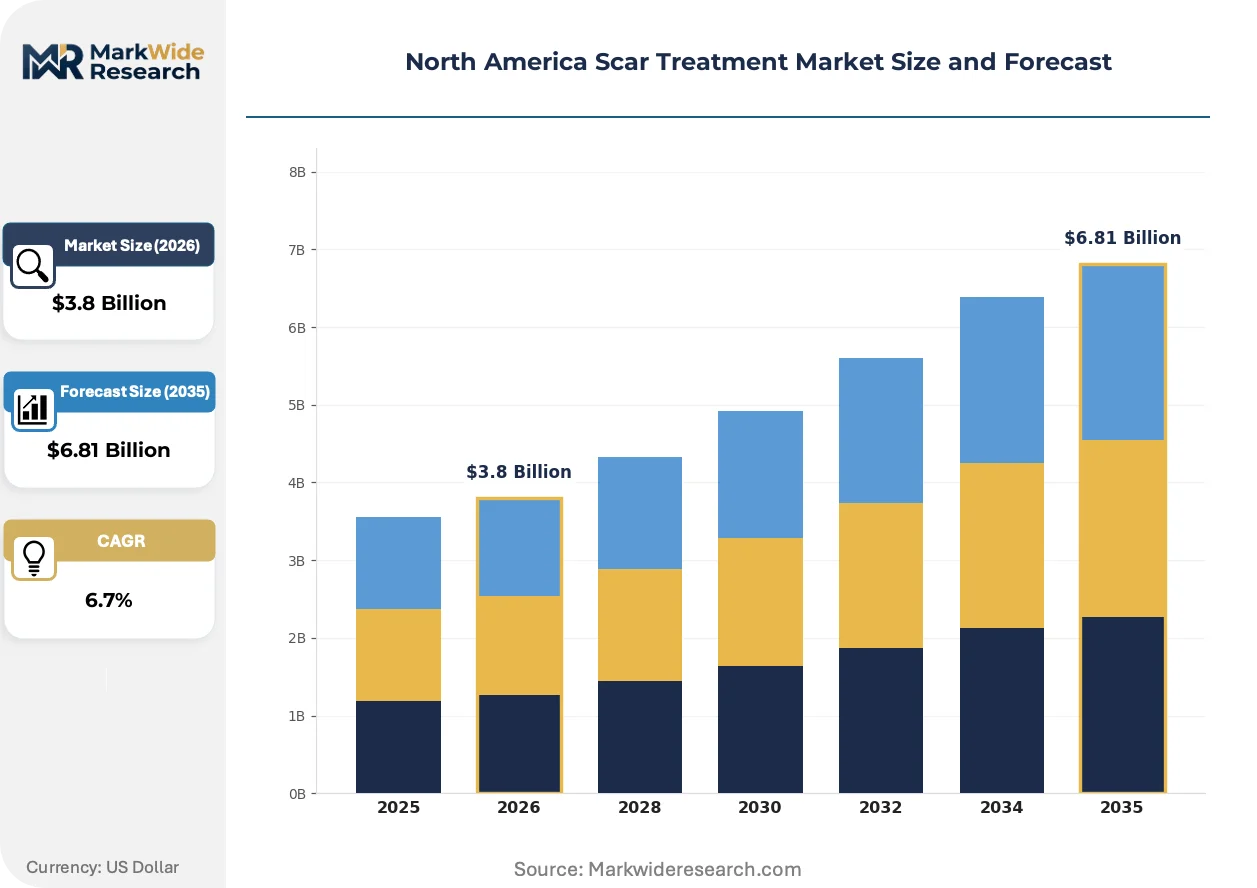
Market Dynamics
The North America scar treatment market is restructuring around outpatient migration, with aesthetic centers capturing procedural volume formerly routed through hospital outpatient departments. This channel shift compresses reimbursement complexity while elevating capital efficiency requirements for device vendors.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for laser systems with predicate devices are accelerating commercialization timelines for fractional resurfacing platforms.
- Silicone Hydration Science:Occlusive wound care protocols in post-surgical settings are expanding silicone sheet utilization beyond burn scars into routine dermatologic procedures.
- Texas Metropolitan Corridors:Concentrated aesthetic center density across Dallas-Fort Worth and Houston is generating disproportionate demand for combination laser-topical treatment packages.
Market Restraints
- Capital Equipment Intensity:Fractional CO2 and pulsed-dye laser systems require substantial upfront investment, constraining independent dermatology practice participation.
- EPA VOC Reformulation:Volatile organic compound restrictions on topical scar gel solvents are forcing manufacturers to reformulate silicone-based products at elevated R&D cost.
- Keloid Recurrence Rates:Surgical excision alone demonstrates elevated recurrence for keloid pathologies, limiting procedural confidence and repeat intervention rates.
Strategic Opportunities
- Canadian Market Expansion:Health Canada and PMRA registration pathways present underexploited entry points for silicone sheet manufacturers with US distribution infrastructure.
- Biologic Convergence:Emerging injectable therapies targeting TGF-beta signaling pathways offer white space for keloid and hypertrophic scar management beyond corticosteroid standards.
- Direct-to-Consumer Channels:E-commerce platforms for silicone gel sheets are bypassing traditional wound care distribution, capturing homecare segments previously served through retail pharmacy.
Industry Challenges
- Laser Technician Certification:State-level medical board variations in laser operator licensing create compliance fragmentation across California, Texas, and Florida markets.
- Reimbursement Code Evolution:Private payer reassessment of cosmetic-adjacent procedure coverage is creating uncertainty for laser-based scar revision coding and prior authorization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Scar Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hypertrophic Scars, Keloid Scars, Atrophic Scars, Contracture Scars Product Type: Silicone Gel, Creams, Sheets, Laser Devices End User: Hospitals, Clinics, Homecare, Aesthetic Centers Treatment Method: Topical Therapy, Surgical Intervention, Laser Therapy, Injectable Treatments |
| Companies Covered | Smith & Nephew PLC, Merz Pharmaceuticals, Lumenis, Cynosure, Sonoma Pharmaceuticals Inc., CCA Industries Inc., Mölnlycke Health Care AB, Avita Medical Limited, Enaltus LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Scar Treatment Market Evolving Landscape
Device automation and algorithmic treatment planning are redefining clinical workflow efficiency in scar revision, while regulatory clarity and consumer channel preferences reshape competitive positioning across product categories.
Fractional laser systems equipped with real-time skin temperature monitoring and automated pulse delivery are automating treatment parameter selection previously requiring extensive clinician judgment. Aesthetic centers with high patient throughput are adopting these platforms most aggressively. This automation is compressing training timelines and reducing operator-induced outcome variability across metropolitan Texas and Florida corridors.
FDA guidance documents on laser device software as a medical device are clarifying validation requirements for algorithmic treatment planning modules. Manufacturers must now document clinical performance of automated dosing algorithms through controlled studies. Fractional resurfacing platforms with embedded intelligence face the steepest compliance burden, with California-based vendors investing heavily in predicate device alignment strategies.
Consumer purchasing for silicone-based scar management is migrating from retail pharmacy shelves to subscription e-commerce models with automated replenishment cycles. Amazon and direct brand storefronts are displacing hospital discharge kit bundling as the primary acquisition channel. This behavioral shift is most pronounced in Florida and California, where aesthetic-conscious patient populations demonstrate elevated willingness to self-direct post-procedural care purchases.
North America Scar Treatment Market Segmentation
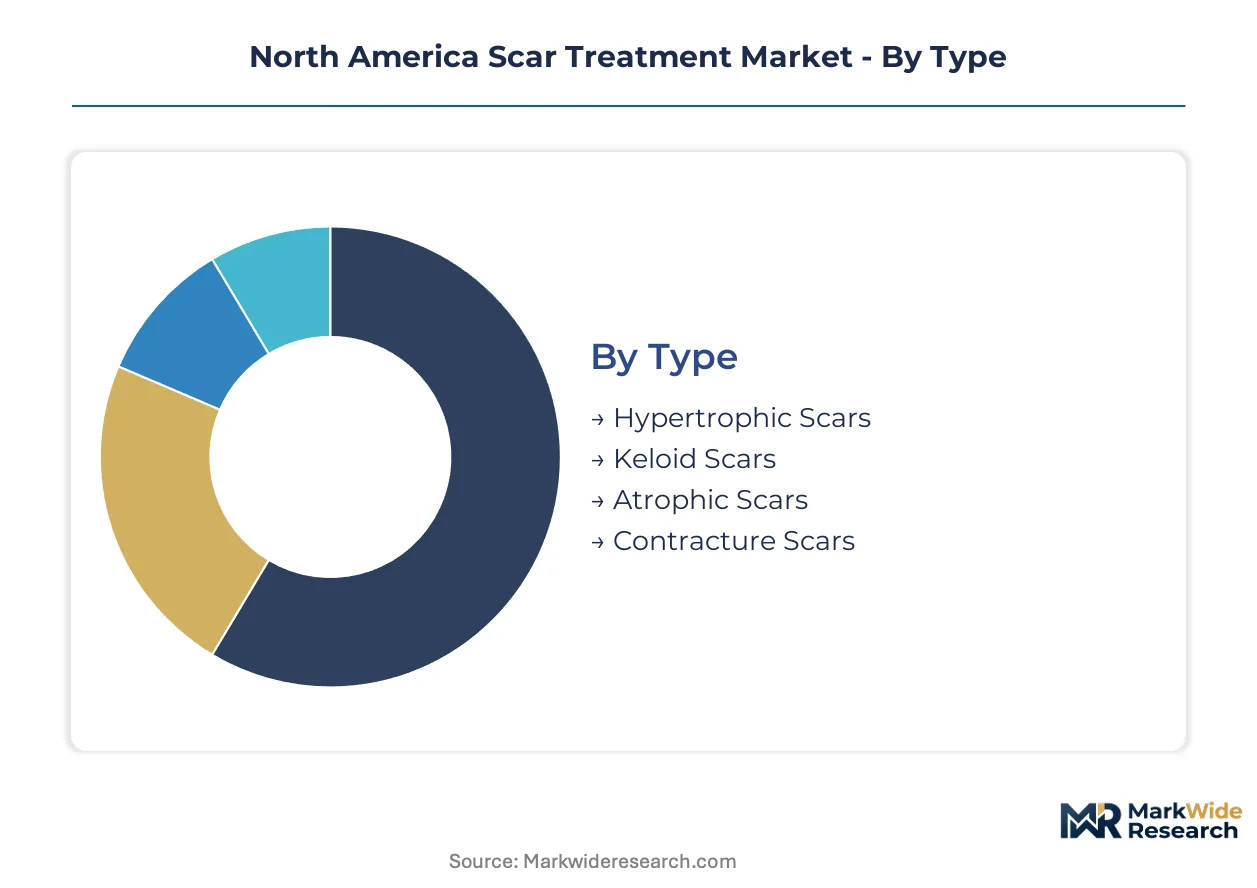
Scar treatment segmentation reveals distinct procurement patterns across standalone homecare products versus embedded clinic-based systems. Understanding these integration pathways clarifies why silicone sheets dominate retail pharmacy while laser platforms concentrate in metropolitan aesthetic centers.
Type:
Standalone topical management suits superficial scar types, while embedded procedural interventions address deeper fibrotic pathologies requiring clinician oversight.
- Hypertrophic Scars:Raised fibrous tissue remaining within original wound boundaries responds to silicone occlusion and pressure therapy. Demand concentrates in post-surgical dermatology across Texas and Florida metropolitan corridors, driven by elevated cosmetic procedure volume and patient willingness to pursue adjunctive homecare.
- Keloid Scars:Aggressive fibroproliferative growth extending beyond wound margins requires multimodal intervention combining corticosteroid injection, laser, and surgical excision. Aesthetic centers in California report the highest recurrence-driven repeat treatment rates, constraining standalone procedural economics.
- Atrophic Scars:Depressed collagen-deficient tissue common in acne and varicella histories.
- Contracture Scars:Functional impairment across joints from burn injury requiring surgical release and grafting.
Volume placements concentrate in Hypertrophic Scars; the faster expansion belongs to Keloid Scars.
Product Type:
Cost tier stratification separates premium capital equipment from disposable consumables, with reimbursement pathways diverging sharply across these economic boundaries.
- Silicone Gel:Cross-linked polysiloxane formulations creating semi-occlusive hydration barrier over healing dermis. Homecare acquisition through Amazon and direct-to-consumer channels is displacing hospital discharge bundling in California and Florida patient populations.
- Laser Devices:Fractional CO2 and pulsed-dye systems delivering selective photothermolysis for collagen remodeling. Capital equipment intensity limits placement to hospital outpatient departments and high-volume aesthetic centers across Dallas-Fort Worth and Houston corridors.
- Creams:Emulsion-based formulations with onion extract or vitamin E active ingredients.
- Sheets:Self-adherent silicone membranes for extended occlusive therapy.
Revenue concentration sits with Laser Devices; unit volume leadership belongs to Silicone Gel.
End User:
Customer type migration patterns show procedural volume shifting from institutional settings toward specialized outpatient facilities with streamlined operational models.
- Aesthetic Centers:Dedicated cosmetic facilities capturing scar revision volume through combination package pricing and reduced administrative overhead. Texas metropolitan corridors demonstrate the densest center concentration, generating disproportionate demand for integrated laser-topical treatment protocols.
- Homecare:Patient-directed management utilizing over-the-counter silicone products and physician-prescribed topical regimens. Florida and California patient populations show the highest self-directed purchasing propensity through subscription e-commerce models.
- Hospitals:Acute care settings with burn centers and surgical departments.
- Clinics:Dermatology and plastic surgery offices with limited capital equipment.
Procedure volume concentrates in Aesthetic Centers; product unit expansion is climbing fastest in Homecare.
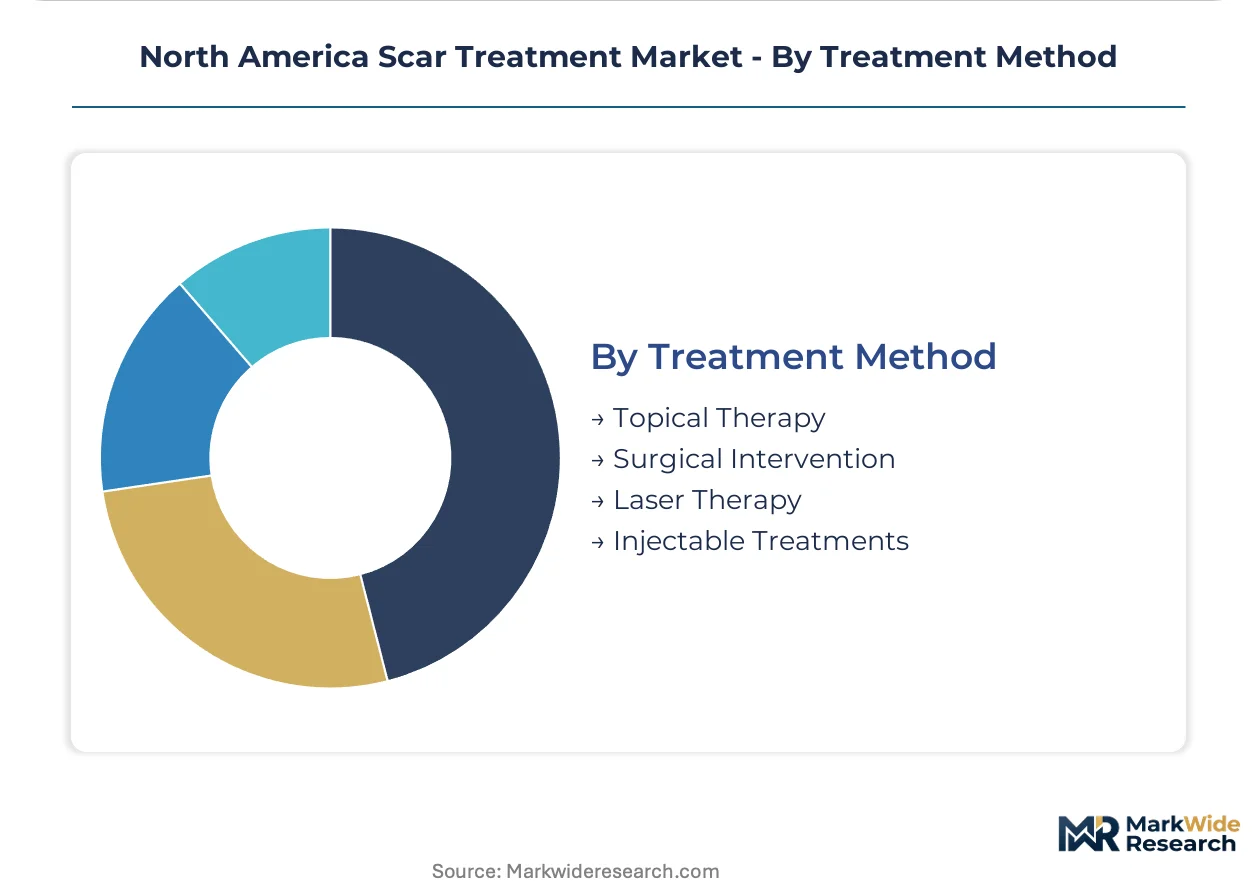
Treatment Method:
Maturity differentiation separates established first-line therapies from emerging modalities still navigating reimbursement code establishment and clinical evidence accumulation.
- Topical Therapy:Silicone-based hydration protocols and pharmacologic creams applied through patient-administered regimens. FDA 510(k) clearance pathways govern commercial entry, with EPA VOC restrictions forcing solvent reformulation at elevated manufacturer cost.
- Laser Therapy:Device-based collagen remodeling through controlled thermal injury delivered in serial treatment sessions. Private payer reassessment of cosmetic-adjacent coverage creates coding uncertainty across California, Texas, and Florida markets.
- Surgical Intervention:Excision, Z-plasty, and grafting procedures for functional restoration.
- Injectable Treatments:Corticosteroid and emerging biologic therapies targeting TGF-beta signaling.
Patient visit volume concentrates in Topical Therapy; technology investment intensity is expanding most quickly in Laser Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of scar treatment devices and topicals, while Canada and Mexico import specialized laser systems and silicone-based formulations from US and European suppliers. Production of capital equipment clusters in California and Massachusetts, with formulation manufacturing distributed across Midwest pharmaceutical corridors.
United States
FDA 510(k) clearance pathways govern laser device commercialization, with California-based vendors investing heavily in predicate device alignment strategies. The EPA regulates volatile organic compounds in topical scar gel solvents, forcing manufacturers to reformulate silicone-based products at elevated cost. Aesthetic center density across Dallas-Fort Worth and Houston generates disproportionate demand for combination laser-topical treatment packages.
Canada
Health Canada and PMRA registration standards create additional compliance layers for cross-border product registration of silicone sheets and laser systems. Health Canada guidance on software as a medical device clarifies validation requirements for algorithmic treatment planning modules. Toronto and Vancouver metropolitan areas concentrate demand for outpatient scar revision procedures as private clinic networks expand.
Mexico
COFEPRIS regulatory pathways govern pharmaceutical and medical device market entry, with import dependencies for advanced laser platforms. Mexico's national pharmaceutical regulator maintains alignment with FDA standards for expedited review of predicate devices. Mexico City and Monterrey anchor aesthetic center growth, with Guadalajara emerging as a secondary hub for dermatology clinic expansion.
North America Scar Treatment Market Competitive Landscape
Top-tier vendors anchor premium laser device segments, while mid-tier specialists dominate silicone sheet distribution and topical formulation supply. The vendor base stratifies across capital equipment intensity tiers, with fractional CO2 and pulsed-dye laser manufacturers requiring substantial upfront investment versus disposable consumable suppliers. Three archetypes define competitive positioning: wound care heritage players extending into scar protocols, pure-play laser technology vendors, and emerging biologic therapy developers. Dominant competitive moves include strategic partnerships between device manufacturers and aesthetic center chains, plus portfolio diversification into combination therapy packaging.
Within the wound care heritage tier, Smith & Nephew PLC and Mölnlycke Health Care AB exemplify incumbents leveraging established distribution infrastructure. Lumenis occupies a position representing pure-play laser technology leadership. These three entities illustrate how competitive advantage derives from channel control depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| Merz Pharmaceuticals |
| Lumenis |
| Cynosure |
| Sonoma Pharmaceuticals Inc. |
| CCA Industries Inc. |
| Mölnlycke Health Care AB |
| Avita Medical Limited |
| Enaltus LLC |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock indices and fractional laser component costs cascade through North American scar treatment supply chains into three-tier pricing structures across premium capital equipment, standard clinic-based systems, and economy homecare consumables. EPA-mandated VOC reformulation is elevating raw material input costs for topical manufacturers while aesthetic center procurement consolidation amplifies volume discount leverage.
Pricing Analysis
Margin tightening in silicone gel manufacturing reflects EPA solvent reformulation compliance costs and raw material price volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared laser platforms from clinic-branded topical kits and direct-to-consumer sheet products. Cost-down pressure on economy-tier homecare accelerates as Amazon subscription models displace retail pharmacy margins. Aesthetic centers demonstrate lowest price sensitivity due to package bundling, while independent dermatology clinics face highest capital equipment procurement constraints.
Supply Chain Analysis
Dual-sourcing requirements from GPOs and aesthetic center chains mandate multi-supplier qualification for silicone sheet vendors across US and Canadian distribution networks. Manufacturing concentrates in US Midwest pharmaceutical corridors for topical formulations, California and Massachusetts for laser device assembly, and imported German and Israeli optical components for fractional systems. Supply chain risk centers on single-source vulnerability for medical-grade silicone polymers and pulsed-dye laser resonator tubes. Distribution runs through specialized wound care distributors, direct-to-consumer e-commerce platforms, and hospital discharge kit bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American scar treatment markets are consolidating around capital-intensive laser platforms and regulatory-compliant topical portfolios, with EPA reformulation costs and FDA 510(k) validation burdens forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Deepen vertical integration into medical-grade silicone polymer supply through captive manufacturing agreements or tolling arrangements with Midwest chemical processors. Expand algorithmic laser platform software validation pipelines ahead of FDA guidance finalization to preempt competitor predicate device alignment. Threat substitution from emerging TGF-beta biologic injectables demands accelerated R&D partnership structures with dermatology academic centers. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels for silicone gel products targeting Florida and California patient populations with elevated self-directed purchasing propensity. White-space targets include Canadian Health Canada registration pathways for US-formulated silicone sheets and biologic convergence therapies for keloid recurrence management. Go-to-market angle should emphasize automated replenishment cycles and telehealth-integrated post-procedural care protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor wound care heritage players with established GPO contracts and silicone sheet distribution infrastructure in Texas and California metropolitan corridors. Long-term viability across the projection horizon hinges on regulatory compliance scalability and aesthetic center chain partnership depth. Signal to watch is private payer reimbursement code expansion for laser-based scar revision as cosmetic-adjacent coverage criteria evolve.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance timelines compress commercialization lag for fractional resurfacing platforms against predicate devices. |
| Health Canada PMRA Registration | Cross-border regulatory alignment unlocks Canadian aesthetic center demand through existing US distribution infrastructure. |
| Aesthetic Center Chain Partnership | Combination laser-topical package pricing secures procedural volume commitment across Dallas-Fort Worth and Houston corridors. |
| Direct-to-Consumer Channel Launch | Amazon and brand storefront displacement of retail pharmacy captures Florida and California homecare subscription growth. |
| Biologic Therapy Pipeline Investment | TGF-beta signaling pathway targeting addresses keloid recurrence limitations constraining standalone procedural economics. |
Research Methodology
FDA 510(k) device filings, EPA regulatory dockets, and hospital procurement database extracts formed the secondary backbone, cross-referenced with primary interviews involving aesthetic center operators, dermatology clinic purchasing managers, biomedical engineers at laser device manufacturers, and silicone formulation chemists at topical suppliers. Bottom-up and top-down triangulation validated segment-level demand estimates against GPO contract volumes and direct-to-consumer channel shipment data.
Bottom-up modeling aggregated procedure volume by scar type, treatment method, and end-user channel across the projection horizon. Segmentation dimensions included hypertrophic versus keloid versus atrophic scar indications, silicone gel versus laser device versus injectable product categories, and aesthetic center versus homecare versus hospital settings. CAGRs derived from regression analysis of historical FDA clearance timelines, aesthetic center expansion rates, and patient-reported outcome adoption curves.
Regulatory delay, private payer reimbursement retraction, and silicone raw material supply disruption are the dominant revision risks to forecast assumptions. Deviation in FDA software-as-medical-device guidance finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market