
 Radiotherapy Patient Positioning Accessories Market | 2026-2036
Radiotherapy Patient Positioning Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Patient Positioning Accessories Market Outlook
A shift from single-source to multi-source procurement for thermoplastic masks and vacuum cushions is recalibrating supplier relationships across radiotherapy departments. Elekta leverages its integrated linear accelerator ecosystem to bundle positioning systems with treatment delivery contracts. CIVCO Radiotherapy anchors its market presence through specialized immobilization devices for head and neck applications. Qfix competes on modular platform designs that accommodate multiple anatomical sites without dedicated hardware swaps.
Radiotherapy patient positioning accessories comprise patient immobilization devices, indexing systems, and setup verification tools manufactured from thermoplastic resins, low-density foams, and carbon-fiber composites to achieve sub-millimeter repositioning accuracy during fractionated treatment courses. These accessories serve the essential function of minimizing inter-fraction and intra-fraction motion to preserve the therapeutic ratio between tumor control and normal tissue sparing. Head and neck immobilization occupies the largest revenue pool due to steep dose gradients in parotid and optic pathway sparing protocols, while body positioning systems represent the fastest-expanding category as stereotactic ablative radiotherapy for lung and oligometastatic disease proliferates. Breast positioning devices command premium pricing in proton therapy settings where cardiac sparing demands reproducible deep-inspiration breath-hold configurations.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern material biocompatibility and mechanical stability testing for reusable positioning accessories. ISO 13485 quality management systems and IEC 60601-2-1 electrical safety standards further constrain design choices for integrated positioning-electronic interfaces. Stakeholders must monitor evolving reimbursement codes for image-guided setup verification, as payor acceptance of adaptive replanning workflows will determine capital allocation between fixed installation platforms and portable repositioning systems.
Market Dynamics
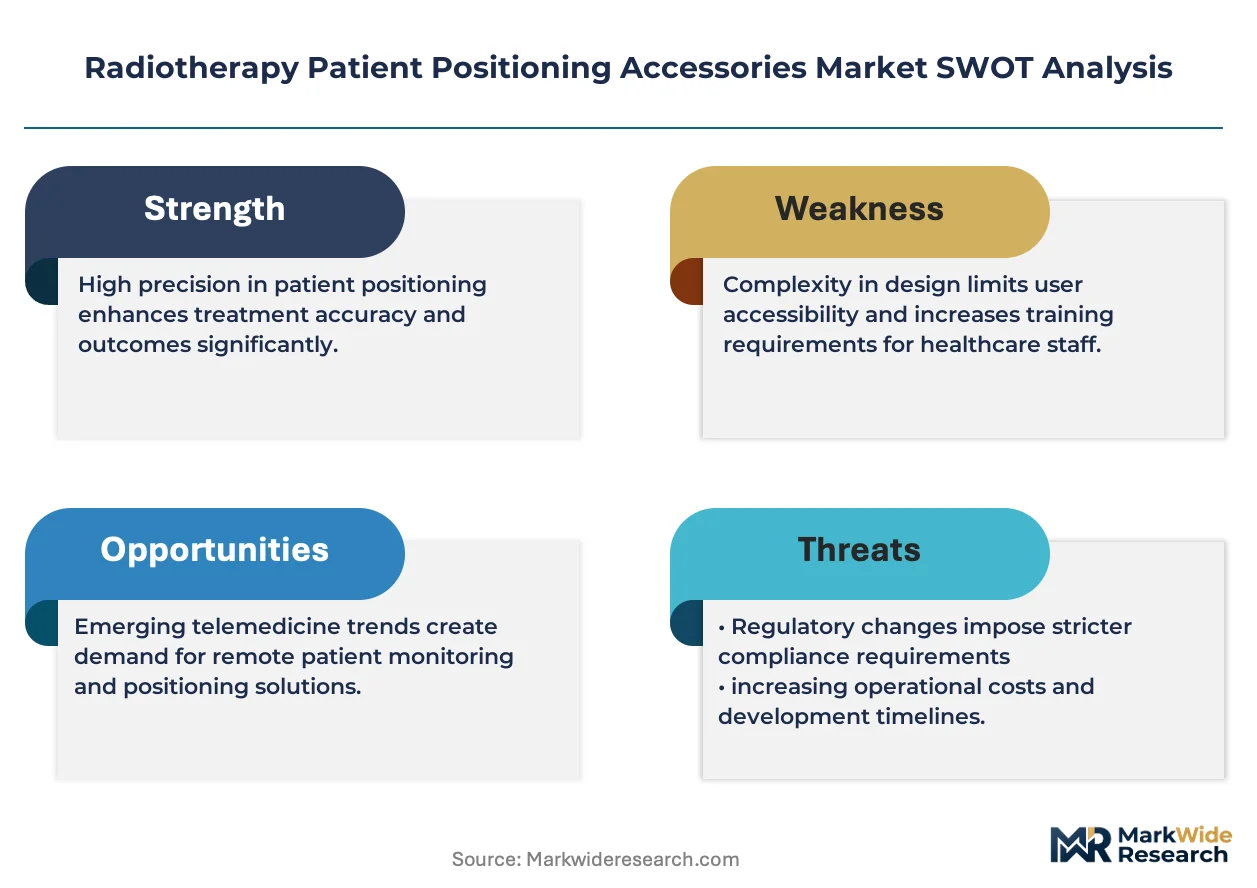
Hypofractionated radiotherapy regimens are compressing setup tolerances from millimeters to sub-millimeter thresholds, forcing positioning accessory specifications to tighten across every treatment modality. This precision imperative is restructuring supplier qualification criteria and procurement evaluation frameworks in oncology departments worldwide.
Growth Catalysts
- EU MDR compliance deadlines:CE marking renewal cycles under the Medical Device Regulation are accelerating replacement of legacy thermoplastic masks with next-generation biocompatible formulations certified for extended reuse cycles.
- Proton therapy center construction:Installation of particle therapy systems in the United States, Germany, and China is generating dedicated demand for carbon-fiber indexing cradles that withstand gantry rotation stresses.
- Adaptive replanning workflows:Daily image-guided setup verification is expanding the installed base of reusable positioning platforms with integrated radio-opaque fiducial arrays.
Market Restraints
- Thermoplastic resin price volatility:Petrochemical feedstock fluctuations are compressing gross margins for mask manufacturers dependent on copolyester sheet extrusion.
- Carbon-fiber composite supply concentration:Toray Industries and Hexcel Corporation control aerospace-grade prepreg supply chains, creating bottleneck risk for radiotherapy positioning cradle producers.
- Reimbursement code lag:CMS and national health technology assessment bodies have not established distinct procedure codes for advanced immobilization, limiting capital recovery timelines.
Strategic Opportunities
- India cancer center expansion:Tata Memorial Centre and regional government oncology networks are procuring vacuum cushion systems for linear accelerator installations in tier-2 cities.
- Surface-guided radiation therapy convergence:Optical tracking systems from Vision RT and CatalystHD are creating integration partnerships with positioning device manufacturers for markerless setup verification.
- Japan superconducting rotating-gantry proton facilities:National Institute of Radiological Sciences installations are specifying ultra-lightweight immobilization to accommodate reduced structural load limits.
Industry Challenges
- Medical physics staffing scarcity:Qualified radiation therapists capable of commissioning custom immobilization protocols are concentrated in academic medical centers, limiting community hospital adoption.
- Legacy linear accelerator retrofit complexity:Couch top indexing interfaces from Varian Medical Systems and Elekta use proprietary rail geometries, complicating third-party positioning system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Patient Positioning Accessories Market |
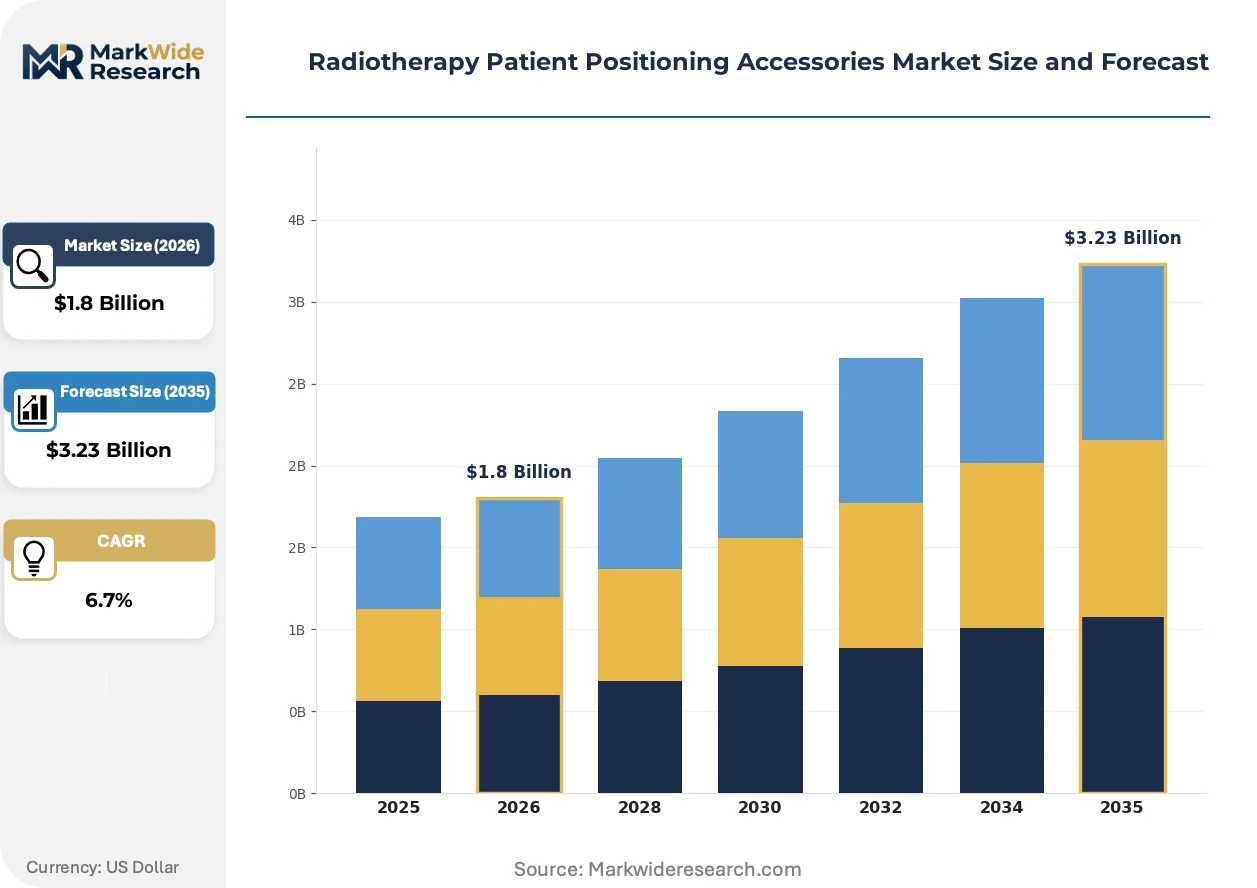
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head & Neck Immobilization, Body Positioning Systems, Breast Positioning Devices, Stereotactic Frames Material: Foam, Plastics, Metal, Silicone End User: Hospitals, Cancer Treatment Centers, Research Institutes, Home Healthcare Providers Installation: Fixed, Portable, Modular, Integrated |
| Companies Covered | Elekta, Mizuho OSI, CIVCO Radiotherapy, Bionix Radiation Therapy, CDR Systems, Qfix, Klarity Medical, Landauer, Orfit Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Patient Positioning Accessories Market Strategic Shifts
Digital manufacturing methods are penetrating positioning accessory production, compressing prototyping cycles from months to weeks while enabling patient-specific geometries. This capability shift is redrawing competitive boundaries between mass-produced and customized immobilization.
Carbon-fiber reinforced thermoplastic composites are overtaking traditional fiberglass-epoxy laminates in body immobilization cradles. Major proton therapy centers in the United States and Germany are specifying these materials for their superior strength-to-weight ratios and reduced neutron activation. The structural consequence is a bifurcation in supplier tiers, with composite-capable manufacturers capturing premium positioning contracts while conventional fabricators retreat to cost-sensitive photon therapy segments.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence packages for reusable positioning devices previously grandfathered under the Medical Devices Directive. Manufacturers must now submit biocompatibility testing per ISO 10993 and mechanical fatigue data for multi-year reuse claims. Head and neck mask suppliers are most affected, with several European players withdrawing legacy SKUs rather than absorbing notified body review costs.
Hospital procurement departments are consolidating vendor panels for positioning accessories, replacing single-item purchasing with multi-year framework agreements that bundle masks, cushions, and indexing systems. Group purchasing organizations in the United States are driving this consolidation, awarding sole-source contracts to suppliers offering training credits and loaner device programs. The shift is most visible in community oncology practices lacking dedicated medical physics support, where vendor-managed inventory reduces stockout risk.
Radiotherapy Patient Positioning Accessories Market Segmentation
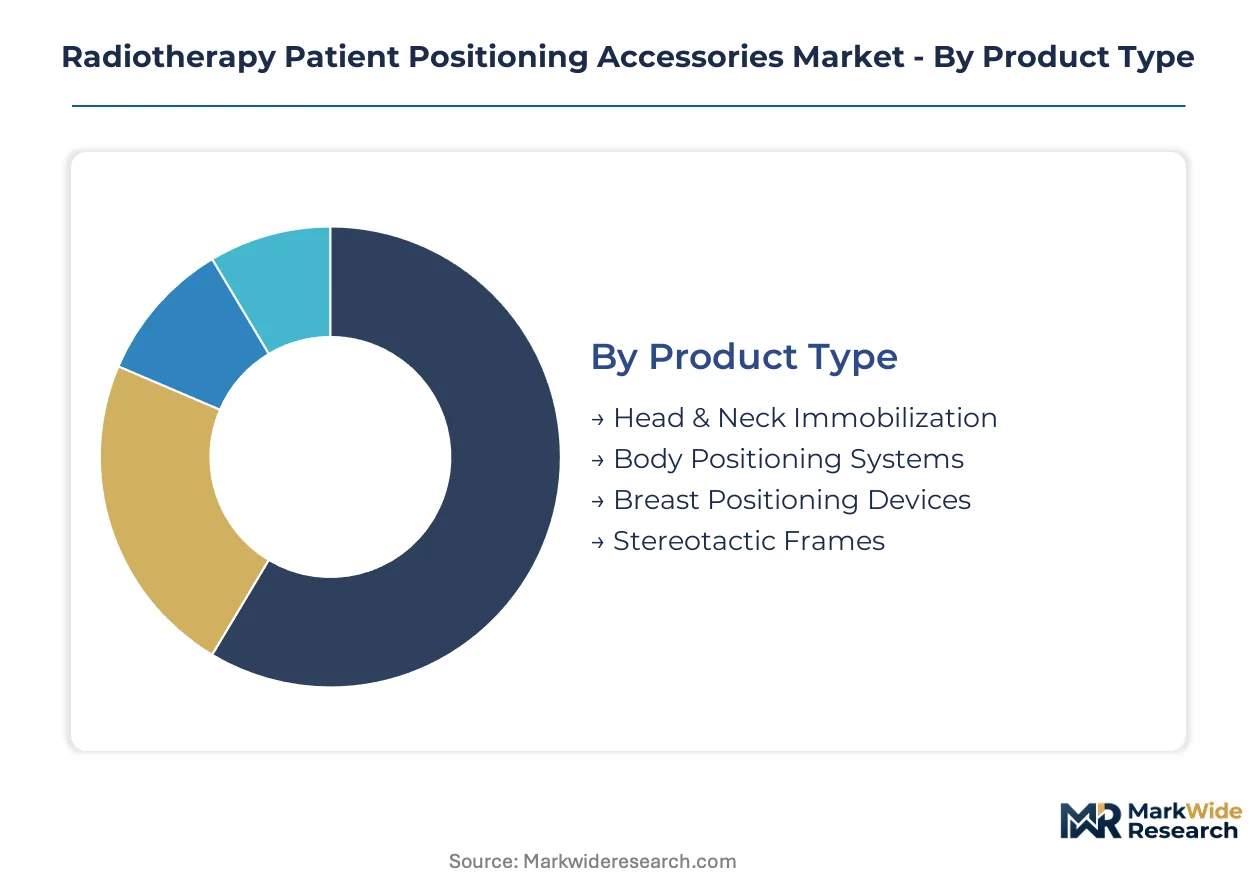
Segmentation in radiotherapy positioning accessories determines procurement pathways, regulatory submission strategies, and service revenue models. Material specifications and installation architectures shape compatibility with linear accelerator ecosystems across treatment modalities.
Product Type:
Volume concentration sits with established photon therapy applications, while premium expansion tracks hypofractionated and particle therapy adoption.
- Head & Neck Immobilization:Thermoplastic masks and bite-block systems achieve sub-millimeter reproducibility for parotid and optic pathway sparing. Demand concentrates in academic medical centers across the United States and Germany where complex oropharyngeal protocols require daily image-guided verification.
- Body Positioning Systems:Vacuum cushions and carbon-fiber cradles accommodate thoracic and abdominal immobilization for stereotactic ablative regimens. Cancer treatment centers in China are expanding orders as lung SBRT volumes multiply.
- Breast Positioning Devices:Deep-inspiration breath-hold platforms with integrated cardiac monitoring.
- Stereotactic Frames:Invasive and frameless radiosurgery reference systems for cranial lesions.
Today's leader: Head & Neck Immobilization. Tomorrow's challenger: Body Positioning Systems.
Material:
Cost tiers separate disposable commodity inputs from durable composite platforms with extended reuse certification.
- Foam:Open-cell polyurethane and memory foam formulations provide patient comfort layers and vacuum cushion cores. Hospitals in tier-2 Indian cities prefer foam-based systems for lower capital outlay on linear accelerator commissioning.
- Plastics:Copolyester thermoplastic sheets dominate mask fabrication with radio-translucent properties. FDA 510(k) clearance pathways for new biocompatible formulations are extending development timelines for European suppliers.
- Metal:Aluminum and titanium indexing hardware for couch-top interfaces.
- Silicone:Soft-tissue equivalent materials for pediatric and surface-molded applications.
Plastics command the largest procurement volumes. Carbon-fiber composites embedded in plastic substrates are gaining the steepest expansion trajectory.
End User:
Customer type dictates service intensity, with research institutes requiring custom fabrication against standardized hospital contracts.
- Hospitals:Integrated delivery networks with dedicated medical physics departments manage multi-site immobilization standardization. Community hospital systems in the United States are consolidating vendor panels to reduce stockout risk across radiation oncology departments.
- Cancer Treatment Centers:Dedicated oncology facilities with high fraction volumes drive reusable platform adoption. Proton therapy centers in Germany specify carbon-fiber cradles for gantry rotation durability.
- Research Institutes:National Institute of Radiological Sciences in Japan and academic consortia commission patient-specific geometries for protocol development.
- Home Healthcare Providers:Emerging category for portable positioning in palliative radiotherapy delivery.
Hospitals anchor current purchasing volume. Cancer Treatment Centers are expanding most quickly as standalone proton and carbon-ion facilities proliferate.
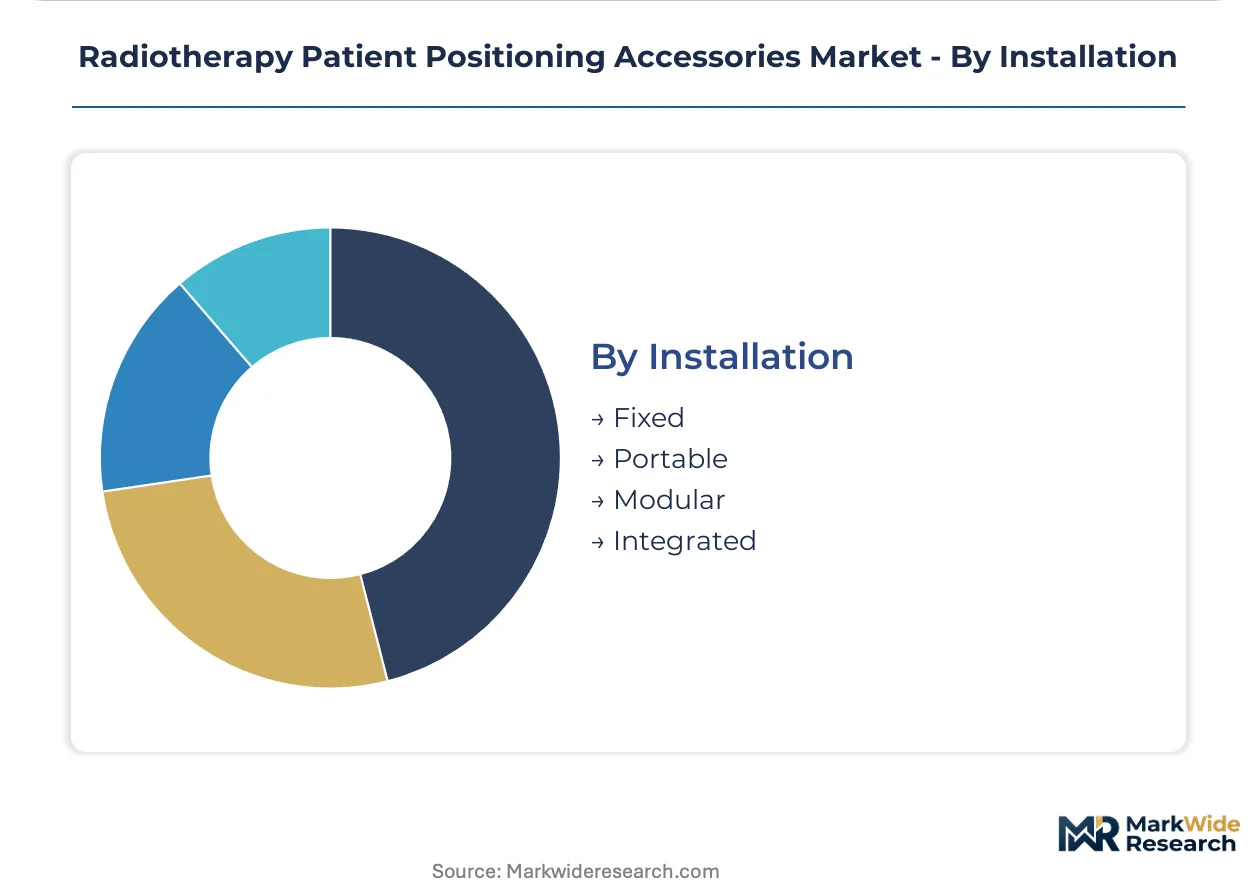
Installation:
Architecture choices reflect capital deployment philosophy between permanent infrastructure and adaptive workflow flexibility.
- Fixed:Permanent couch-top indexing systems with proprietary rail geometries from Varian Medical Systems and Elekta. Academic medical centers in the United States favor fixed installations for high-throughput photon therapy suites.
- Portable:Lightweight repositioning platforms enabling multi-room utilization and linear accelerator sharing. Regional oncology networks in India specify portable vacuum cushion systems for equipment mobility across tier-2 city installations.
- Modular:Interchangeable cradle and mask configurations for anatomical site flexibility without dedicated hardware.
- Integrated:Positioning-electronic interfaces with embedded fiducial arrays for surface-guided radiation therapy convergence.
Fixed installations dominate legacy linear accelerator fleets. Modular platforms are gaining share fastest as hypofractionated regimens demand anatomical flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Proton therapy corridor spanning Boston to Philadelphia anchors procurement volumes for carbon-fiber positioning cradles. Academic medical centers in Germany and Japan commission patient-specific geometries for hypofractionated protocols. Installation growth in China and India is reshaping supplier qualification frameworks across Asia-Pacific.
United States
Proton therapy center construction in Florida, Texas, and California is generating dedicated demand for gantry-compatible indexing systems. FDA 510(k) clearance pathways for reusable thermoplastic masks are tightening biocompatibility documentation requirements. The MD Anderson Cancer Center proton facility in Houston specifies carbon-fiber cradles with embedded fiducial arrays for daily image-guided verification workflows.
Germany
Heidelberg Ion-Beam Therapy Center and Munich proton facilities are commissioning ultra-lightweight immobilization for rotating-gantry installations. EU MDR Article 10 technical documentation mandates clinical evidence packages for legacy mask renewals. The DKFZ German Cancer Research Center cluster drives standardization protocols for head and neck positioning across university hospital networks.
China
Carbon-ion therapy installations at Shanghai Proton and Heavy Ion Center and Lanzhou facilities are accelerating orders for neutron-resistant composite cradles. NMPA medical device registration rules are extending approval timelines for imported positioning systems. The Yangtze River Delta oncology corridor concentrates domestic vacuum cushion manufacturing for tier-2 city linear accelerator deployments.
Japan
National Institute of Radiological Sciences superconducting rotating-gantry proton facilities are specifying reduced-weight immobilization for structural load constraints. PMDA quality management system inspections govern reusable device certification for extended reuse cycles. The Chiba clinical proton research cluster commissions patient-specific geometries for protocol development in carbon-ion therapy.
India
Tata Memorial Centre Mumbai and regional government oncology networks are procuring portable vacuum cushion systems for linear accelerator installations in tier-2 cities. CDSCO medical device import licensing requirements are constraining supplier qualification for European and North American manufacturers. The Delhi-NCR cancer center corridor is consolidating vendor panels for thermoplastic mask standardization across public hospital networks.
Radiotherapy Patient Positioning Accessories Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue surface-guided radiation therapy integration partnerships. The supplier base concentrates around linear accelerator ecosystem bundling and specialized immobilization fabrication. Three archetypes dominate: integrated equipment vendors with treatment delivery contracts, dedicated positioning device specialists, and composite material fabricators serving proton therapy specifications. Competitive moves center on multi-year framework agreements with group purchasing organizations and digital manufacturing capability investments for patient-specific prototyping.
Within the integrated systems tier, Elekta anchors positioning accessory bundling with linear accelerator contracts across European and North American academic centers. CIVCO Radiotherapy and Qfix occupy specialized fabrication positions, with the former emphasizing head and neck applications and the latter modular platform designs for anatomical flexibility. These three entities exemplify divergent strategic postures: ecosystem lock-in versus anatomical specialization versus workflow adaptability.
| Leading Market Players |
|---|
| Elekta |
| Mizuho OSI |
| CIVCO Radiotherapy |
| Bionix Radiation Therapy |
| CDR Systems |
| Qfix |
| Klarity Medical |
| Landauer |
| Orfit Industries |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber composite certification tiers bifurcate supplier economics between proton therapy-grade manufacturers and photon therapy commodity fabricators, with FDA 510(k) clearance timelines and EU MDR Article 10 compliance costs embedding directly into quoted pricing and sourcing geography. This tier divergence concentrates premium positioning system production in Germany and the United States while vacuum cushion manufacturing migrates to lower-cost Asian fabrication hubs serving price-sensitive Indian and Chinese hospital procurement panels.
Pricing Analysis
Petrochemical feedstock pass-through from copolyester resin suppliers compresses gross margins for thermoplastic mask manufacturers serving cost-sensitive photon therapy segments. Three-tier pricing structure across premium carbon-fiber cradles, mid-grade vacuum cushions, and economy foam-based systems reflects FDA clearance tier and reuse cycle certification. Pricing pressure stems from CMS reimbursement code lag for advanced immobilization protocols. Community hospital systems exhibit highest price sensitivity; proton therapy centers accept premium positioning for gantry durability specifications.
Supply Chain Analysis
Dual-sourcing mandates from MD Anderson Cancer Center and Heidelberg Ion-Beam Therapy Center require qualified backup suppliers for carbon-fiber prepreg and thermoplastic sheet extrusion. Manufacturing concentrates in the United States, Germany, and China. Raw material dependencies include Toray Industries aerospace-grade carbon fiber, Hexcel Corporation prepreg formulations, and petrochemical-derived copolyester resins. Single-source vulnerability concentrates in Japanese carbon-fiber supply for neutron-resistant cradles. Distribution runs through group purchasing organizations in the United States and regional oncology network tenders in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU MDR compliance cost inflation in European manufacturing and NMPA registration pathway efficiencies for China-sourced vacuum cushion systems serving price-sensitive Asian procurement panels.
For Market Incumbents: Acquire digital manufacturing capability for patient-specific immobilization prototyping to defend against surface-guided radiation therapy integration partnerships threatening standardized mask volumes. Deepen backward integration into carbon-fiber prepreg supply through captive relationships with Toray Industries or Hexcel Corporation to mitigate aerospace-grade material bottleneck risk. Secure multi-year framework agreements with group purchasing organizations before EU MDR renewal cycles accelerate supplier consolidation. For New Entrants and Emerging Players: Linear accelerator OEM channel partners represent the fastest path to hospital procurement panels lacking dedicated medical physics support. Target tier-2 Indian city cancer centers with portable vacuum cushion systems for equipment-sharing workflows across regional oncology networks. Pursue surface-guided radiation therapy convergence through optical tracking integration partnerships with Vision RT or CatalystHD for markerless setup verification differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed revenue thresholds for European thermoplastic mask specialists with legacy SKU portfolios. Long-term viability favors composite-capable manufacturers with proton therapy center relationships and digital fabrication infrastructure. Watch FDA 510(k) clearance pathway expansion for reusable positioning-electronic interfaces as inflection signal for integrated platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body clinical evidence packages secure CE marking renewal for extended reuse cycle claims. |
| Carbon-Fiber Composite Backward Integration | Captive aerospace-grade prepreg supply insulates proton therapy cradle production from Toray-Hexcel bottleneck risk. |
| Surface-Guided Radiation Therapy Partnership | Optical tracking convergence with Vision RT or CatalystHD enables markerless setup verification premium positioning. |
| Digital Manufacturing Capability Deployment | Patient-specific prototyping compression from months to weeks redraws competitive boundaries against mass-produced immobilization. |
| Group Purchasing Organization Framework Agreement | Multi-year sole-source contracts with training credits reduce stockout risk for community oncology practices. |
Study Parameters
Direct dialogue with radiation oncology department heads, medical physics directors, hospital procurement committee members, and group purchasing organization contract managers grounded qualitative findings in clinical workflow realities and purchasing decision frameworks. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, CMS reimbursement code proposals, and proton therapy center construction permits. Bottom-up installed base modeling and top-down cancer incidence projections were triangulated against manufacturer shipment disclosures.
Segment-level value outputs across product type, material, end user, and installation architecture were generated through patient-volume-linked demand modeling and capital equipment replacement cycle analysis. CAGRs were derived from linear accelerator installation forecasts, hypofractionated regimen adoption curves, and particle therapy center construction pipelines. Industry-specific inputs included EU MDR compliance cost absorption rates and NMPA registration timeline distributions for imported positioning systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement code establishment for adaptive replanning workflows and carbon-fiber composite supply concentration resolution. Deviation in FDA 510(k) clearance pathway stringency or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Breast Pump Flange Market
Medical Devices
Pen Injectors Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Trial Prostheses Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Global Nasal Spray Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Ultrasonic Diathermy Market