
 Scar Treatment Market | 2026-2036
Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Scar Treatment Market Intelligence
Project finance for laser and energy-based device fleets is tilting competitive access toward clinic chains with balance-sheet capacity. Merz Pharmaceuticals leverages its neuromodulator and filler portfolio to anchor bundled scar-revision offerings. Lumenis competes through technology leadership in fractional laser platforms. Cynosure controls distribution density across North American dermatology channels.
Scar treatment encompasses medical and aesthetic interventions that modify collagen remodeling, vascularity, or surface topography of dermal and subdermal tissue. Topical products containing silicone or allantoin represent the most accessible entry point, while laser resurfacing using fractional CO2 or erbium-doped systems delivers controlled thermal injury to stimulate neocollagenesis. Topical products occupy the largest volume position due to over-the-counter availability and post-surgical protocol integration. Laser therapy captures premium margin pools tied to per-session pricing and device utilization rates. Injectable treatments, including corticosteroids and collagen stimulators, serve refractory hypertrophic and keloid presentations where first-line modalities fail.
FDA 510(k) premarket notification governs device commercialization, while EPA oversees sterilants and disinfectants used in clinic settings. ISO 13485 quality management standards shape supplier qualification for OEM device manufacturers. State medical board scope-of-practice rules determine whether non-physician operators may administer laser and energy-based therapies. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device for AI-assisted treatment planning systems.
Market Dynamics
Fractional laser technology is compressing treatment cycles from months to weeks, forcing dermatology clinics to reconfigure staffing models and capital deployment schedules around device utilization rates rather than physician appointment density.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for aesthetic laser devices reduces time-to-clinic from 18 months to under 6 months, enabling faster fleet refresh cycles.
- Post-surgical protocol integration:Silicone sheeting and topical formulations now embed directly into discharge bundles from ambulatory surgery centers, creating automatic demand pull.
- Keloid prevalence in African and Asian descent populations:Higher genetic predisposition to hypertrophic scarring in these demographic clusters concentrates procedure demand in urban dermatology networks serving diverse patient bases.
Market Restraints
- Capital intensity of fractional CO2 systems:Device procurement costs exceeding $150,000 per unit restrict fleet expansion to balance-sheet-strong clinic chains, excluding independent practices.
- Reimbursement fragmentation:Medicare and commercial payors deny coverage for aesthetic scar revision, limiting addressable volume to out-of-pocket payors with discretionary liquidity.
- Silicone raw material concentration:Medical-grade silicone supply clusters in Chinese and German chemical manufacturing corridors, exposing formulators to freight cost volatility and customs delays.
Strategic Opportunities
- AI-assisted treatment planning:Software-as-a-medical-device applications for laser parameter optimization await FDA guidance finalization, creating first-mover advantage for compliant submissions.
- Tele-dermatology triage channels:Remote scar assessment platforms identify candidates for in-clinic intervention, expanding catchment radius beyond traditional geographic constraints.
- Combination therapy bundling:Integrated protocols pairing fractional lasers with intralesional corticosteroids capture premium pricing from refractory keloid patients failed by monotherapy.
Industry Challenges
- Laser operator certification gaps:State medical board scope-of-practice variations create compliance complexity for multi-state clinic chains deploying non-physician technicians.
- Device obsolescence cycles:36-month technology refresh schedules strain depreciation schedules and residual value recovery for leased equipment portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scar Treatment Market |
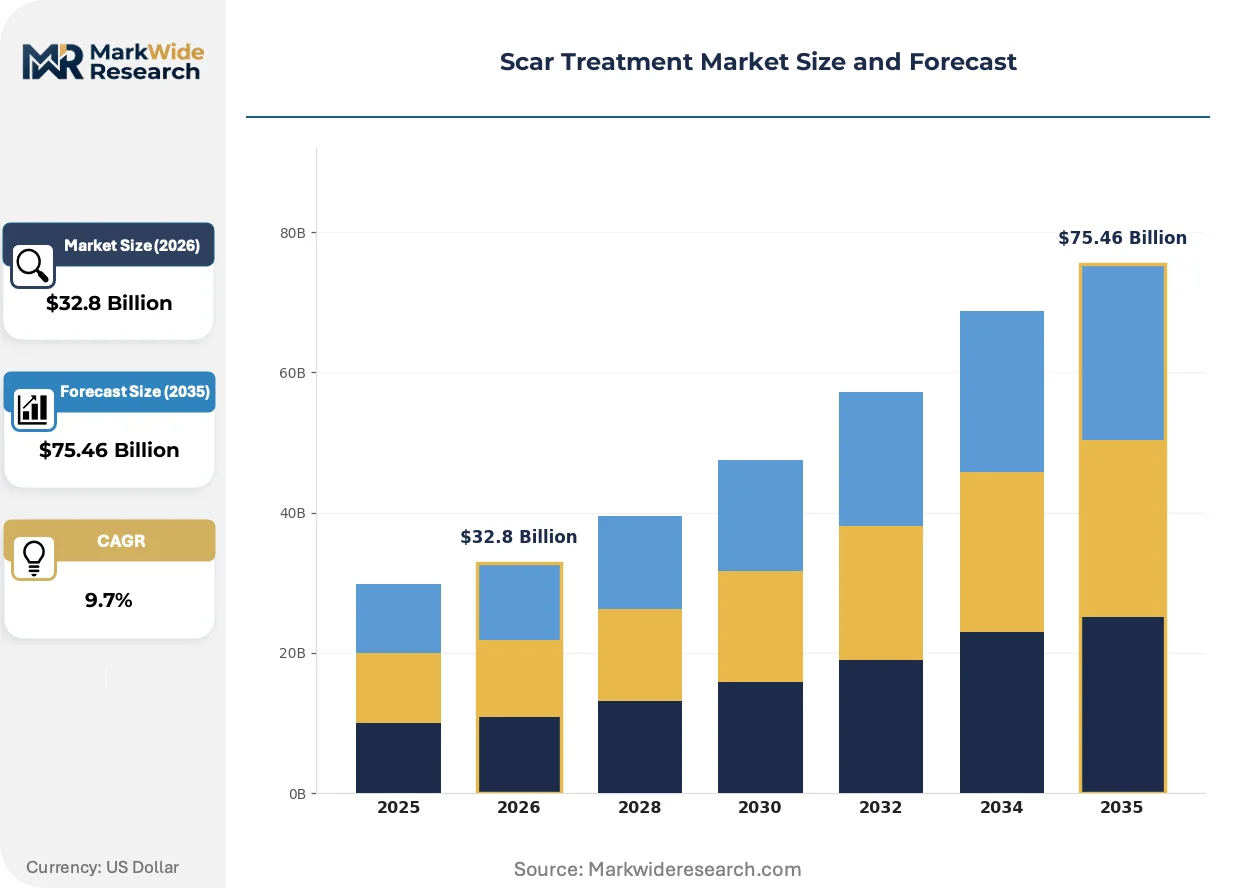
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Products, Laser Therapy, Surgical Treatments, Injectable Treatments End User: Hospitals, Dermatology Clinics, Homecare Settings, Ambulatory Surgical Centers Application: Hypertrophic Scars, Keloid Scars, Atrophic Scars, Acne Scars Technology: Microdermabrasion, Chemical Peels, Radiofrequency Therapy, Laser Resurfacing |
| Companies Covered | Smith & Nephew plc, Merz Pharmaceuticals, Lumenis, Sonoma Pharmaceuticals, Cynosure, Bausch Health Companies, Mölnlycke Health Care, CCA Industries, Candela Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scar Treatment Market Strategic Shifts & Innovations
Three converging forces are restructuring competitive advantage in scar treatment: computational treatment planning, regulatory clarity on software-enabled devices, and channel compression between manufacturers and end-users.
Radiofrequency microneedling is digitizing scar assessment and energy delivery through real-time impedance feedback algorithms. Dermatology clinic chains with centralized purchasing authority are adopting these systems at replacement cycle acceleration. The technology is digitizing outcome prediction, compressing the trial-and-error phase of parameter selection that previously consumed 2-3 sessions per patient.
MDR implementation in Europe is reclassifying certain aesthetic energy devices from Class IIa to Class IIb, triggering notified body involvement and clinical evidence requirements. Manufacturers with legacy technical files face 12-18 month remediation timelines. Fractional laser platforms with existing MDR certificates command procurement preference from EU hospital systems navigating vendor consolidation mandates.
Direct-to-clinic distribution models are displacing traditional medical device distributor networks for consumables and topical formulations. Large dermatology platforms with 50+ locations negotiate manufacturer-direct contracts, capturing 15-20 point margin improvements. This channel compression concentrates procurement leverage in Texas, California, and Florida, where the largest clinic platforms maintain headquarters and central purchasing functions.
Scar Treatment Market Segmentation
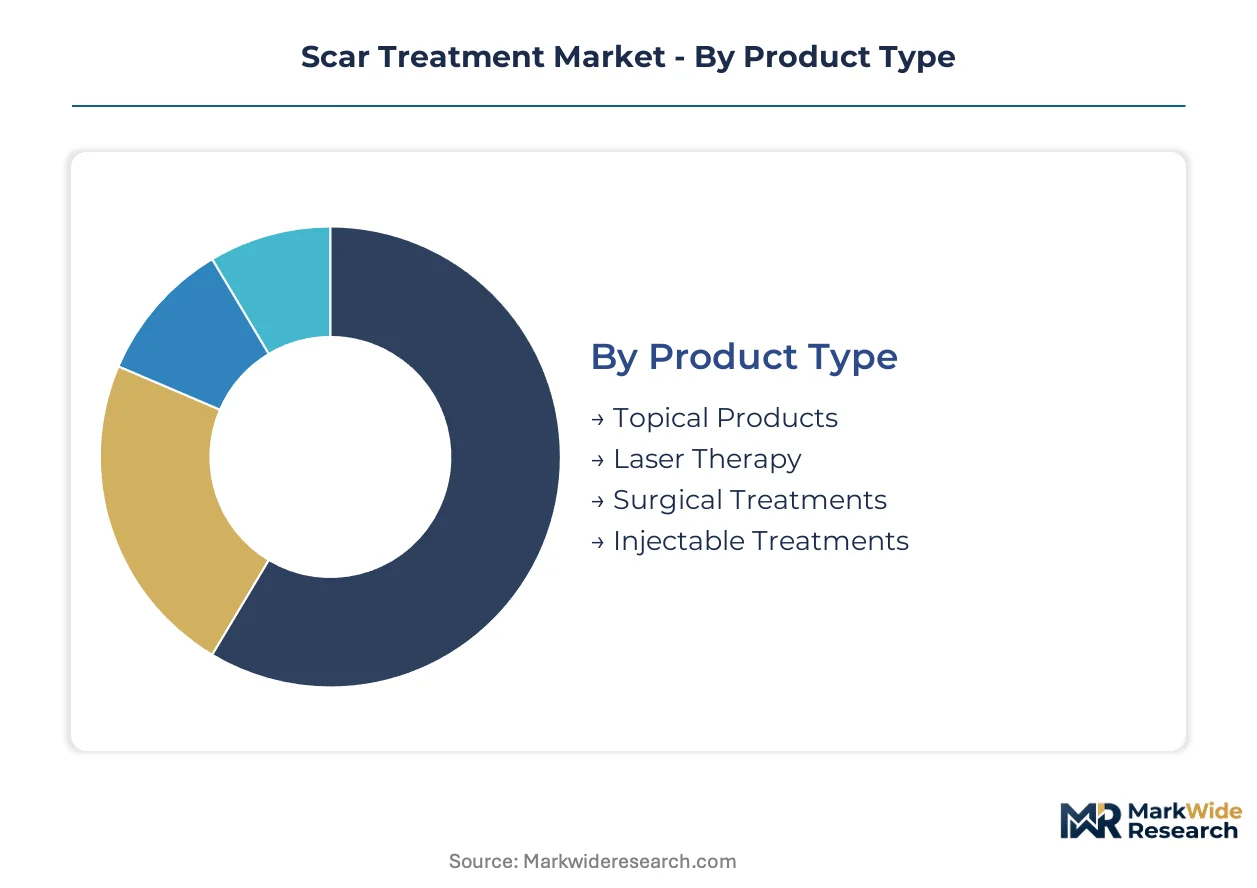
Scar treatment segmentation reveals divergent margin structures across intervention modalities. Product type determines reimbursement eligibility and capital intensity, while end-user concentration shapes distribution economics and device utilization rates.
Product Type:
Silicone-based topicals anchor outpatient protocols, while energy-based systems command per-session premiums in clinic settings.
- Topical Products:Silicone gels and sheeting formulations modulate collagen remodeling through occlusion and hydration. Demand concentrates in post-surgical discharge bundles from ambulatory surgery centers in the United States, where protocol integration creates automatic replenishment cycles.
- Laser Therapy:Fractional CO2 and erbium-doped systems deliver controlled thermal injury to stimulate neocollagenesis. Dermatology clinic chains in Texas and California prioritize fleet deployment here, driven by out-of-pocket payor willingness and per-session pricing power.
- Surgical Treatments:Excision and revision procedures address severe contracture cases.
- Injectable Treatments:Corticosteroids and collagen stimulators serve refractory presentations.
The dominant share belongs to Topical Products, while Laser Therapy is closing the gap fastest.
End User:
Channel concentration tilts procurement leverage toward multi-site operators with centralized purchasing authority.
- Dermatology Clinics:Specialized settings deploy fractional laser fleets and combination protocols. Large platforms in Florida negotiate manufacturer-direct contracts, capturing margin improvements unavailable to independent practices.
- Hospitals:Academic medical centers handle complex contracture and burn reconstruction cases. Demand clusters in urban referral networks serving diverse populations with higher keloid predisposition.
- Homecare Settings:Direct-to-consumer silicone products serve maintenance phases.
- Ambulatory Surgical Centers:Discharge bundle integration drives topical product volume.
Dermatology Clinics capture the steepest expansion trajectory, though Hospitals retain the highest acuity case mix.
Application:
Scar morphology determines intervention selection and treatment cycle duration.
- Acne Scars:Atrophic and boxcar variants respond to fractional resurfacing and radiofrequency microneedling. Demand concentrates among younger demographics in coastal metropolitan areas, where aesthetic concern drives out-of-pocket expenditure.
- Keloid Scars:Excessive collagen deposition beyond wound margins requires multimodal management. Urban dermatology networks serving African and Asian descent populations see elevated procedure density due to genetic predisposition.
- Hypertrophic Scars:Raised but contained collagen overgrowth.
- Atrophic Scars:Depressed tissue loss from collagen degradation.
Acne Scars generate the highest session volume, while Keloid Scars command the premium pricing per treatment cycle.
Technology:
Energy delivery mechanisms differentiate on precision, downtime, and operator skill requirements.
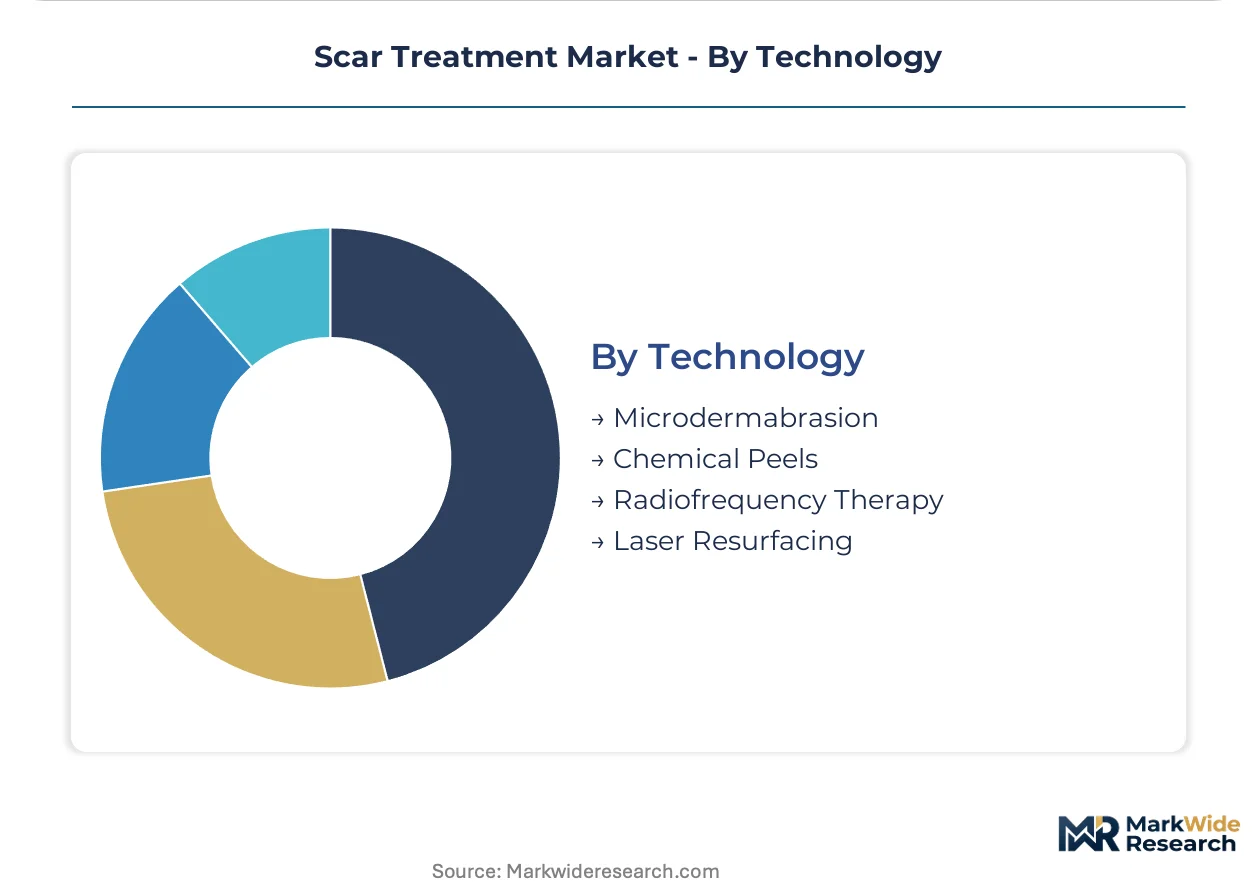
- Laser Resurfacing:Ablative and non-ablative platforms dominate commercial scar revision. FDA 510(k) clearance velocity accelerates fleet refresh cycles for dermatology clinic chains with balance-sheet capacity.
- Radiofrequency Therapy:Microneedling systems with real-time impedance feedback digitize parameter selection. Replacement cycle acceleration occurs among centralized purchasing platforms seeking outcome prediction capabilities.
- Chemical Peels:Acid-based exfoliation for superficial scarring.
- Microdermabrasion:Mechanical resurfacing for mild textural irregularities.
Laser Resurfacing maintains installed base dominance, though Radiofrequency Therapy is gaining share fastest through shorter downtime profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Per-session laser pricing in the United States commands 2.3x premiums over comparable procedures in India, while reimbursement fragmentation in Germany limits aesthetic volume to affluent urban corridors.
United States
FDA 510(k) clearance velocity and ambulatory surgery center protocol integration drive topical product demand. The Centers for Medicare & Medicaid Services denies coverage for aesthetic scar revision, concentrating volume in out-of-pocket coastal metropolitan markets. Dallas and Los Angeles dermatology clinic chains negotiate manufacturer-direct contracts for fractional CO2 fleet deployment.
Germany
MDR implementation reclassifies aesthetic energy devices to Class IIb, triggering notified body involvement and clinical evidence requirements. The BfArM oversees post-market surveillance for combination therapy protocols. Berlin and Munich academic medical centers handle complex contracture reconstruction cases with elevated keloid prevalence among immigrant populations.
China
NMPA streamlined review pathways for laser devices accelerate domestic manufacturer market entry. Provincial procurement platforms in Guangdong and Jiangsu concentrate demand for radiofrequency microneedling systems. Shanghai dermatology networks deploy AI-assisted treatment planning ahead of regulatory guidance finalization.
Japan
PMDA marketing authorization requirements for software-as-a-medical-device applications create compliance timelines for AI-enabled laser platforms. METI subsidizes tele-dermatology infrastructure expansion in rural prefectures. Osaka and Tokyo aesthetic clinic chains prioritize fractional laser fleet refresh cycles on 24-month schedules.
South Korea
MFDS fast-track designation for novel energy-based devices supports domestic manufacturer export competitiveness. Seoul Capital Area clinic density exceeds 400 aesthetic dermatology locations per million population. Busan-Ulsan medical tourism corridors attract regional patients for combination keloid therapy protocols.
Scar Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying medical-grade silicone and laser consumables. Market structure tilts toward consolidated procurement leverage among multi-site dermatology chains with centralized purchasing authority. Three archetypes dominate: diversified aesthetic device manufacturers, pharmaceutical formulators with neuromodulator portfolios, and specialized topical product houses. Competitive moves concentrate on direct-to-clinic distribution bypass and M&A targeting software-enabled treatment planning capabilities.
Within the diversified device tier, Lumenis and Cynosure exemplify platform integrators with installed base dominance across North American dermatology channels. Merz Pharmaceuticals anchors the pharmaceutical archetype through bundled scar-revision offerings. Sonoma Pharmaceuticals occupies a position among specialized topical formulators serving post-surgical discharge bundle integration.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Merz Pharmaceuticals |
| Lumenis |
| Sonoma Pharmaceuticals |
| Cynosure |
| Bausch Health Companies |
| Mölnlycke Health Care |
| CCA Industries |
| Candela Corp |
| Others |
Cost & Logistics Intelligence
Chinese and German chemical manufacturing corridors anchor medical-grade silicone supply, concentrating formulation cost leverage in topical product tiers while fractional laser device margins pool with balance-sheet-strong clinic chains in Texas and California.
Pricing Analysis
Configured-to-order pricing for fractional CO2 systems commands substantial premiums over standard platform configurations, with customization depth around pulse parameters and cooling modules driving differentiation. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center procurement from ambulatory surgery center bundles and direct-to-consumer topical channels. Cost compression in economy-tier silicone sheeting is intensifying because raw material freight volatility from Chinese suppliers feeds through to contract manufacturers. Homecare settings exhibit highest price sensitivity due to out-of-pocket payment structures, while hospital systems demonstrate lowest sensitivity tied to bundled reimbursement protocols.
Supply Chain Analysis
Export-control regimes on erbium-doped fiber laser technology limit flows from US and German component suppliers to Chinese device assemblers, fragmenting sourcing strategies for fractional laser OEMs. Medical-grade silicone concentrates in Chinese and German chemical corridors, while fractional laser chassis assembly clusters in Israel and the United States. Supply chains draw from optical components, precision cooling systems, and biocompatible polymers as critical inputs. Single-source vulnerability around erbium fiber amplifiers creates procurement risk for second-tier device manufacturers. Distribution runs through direct-to-clinic contracts for large dermatology platforms, bypassing traditional medical device distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scar treatment is approaching a platform-economics inflection where AI-assisted treatment planning software interoperability will determine competitive moats, with FDA guidance finalization on software-as-a-medical-device creating ecosystem lock-in opportunities.
For Market Incumbents: Entrench installed base dominance through backward integration into consumable supply, securing captive silicone formulation capacity against raw material volatility. Lumenis and Cynosure should accelerate M&A targeting AI-enabled parameter optimization startups before FDA guidance crystallizes first-mover advantage. Device obsolescence cycles compressing to 24 months in Seoul and Tokyo markets threaten residual value recovery for leased fleets.
For New Entrants and Emerging Players: Rural Japanese prefectures present underpenetrated tele-dermatology infrastructure where METI subsidies lower capital barriers for remote scar assessment platforms. Refractory keloid combination therapy in Busan-Ulsan medical tourism corridors offers service-based entry with lower device procurement requirements. Partner with established dermatology clinic chains for white-label topical formulation distribution rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology clinic platforms in Florida and Texas that have aggregated centralized purchasing leverage but lack software-enabled treatment planning capabilities. Five-to-ten year viability hinges on successful platform integration of AI-assisted laser parameter optimization ahead of regulatory standardization. Monitor FDA 510(k) clearance velocity for software-as-a-medical-device applications as the signal indicating which device manufacturers will command procurement preference.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification for AI-assisted laser platforms compresses time-to-clinic from 18 months to under 6 months. |
| Software Companion Development | Real-time impedance feedback algorithms for radiofrequency microneedling digitize outcome prediction and parameter selection. |
| Hospital System Partnership | Academic medical centers in Berlin and Munich anchor complex contracture reconstruction case volume with elevated keloid prevalence. |
| CE Marking Pathway Navigation | MDR reclassification of aesthetic energy devices to Class IIb triggers 12-18 month remediation timelines for legacy technical files. |
| Reimbursement Strategy Formulation | CMS denial of aesthetic scar revision coverage concentrates volume in out-of-pocket coastal metropolitan markets. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, NMPA streamlined review pathway documentation, and MDR technical file remediation records preceded structured interviews with dermatology clinic procurement directors, biomedical engineers at laser device OEMs, GPO contracts managers, and silicone formulation chemists. Primary intelligence combined with secondary validation against hospital procurement databases, ambulatory surgery center discharge bundle protocols, and customs records for medical-grade silicone trade flows. Bottom-up patient volume estimates and top-down device shipment data underwent cross-triangulation to anchor segmentation splits.
Assumptions held fixed include FDA 510(k) clearance velocity at current levels, MDR implementation timelines in Europe, and Medicare coverage denial for aesthetic procedures across the analysis window. Segmentation dimensions modeled encompass product type, end-user channel concentration, scar morphology application, and energy delivery technology. CAGRs derived from fitted growth curves applied to procedure volume projections and per-session pricing trajectories. Forecast inputs incorporated ambulatory surgery center expansion rates and tele-dermatology platform penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in discretionary healthcare expenditure patterns or freight cost volatility from Chinese silicone suppliers would shift the trajectory. Forecasts reflect assumptions around regulatory pathway stability and reimbursement fragmentation persistence. Material shifts in FDA software-as-a-medical-device guidance or MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Acne Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Dermatology Devices Market
Dermatology
Australia Skin Laser Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Skin Cancer Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Microdermabrasion Market