
 Bone Regeneration Market | 2026-2036
Bone Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Regeneration Market Analysis
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between established manufacturers and emerging entrants. DePuy Synthes leverages its integrated orthopedic portfolio to sustain hospital system contracts across North America and Europe. Zimmer Biomet Holdings anchors its position through specialized extremities and trauma reconstruction platforms that command premium positioning in academic medical centers.
Bone regeneration encompasses the biological repair of skeletal defects through osteoconductive, osteoinductive, and osteogenic mechanisms, typically employing calcium phosphate ceramics, collagen matrices, or recombinant human bone morphogenetic protein-2 at concentrations between 1.5 mg/mL and 12 mg/mL depending on defect volume. Scaffolds and bone grafts dominate current revenue as mature categories with established reimbursement, while stem cell therapy represents the fastest-expanding segment driven by autologous approaches that reduce immunogenic rejection risk. Delivery mode selection increasingly favors injectable formulations in outpatient orthopedic clinics, shifting procedural economics away from implantable constructs that require operating room allocation.
FDA 510(k) and premarket approval pathways govern United States market access, with the agency's evolving stance on cell-based products creating compliance complexity for manufacturers pursuing regenerative medicine claims. The European Medicines Agency's Advanced Therapy Medicinal Products framework imposes centralized manufacturing and traceability standards that raise barriers for smaller developers without GMP-certified facilities. Stakeholders must monitor regulatory convergence between device and biologic classifications, as reclassification decisions will reshape competitive moats and partnership strategies for platform technologies spanning multiple jurisdictions.
Market Dynamics
The shift toward outpatient orthopedic procedures is restructuring demand patterns for bone regeneration technologies, with injectable delivery systems capturing procedural volume previously reserved for implantable constructs requiring operating room allocation.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Centralized manufacturing standards for cell-based therapies are accelerating platform standardization across European markets, reducing batch-to-batch variability concerns that previously limited clinical adoption.
- Autologous stem cell approaches:Patient-derived biological materials are eliminating immunogenic rejection protocols, shortening recovery timelines and expanding treatable patient populations beyond allograft-compatible candidates.
- Calcium phosphate ceramic innovation:Synthetic scaffold materials with tunable degradation rates are displacing structural autografts in spinal fusion and craniomaxillofacial applications.
Market Restraints
- Recombinant protein production costs:rhBMP-2 manufacturing requires mammalian cell culture infrastructure with multi-million dollar bioreactor investments, compressing margins for developers without captive biologics capacity.
- GMP facility concentration:Contract manufacturing organizations with cell therapy expertise cluster in Switzerland and Germany, creating geographic supply vulnerability for developers in peripheral markets.
- FDA biologic-device classification ambiguity:Evolving guidance on combination products creates regulatory friction, with some scaffold-plus-cell constructs facing dual jurisdiction review timelines exceeding thirty-six months.
Strategic Opportunities
- India's CDSCO streamlined pathway:The regulator's priority review designation for regenerative medicine products is opening access to a surgical volume market with accelerating orthopedic infrastructure investment.
- 3D bioprinting convergence:Integration of patient-specific imaging with extrusion-based deposition systems is enabling custom scaffold geometries matched to defect morphology.
- Ambulatory surgery center channel expansion:Medicare reimbursement shifts toward site-neutral payment are redirecting bone graft procedures to outpatient settings with lower overhead structures.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies for medical device quality management face eighteen-month backlogs, delaying market entry for emerging scaffold manufacturers.
- Cell therapy supply chain cold chain integrity:Autologous products require temperature-controlled logistics with chain-of-custody documentation, complicating distribution to secondary and tertiary care centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Regeneration Market |
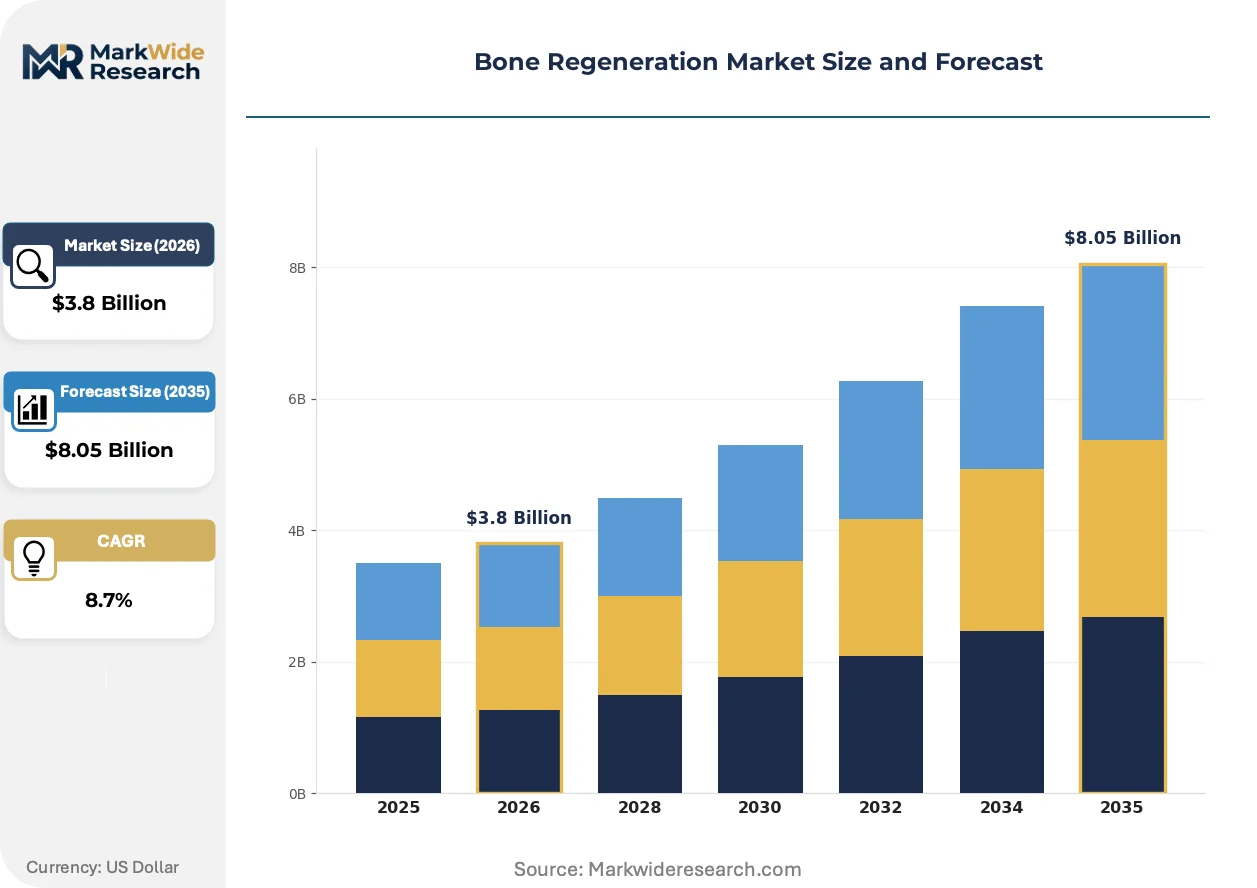
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Bone Grafts, Growth Factors, Stem Cells End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Research Laboratories Technology: 3D Bioprinting, Tissue Engineering, Stem Cell Therapy, Gene Therapy Delivery Mode: Injectable, Implantable, Topical, Transdermal |
| Companies Covered | DePuy Synthes, Bioventus, Zimmer Biomet Holdings, Geistlich Pharma, BONESUPPORT, Stryker Corporation, Orthofix Medical, Septodont, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Regeneration Market Emerging Trajectories
Biological scaffold engineering is converging with digital surgical planning, creating patient-matched constructs that alter procurement economics and clinical workflow integration requirements.
Injectable hydrogel carriers loaded with demineralized bone matrix are fragmenting the traditional split between putty and structural graft categories. Outpatient orthopedic clinics in the United States are adopting these formulations for extremity defect repair, collapsing the distinction between operating room and clinic-based reimbursement tiers.
Japan's PMDA has issued conditional approval pathways for regenerative medicine products, compressing premarket review timelines for autologous cell therapies with demonstrated safety profiles. Domestic manufacturers are leveraging this regulatory velocity to establish clinical data packages exportable to Asian markets with mutual recognition agreements.
Hospital procurement committees are consolidating vendor contracts around integrated orthopedic portfolios, displacing standalone bone graft suppliers from formulary access. Academic medical centers in Germany and the United States are leading this concentration, bundling scaffold procurement with trauma and extremities platform agreements that lock out niche competitors.
Bone Regeneration Market Segmentation
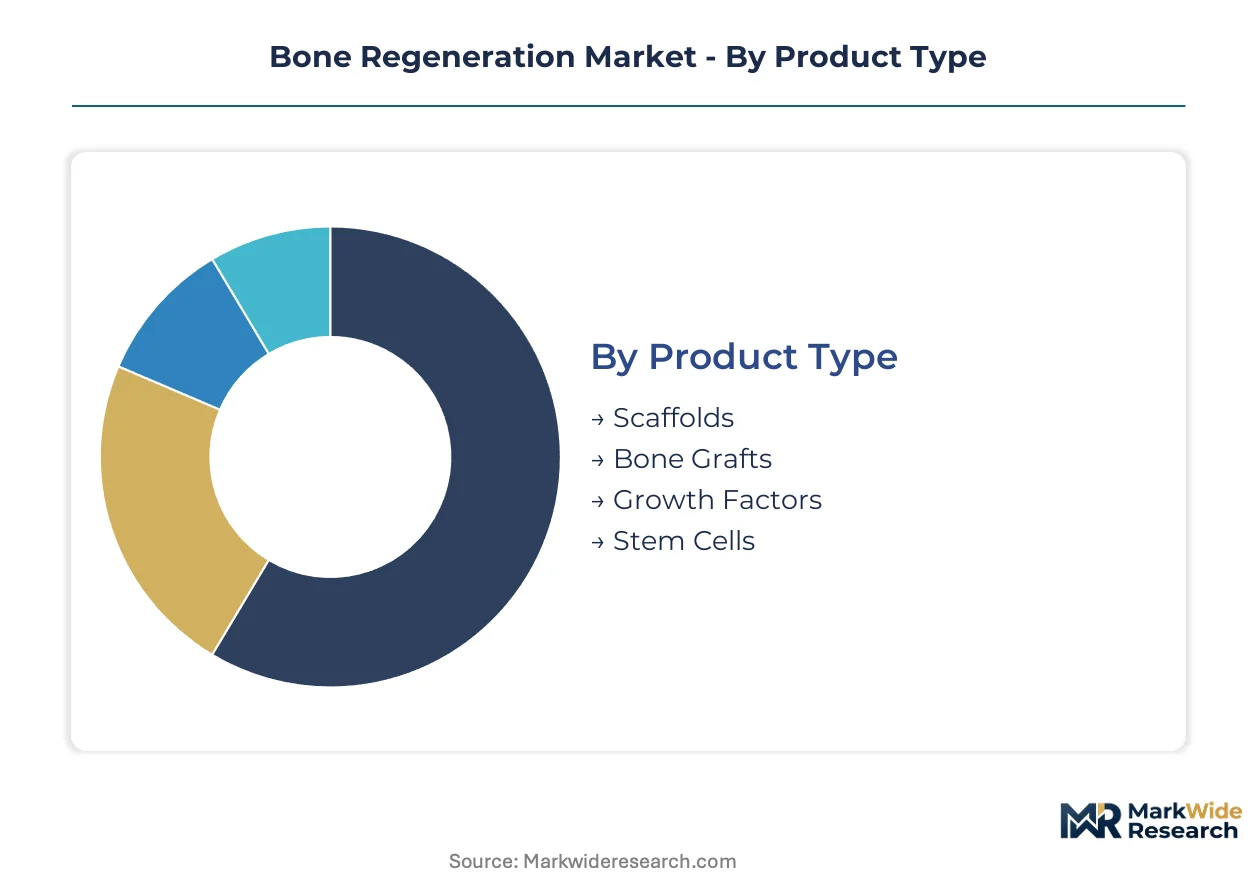
Bone regeneration technologies fragment across multiple technical and commercial dimensions, each with distinct regulatory pathways and reimbursement profiles. Understanding these divisions reveals where capital is concentrating and which platforms face commoditization pressure.
Product Type:
Scaffolds and bone grafts anchor domestic procurement in Germany and the United States, while stem cell platforms increasingly serve export markets through centralized European manufacturing.
- Scaffolds:Synthetic calcium phosphate and collagen-based matrices provide osteoconductive frameworks with tunable degradation rates matched to defect healing timelines. German orthopedic clinics favor these for spinal fusion procedures, driven by Geistlich Pharma's surgeon training networks and established hospital formulary contracts.
- Bone Grafts:Allograft and xenograft materials remain the volume leader in North American hospital procurement, though synthetic alternatives are displacing structural autografts in craniomaxillofacial applications. The segment benefits from mature CPT reimbursement codes that simplify revenue cycle management.
- Growth Factors:Recombinant human bone morphogenetic protein-2 at concentrations between 1.5 mg/mL and 12 mg/mL stimulates osteoinduction in large-volume defects.
- Stem Cells:Autologous approaches eliminate immunogenic rejection protocols and shorten recovery timelines, with the steepest expansion trajectory across all product categories.
Scaffolds command the established base. The steepest expansion runs through stem cells.
End User:
Cost tier stratification separates premium academic medical centers from high-volume orthopedic clinics, with reimbursement differentials driving technology selection.
- Hospitals:Integrated health systems bundle bone regeneration procurement with trauma and extremities platform agreements, locking out standalone suppliers. These institutions maintain captive bioreactor capacity for cell therapy processing and command premium positioning for complex reconstructive procedures.
- Orthopedic Clinics:Outpatient facilities are adopting injectable formulations for extremity defect repair, collapsing the distinction between operating room and clinic-based reimbursement tiers. Medicare's site-neutral payment shifts are accelerating this channel's volume capture.
- Rehabilitation Centers:Post-surgical recovery facilities coordinate with primary surgical sites for graft monitoring and complication management.
- Research Laboratories:Academic and commercial R&D operations drive preclinical validation for novel scaffold materials and cell processing protocols.
Hospitals retain the revenue concentration. Orthopedic clinics are climbing the fastest as procedural economics shift toward outpatient settings.
Technology:
Manufacturing maturity separates tissue engineering platforms with decades of clinical data from emerging modalities still navigating regulatory classification.
- 3D Bioprinting:Extrusion-based deposition systems integrate patient-specific imaging to enable custom scaffold geometries matched to defect morphology. The technology clusters in German and Swiss research institutions with strong industrial partnerships.
- Tissue Engineering:Decellularized matrices and bioreactor-cultured constructs represent the most commercially mature category, with established FDA 510(k) clearance pathways and European MDR technical documentation requirements.
- Stem Cell Therapy:Autologous processing platforms require GMP-certified facilities concentrated in Switzerland and Germany, creating geographic supply vulnerability for peripheral markets.
- Gene Therapy:Viral vector delivery of osteogenic factors remains in early clinical development, with regulatory frameworks still evolving for skeletal applications.
Tissue engineering holds the installed base. 3D bioprinting shows the steepest technology trajectory as digital surgical planning converges with biological scaffold fabrication.
Delivery Mode:
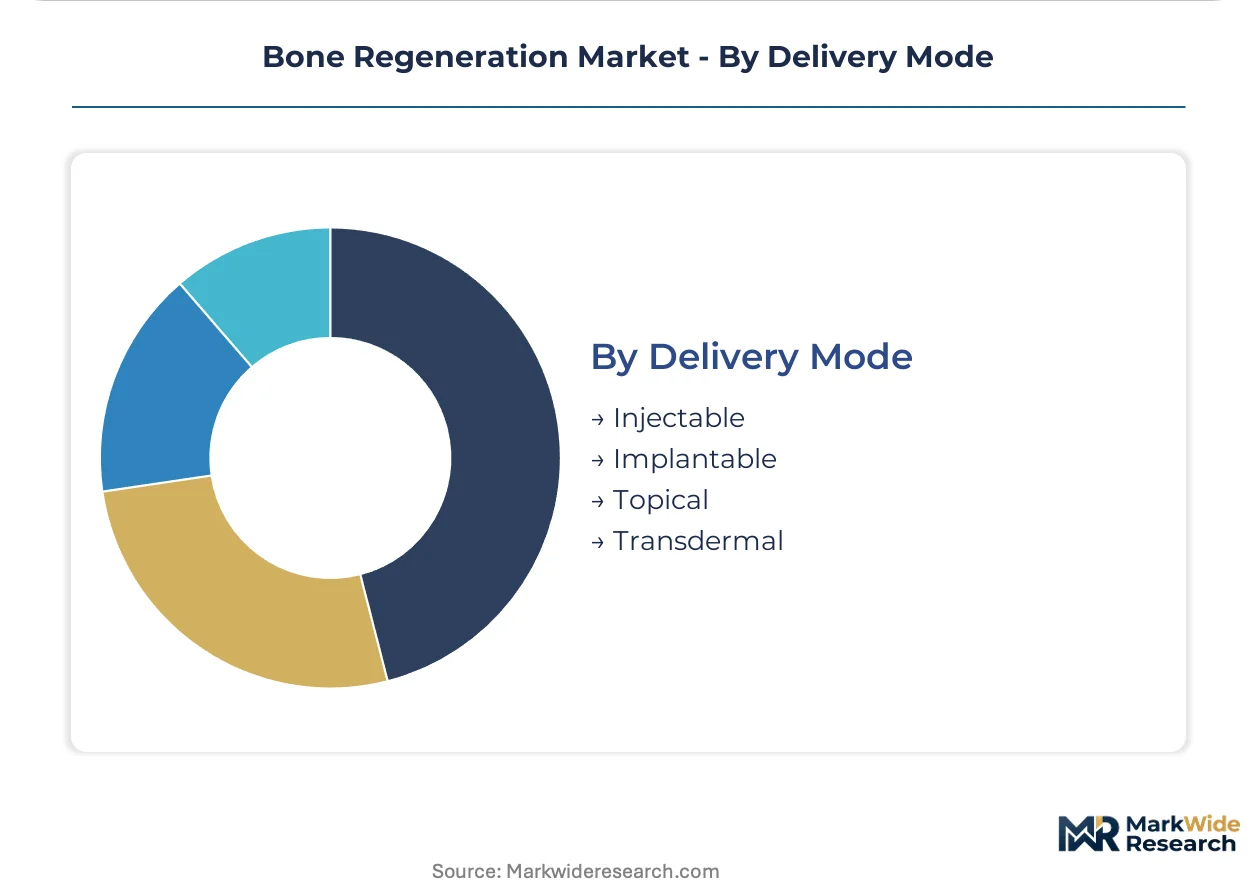
Application setting determines delivery selection, with minimally invasive preferences reshaping procurement away from open surgical constructs.
- Injectable:Hydrogel carriers loaded with demineralized bone matrix fragment traditional putty and structural graft categories. United States orthopedic clinics are adopting these formulations for extremity defect repair in ambulatory settings.
- Implantable:Structural constructs requiring operating room allocation face volume pressure as reimbursement shifts favor outpatient alternatives.
- Topical:Surface applications serve superficial bone defects and adjunctive procedures with simpler regulatory pathways.
- Transdermal:Percutaneous delivery systems remain experimental for bone regeneration, with limited clinical validation compared to other modes.
Implantable modes retain the procedural volume base. Injectable delivery is expanding most quickly as site-neutral payment redirects bone graft procedures to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basel-Mulhouse-Freiburg tri-national pharmaceutical corridor anchors European bone regeneration manufacturing capacity, with GMP-certified facilities clustered within 50 kilometers of this logistics node.
United States
FDA's 510(k) clearance pathway accelerates combination product entry for scaffold-plus-cell constructs. Medicare's site-neutral payment reforms redirect bone graft volume toward ambulatory surgery centers in Florida and Texas. The Greater Boston biotech corridor hosts contract manufacturing organizations specializing in mammalian cell culture for rhBMP-2 production.
Germany
Geistlich Pharma and Stryker Corporation maintain surgeon training networks that lock in hospital formulary contracts across Baden-Württemberg and Bavaria. The EMA's Advanced Therapy Medicinal Products framework imposes centralized manufacturing standards that favor established GMP-certified facilities in Basel-proximate zones. The Rhine-Neckar medical technology cluster concentrates 3D bioprinting research partnerships between academic medical centers and industrial fabricators.
Switzerland
Swissmedic's alignment with EMA centralized procedures reduces regulatory friction for cell therapy developers seeking multi-country market access. Contract manufacturing organizations with autologous processing expertise cluster in Zurich and Basel, creating geographic supply bottlenecks for peripheral European markets. The country's pharmaceutical logistics infrastructure maintains cold chain integrity standards that exceed baseline EU requirements.
Japan
PMDA's conditional approval pathway compresses premarket review timelines for autologous cell therapies with demonstrated safety profiles. The Kansai region's regenerative medicine industrial zone attracts domestic manufacturers building clinical data packages for Asian mutual recognition agreements. METI's strategic prioritization of cell therapy manufacturing has concentrated bioreactor capacity in Osaka and Kobe.
India
CDSCO's priority review designation for regenerative medicine products opens access to surgical volume markets with accelerating orthopedic infrastructure investment in Maharashtra and Karnataka. Domestic hospital chains in Delhi-NCR and Mumbai are expanding captive biologics processing capabilities to reduce import dependency for bone graft substitutes. The country's central drug regulator has streamlined import licensing for scaffold materials while maintaining stringent GMP verification for cell-based products.
Bone Regeneration Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage, creating a bifurcated structure where ISO 13485-certified incumbents defend hospital system contracts against emerging entrants facing eighteen-month auditor backlogs. The vendor base stratifies into three archetypes: integrated orthopedic portfolios with captive biologics capacity, standalone scaffold specialists dependent on contract manufacturing, and cell therapy platform developers concentrated in Swiss-German manufacturing zones. Dominant competitive moves include backward integration into GMP-certified bioreactor capacity and geographic expansion through distributor partnerships in India's surgical volume markets.
Within the integrated orthopedic tier, DePuy Synthes and Zimmer Biomet Holdings exemplify portfolio breadth strategies that bundle bone regeneration procurement with trauma and extremities platform agreements. Among European-based specialists, Geistlich Pharma occupies a position anchored by surgeon training networks and established formulary access in German-speaking markets. These three entities represent distinct competitive archetypes: the diversified device-biologic hybrid, the premium-positioned academic medical center supplier, and the regional training-network incumbent.
| Leading Market Players |
|---|
| DePuy Synthes |
| Bioventus |
| Zimmer Biomet Holdings |
| Geistlich Pharma |
| BONESUPPORT |
| Stryker Corporation |
| Orthofix Medical |
| Septodont |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Multi-million dollar bioreactor investments in mammalian cell culture infrastructure create scale thresholds that compress margins for developers without captive biologics capacity while anchoring price floors for rhBMP-2 formulations. This concentration of production assets in the Greater Boston corridor and Swiss-German zones shapes both supply availability and tiered procurement economics across hospital systems and orthopedic clinics.
Pricing Analysis
Volume-discount tiering structures dominate hospital system procurement, with integrated orthopedic portfolios commanding premium positioning through bundled trauma and extremities platform agreements. Price differentiation separates ISO 13485-certified manufacturers with established GMP facilities from emerging entrants facing eighteen-month auditor backlogs. Cost compression in synthetic scaffold categories is intensifying as calcium phosphate ceramics displace structural autografts. Academic medical centers exhibit the lowest price sensitivity due to captive bioreactor capacity and complex reconstructive procedure margins, while ambulatory surgery centers prioritize site-neutral reimbursement optimization.
Supply Chain Analysis
Inventory lead times for autologous cell therapies extend beyond standard orthopedic implant procurement due to chain-of-custody documentation and temperature-controlled logistics requirements. Manufacturing concentrates in Switzerland, Germany, and the United States, with GMP-certified facilities clustering in the Basel-Mulhouse-Freiburg corridor and Greater Boston. Raw material dependencies include demineralized bone matrix, collagen matrices, and recombinant protein feedstocks. Single-source vulnerability runs through contract manufacturing organizations with cell therapy expertise. Distribution runs through hospital procurement committees consolidating vendor contracts around integrated portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgeon training network subscriptions and bioreactor processing service contracts are expanding faster than scaffold hardware sales, creating durable recurring-revenue layers that alter capital deployment priorities across the competitive landscape.
For Market Incumbents: Secure backward integration into GMP-certified bioreactor capacity to defend margin position against standalone scaffold specialists dependent on contract manufacturing. Lock in hospital system contracts through bundled procurement agreements that combine bone regeneration technologies with trauma and extremities platforms, displacing niche competitors from formulary access. For New Entrants and Emerging Players: CDSCO's priority review designation for regenerative medicine products offers the fastest regulatory pathway into India's surgical volume markets with accelerating orthopedic infrastructure investment. Target ambulatory surgery centers adopting injectable hydrogel formulations for extremity defect repair, where site-neutral payment shifts have collapsed traditional reimbursement tier distinctions and opened procurement access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cell therapy platform developers with autologous processing capabilities and established surgeon training networks, offering superior cash flow predictability across the analysis window. Acquisition targets should demonstrate GMP-certified manufacturing assets in Basel-proximate zones or captive bioreactor capacity in the Greater Boston corridor. The signal to watch is FDA reclassification decisions on scaffold-plus-cell combination products, which will reshape competitive moats and partnership strategies.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | ISO 13485 and GMP facility accreditation bifurcates competitive access between established manufacturers and emerging entrants. |
| Surgeon Training Network Expansion | Geistlich Pharma's Baden-Württemberg and Bavaria programs demonstrate how clinical education locks in hospital formulary contracts. |
| Injectable Formulation Development | Hydrogel carriers loaded with demineralized bone matrix capture outpatient orthopedic clinic volume shifting from operating room settings. |
| 3D Bioprinting Partnership | Rhine-Neckar cluster collaborations between academic medical centers and industrial fabricators enable patient-specific scaffold geometries. |
| Site-Neutral Reimbursement Strategy | Medicare payment reform redirects bone graft procedures to ambulatory surgery centers with lower overhead structures. |
Methodological Framework
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at scaffold and cell therapy manufacturers, then refined through secondary validation against FDA 510(k) filings, EMA Advanced Therapy Medicinal Products submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up volume estimates from product-level adoption curves were triangulated with top-down market sizing from expenditure flow analysis.
Variance decomposition across product type, delivery mode, end-user facility tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating procedural volume shifts, reimbursement policy evolution, and technology substitution rates. Industry-specific forecast inputs included orthopedic clinic expansion timelines and GMP facility capacity utilization trends.
Underlying assumptions cover regulatory pathway stability, reimbursement tier persistence, and supply chain cold chain integrity, with deviation risk concentrated in FDA biologic-device classification decisions and EMA MDR implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market