
 Floating Power Plant Market | 2026-2036
Floating Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Power Plant Market Intelligence
The EU Green Deal is restructuring marine energy infrastructure requirements across European waters, forcing operators to retire older coastal barges and adopt cleaner floating configurations. Wärtsilä Corporation leverages its dual-fuel engine portfolio to dominate the gas turbine segment for offshore applications. Siemens AG anchors its position through integrated power island designs that combine generation with grid stabilization hardware. Karadeniz Holding competes via its Power Ship fleet deployments across African and Asian coastal markets.
A floating power plant is a self-contained electricity generation facility mounted on a barge, vessel, or semi-submersible platform, typically rated between 50 MW and 500 MW and designed for rapid deployment without land-based civil works. These units serve remote industrial sites, island grids, and emergency response scenarios where conventional grid extension proves uneconomical or technically infeasible. Combined cycle configurations command the premium tier due to superior thermal efficiency and lower fuel consumption per megawatt-hour. Floating solar technology represents the fastest-expanding segment as modular photovoltaic arrays integrate with existing offshore infrastructure. Island electrification applications sustain steady demand from archipelago nations seeking to replace diesel-dependent mini-grids.
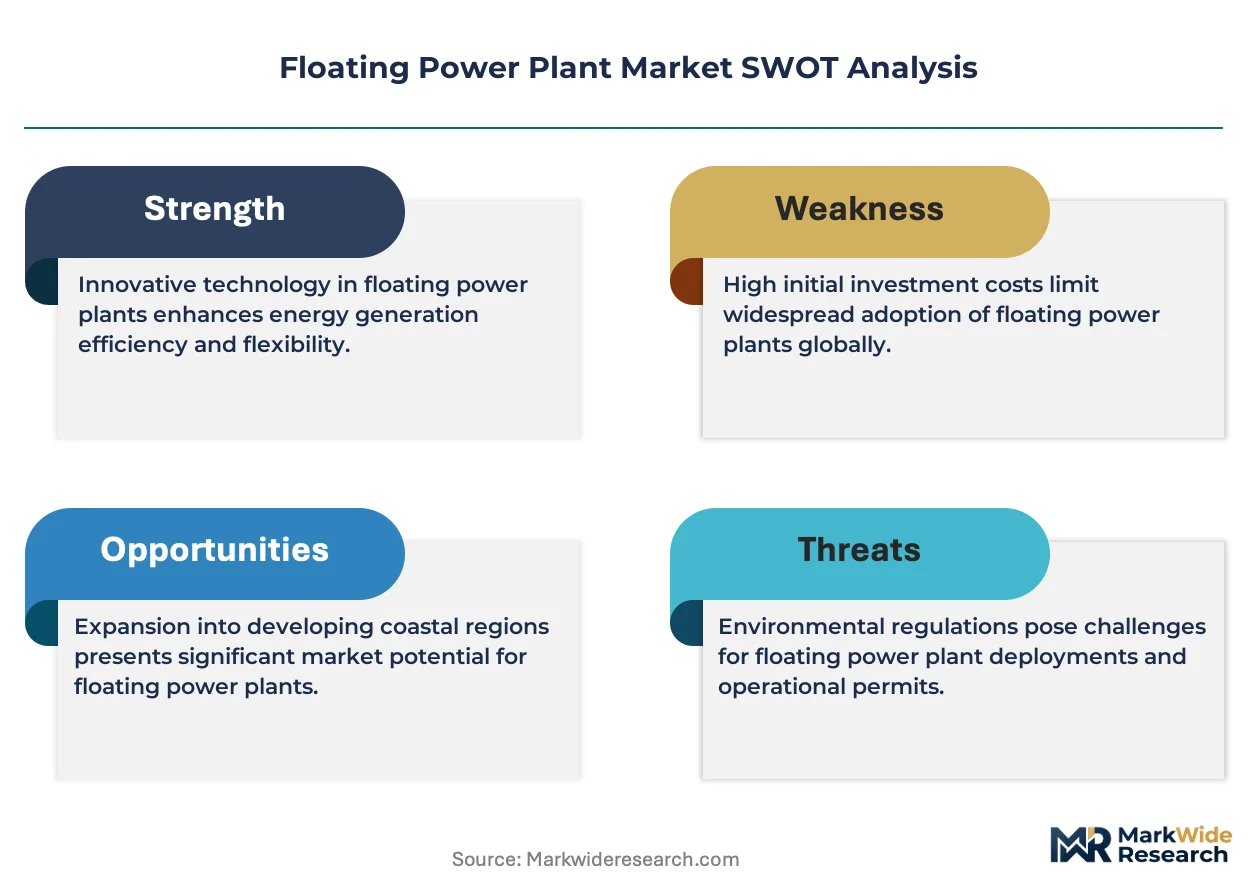
The International Maritime Organization's carbon intensity regulations and the EU F-Gas Directive are tightening emissions standards for marine-based generation equipment, compelling manufacturers to certify engines against stricter NOx and methane leakage thresholds. The US EPA and Japan's METI have introduced parallel frameworks for floating power systems operating in territorial waters, creating a fragmented but demanding compliance landscape. Stakeholders must monitor how evolving marine carbon accounting rules reshape equipment specifications and deployment timelines across jurisdictions.
Market Dynamics
Offshore electrification mandates are compressing deployment timelines for floating generation assets, forcing operators to abandon fixed-platform infrastructure in favor of mobile, low-carbon alternatives that can relocate with drilling campaigns.
Growth Catalysts
- EU F-Gas Directive:Marine emissions standards under this framework are compelling fleet operators to retire diesel-heavy barges and contract dual-fuel floating units for coastal power delivery.
- Pre-salt field development:Brazil's deepwater petroleum extraction requires mobile power solutions that conventional grid extension cannot economically serve.
- Floating solar integration:Modular photovoltaic arrays are attaching to existing offshore oil infrastructure, creating hybrid generation configurations that reduce fuel consumption.
Market Restraints
- Specialized hull fabrication:Construction of semi-submersible platforms concentrates among South Korean and Singaporean shipyards, creating bottle-necked capacity for new orders.
- Liquefied natural gas price volatility:Fuel cost swings for gas turbine configurations compress operator margins and deter long-term charter commitments.
- Grid connection standards:Jurisdictional variation in subsea cable specifications forces redundant engineering reviews and extends commissioning schedules.
Strategic Opportunities
- Indonesian archipelago electrification:Island provinces outside Java-Bali grid coverage present unserved demand for barge-mounted generation replacing diesel mini-grids.
- Power-as-a-service contracts:Charter models transferring operational risk from utilities to vessel owners are penetrating African coastal markets.
- Green hydrogen co-location:Electrolyzer integration with offshore wind-to-power platforms creates synthetic fuel export hubs in North Sea waters.
Industry Challenges
- Marine electrical certification:Dual-class society approvals from Bureau Veritas and DNV require parallel documentation streams that extend delivery timelines.
- Subsea cable installation:Specialized vessel availability for export cable lay operations constrains project execution windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Power Plant Market |
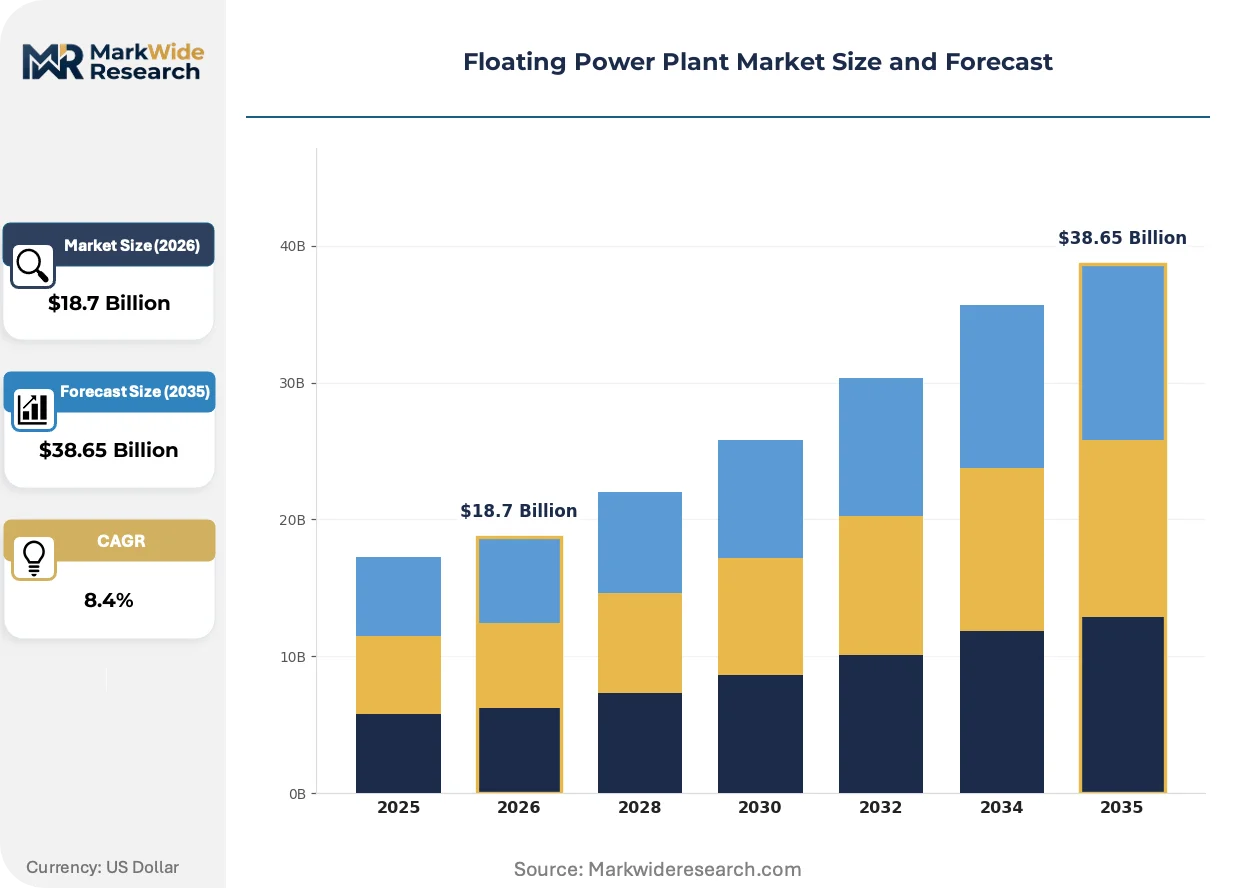
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Combined Cycle, Gas Turbine, Steam Turbine, Reciprocating Engine Technology: Floating Solar, Hydrokinetic, Offshore Wind, Tidal Stream Application: Remote Power Supply, Island Electrification, Disaster Relief, Maritime Operations End User: Energy Producers, Naval Organizations, Mining Firms, Offshore Drilling Companies |
| Companies Covered | MAN Energy Solutions SE, Kawasaki Heavy Industries, Ltd., Wärtsilä Corporation, Doosan Heavy Industries & Construction Co., Ltd., Shanghai Electric Group Co., Ltd., Siemens AG, Mitsubishi Heavy Industries, Ltd., Karadeniz Holding, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Power Plant Market Strategic Shifts & Innovations
Equipment manufacturers are converging generation hardware with grid stabilization systems, blurring traditional boundaries between power production and transmission infrastructure. This integration is compressing supplier lists and raising technical barriers for component specialists.
Hybrid power islands combining gas turbines with battery energy storage systems are unifying dispatchable and intermittent generation profiles within single floating platforms. Offshore drilling contractors in the North Sea and Gulf of Mexico are specifying these configurations for variable load-following capability. The technology is unifying procurement decisions that previously separated prime mover and storage contracts into integrated vessel charters.
Japan's METI has introduced territorial water emissions frameworks that parallel IMO carbon intensity regulations, creating overlapping compliance obligations for equipment deployed in Japanese exclusive economic zones. Dual-certification requirements are raising engineering costs for manufacturers serving multiple jurisdictions. Gas turbine suppliers are responding with modular after-treatment systems that can be reconfigured for regional NOx and methane leakage thresholds.
Charter contract structures are migrating from fixed-term leases to availability-based agreements where vessel owners assume fuel price and maintenance risk. Indonesian state utility PLN and West African distribution companies are piloting these models for island grid supply. The shift is most visible in markets where currency volatility and credit risk deter traditional capital expenditure approaches.
Floating Power Plant Market Segmentation
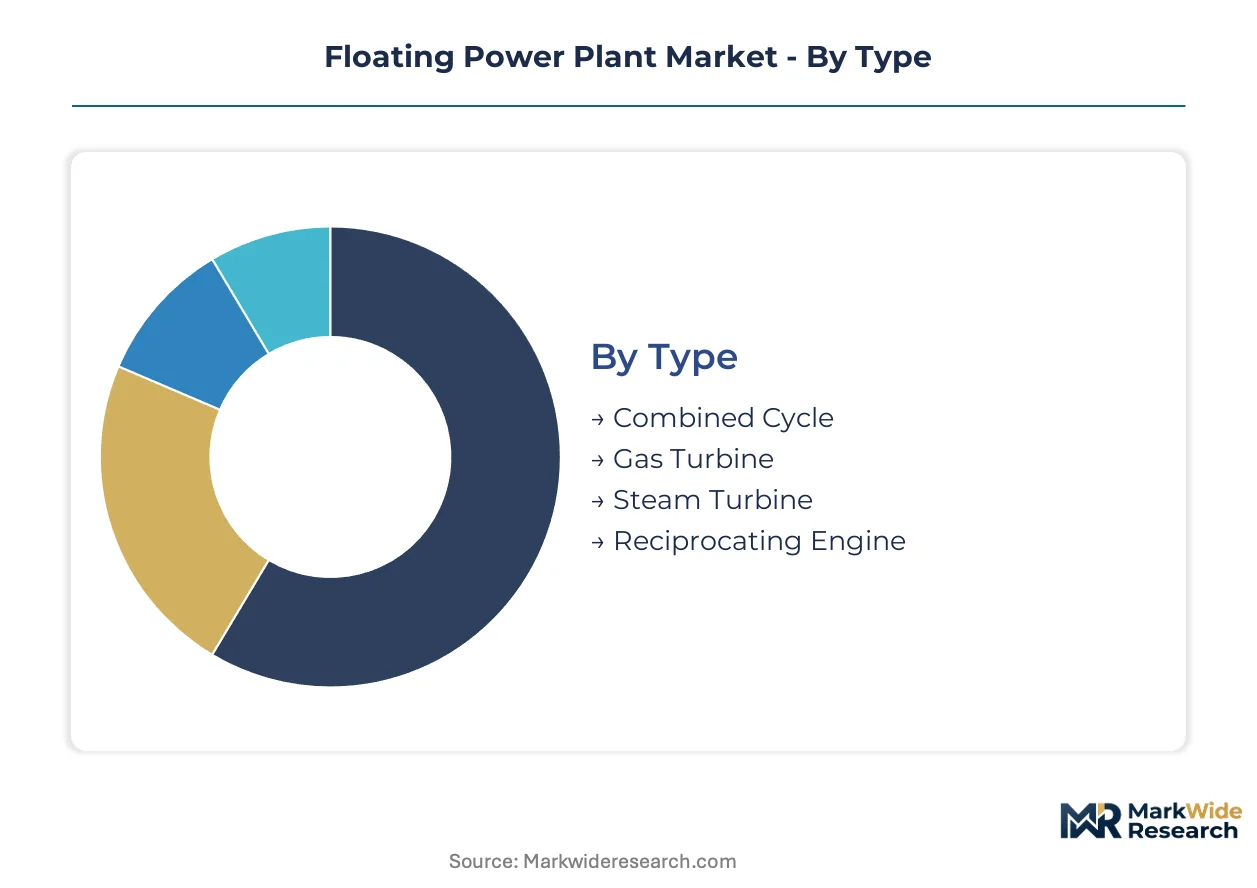
Floating power plant configurations vary sharply in capital intensity and fuel flexibility, creating distinct procurement patterns across utility and industrial buyers. Equipment selection hinges on deployment duration, fuel access, and grid connection requirements rather than uniform technical specifications.
Type:
Volume deployment clusters around mature thermal configurations with proven marine certification, while premium contracts flow toward integrated systems with dual-fuel flexibility.
- Combined Cycle:Heat recovery steam generators capture exhaust energy from gas turbines, pushing thermal efficiency above 55% for barge-mounted installations. Brazilian pre-salt operators specify these units for multi-year platform electrification where fuel logistics justify capital-intensive configurations.
- Gas Turbine:Aeroderivative and industrial turbine packages dominate rapid-deployment charters due to modular installation and lower upfront capital. West African coastal utilities favor these units for 50-150 MW island grid supply where commissioning speed outweighs efficiency premiums.
- Steam Turbine:Heavy fuel oil and coal-fired boilers persist in legacy barge fleets serving Southeast Asian industrial zones with captive fuel supply chains.
- Reciprocating Engine:Medium-speed diesel and dual-fuel engines occupy the 10-50 MW niche for emergency response and seasonal peak shaving applications.
Mature deployment sits with Gas Turbine configurations. Newer deployment is concentrated in Combined Cycle systems as fuel price volatility rewards efficiency investments.
Technology:
Technology selection tracks the tension between dispatchable baseload and variable renewable output, with hybrid architectures gaining traction in North Sea and Mediterranean waters.
- Floating Solar:Modular photovoltaic arrays integrate with existing offshore oil infrastructure, reducing fuel consumption for platform electrification. Tethered systems in Indonesian and Vietnamese waters exploit calm tropical seas with minimal wave loading.
- Offshore Wind:Floating substations and power conversion platforms anchor grid connection for remote wind farms, particularly in Japanese and South Korean waters where seabed depth excludes fixed foundations.
- Hydrokinetic:Tidal and river-current turbines remain pre-commercial for marine power applications, constrained by biofouling and debris entanglement in coastal deployments.
- Tidal Stream:Horizontal-axis turbines in high-velocity channels supply predictable output for island mini-grids in Orkney and Brittany pilot zones.
Offshore Wind commands the steepest expansion trajectory as floating foundation costs decline. Hydrokinetic systems remain confined to demonstration budgets without commercial scale.
Application:
Application demand splits between permanent infrastructure replacement and temporary mobile solutions, with contract duration and risk allocation driving technology selection.
- Maritime Operations:Offshore drilling contractors in Brazil, Norway, and the Gulf of Mexico charter floating generation for platform electrification, abandoning fixed infrastructure that cannot relocate with drilling campaigns. EU Green Deal emissions standards accelerate diesel-to-gas conversions in these fleets.
- Island Electrification:Archipelago nations in Indonesia, the Philippines, and the Caribbean replace diesel mini-grids with barge-mounted LNG and dual-fuel systems. PLN and similar state utilities pilot availability-based contracts transferring fuel price risk to vessel owners.
- Remote Power Supply:Mining and industrial sites in remote coastal zones contract short-term generation during grid extension delays or infrastructure failures.
- Disaster Relief:Emergency response agencies deploy rapidly mobilized reciprocating engine barges following typhoon or earthquake damage to onshore generation assets.
Maritime Operations absorb the largest share of newbuild investment. Disaster Relief relies on refurbished legacy assets with minimal customization.
End User:
End user procurement sophistication varies from integrated energy majors with captive technical teams to government agencies with constrained contracting capacity.
- Offshore Drilling Companies:Petrobras, Equinor, and independent drillers specify hybrid power islands combining gas turbines with battery storage for variable load-following. These buyers unify prime mover and storage procurement into single vessel charters.
- Energy Producers:State utilities and independent power developers charter floating assets for grid supplementation, particularly in markets where land acquisition or permitting delays block conventional construction.
- Naval Organizations:Coast guards and naval logistics commands deploy mobile generation for expeditionary base support and humanitarian assistance operations.
- Mining Firms:Remote coastal extraction sites in West Africa and Latin America contract short-term power during infrastructure development phases.
Offshore Drilling Companies drive specification innovation through integrated technical requirements. Mining Firms remain price-sensitive spot market participants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong shipyard cluster concentrates specialized hull fabrication for semi-submersible power platforms serving Southeast Asian and Middle Eastern charter markets.
Brazil
Petrobras-led pre-salt field development drives demand for mobile generation assets that conventional grid extension cannot economically reach. ANVISA and environmental licensing frameworks govern offshore equipment certification. The Campos Basin hosts active deployment of combined cycle barges for deepwater platform electrification.
Norway
Equinor and independent drillers specify hybrid power islands combining gas turbines with battery storage for North Sea variable load-following. The EU Green Deal and domestic carbon intensity regulations accelerate diesel-to-gas conversions in offshore fleets. Stavanger anchors engineering specification and vessel charter contracting for North Sea operations.
Indonesia
Island provinces outside Java-Bali grid coverage present unserved demand for barge-mounted generation replacing diesel mini-grids. PLN pilots availability-based contracts transferring fuel price risk to vessel owners. The Riau Islands and Sulawesi clusters concentrate floating solar integration with existing maritime infrastructure.
Japan
METI territorial water emissions frameworks parallel IMO carbon intensity regulations for equipment deployed in exclusive economic zones. Dual-certification requirements raise engineering costs for manufacturers serving Japanese waters. The Nagoya-Chubu industrial corridor hosts gas turbine after-treatment system reconfiguration for regional NOx thresholds.
South Korea
DSME and Hyundai Heavy Industries dominate semi-submersible platform construction for floating power applications. Domestic shipyard capacity constraints create bottlenecks for new floating generation orders. The Ulsan-Busan shipbuilding cluster concentrates hull fabrication and integrated power island assembly for export markets.
Floating Power Plant Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive marine engineering capabilities. Equipment fabrication and vessel integration demand capital-intensive shipyard access that filters out pure-play generation specialists. Three archetypes dominate: European-Swiss engineering houses with dual-fuel engine portfolios, Japanese-Korean heavy industrial groups with integrated shipbuilding-power generation divisions, and Turkish-African charter operators with power ship fleet deployment models. Competitive moves center on strategic partnerships between turbine suppliers and shipyards, plus geographic expansion of power-as-a-service contracting into island electrification markets.
Among European-Swiss engineering specialists, Wärtsilä Corporation and Siemens AG exemplify the integrated power island archetype combining generation hardware with grid stabilization systems. MAN Energy Solutions SE represents the dual-fuel engine configuration tier serving offshore drilling electrification requirements. Mitsubishi Heavy Industries, Ltd. and Kawasaki Heavy Industries, Ltd. occupy positions within the Japanese heavy industrial group structure that unifies shipbuilding, power generation, and marine equipment manufacturing. Karadeniz Holding anchors the power ship charter model with fleet deployments across African and Asian coastal markets.
| Leading Market Players |
|---|
| MAN Energy Solutions SE |
| Kawasaki Heavy Industries, Ltd. |
| Wärtsilä Corporation |
| Doosan Heavy Industries & Construction Co., Ltd. |
| Shanghai Electric Group Co., Ltd. |
| Siemens AG |
| Mitsubishi Heavy Industries, Ltd. |
| Karadeniz Holding |
| General Electric |
| Others |
Cost & Logistics Intelligence
The EU F-Gas Directive gates qualified supply and premium-tier pricing access by mandating dual-fuel engine certifications that only Wärtsilä, MAN Energy Solutions, and Siemens AG can deliver at scale. Buyers lacking marine emissions compliance face vessel charter exclusion or diesel-heavy barge retirement, compressing procurement options to certified suppliers commanding 15-25% efficiency premiums.
Pricing Analysis
Availability-based charter contracts anchor pricing to uptime guarantees rather than capital expenditure, transferring fuel price and maintenance risk from PLN and West African utilities to vessel owners. Price differentiation hinges on dual-fuel certification tier and integrated battery storage bundling, with hybrid power islands commanding premiums over standalone gas turbine configurations. LNG price volatility is squeezing operator margins and shortening contract durations as charterers resist long-term fuel commitments. State utilities in Indonesia and Caribbean archipelago nations exhibit highest price sensitivity, while Petrobras and Equinor prioritize technical specification compliance over unit economics.
Supply Chain Analysis
Semi-submersible hull fabrication rests on South Korean and Singaporean shipyard capacity, with DSME, Hyundai Heavy Industries, and Jurong cluster yards controlling newbuild orders through 2026. Specialized inputs include heat recovery steam generators, aeroderivative turbine packages, and subsea cable armoring systems. Single-source vulnerability concentrates in dual-class society approvals from Bureau Veritas and DNV, where parallel documentation streams extend delivery timelines. Distribution runs through integrated power island charters that unify prime mover, storage, and grid stabilization procurement under single vessel contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated power island capabilities as specialized hull fabrication bottlenecks and dual-certification requirements force pure-play generation specialists toward acquisition or exit.
For Market Incumbents: Cement market position through captive shipyard partnerships in Ulsan-Busan and Jurong clusters, securing hull fabrication slots against Korean and Singaporean capacity constraints. Invest in modular after-treatment systems reconfigurable for Japanese METI and EU F-Gas Directive thresholds, neutralizing regulatory fragmentation threats from overlapping compliance obligations. For New Entrants and Emerging Players: Enter via Indonesian archipelago electrification, where PLN's availability-based contract pilots create entry paths without capital-intensive vessel ownership. Target Riau Islands and Sulawesi floating solar integration projects, leveraging tethered photovoltaic arrays that attach to existing maritime infrastructure without semi-submersible platform requirements. For Investors and Strategic Acquirers: Karadeniz Holding's power ship fleet deployments across African and Asian coastal markets are the leading indicator that charter-based asset-light models outperform capital-heavy ownership structures in currency-volatile environments. Prioritize acquisition targets with established dual-fuel engine certifications and Bureau Veritas/DNV approval track records, watching for METI territorial water framework expansion as the signal for Japanese market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Shipyard Partnership Lock-up | Secures semi-submersible hull fabrication slots against South Korean and Singaporean capacity constraints. |
| Dual-Fuel Certification Expansion | Extends Wärtsilä and MAN Energy Solutions engine portfolios to EU F-Gas Directive compliance tiers. |
| Power-as-a-Service Charter Rollout | Transfers fuel price risk to vessel owners in Indonesian and West African island electrification markets. |
| Battery Storage Integration | Unifies gas turbine and BESS procurement into single hybrid power island specifications for Equinor and Petrobras. |
| Floating Solar Tether Systems | Attaches modular photovoltaic arrays to existing offshore oil infrastructure in Indonesian and Vietnamese waters. |
Research Approach
Multi-period observation of vessel order backlogs, charter contract structures, and marine emissions certification timelines anchored the trend analysis, supplemented by interviews with utility planning officers, offshore drilling procurement leads, EPC contractors, and shipyard project managers. Secondary validation drew from IMO carbon intensity regulation filings, EU F-Gas Directive implementation guidance, ANVISA environmental licensing records, and METI territorial water framework documentation. Bottom-up triangulation across individual vessel charters and top-down validation against regional electrification demand aggregates established market sizing boundaries.
Segment-weighting across generation type, technology, application, and end-user dimensions shaped the analytical framework, with fuel flexibility and marine certification status as cross-cutting variables. CAGRs were derived from deployment timeline compression observed in Brazilian pre-salt field development and Indonesian archipelago grid extension programs. Forecast inputs incorporated LNG price volatility scenarios and dual-class society approval backlog estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under South Korean shipyard strike actions or abrupt EU F-Gas Directive threshold revisions. Assumptions reflect current regulatory trajectories and charter contract migration patterns. Vessel availability rates, LNG contract duration preferences, and Japanese METI framework expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Hydropower Market