
 Wind Turbine Pitch and Yaw Drive Market | 2026-2036
Wind Turbine Pitch and Yaw Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Pitch and Yaw Drive Market Insights
The capital-intensity divergence between integrated turbine OEMs and specialized drivetrain suppliers is unwinding competitive dynamics across the supply base. Siemens Gamesa leverages captive gearbox production to control cost structures on offshore platforms. Bosch Rexroth anchors its position through hydraulic pitch systems that dominate the retrofit channel for aging European fleets. Bonfiglioli Transmissions specializes in compact yaw drives that compete aggressively for space-constrained nacelle designs in Asian markets.
Wind turbine pitch and yaw drives are electromechanical or hydraulic actuation systems that adjust blade angle and nacelle orientation, typically rated for torque outputs exceeding 50 kNm and operating cycles of 20-plus years in variable load conditions. Their primary purpose is to maximize energy capture while protecting rotor assemblies from aerodynamic and structural overload. Gearbox assemblies command the largest share of component value due to material intensity and precision machining requirements, while hybrid electromechanical-hydraulic mechanisms are gaining fastest in offshore applications where redundancy requirements are strictest. OEMs retain the dominant procurement channel, though maintenance providers are expanding share as repowering cycles compress and service contracts extend to 15-year terms.
The EU Green Deal and F-Gas Regulation are tightening lubricant and sealing standards for yaw systems deployed in European waters, while China's GB standards and dual carbon goals are accelerating domestic certification requirements for pitch drive reliability. The US IRA production tax credits are reshaping supplier qualification timelines as developers rush to secure compliant components for projects under construction. Stakeholders must monitor how divergent certification timelines across ECHA, SAMR, and EPA frameworks affect cross-border component sourcing and inventory positioning.
Market Dynamics
Offshore wind turbine scaling toward 15 MW-plus capacities is forcing redesigns of pitch and yaw drivetrain architectures, as torque loads and redundancy requirements outstrip legacy electromechanical specifications.
Growth Catalysts
- EU Green Deal implementation:Tightening reliability mandates for drivetrain components in European waters accelerate replacement cycles for aging onshore fleets and specification upgrades for new offshore installations.
- China's coastal province clustering:Gigawatt-scale offshore wind construction in Jiangsu, Guangdong, and Fujian provinces concentrates demand for high-torque yaw systems rated above 80 kNm.
- Electromechanical-hybrid actuation:Dual-redundant pitch mechanisms combining servo motors with hydraulic backup are capturing specification share in North Sea developments where turbine availability targets exceed 97 percent.
Market Restraints
- Specialized alloy supply concentration:Case-hardened steel forgings for planetary gearboxes depend on a limited supplier base in Germany and Japan, exposing OEMs to 18-24 month order backlogs.
- F-Gas Regulation compliance costs:Sealed hydraulic systems using fluorinated lubricants face reformulation expenses and recertification delays for European offshore deployments.
- Direct-drive turbine substitution:Permanent-magnet generators eliminating gearboxes entirely threaten addressable market volume in onshore segments below 5 MW rated capacity.
Strategic Opportunities
- US IRA production tax credit qualification:Domestic content bonuses for offshore wind components create first-mover advantage for yaw drive suppliers establishing US-based machining and assembly.
- Retrofit channel expansion:Service providers unbundling 15-year maintenance contracts from OEM supply agreements open procurement access for specialized pitch system refurbishers.
- Digital twin integration:Real-time load monitoring fused with predictive maintenance algorithms enables performance-based service pricing models for fleet operators.
Industry Challenges
- Precision machining skill scarcity:Gear grinding and heat treatment expertise for 20-year fatigue-rated components concentrates in aging workforces across Upper Austria and northern Italy.
- Cross-border certification friction:Divergent ECHA, SAMR, and EPA approval timelines for lubricant formulations complicate inventory positioning for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Pitch and Yaw Drive Market |
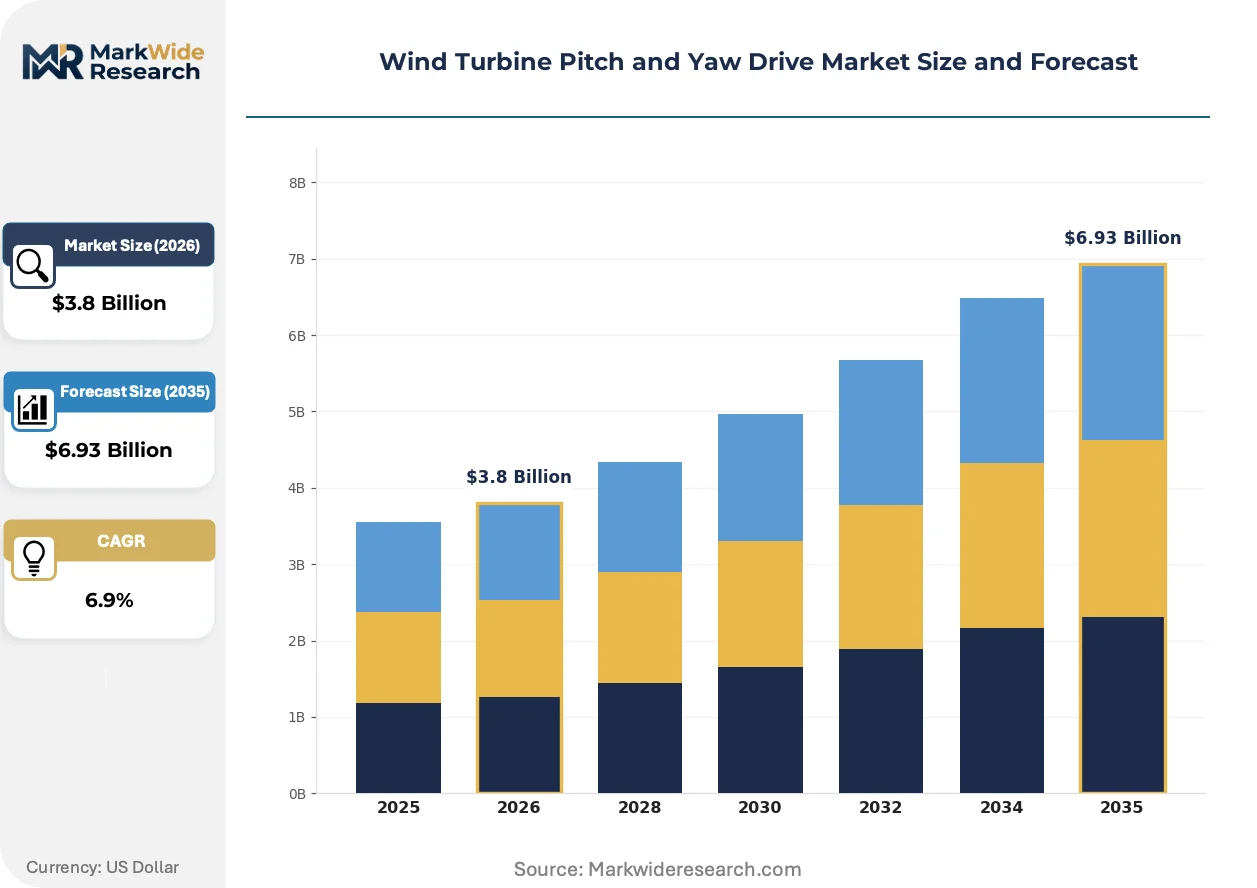
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.93 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Pitch Drives, Yaw Drives, Gearbox Assemblies, Control Systems Mechanism: Electrical, Hydraulic, Mechanical, Hybrid End User: OEMs, Power Producers, Maintenance Providers, Asset Managers Application: Onshore, Offshore, Co-located, Repowering |
| Companies Covered | Siemens Gamesa, GE Renewable Energy, Nordex, Vestas Wind Systems, Suzlon Energy, Mitsubishi Heavy Industries, Bonfiglioli Transmissions, Bosch Rexroth, Nanjing High Speed Gear Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Pitch and Yaw Drive Market Trends and Innovations
Actuation technology divergence, regulatory chemistry restrictions, and procurement unbundling are compressing traditional supply relationships while opening specialized service channels.
Integrated electromechanical-hydraulic pitch actuators is fragmenting supplier tiers in offshore markets. These systems combine high-response servo control with failsafe hydraulic locking for emergency feathering. Tier-one turbine OEMs are qualifying second-source suppliers for hybrid architectures, breaking historical single-source gearbox dependencies. The technology is fragmenting procurement concentration that previously favored captive drivetrain divisions.
REACH and F-Gas Regulation amendments are restricting perfluoropolyether lubricants in yaw bearing seals for European offshore installations. Manufacturers must reformulate greases to maintain 20-year corrosion resistance without restricted fluorinated compounds. German and Danish turbine operators face accelerated replacement schedules for existing fleets using non-compliant sealing systems.
Long-term service agreements are unbundling from initial equipment supply, allowing independent maintenance providers to capture pitch and yaw overhaul revenue. Specialist drivetrain refurbishers in Spain and Poland are building regional hub capabilities to serve aging onshore installations. This channel shift is most visible in Germany's repowering corridors, where 2-3 MW class turbines installed in the early 2000s require systematic drivetrain replacement.
Wind Turbine Pitch and Yaw Drive Market Segmentation
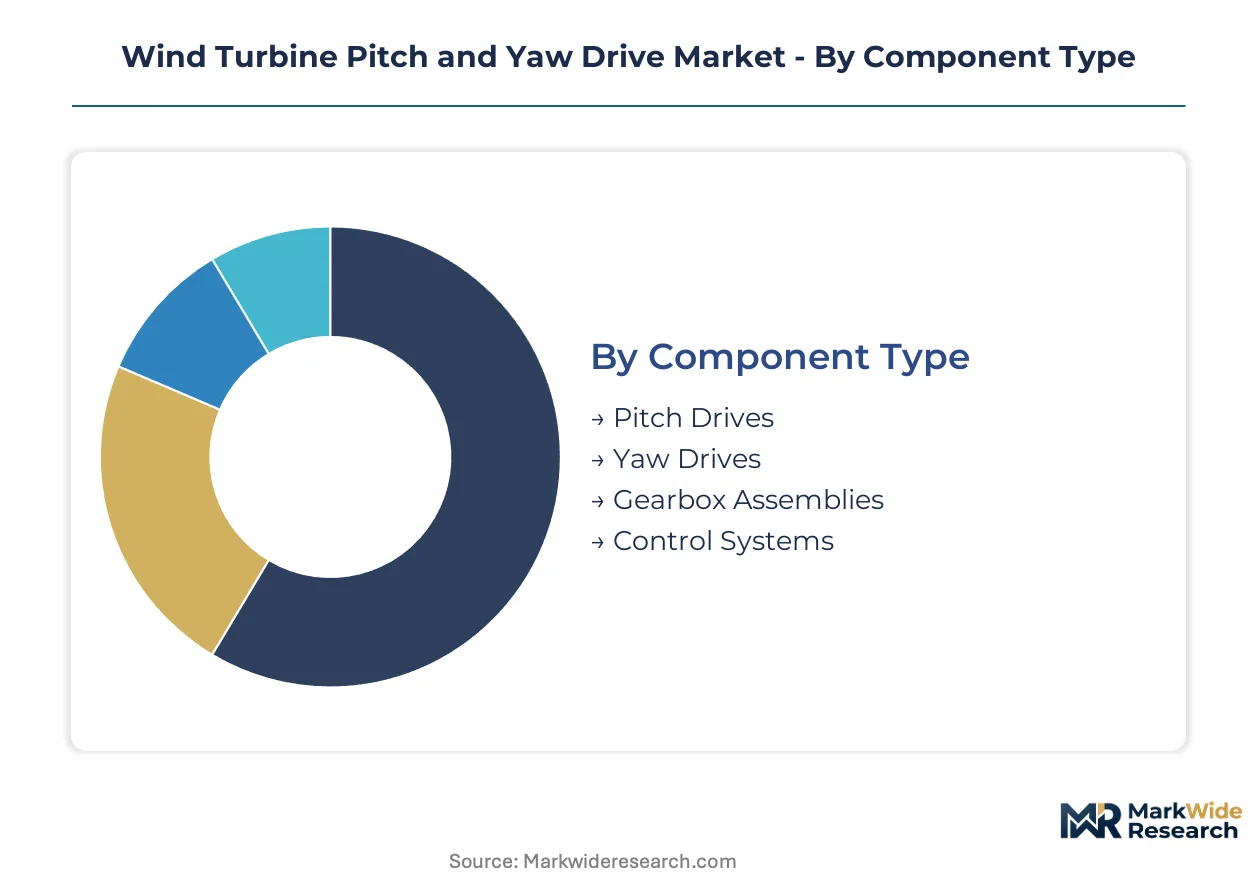
Pitch and yaw drive procurement patterns fragment sharply across component hierarchies, actuation technologies, and customer archetypes. Margin capture concentrates where fatigue-rated machining expertise collides with 20-year service obligations.
Component Type:
Gearbox assemblies command the deepest margin pools due to case-hardened steel intensity and precision grinding requirements.
- Gearbox Assemblies:Planetary gear trains rated above 80 kNm torque dominate offshore specifications. Demand clusters in China's Jiangsu and Guangdong provinces where 15 MW-plus turbines require redundant drivetrain architectures.
- Pitch Drives:Electromechanical actuators with servo motor control adjust blade angle in 0.1-degree increments. European OEMs specify these for North Sea developments where availability targets exceed 97 percent.
- Yaw Drives:Compact multi-motor systems orient nacelles against wind direction. Asian nacelle designers favor space-constrained configurations from Italian and Austrian suppliers.
- Control Systems:PLC-based architectures integrate turbine SCADA with pitch and yaw positioning algorithms. These capture value through software-enabled predictive maintenance contracts.
Gearbox assemblies hold installed capacity. Control systems are rotating up the share rankings.
Mechanism:
Cost tier stratification separates premium hybrid architectures from commodity electromechanical units.
- Hybrid:Dual-redundant systems combining servo motors with hydraulic backup dominate offshore procurement. German and Danish developers specify these for F-Gas Regulation compliance in North Sea waters.
- Electrical:Pure electromechanical actuators serve onshore turbines below 5 MW where capital constraints limit specification flexibility. These face displacement pressure from direct-drive generator substitution.
- Hydraulic:Sealed hydraulic systems with fluorinated lubricants face REACH-mandated reformulation. Bosch Rexroth anchors retrofit demand for aging European fleets.
- Mechanical:Legacy rack-and-pinion architectures persist in early-2000s installations. Spanish and Polish refurbishers target these for systematic replacement cycles.
Hybrid mechanisms hold installed capacity. Electrical systems are rotating up the share rankings in cost-sensitive onshore segments.
End User:
Customer type determines contract structure and margin durability across the equipment lifecycle.
- OEMs:Turbine manufacturers source through captive drivetrain divisions or qualified second-source suppliers. Siemens Gamesa leverages in-house gearbox production for offshore cost control.
- Maintenance Providers:Independent service firms unbundle 15-year overhaul contracts from initial supply agreements. German repowering corridors concentrate demand for systematic drivetrain replacement.
- Power Producers:Utility and IPP direct procurement concentrates in China's coastal provinces where gigawatt-scale clusters standardize component specifications.
- Asset Managers:Financial owners optimize fleet availability through performance-based service pricing. Digital twin integration enables predictive maintenance algorithms.
OEMs hold installed capacity. Maintenance providers are rotating up the share rankings as repowering cycles compress.
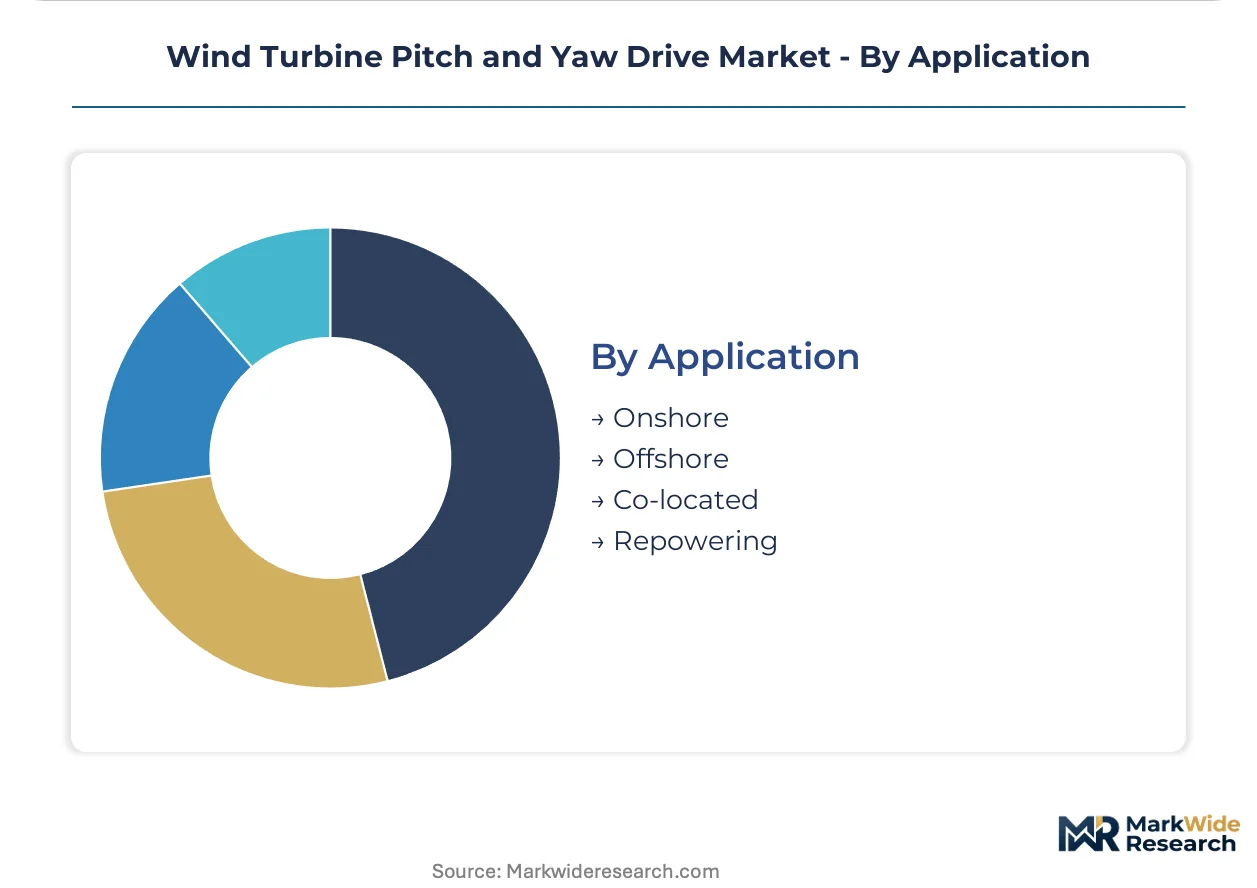
Application:
Volume concentration diverges between mature onshore replacement and explosive offshore expansion.
- Offshore:15 MW-plus turbines force torque specification upgrades beyond legacy electromechanical limits. China's Fujian province and Germany's North Sea zones anchor demand.
- Onshore:Sub-5 MW installations face direct-drive substitution eliminating gearbox demand entirely. US IRA production tax credits reshape supplier qualification timelines.
- Repowering:Systematic replacement of 2-3 MW class turbines installed in the early 2000s drives drivetrain overhaul demand. German corridors concentrate refurbishment activity.
- Co-located:Hybrid renewable sites with shared grid infrastructure standardize pitch and yaw specifications across mixed generation assets.
Onshore holds installed capacity. Offshore applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Danish precision machining clusters while Chinese coastal provinces capture volume leadership through gigawatt-scale offshore procurement. This asymmetry shapes supplier qualification timelines and inventory positioning across the forecast window.
China
Gigawatt-scale offshore construction in Jiangsu, Guangdong, and Fujian provinces drives demand for yaw systems rated above 80 kNm torque. GB standards and dual carbon goals accelerate domestic certification requirements for pitch drive reliability. Nanjing anchors gearbox manufacturing capacity serving coastal turbine clusters.
Germany
North Sea offshore developments specify dual-redundant hybrid actuation systems for availability targets exceeding 97 percent. ECHA and F-Gas Regulation amendments restrict fluorinated lubricants in yaw bearing seals, forcing reformulation investments. Repowering corridors in northern states concentrate systematic drivetrain replacement demand from early-2000s installations.
United States
IRA production tax credit domestic content bonuses reshape supplier qualification timelines for offshore projects under construction. EPA frameworks govern lubricant formulations for coastal deployments. East Coast port infrastructure investments position Massachusetts and Virginia assembly hubs for yaw drive localization.
Denmark
EU Green Deal implementation tightens reliability mandates for drivetrain components in Baltic and North Sea waters. REACH compliance requirements accelerate replacement cycles for aging onshore fleets. Copenhagen-Aarhus industrial corridor retains precision grinding expertise for 20-year fatigue-rated planetary gearboxes.
Japan
METI offshore wind targets drive specification upgrades for typhoon-resistant pitch actuation systems. JIS standards govern materials certification for case-hardened steel forgings. Nagoya-Yokohama manufacturing belt concentrates heat treatment expertise for high-torque planetary architectures.
Wind Turbine Pitch and Yaw Drive Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated turbine OEMs controlling captive drivetrain production while specialized transmission suppliers capture retrofit and second-source opportunities. The market structures around three tiers: vertically integrated turbine manufacturers, precision gearbox specialists, and hydraulic actuation providers. Consolidation pressure concentrates in the mid-tier as OEMs qualify alternative suppliers for hybrid electromechanical-hydraulic architectures. Strategic moves center on regional assembly localization and long-term service contract unbundling.
Among European-anchored industrial groups, Siemens Gamesa and Bosch Rexroth exemplify divergent archetypes—one representing captive integration into turbine platforms, the other anchoring independent hydraulic system supply. Bonfiglioli Transmissions occupies a position within the specialized transmission tier focused on compact yaw drive configurations.
| Leading Market Players |
|---|
| Siemens Gamesa |
| GE Renewable Energy |
| Nordex |
| Vestas Wind Systems |
| Suzlon Energy |
| Mitsubishi Heavy Industries |
| Bonfiglioli Transmissions |
| Bosch Rexroth |
| Nanjing High Speed Gear Manufacturing |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal certification tiers gate both supplier qualification timelines and price differentiation across offshore and onshore procurement channels simultaneously. F-Gas Regulation compliance costs for sealed hydraulic systems create a bifurcated supply base where certified European suppliers command sustained premiums against Asian competitors serving less regulated markets.
Pricing Analysis
Configured-to-order pricing for hybrid electromechanical-hydraulic systems carries 40-60% premiums over standard electromechanical units due to dual-redundant architecture requirements. Price differentiation hinges on GB standard certification grade for Chinese deployments and F-Gas Regulation compliance tier for European waters. Cost compression in pure electromechanical onshore segments is intensifying because direct-drive generator substitution eliminates gearbox demand entirely. Maintenance providers show highest price sensitivity due to unbundled service contract economics, while offshore developers prioritize availability guarantees over capital expenditure minimization.
Supply Chain Analysis
German and Japanese case-hardened steel forging capacity constitutes the critical chokepoint for planetary gearbox production, with order backlogs extending 18-24 months for 20-year fatigue-rated components. Raw material dependencies center on specialized alloy feedstock from Upper Austrian precision machining clusters, fluorinated lubricant formulations facing REACH-mandated reformulation, and rare-earth elements for servo motor magnets. Single-source vulnerability concentrates in heat treatment expertise for high-torque yaw systems. Distribution runs through OEM captive divisions for new turbine supply and independent service hubs for retrofit channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind scaling toward 15 MW-plus capacities represents an early-cycle expansion story. China's gigawatt-scale coastal clustering and US IRA domestic content bonuses together accelerate penetration beyond historical onshore replacement patterns.
For Market Incumbents: Compound defensive positioning through captive gearbox production integration and second-source supplier qualification for hybrid architectures. Direct-drive generator substitution threatens addressable volume in sub-5 MW onshore segments. Prioritize F-Gas Regulation compliance investment to sustain European offshore pricing power against reformulation-lagged competitors. For New Entrants and Emerging Players: Independent maintenance contract unbundling from OEM supply agreements represents the most penetrable service-layer gap for specialized pitch system refurbishers. German repowering corridors and Spanish regional hub capabilities offer geographic white-space. Target 15-year overhaul contract capture through predictive maintenance algorithm integration as the primary go-to-market angle. For Investors and Strategic Acquirers: IRA production tax credit domestic content requirements reshape the acquisition landscape toward US-based machining and assembly capabilities. Five-to-ten year viability favors suppliers with established certification pathways across ECHA, SAMR, and EPA frameworks. Watch for cross-border lubricant formulation approval timeline divergence as the key inflection signal for inventory positioning risk.| Strategic Initiative | Industry Significance |
|---|---|
| US Assembly Localization | IRA domestic content bonuses reward Massachusetts and Virginia hub establishment for yaw drive machining. |
| Hybrid Actuator Qualification | Second-source supplier certification for electromechanical-hydraulic systems fragments captive gearbox dependencies. |
| Predictive Maintenance Platform | Digital twin integration enables performance-based service pricing for asset managers optimizing fleet availability. |
| F-Gas Compliant Reformulation | REACH-mandated lubricant chemistry investment sustains European offshore market access against regulatory exclusion. |
| Repowering Channel Expansion | Systematic 2-3 MW class drivetrain replacement in German corridors concentrates independent service provider demand. |
Research Methodology
Operator-level perspectives from turbine OEM procurement directors, independent maintenance service heads, offshore project developers, and gearbox manufacturing plant managers anchored the qualitative base. Primary interview findings triangulated against secondary validation from EIA wind deployment databases, IEA offshore wind outlooks, FERC interconnection filings, and customs trade data for case-hardened steel forgings. Bottom-up component cost modeling and top-down market sizing across actuation technology tiers ensured methodological cross-checking.
Sensitivity analysis framing governed the analytical approach throughout the projection horizon. Segmentation dimensions modeled include mechanism type, application category, end-user archetype, and regional regulatory cluster. CAGRs derived from installed capacity buildout trajectories, replacement cycle compression rates, and specification upgrade elasticities. Industry-specific forecast inputs incorporated 15 MW-plus turbine torque requirements and repowering corridor activity concentration.
Material uncertainties — alloy supply bottleneck duration, cross-border certification timeline divergence, and direct-drive substitution pace in onshore segments — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding GB standard adoption timelines and IRA domestic content interpretation stability. Practitioners should keep alternative scenarios live as F-Gas Regulation amendment implementation and SAMR pitch drive reliability enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market