
 North America Hydropower Market | 2026-2036
North America Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydropower Market Analytics
Multi-source equipment procurement is pivoting as developers diversify beyond single OEM dependencies for large turbine-generator packages. GE Renewable Energy leverages its digital hydropower portfolio to compete on plant optimization software. Andritz AG anchors its North American position through specialized Francis and Kaplan turbine engineering for retrofit markets. Duke Energy Corporation sustains its competitive edge by controlling extensive pumped storage assets across the Appalachian region.
North America hydropower encompasses electricity generation from flowing or stored water through turbines connected to generators, with modern installations achieving 90-95% efficiency in large Francis turbine configurations and serving as dispatchable baseload and grid-balancing resources. Pumped storage technology leads capacity investment as utilities seek long-duration storage alternatives to lithium-ion batteries. Run-of-river installations represent the fastest-growing segment for new greenfield development, particularly for Indigenous community partnerships and distributed utility procurement. Reservoir-based generation occupies the mature margin pool, where brownfield modernization of control systems and runner replacements yields returns without new civil works.
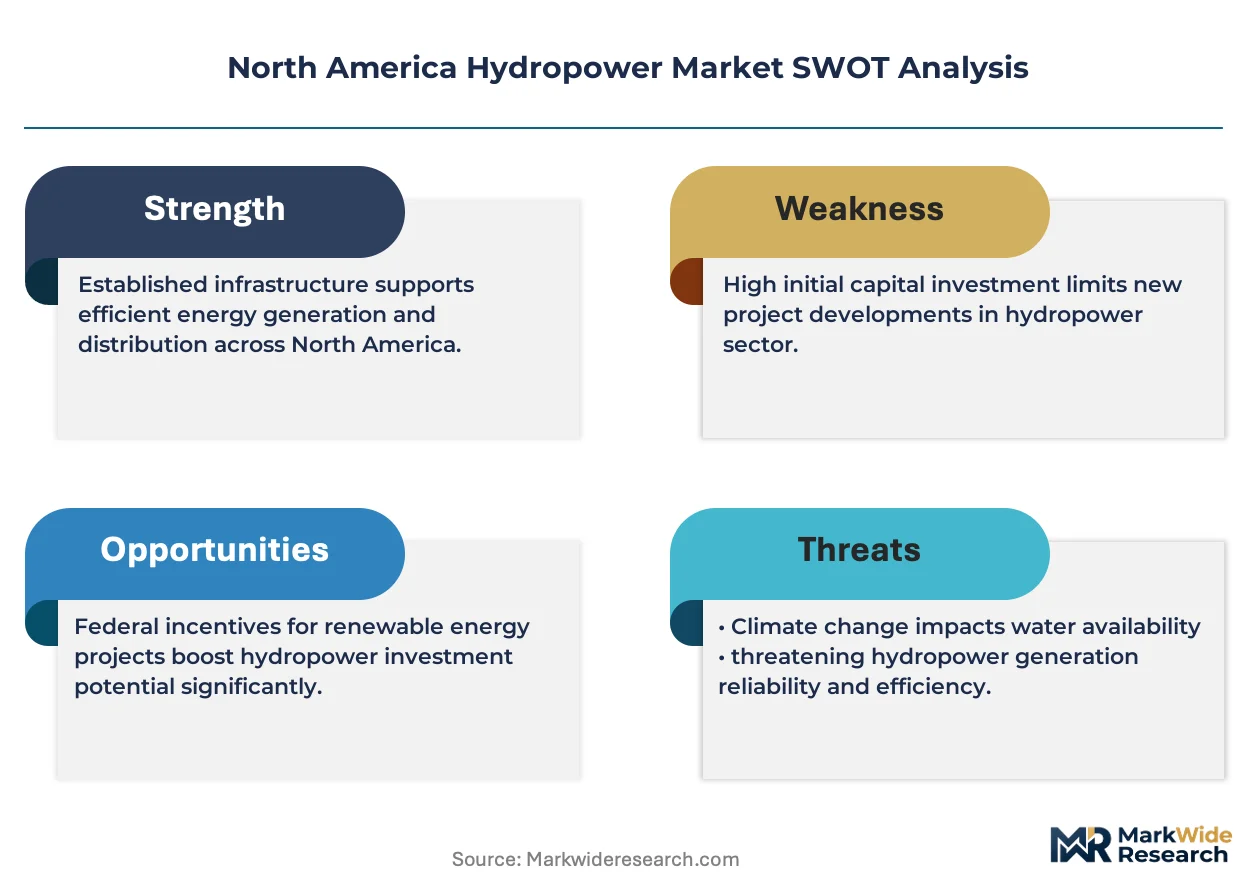
FERC relicensing requirements and Canada's CEA environmental flow mandates shape capital allocation by imposing fish passage, water quality, and recreational access conditions that extend project timelines and retrofit obligations. The EPA's Clean Water Act Section 404 permits and provincial water rights frameworks in British Columbia and Quebec further constrain site access and operational flexibility. Stakeholders must monitor evolving grid interconnection standards and carbon accounting methodologies that determine whether hydropower qualifies for clean energy procurement mandates in state and provincial regimes.
Market Dynamics
The North America hydropower market pivots on FERC's accelerated relicensing timeline, which compresses decades-old project economics into 30-50 year investment horizons while mandating fish passage and environmental flow retrofits that reshape capital deployment strategies across the United States and Canada.
Growth Catalysts
- Intermittency balancing requirements:State-level renewable portfolio standards in California and New York mandate storage co-location, driving pumped storage procurement as lithium-ion alternatives face duration limitations.
- FERC Order 2222 implementation:The Federal Energy Regulatory Commission's distributed energy resource aggregation rule enables run-of-river facilities to participate in wholesale markets, unlocking revenue streams for small-scale developers.
- Indigenous partnership frameworks:Canada's Indigenous-led clean energy initiative channels federal infrastructure funding toward community-owned hydroelectric projects in British Columbia and Quebec.
Market Restraints
- Steel and copper price volatility:Turbine runner fabrication and generator winding costs fluctuate with commodity markets, squeezing fixed-price EPC contracts for brownfield modernization.
- Environmental permitting density:The EPA's Clean Water Act Section 404 wetland permits and state-level water quality certifications create sequential approval bottlenecks that extend project timelines.
- Geologic site scarcity:Pumped storage development confronts limited suitable topography in the eastern United States, concentrating viable locations in the Appalachian region.
Strategic Opportunities
- Non-powered dam conversion:The U.S. Army Corps of Engineers inventory of 80,000+ dams without generation equipment offers brownfield installation potential with reduced civil works.
- Hybrid renewable pairing:Co-located solar-floatovoltaic arrays on reservoir surfaces enable dual land use and shared interconnection infrastructure in the southwestern United States.
- Canada's Investment Tax Credit:The federal clean technology ITC covers 30% of eligible capital costs for new hydroelectric and pumped storage facilities through 2034.
Industry Challenges
- Specialized turbine engineering talent:Francis and Kaplan runner design expertise concentrates among retiring OEM engineers, constraining retrofit project execution capacity.
- Legacy control system integration:Digital governor replacements must interface with 1960s-era civil structures and mechanical governors, complicating automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydropower Market |
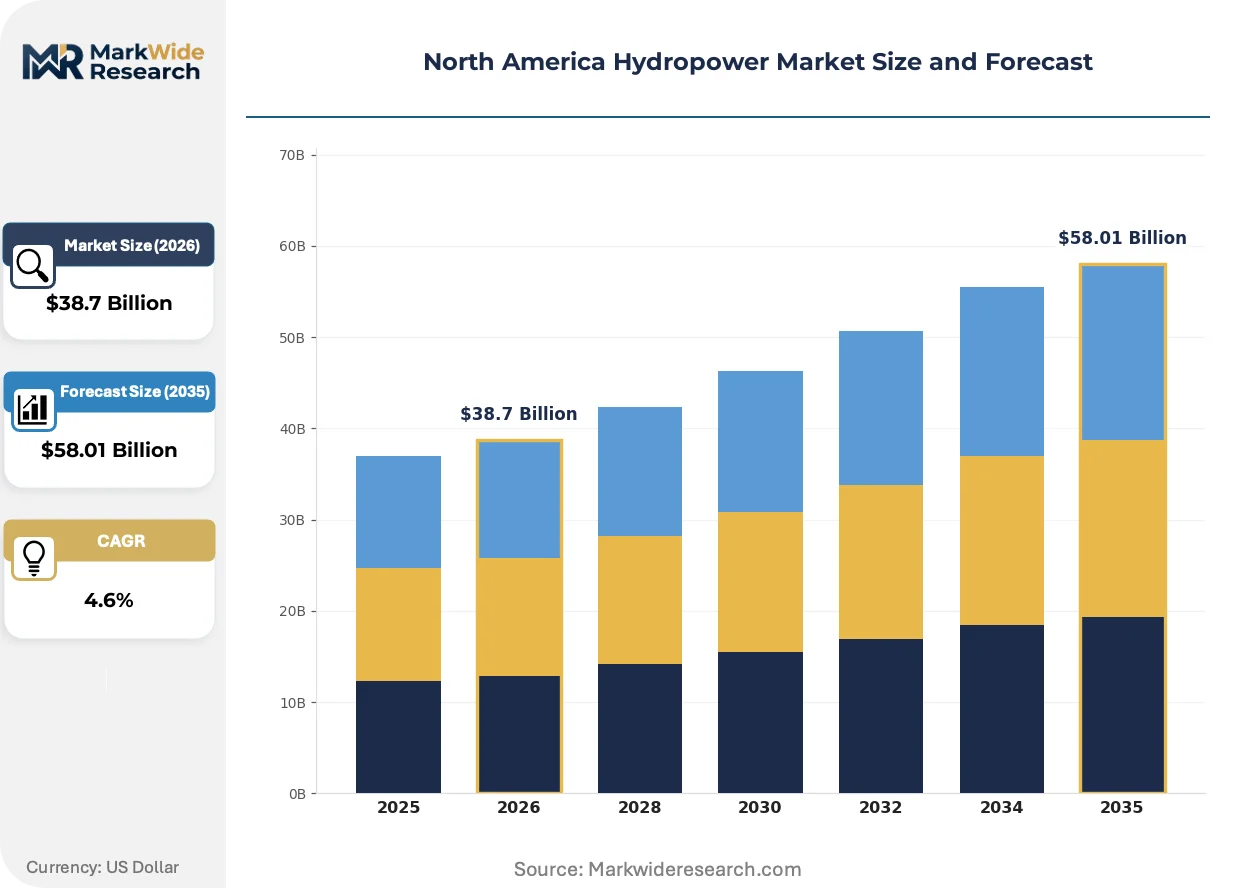
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Run-of-River, Pumped Storage, Reservoir, Small-Scale Application: Electricity Generation, Irrigation, Flood Control, Navigation End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Greenfield, Brownfield |
| Companies Covered | Hydro-Québec, BC Hydro, Duke Energy Corporation, Ontario Power Generation, Tennessee Valley Authority, Brookfield Renewable Partners, Georgia Power Company, GE Renewable Energy, Andritz AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydropower Market Evolving Landscape
Digitalization and modular system architectures are compressing project development cycles while environmental performance standards reconfigure equipment specifications across the North American supply base.
Variable-speed pump-turbine technology is decentralizing grid services provision by enabling pumped storage facilities to provide synthetic inertia and fast frequency response previously reserved to thermal generators. Independent system operators in Texas and California are procuring these capabilities through ancillary service markets. Equipment suppliers are retrofitting fixed-speed units with full-power converter interfaces to capture this revenue stream.
The EPA's revised Section 316(b) cooling water intake regulations mandate closed-cycle systems or fish-friendly intake designs for new and relicensed facilities. This industrial consequence elevates capital costs for reservoir-based projects while accelerating adoption of behavioral deterrent technologies. Developers in the Pacific Northwest are responding with acoustic and light-based fish guidance systems rather than physical screens.
Utility procurement departments are consolidating turbine-generator packages under single-source EPC arrangements, displacing traditional multi-contractor project structures. This concentration shifts risk to integrated vendors and compresses owner engineering oversight requirements. The pattern is most visible among municipal utilities in the Midwest seeking to streamline relicensing execution.
North America Hydropower Market Segmentation
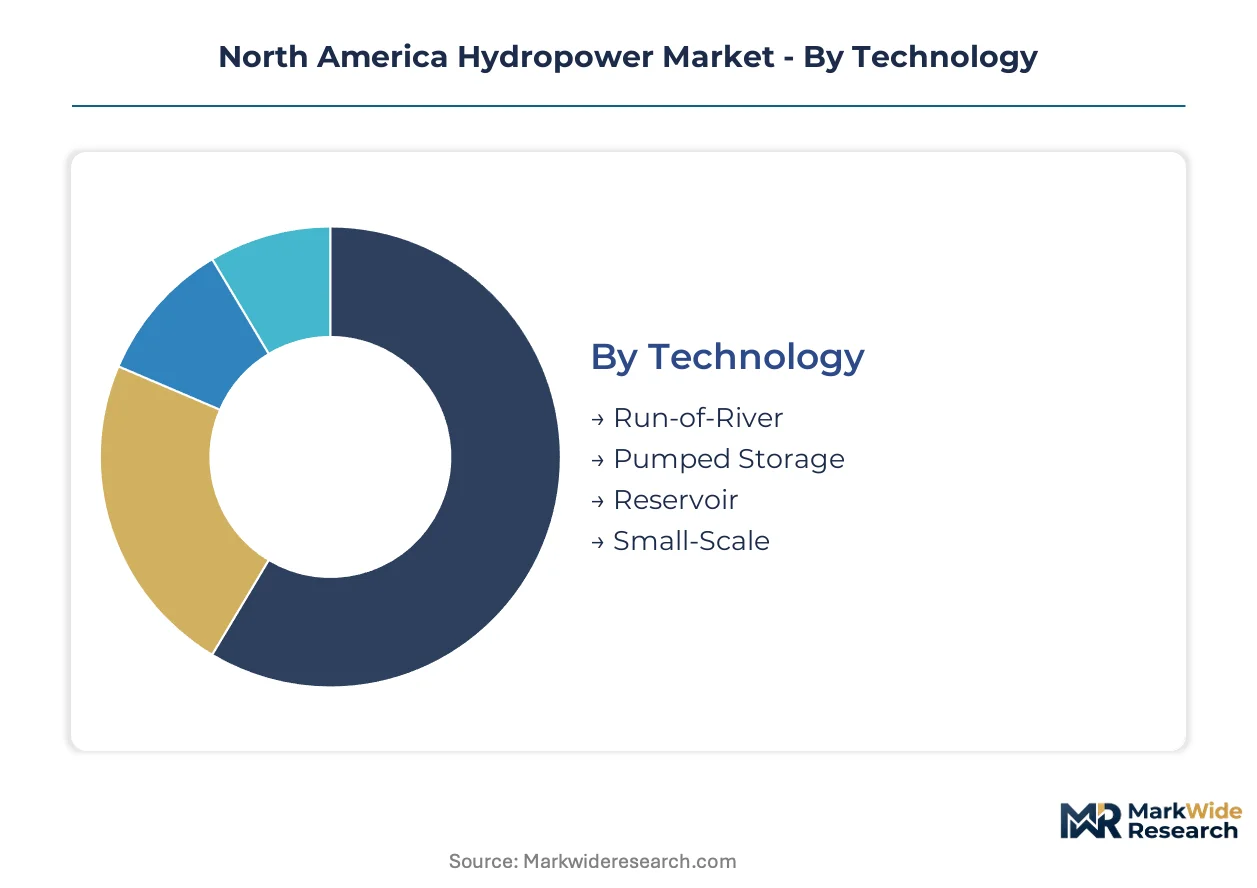
Segmentation reveals how capital deployment splits across radically different engineering profiles and regulatory pathways in North American hydropower. Each dimension carries distinct FERC, EPA, and provincial permitting burdens that determine project feasibility and returns.
Technology:
FERC relicensing timelines and EPA Section 404 wetland permits impose divergent compliance costs across technology types, with pumped storage facing the most intensive federal review.
- Run-of-River:Facilities generate electricity from natural river flow without large impoundments, utilizing diversion weirs and penstocks. Indigenous community partnerships in British Columbia and Quebec concentrate procurement here, driven by Canada's federal clean energy funding frameworks.
- Pumped Storage:Reversible pump-turbines cycle water between upper and lower reservoirs to provide grid-scale storage. Appalachian topography in the eastern United States hosts nearly all viable greenfield sites, constrained by geologic scarcity elsewhere.
- Reservoir:Large impoundment dams with seasonal storage capacity dominate the Pacific Northwest's Columbia River basin. EPA Section 316(b) fish protection mandates elevate retrofit costs for intake structures.
- Small-Scale:Run-of-river units under 10 MW capacity serve distributed utility procurement and rural electrification. FERC Order 2222 aggregation rules unlock wholesale market participation for these facilities.
Leading the category by volume: Reservoir. Growing fastest: Run-of-River.
Application:
Revenue models diverge sharply between power sales and non-power benefits, with electricity generation commanding premium equipment specifications.
- Electricity Generation:Baseload and peaking power sales to ISOs and utilities. California and New York renewable portfolio standards mandate storage co-location, driving pumped storage procurement.
- Irrigation:Water delivery infrastructure integrated with generation facilities. Bureau of Reclamation projects in the western United States combine these functions.
- Flood Control:Dam operations prioritize downstream protection over energy optimization. U.S. Army Corps of Engineers maintains operational authority.
- Navigation:Lock-and-dam systems on inland waterways enable barge traffic. Ohio and Mississippi River basins concentrate this application.
Electricity generation commands equipment expenditure concentration. Irrigation integration offers the steepest expansion trajectory for hybrid revenue models.
End User:
Procurement scale and contracting sophistication separate utility buyers from distributed commercial and residential adopters.
- Utilities:Investor-owned and municipal utilities dominate turbine-generator procurement. Duke Energy Corporation controls extensive pumped storage assets across the Appalachian region.
- Industrial:Captive generation for pulp-and-paper, aluminum smelting, and mining operations. Quebec's hydro-intensive industrial base anchors this segment.
- Commercial:Corporate renewable energy procurement through virtual power purchase agreements. Tech sector demand concentrates in Oregon and Washington.
- Residential:Micro-hydro installations for off-grid properties and rural electrification. Limited scale constrains equipment supplier engagement.
Utilities absorb the majority of capital equipment. Commercial procurement is climbing the fastest on corporate sustainability mandates.
Installation:
Civil works intensity and environmental disturbance determine project timelines and community opposition intensity.
- Onshore:Conventional dam and powerhouse construction on terrestrial sites. FERC relicensing of existing facilities dominates activity.
- Offshore:Tidal and wave energy installations in coastal waters. Limited commercial deployment in North America.
- Greenfield:New construction on previously undeveloped sites. Permitting density and geologic scarcity constrain pipeline.
- Brownfield:Modernization of existing dams and equipment replacement. Non-powered dam conversion offers 80,000-plus candidate sites in the U.S. Army Corps of Engineers inventory.
Brownfield dominates current expenditure. Greenfield faces the steepest constraints from site access limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Columbia River basin topography anchors North American hydropower capacity, with glacial meltwater and mountainous terrain concentrating development in the Pacific Northwest and Canadian provinces.
United States
FERC relicensing mandates and state renewable portfolio standards drive turbine upgrades across the Pacific Northwest and Appalachian regions. The EPA's Clean Water Act Section 404 permits and Section 316(b) fish protection rules impose retrofit obligations on reservoir-based facilities. Duke Energy Corporation controls pumped storage assets across the Carolinas and Virginia, while Tennessee Valley Authority maintains Columbia River basin generation capacity.
Canada
Quebec's La Grande complex and British Columbia's Peace River system anchor provincial export capacity to US markets. The federal Investment Tax Credit covers eligible capital costs for new hydroelectric and pumped storage facilities through 2034. Hydro-Québec and BC Hydro dominate procurement in Montreal and Vancouver corridor clusters.
Mexico
Comisión Federal de Electricidad operates the Grijalva River cascade in Chiapas and the Colorado River diversion projects in Baja California. The country's national energy regulator oversees grid interconnection standards for independent power producers. Industrial load centers in Monterrey and Mexico City Metro drive demand for firm generation capacity.
North America Hydropower Market Competitive Landscape
Global majors compete with regional champions across turbine-generator supply and utility asset ownership. The market structure concentrates around integrated equipment vendors and large-scale asset operators with FERC-licensed portfolios. Two strategic archetypes dominate: full-service OEMs bundling digital optimization software, and utility-holding companies controlling pumped storage and reservoir assets. Competitive moves center on brownfield modernization contracts and Indigenous partnership frameworks for greenfield development.
Within the utility-holding archetype, Duke Energy Corporation and Tennessee Valley Authority exemplify scale-driven operators with extensive licensed capacity across multiple river basins. Among equipment specialists, GE Renewable Energy and Andritz AG occupy positions in the digital turbine and specialized runner engineering segments. Brookfield Renewable Partners represents the independent power producer model with transborder asset portfolios spanning Canadian provinces and US regions.
| Leading Market Players |
|---|
| Hydro-Québec |
| BC Hydro |
| Duke Energy Corporation |
| Ontario Power Generation |
| Tennessee Valley Authority |
| Brookfield Renewable Partners |
| Georgia Power Company |
| GE Renewable Energy |
| Andritz AG |
| Others |
Value Network & Pricing Analysis
EPA Section 316(b) fish protection mandates gate qualified supply for turbine intake retrofits and reserve premium-tier pricing access for vendors with certified behavioral deterrent engineering capabilities. FERC relicensing timelines compress procurement windows, forcing utilities toward bundled service contracts that embed environmental compliance risk in supplier pricing.
Pricing Analysis
Warranty and digital optimization software bundling separates premium turbine-generator packages from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects runner metallurgy grade and governor control system vintage. Cost compression in standard-tier Francis turbine retrofits is intensifying because steel and copper commodity volatility squeezes fixed-price EPC margins. Municipal utilities in the Midwest exhibit highest price sensitivity, while investor-owned utilities absorbing FERC-mandated environmental retrofits show lowest sensitivity due to cost-recovery mechanisms.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale pumped storage procurement, while regional distributors serve small-scale run-of-river developers. Manufacturing concentrates in Austria, Germany, and Switzerland for precision Francis and Kaplan runner fabrication. Raw material dependencies center on high-grade stainless steel forgings, copper generator windings, and rare-earth permanent magnets for variable-speed converters. Single-source vulnerability in specialized turbine engineering talent constrains retrofit execution capacity. Distribution runs through OEM-direct contracting for large projects and EPC-aggregated procurement for brownfield modernization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American hydropower is becoming a vertical-integration race as equipment suppliers pursue captive control over digital optimization software and utilities seek in-house turbine refurbishment capabilities.
For Market Incumbents: Deploy digital twin and predictive maintenance software as the anchor lever to lock in long-term service revenue. Incumbents should consolidate brownfield modernization contracts through single-source EPC bundling, displacing fragmented multi-contractor structures. Battery storage substitution threatens pumped storage margins, requiring incumbents to emphasize duration advantages and synthetic inertia services. Backward integration into runner remanufacturing secures capacity during specialized engineering talent shortages. For New Entrants and Emerging Players: Indigenous partnership frameworks in British Columbia and Quebec offer the most penetrable entry channel for community-owned run-of-river development. New entrants should target distributed utility procurement segments below 10 MW where FERC Order 2222 aggregation rules unlock wholesale market participation. Non-powered dam conversion projects in the U.S. Army Corps of Engineers inventory present white-space opportunities with reduced civil works requirements. Go-to-market positioning through federal clean technology ITC advisory services differentiates entrants from established OEMs. For Investors and Strategic Acquirers: Canada's federal Investment Tax Credit expansion announcements are the leading indicator that capital deployment toward pumped storage and new hydroelectric facilities will accelerate. Long-term viability across the analysis window hinges on FERC relicensing success rates and environmental compliance cost trajectories. Acquisition targets should display licensed capacity portfolios with near-term relicensing timelines and established Indigenous partnership frameworks. The signal to monitor is variable-speed pump-turbine technology adoption rates in California and Texas ancillary service markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Runner Remanufacturing | Captive supply of specialized Francis and Kaplan engineering capacity addresses OEM talent retirement waves. |
| FERC Relicensing Execution Partnership | Coordinated environmental compliance and fish passage retrofit bundling compresses project timelines for utilities. |
| Variable-Speed Pump-Turbine Technology Licensing | Full-power converter interfaces unlock synthetic inertia revenue streams in California and Texas ISO markets. |
| Indigenous-Led Clean Energy Joint Venture | Federal infrastructure funding channels in British Columbia and Quebec accelerate community-owned project development. |
| Digital Hydropower Platform Integration | Plant optimization software embeds recurring revenue and raises switching costs for utility customers. |
Research Methodology
FERC licensing databases, EIA generation statistics, and IEA hydropower technology reports formed the secondary backbone of this analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators validated capacity addition timelines and procurement patterns. Bottom-up project pipeline aggregation across the United States and Canada combined with top-down macroeconomic triangulation to establish market sizing. Secondary sources included provincial utility annual reports, environmental impact statements, and equipment supplier technical documentation.
Historical trendline analysis of capacity installations and modernization expenditure patterns informed the projection framework. Segmentation modeling covered technology type, application, end user, and installation methodology across the analysis window. CAGRs were derived from regression analysis of announced project pipelines and regulatory-mandated retrofit obligations. Forecast inputs incorporated steel and copper commodity price trajectories, FERC relicensing queue velocity, and Canada's Investment Tax Credit utilization assumptions.
Caveats apply where commodity price volatility, FERC regulatory delays, or Indigenous partnership negotiation timelines could materially shift the outlook. Forecasts reflect assumptions regarding environmental permit approval rates and grid interconnection standard evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Hydro Turbines Market