
 Europe Hydropower Market | 2026-2036
Europe Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydropower Market Foresight
Engineering talent specialized in turbine refurbishment and digital control systems is bifurcating the competitive landscape between full-service OEMs and niche service providers. Voith Hydro leverages its century of turbine manufacturing heritage to anchor large-scale rehabilitation contracts across German and Austrian river basins. Statkraft AS dominates Nordic pumped storage development, while Andritz AG competes through its integrated electromechanical package offerings for mid-capacity installations.
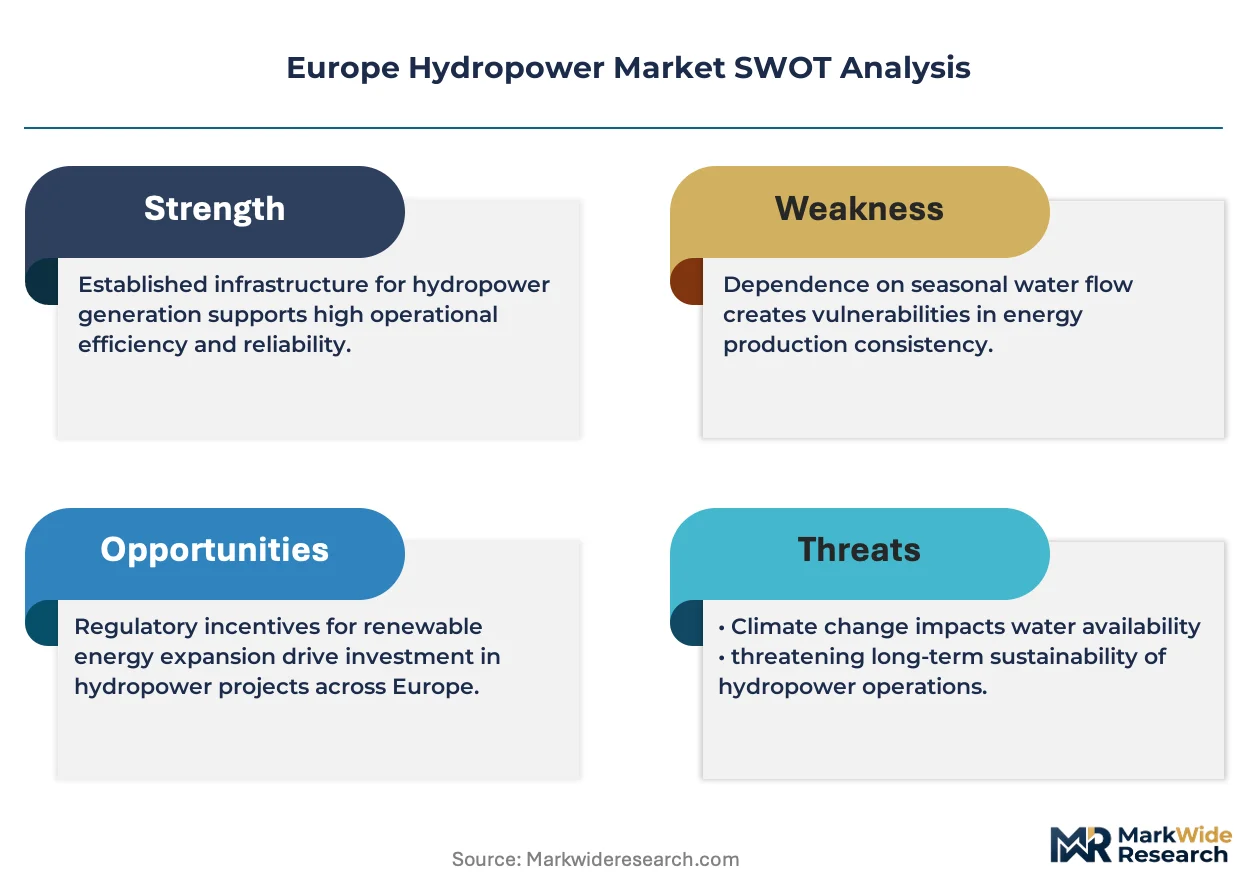
Hydropower harnesses gravitational energy from flowing or stored water to spin turbines connected to electric generators, with modern installations achieving conversion efficiencies exceeding ninety percent in Francis and Kaplan turbine configurations. The technology serves as the backbone of Europe's renewable grid stability, providing dispatchable baseload and rapid frequency response. Run-of-river installations lead capacity additions in the Alpine region due to lower environmental permitting barriers, while pumped storage commands the strongest margin pools as utilities seek arbitrage revenue from day-ahead electricity markets. Small hydropower below ten megawatts occupies a fragmented tier where local developers navigate divergent national licensing regimes.
The EU Green Deal and revised Renewable Energy Directive mandate streamlined permitting for renewable infrastructure, while the Water Framework Directive imposes strict ecological flow requirements that constrain operational flexibility. EMA coordination on cross-border grid codes shapes how pumped storage operators participate in ancillary service markets. Stakeholders must monitor how national implementations of the EU Electricity Market Design reform affect long-term capacity remuneration mechanisms for storage assets.
Market Dynamics
The EU Green Deal is compressing refurbishment timelines for aging European hydropower infrastructure while simultaneously tightening ecological constraints through the Water Framework Directive, forcing operators to modernize turbines without expanding reservoir footprints.
Growth Catalysts
- Alpine corridor topography:Switzerland, Austria, and Norway leverage steep river gradients for run-of-river and pumped storage development with minimal new environmental impact assessments required.
- EU Electricity Market Design reform:The revised framework establishes clearer capacity remuneration mechanisms for storage assets, improving pumped storage project economics across member states.
- Grid balancing mandates:Transmission system operators in Germany and Spain now procure frequency containment reserves explicitly favoring fast-ramping hydropower over thermal alternatives.
Market Restraints
- Steel and copper price volatility:Turbine runners and generator windings depend on these commodity inputs, exposing OEMs to margin compression when metals markets spike.
- Environmental permitting duration:The Water Framework Directive's strict ecological flow requirements extend licensing timelines in France and Italy by three to five years compared to pre-2010 baselines.
- Intermittent renewable substitution:Battery storage and green hydrogen projects compete for the same ancillary service revenue pools and grid connection capacity in Nordic markets.
Strategic Opportunities
- Small hydropower digitization:Run-of-river installations below ten megawatts in Romania and Bulgaria remain underserved by predictive maintenance platforms, creating white space for IoT-enabled monitoring providers.
- Repowering incentives:The EU Green Deal's streamlined permitting for renewable upgrades applies specifically to turbine replacements that improve efficiency without increasing water withdrawals.
- Cross-border ancillary services:EMA coordination on grid codes enables Norwegian and Swiss pumped storage operators to bid into German and French frequency regulation markets.
Industry Challenges
- Turbine engineering specialization:The workforce capable of Francis and Kaplan runner refurbishment is aging, with Alpine technical universities producing fewer graduates than retirement rates.
- Legacy control system integration:Digital turbine governors must interface with mechanical-hydraulic governors installed in the 1970s and 1980s across Austrian and Italian plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydropower Market |
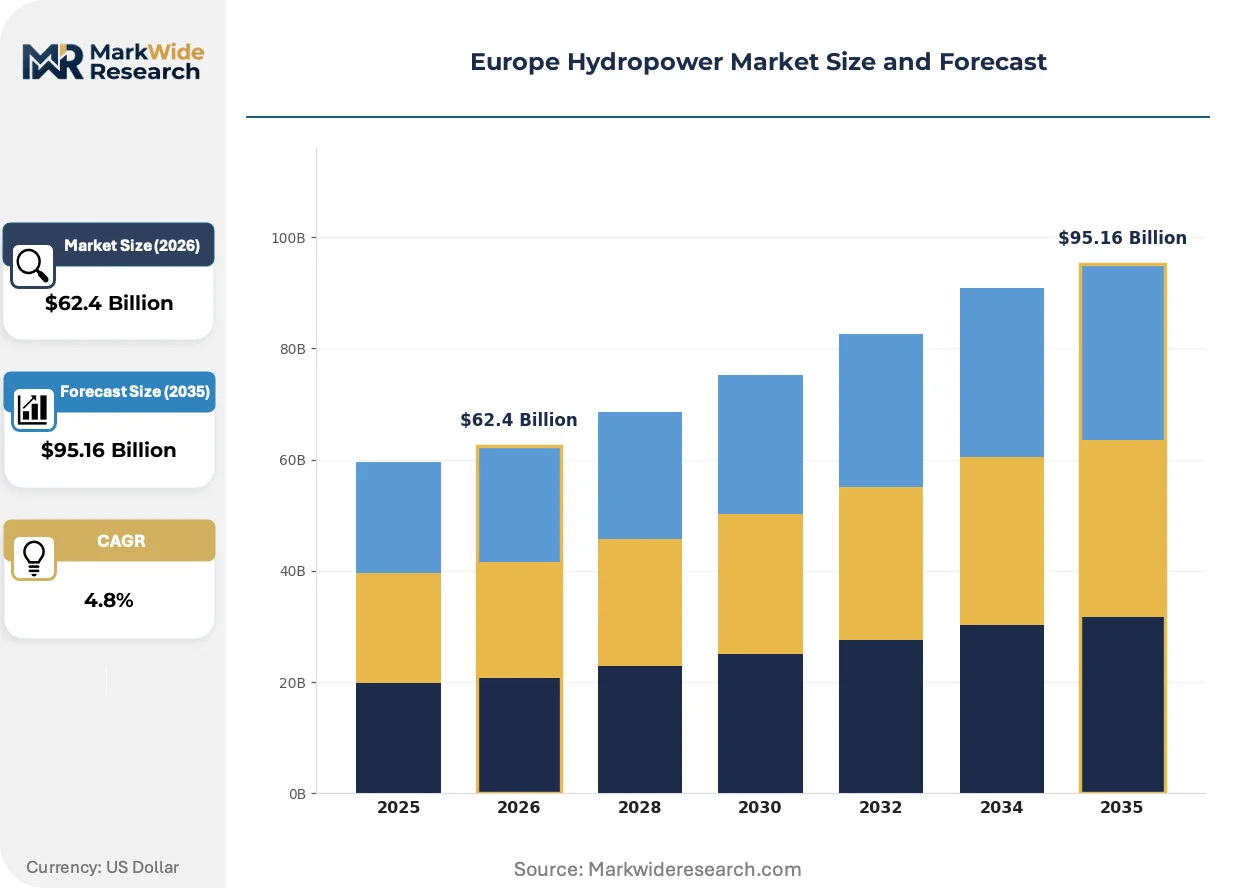
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electricity Generation, Pumped Storage, Irrigation, Flood Control Technology: Run-of-River, Reservoir, Small Hydropower, Micro Hydropower End User: Utilities, Industrial Sector, Residential Users, Agricultural Sector Capacity: Up to 1 MW, 1 MW – 10 MW, 10 MW – 100 MW, Over 100 MW |
| Companies Covered | Electricite de France SA, Andritz AG, PJSC RusHydro, Statkraft AS, Enel Green Power S.p.A., Voith Hydro, General Electric Company, Agder Energi SA, GE Vernova, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydropower Market Shifts & Advancements
Digitalization is penetrating every layer of hydropower asset management, from sediment monitoring in reservoirs to AI-driven dispatch optimization. These shifts are compressing operational decision cycles and redrawing competitive boundaries between equipment OEMs and software specialists.
Additive manufacturing is decomposing traditional casting supply chains for turbine components. Voith Hydro and Andritz AG now print stainless steel runner blades with complex internal cooling channels impossible to machine conventionally. Alpine utilities in Switzerland and Austria are adopting these parts for mid-life refurbishments, shrinking lead times from fourteen months to six and reducing spare parts inventory requirements by half.
The EU Green Deal's revised Renewable Energy Directive mandates streamlined permitting timelines for renewable infrastructure upgrades. Member states must now process hydropower modernization applications within twenty-four months or provide written justification for delays. German regulators have responded by pre-approving standardized turbine replacement designs, while French authorities still struggle with Water Framework Directive compliance overlays that extend reviews.
Utility procurement teams now unbundle electromechanical packages from civil works contracts, fragmenting what were historically turnkey awards. Nordic transmission operators and Alpine municipal utilities separately tender turbine supply, installation supervision, and balance-of-plant construction. This pattern is most pronounced in Norway and Austria, where Statkraft and Verbund have established dedicated engineering departments capable of integrating multi-vendor component sets.
Europe Hydropower Market Segmentation
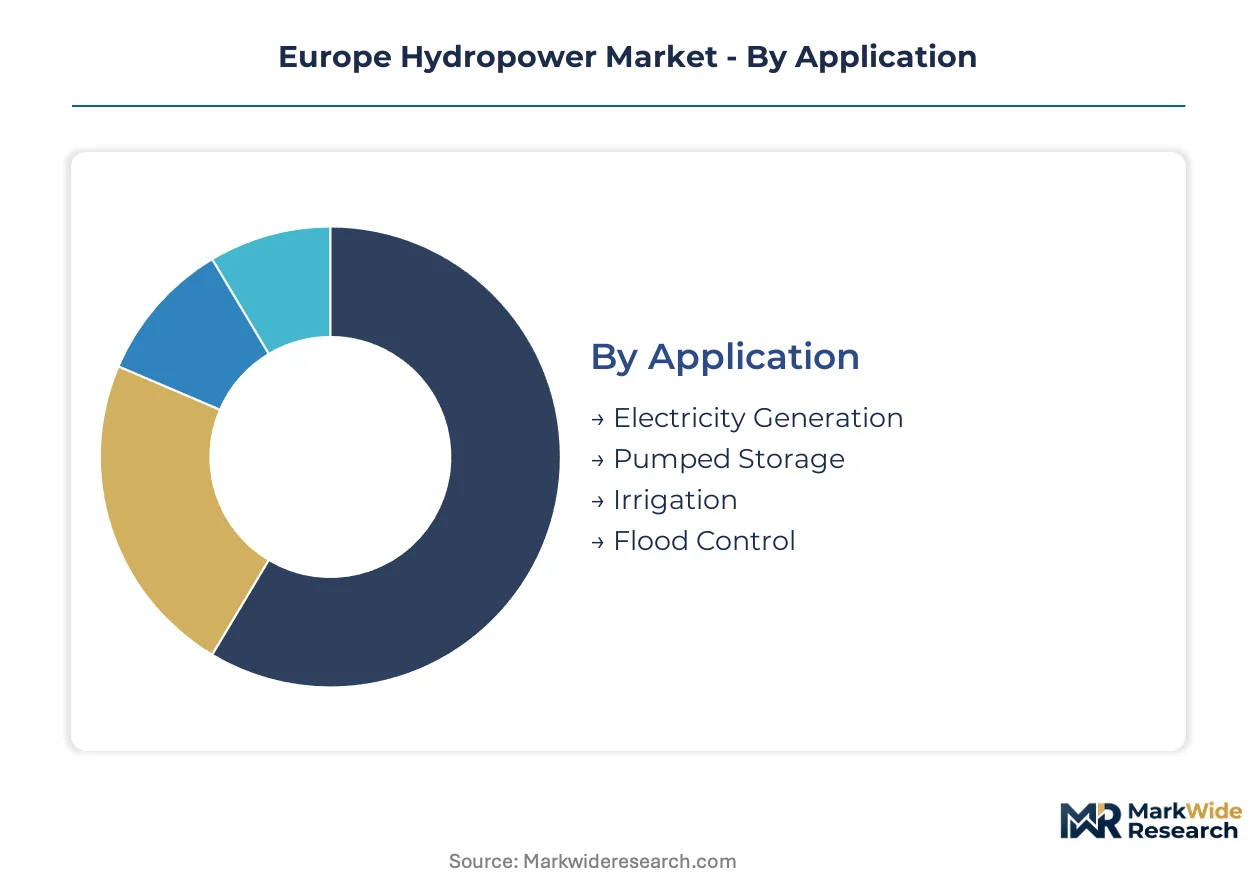
European hydropower segmentation reflects divergent investment timelines and regulatory exposure across project scales. Channel strategies vary sharply between large utilities procuring turnkey electromechanical packages and agricultural cooperatives sourcing sub-megawatt equipment through regional distributors.
Application:
Channel concentration tracks project scale, with pumped storage flowing through specialized engineering procurement and flood control projects routing through public infrastructure tenders.
- Electricity Generation:Baseload and peak-load power delivery from conventional reservoir and run-of-river installations. Demand clusters in Alpine corridor utilities seeking dispatchable renewable capacity to offset German and Spanish solar intermittency.
- Pumped Storage:Reversible turbine-motor units pump water to upper reservoirs during low-price periods and generate during peak demand. Norwegian and Swiss operators dominate this segment, leveraging steep topography and existing reservoir infrastructure to capture arbitrage from day-ahead electricity markets.
- Irrigation:Small-scale canal drops and agricultural water systems generate incidental power. Italian and Spanish agricultural cooperatives drive procurement through regional equipment distributors.
- Flood Control:Multi-purpose dams integrate generation with seasonal water management. French and Austrian river basin authorities control these procurements through public infrastructure tenders with extended environmental review timelines.
By volume, electricity generation leads. By growth pace, pumped storage is expanding most quickly.
Technology:
Cost tier differentiation separates mature large-reservoir designs from emerging digitalized small-scale systems competing on distributed deployment speed.
- Run-of-River:Diversion channels harness natural river flow without large impoundments, minimizing ecological footprint. Austrian and Swiss developers favor this technology for streamlined Water Framework Directive compliance and faster permitting than reservoir alternatives.
- Reservoir:Large-scale impoundments store seasonal water for scheduled generation and grid services. Alpine nations—Switzerland, Austria, Norway—concentrate existing capacity, with new development constrained by strict EU ecological flow mandates.
- Small Hydropower:Installations below ten megawatts serve distributed generation and rural electrification. Romanian and Bulgarian project pipelines remain active due to feed-in tariff remnants and simpler national licensing regimes.
- Micro Hydropower:Sub-100 kilowatt systems target off-grid residential and agricultural loads. Italian Alpine communities and Scottish Highlands deploy these through municipal energy cooperatives and rural development grants.
By installed base, reservoir technology dominates. By deployment velocity, run-of-river is gaining share fastest.
End User:
Customer type determines procurement sophistication, with utilities bundling long-term service contracts and residential users purchasing standardized packaged systems.
- Utilities:Vertically integrated power companies and municipal operators control grid-connected capacity. Statkraft, Verbund, and EDF procure multi-hundred-megawatt electromechanical packages with twenty-year maintenance agreements.
- Industrial Sector:Energy-intensive manufacturers—aluminum smelters, pulp mills, data centers—seek behind-the-meter hydropower for price hedging and carbon reduction targets. Nordic industrial clusters anchor this demand.
- Residential Users:Individual property owners and housing cooperatives install micro-hydro on Alpine streams and hillside watercourses. Swiss cantonal banks and Austrian regional lenders provide specialized green construction financing.
- Agricultural Sector:Farms and irrigation districts exploit elevation changes in water distribution networks. Spanish Extremadura and Italian Piedmont concentrate deployment through agricultural development agency subsidies.
By capital deployed, utilities lead. By project count growth, agricultural sector installations are climbing the fastest.
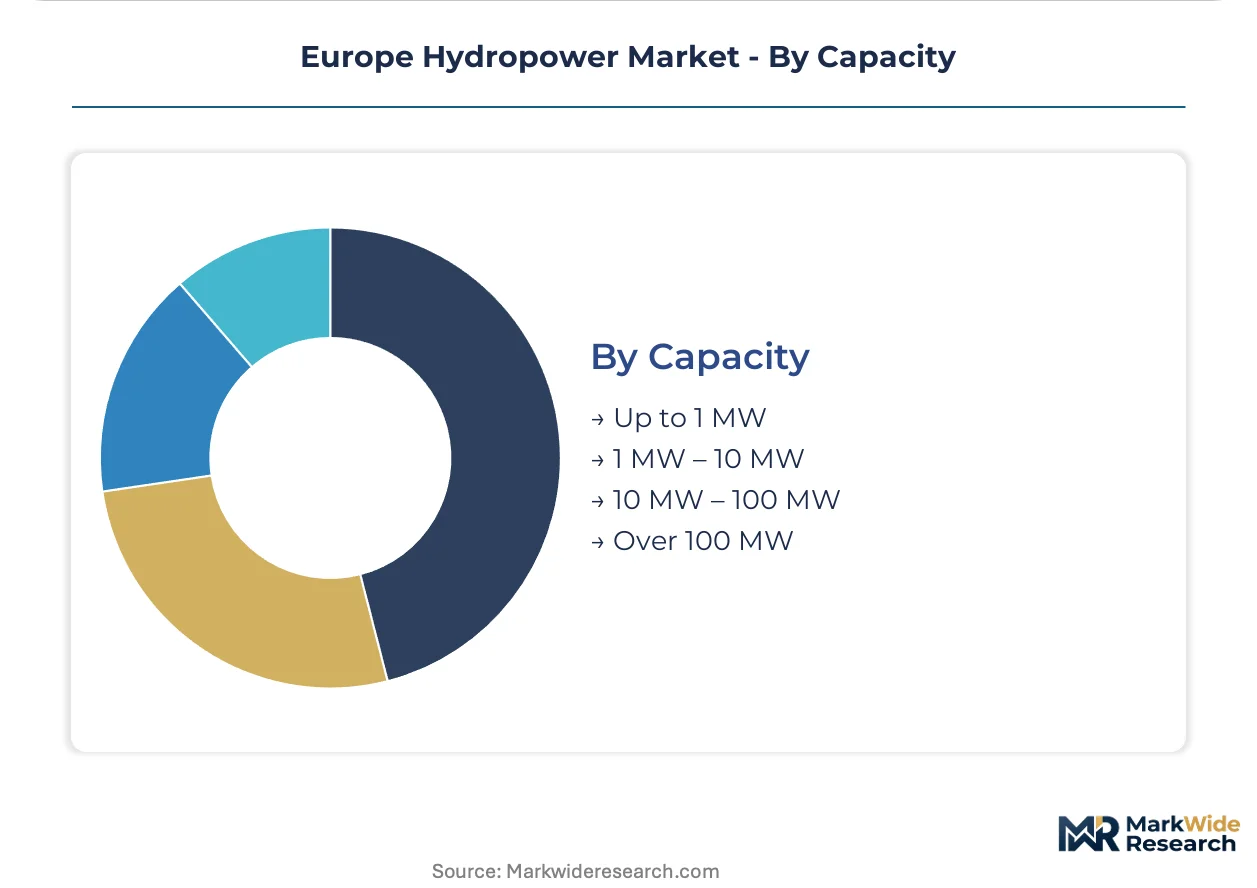
Capacity:
Supply concentration intensifies above ten megawatts, where European OEMs anchor turbine manufacturing, while sub-megawatt segments fragment across Asian and regional suppliers.
- Up to 1 MW:Standardized turbine-generator sets from Czech, Slovenian, and Chinese manufacturers serve distributed applications. Romanian and Bulgarian distributors stock these for rapid rural electrification deployment.
- 1 MW – 10 MW:Mid-scale projects balance customization with manufacturing scale. Austrian and Italian regional utilities favor this bracket for run-of-river modernization without triggering full environmental impact assessments.
- 10 MW – 100 MW:Significant infrastructure requiring bespoke turbine engineering and grid integration studies. Alpine municipal utilities and Nordic independent power producers concentrate procurement in this band.
- Over 100 MW:Strategic national assets with multi-decade development horizons. Swiss pumped storage expansions and Norwegian reservoir upgrades constitute the primary European project pipeline, with Voith Hydro and Andritz AG competing for electromechanical packages.
By cumulative installed capacity, over 100 MW installations lead. By annual additions, the 1 MW – 10 MW bracket shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian pumped storage operators command premium arbitrage revenues from German day-ahead markets, while Romanian run-of-river developers compete on feed-in tariff remnants at thinner margins. This pricing-power asymmetry concentrates investment flows toward Alpine and Nordic topography while leaving Southeast European projects dependent on national subsidy regimes.
Norway
Statkraft AS dominates Nordic pumped storage development, leveraging steep fjord topography for reversible turbine-motor installations. The Norwegian Water Resources and Energy Directorate maintains streamlined licensing for capacity upgrades without new reservoir footprints. Hardanger and Sognefjord regions anchor active refurbishment pipelines as grid operators procure frequency containment reserves.
Switzerland
Alpine utilities exploit existing reservoir infrastructure for pumped storage arbitrage against German and French peak demand. The revised Renewable Energy Directive mandates twenty-four-month permitting timelines for turbine modernizations. Gotthard and Grimsel regions concentrate electromechanical package procurements from Voith Hydro and Andritz AG.
Germany
Bavarian and Baden-Württemberg river basins drive run-of-river modernization as operators replace aging Francis turbines. German regulators pre-approve standardized turbine replacement designs under EU Green Deal streamlining mandates. Alpine foothill municipalities unbundle electromechanical packages from civil works contracts.
France
EDF manages reservoir and run-of-river assets across Rhône-Alpes and Auvergne regions under strict Water Framework Directive ecological flow constraints. French authorities struggle with compliance overlays that extend environmental reviews three to five years beyond pre-2010 baselines. Massif Central pumped storage proposals face prolonged permitting timelines.
Romania
Carpathian run-of-river installations below ten megawatts attract local developers navigating simpler national licensing regimes outside EU directive harmonization. Feed-in tariff remnants support distributed generation in Transylvania and Moldova regions. Bulgarian and Czech equipment distributors stock standardized turbine-generator sets for rapid rural electrification deployment.
Europe Hydropower Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with full-service OEMs commanding premium electromechanical packages while regional fabricators compete on standardized sub-megawatt equipment. The vendor base stratifies across three tiers: century-heritage turbine manufacturers, integrated electromechanical specialists, and niche digital control providers. Strategic moves concentrate on turbine refurbishment contracting and additive manufacturing adoption for runner blade production.
Among Alpine-based heritage manufacturers, Voith Hydro and Andritz AG exemplify the full-service OEM archetype through century-long turbine manufacturing legacies. Statkraft AS represents the vertically integrated utility operator model, combining asset ownership with in-house engineering capabilities. General Electric Company and GE Vernova occupy positions as diversified industrial conglomerates with hydropower divisions. Electricite de France SA anchors the state-integrated utility tier, while Enel Green Power S.p.A. and Agder Energi SA exemplify regional renewable-focused operators. PJSC RusHydro sits within the geographically concentrated state-owned segment.
| Leading Market Players |
|---|
| Electricite de France SA |
| Andritz AG |
| PJSC RusHydro |
| Statkraft AS |
| Enel Green Power S.p.A. |
| Voith Hydro |
| General Electric Company |
| Agder Energi SA |
| GE Vernova |
| Others |
Supply & Pricing Matrix
CE marking and EU Machinery Directive compliance gates both turbine component qualification and price differentiation across European hydropower procurement. OEMs bearing full certification overhead capture premium electromechanical packages, while uncertified regional fabricators compete on standardized sub-megawatt equipment at compressed margins.
Pricing Analysis
Configured-to-order pricing for bespoke Francis and Kaplan turbine runners commands spreads exceeding forty percent above standardized catalog units. Project-based contracting dominates, with price differentiation driven by certification tier and after-sales service bundling. Cost compression in the sub-ten-megawatt bracket intensifies as Asian manufacturers penetrate Romanian and Bulgarian distributor networks. Agricultural cooperatives exhibit highest price sensitivity, while Alpine municipal utilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strait of Hormuz transit risk for copper concentrate shipments from Chile and Peru elevates raw material security planning among European turbine manufacturers. Supply concentrates in Germany, Austria, and China for precision-machined runners, generator windings, and digital control systems. The chain draws from specialty steel foundries in the Czech Republic and Slovenia, with single-source vulnerability in large forging capacity for pump-turbine components. Distribution runs through EPC contractors for utility-scale projects and regional equipment distributors for agricultural and residential micro-hydro deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European hydropower sits in early-cycle expansion as EU Green Deal streamlining mandates compress refurbishment timelines for aging Alpine infrastructure. Penetration of predictive maintenance platforms in sub-ten-megawatt installations remains below fifteen percent, creating runway for digitization vendors.
For Market Incumbents: Compound service contract attach rates by embedding IoT monitoring into legacy turbine rehabilitations. Battery storage and green hydrogen projects threaten ancillary service revenue pools in Nordic markets; defend through backward integration into digital control system development. Prioritize capacity additions in Swiss pumped storage corridors where arbitrage margins remain widest. For New Entrants and Emerging Players: Lead with predictive maintenance software targeting Romanian and Bulgarian run-of-river fleets underserved by incumbent OEM service networks. Small hydropower digitization represents the most penetrable white space, with agricultural cooperatives in Italy and Spain offering rapid reference-building opportunities. Pursue channel partnerships with regional equipment distributors rather than direct utility sales cycles. For Investors and Strategic Acquirers: EU Electricity Market Design reform reshapes the acquisition landscape by clarifying capacity remuneration mechanisms for storage assets. Five-to-ten-year viability favors vertically integrated operators with captive turbine refurbishment capabilities and Alpine reservoir access. Monitor German and French frequency containment reserve procurement volumes as the signal for pumped storage asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Turbine Refurbishment Contracting | Voith Hydro and Andritz AG anchor large-scale rehabilitation pipelines across German and Austrian river basins. |
| Additive Manufacturing Adoption | Stainless steel runner blade printing shrinks lead times from fourteen months to six for Alpine utilities. |
| Cross-Border Ancillary Services | EMA grid code coordination enables Norwegian pumped storage operators to bid into German frequency regulation markets. |
| Small Hydropower Digitization | IoT-enabled monitoring platforms target underserved sub-ten-megawatt installations in Romania and Bulgaria. |
| Streamlined Permitting Navigation | EU Green Deal twenty-four-month mandates favor developers with pre-approved turbine replacement design portfolios. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interview rounds. Secondary validation drew from IEA hydropower outlooks, FERC-style regulatory filings, EU project development databases, and national energy agency statistics. Bottom-up installation forecasts triangulated against top-down renewable capacity targets across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework modeled segmentation across technology type, capacity tier, end-user category, and regional regulatory cluster. CAGRs derived from installation run-rate analysis and equipment procurement pipeline tracking, with commodity price indices and permitting timeline data feeding scenario variations.
The analysis sits within stated boundaries; outcomes outside EU Green Deal implementation timelines or Water Framework Directive enforcement intensity would require recalibration. Forecasts reflect documented assumptions about metals price stability and cross-border grid code harmonization. Practitioners should keep alternative scenarios live as battery storage cost curves and green hydrogen project pipelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Floating Power Plant Market