
 India Battery Cell Market | 2026-2036
India Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery Cell Market Foresight
Electric vehicle fleet operators across state transport undertakings is expanding as a buyer concentration force, pulling procurement volumes away from fragmented aftermarket channels. Exide Industries leverages its lead-acid heritage while building lithium-ion capacity for automotive OEMs. Amara Raja Energy & Mobility anchors its position through R&D partnerships with foreign technology licensors. Panasonic Energy India dominates the premium cylindrical cell segment for consumer electronics and power tool applications.
India battery cells are electrochemical devices converting stored chemical energy into electrical energy through redox reactions, with lithium-ion variants achieving energy densities of 250-300 Wh/kg using nickel-manganese-cobalt cathode formulations. These cells power electric mobility, grid stabilization, and portable electronics by delivering reversible charge-discharge cycles across thousands of operations. Lithium-ion chemistry leads value generation due to its superior energy density and declining cost curve, while lead-acid retains volume in automotive starting-lighting-ignition applications where cost sensitivity prevails. Solid-state technology represents the fastest-growing innovation pathway as developers target enhanced safety profiles and higher voltage stability for premium electric vehicle platforms.
BIS certification mandates and the PLI scheme administered by the Ministry of Heavy Industries shape product standards and capital allocation across domestic manufacturing. CDSCO oversight applies where battery cells interface with medical devices, adding compliance layers for specialized suppliers. Stakeholders must monitor how BIS evolves its testing protocols for advanced chemistry cells as domestic production scales, since standards divergence from IEC benchmarks would force dual certification investments for export-oriented facilities.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is redirecting capital toward domestic gigafactory construction, compressing the timeline for import substitution and reshaping competitive positioning between established lead-acid incumbents and lithium-ion entrants.
Growth Catalysts
- PLI scheme disbursements:The Ministry of Heavy Industries' production-linked incentive framework is accelerating capital deployment into Dholera Special Investment Region gigafactories. Domestic cell output expands as beneficiaries commit to capacity milestones.
- State transport electrification:Maharashtra and Karnataka state transport undertakings are expanding electric bus fleets, pulling procurement volumes toward lithium-ion pack suppliers. Fleet standardization creates predictable demand baselines for cell manufacturers.
- Nickel-manganese-cobalt formulations:Advanced cathode chemistries achieving 250-300 Wh/kg energy densities are enabling longer-range electric two-wheelers. Automotive OEMs specify these cells for premium vehicle platforms.
Market Restraints
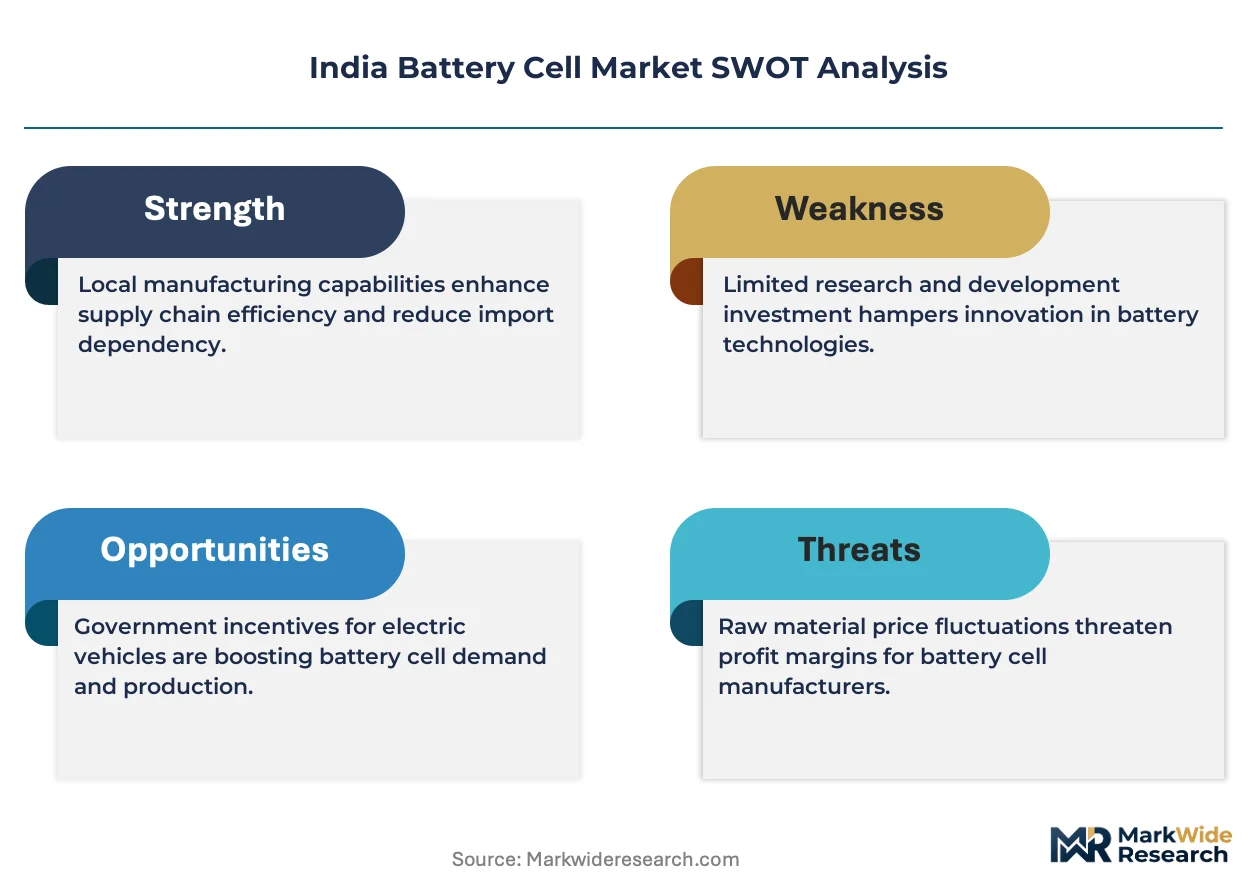
- Lithium carbonate volatility:Raw material input costs swing with Chilean and Australian spodumene concentrate pricing, compressing margin visibility for cell producers. Domestic manufacturers lack upstream mining positions.
- Import concentration:Active materials and separator films concentrate in Chinese and South Korean supplier bases. Geopolitical friction exposes Indian assemblers to supply disruption risks.
- Lead-acid substitution ceiling:Automotive starting-lighting-ignition applications retain cost-sensitive demand where lithium-ion premiums face resistance. Price floors limit addressable market expansion.
Strategic Opportunities
- Gujarat cluster economies:Dholera Special Investment Region infrastructure supports co-located cathode active material plants and cell production. Logistics costs compress as suppliers agglomerate.
- Grid-scale storage integration:Solar-wind hybrid projects with four-hour battery duration requirements create new demand pools. State distribution companies tender for stabilization services.
- BIS certification harmonization:Evolving domestic testing protocols for advanced chemistry cells may align with IEC benchmarks, reducing dual certification burdens for export-oriented facilities.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and manufacturing process engineering expertise concentrates in foreign technology licensors. Domestic workforce development lags capacity expansion timelines.
- Gigafactory capex intensity:Dry electrode coating and formation equipment requires billion-rupee commitments before revenue generation. Financing structures strain balance sheets.
- CDSCO medical device interface compliance:Battery cells powering implantable or portable diagnostic equipment face additional oversight layers. Certification timelines extend commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery Cell Market |
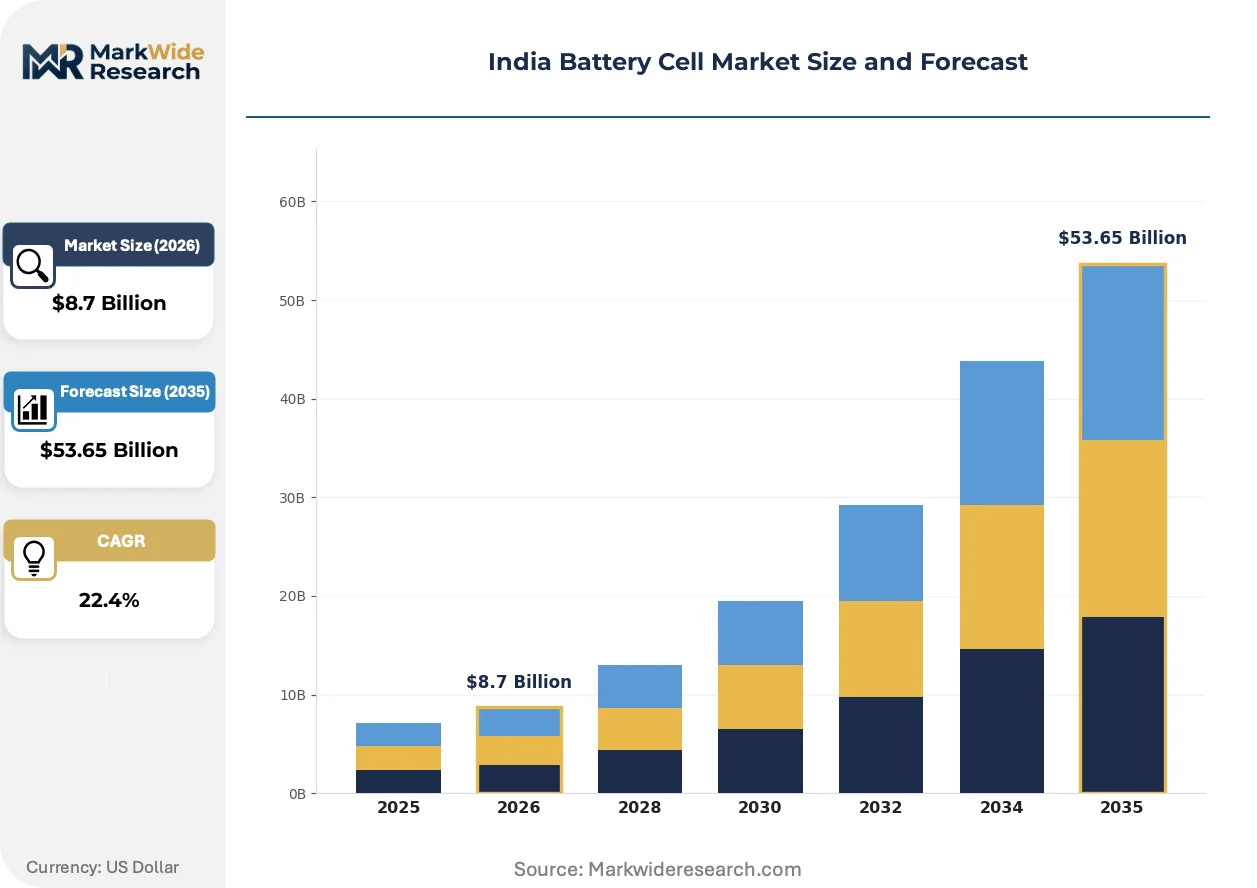
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Battery End User: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Applications Technology: Solid-state, Aqueous Battery, Thin Film, Lithium Polymer Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Exide Industries, Amara Raja Energy & Mobility, Eastman Auto & Power, Su-Kam Power Systems, Artek Energy, Bharat Electronics Limited, Luminous Power Technologies, Panasonic Energy India, Maxvolt Energy Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery Cell Market Shifts & Advancements
Solid-state electrolyte development and silicon-anode integration are reshaping performance benchmarks for premium electric vehicle platforms. Manufacturing process innovation and regulatory alignment are compressing commercialization timelines.
Solid-state lithium-metal cells with ceramic or sulfide electrolyte separators are electrifying safety and energy density expectations for next-generation automotive platforms. Mahindra and Tata Motors' premium electric SUV programs are evaluating prototype supply agreements. This technology is electrifying the competitive gap between incumbent liquid-electrolyte producers and venture-backed solid-state developers.
BIS is evolving testing protocols for advanced chemistry cells as domestic production scales, with draft standards under consultation for thermal runaway propagation and cycle life verification. Industrial consequence includes forced dual certification investments if divergence from IEC 62660 persists. Export-oriented facilities in Gujarat are responding by pre-emptively adopting IEC benchmarks alongside BIS compliance.
Fleet operators at state transport undertakings are consolidating procurement into multi-year supply agreements with annual volume commitments, displacing spot-market purchasing. Fragmented aftermarket channels lose share to direct OEM-fleet contracting. This concentration is most visible in Maharashtra and Karnataka where electric bus deployment targets exceed ten thousand units.
India Battery Cell Market Segmentation
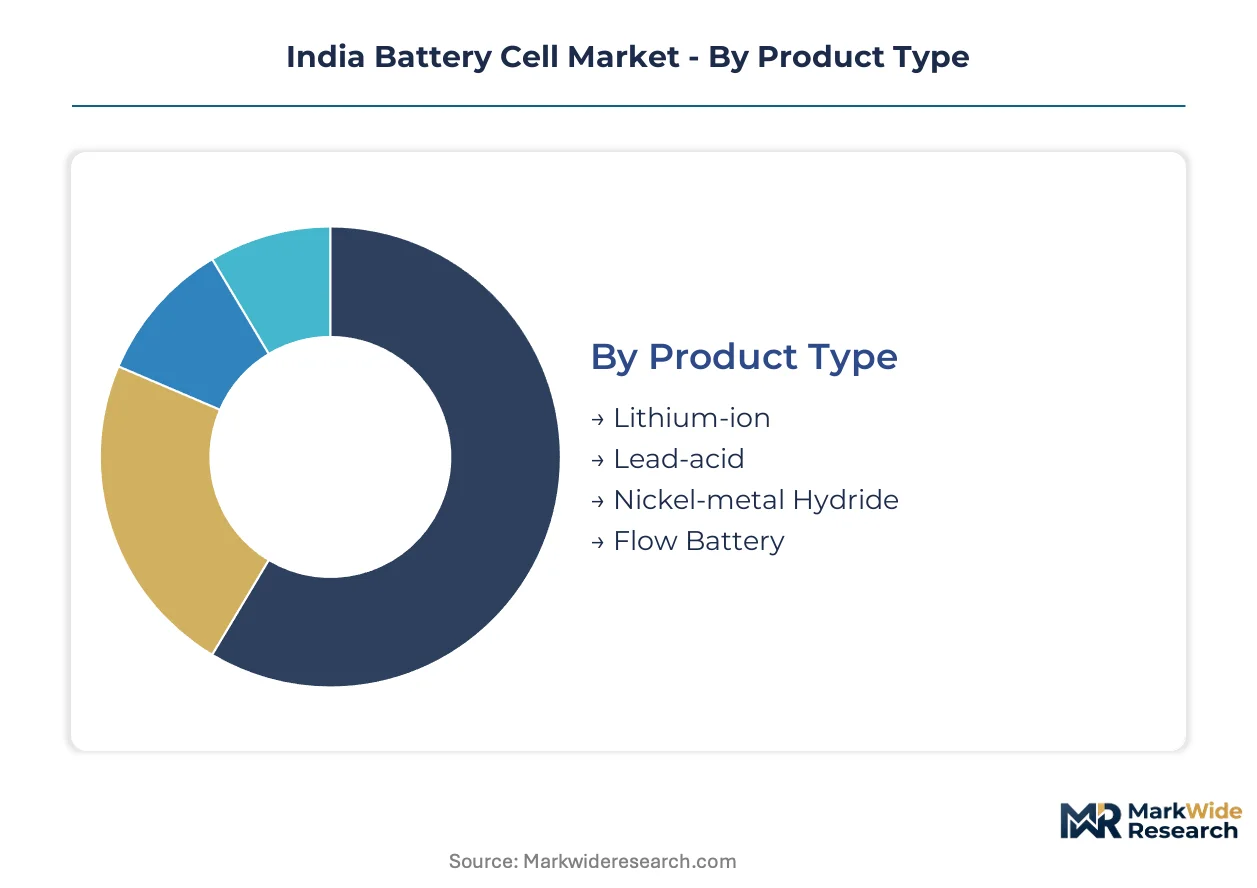
Segmentation reveals how battery cell demand fragments across incompatible performance requirements and procurement economics. Chemistry selection, end-use duty cycles, and channel access create distinct competitive arenas with divergent margin structures.
Product Type:
Cost tier separates mass-market automotive applications from premium mobility and stationary storage deployments.
- Lithium-ion:Nickel-manganese-cobalt cathode formulations achieve 250-300 Wh/kg energy densities for electric two-wheeler and passenger vehicle platforms. Maharashtra and Karnataka state transport undertakings are pulling procurement volumes toward lithium-ion pack suppliers as fleet electrification accelerates.
- Lead-acid:Flooded and valve-regulated designs dominate automotive starting-lighting-ignition functions where cost sensitivity prevails over energy density. Exide Industries leverages its manufacturing heritage to defend volume in this replacement-driven segment despite lithium-ion encroachment.
- Nickel-metal Hydride:Mature chemistry retains position in hybrid electric vehicle auxiliary power units and select industrial backup applications. Toyota Kirloskar Motor sources these cells for domestic hybrid assembly.
- Flow Battery:Vanadium redox systems address four-hour grid-scale storage durations for solar-wind hybrid projects tendered by state distribution companies. Gujarat's Dholera cluster is evaluating dedicated electrolyte processing facilities.
Volume sits with Lead-acid; growth tilts toward Lithium-ion.
End User:
Application duty cycles dictate cell specification, with automotive platforms demanding calendar life and stationary systems prioritizing cycle stability.
- Electric Vehicles:Two-wheeler OEMs specify cylindrical and prismatic formats for integration into chassis-integrated pack architectures. Tata Motors and Mahindra Electric are expanding domestic cell offtake agreements for passenger and commercial platforms.
- Consumer Electronics:Premium cylindrical cells from Panasonic Energy India power smartphones, laptops, and power tools requiring compact form factors. BIS certification mandates shape product standards for this import-competing segment.
- Energy Storage Systems:Grid stabilization and renewable firming applications create demand for containerized battery installations. State distribution companies in Tamil Nadu and Rajasthan are tendering for four-hour duration systems.
- Industrial Applications:Forklift motive power, telecom backup, and uninterrupted power supply functions specify cells for float service and deep discharge tolerance. Amara Raja Energy & Mobility anchors position through R&D partnerships with foreign technology licensors for this fragmented channel.
Procurement concentrates in Electric Vehicles; margin expansion favors Energy Storage Systems.
Technology:
Manufacturing maturity separates commercially deployable formats from pre-commercial architectures requiring capital-intensive scale-up.
- Solid-state:Ceramic and sulfide electrolyte separators eliminate thermal runaway risks while enabling lithium-metal anodes for premium SUV platforms. Mahindra and Tata Motors are evaluating prototype supply agreements as the technology climbs the fastest toward automotive qualification.
- Lithium Polymer:Pouch cell formats with gel electrolytes serve wearable electronics and slim-profile consumer devices. Panasonic Energy India dominates this premium segment for import-substituting domestic assembly.
- Aqueous Battery:Water-based electrolyte systems target cost-sensitive grid storage where energy density penalties are acceptable. IIT-Madras spin-offs are piloting zinc-ion variants for rural microgrid applications.
- Thin Film:Micro-scale solid-state deposits power medical implants and sensor networks requiring extreme form factor miniaturization. CDSCO oversight applies where these cells interface with implantable diagnostic equipment.
Commercial traction rests with Lithium Polymer; technology investment flows toward Solid-state.
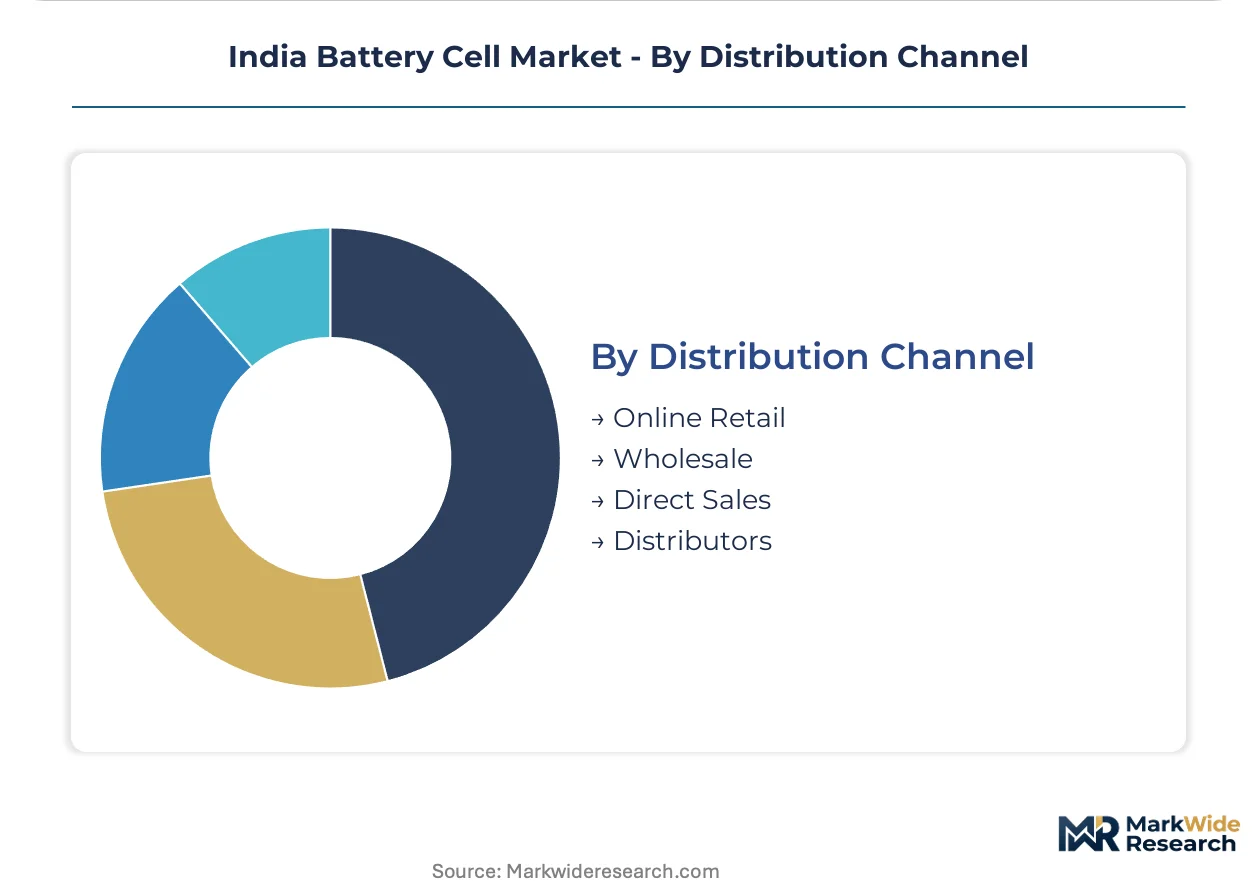
Distribution Channel:
Customer scale and specification complexity determine whether direct contracting or intermediary networks deliver optimal economics.
- Direct Sales:Automotive OEMs and fleet operators negotiate multi-year offtake agreements with annual volume commitments. State transport undertakings in Maharashtra and Karnataka are consolidating procurement through this channel.
- Distributors:Regional stockists serve aftermarket replacement demand for lead-acid automotive batteries and industrial applications. Exide Industries maintains extensive dealer networks for rural market penetration.
- Wholesale:Volume resellers aggregate demand from smaller industrial accounts and institutional buyers. Gujarat's Dholera cluster infrastructure supports co-located distribution hubs for export-oriented facilities.
- Online Retail:E-commerce platforms capture consumer electronics replacement cells and DIY enthusiast segments. BIS-certified products compete with uncertified imports through price-transparent digital marketplaces.
Revenue stability concentrates in Direct Sales; channel development prioritizes Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium spodumene deposits in Karnataka's Mandya district anchor India's upstream positioning, though active material processing concentrates in Gujarat's chemical corridor. State-level policy variation creates divergent investment climates across manufacturing clusters.
Gujarat
Dholera Special Investment Region hosts the country's densest cell production clustering, with cathode active material plants co-locating beside gigafactory investments. The state's single-window clearance mechanism compresses project approval timelines under the PLI scheme administered by the Ministry of Heavy Industries. Mundra and Hazira ports enable export-oriented facilities to bypass inland logistics bottlenecks.
Maharashtra
Maharashtra State Road Transport Corporation's electric bus procurement program exceeds ten thousand units, generating predictable offtake demand for lithium-ion pack suppliers. Mumbai Metropolitan Region's automotive OEM concentration drives specification-setting power for cell formats. Chakan and Talegaon industrial belts are attracting formation and testing facilities to serve western India demand.
Karnataka
Bengaluru's electronics manufacturing ecosystem consumes premium cylindrical cells for consumer devices and power tools, with BIS certification mandates shaping import-substitution dynamics. The state's electric vehicle policy offers capital subsidies for cell manufacturing investments exceeding specified capacity thresholds. Hosur and Bidadi industrial areas are emerging as pack assembly hubs for Tamil Nadu and Kerala markets.
Tamil Nadu
Tamil Nadu Generation and Distribution Corporation tenders for four-hour grid-scale battery storage systems, creating demand pools distinct from automotive applications. Sriperumbudur and Oragadam industrial corridors leverage automotive OEM proximity for logistics optimization. The state's electronics manufacturing policy extends to cell component fabrication, targeting separator film and electrolyte salt investments.
Telangana
Hyderabad's pharmaceutical and medical device cluster generates specialized demand for cells interfacing with implantable equipment under CDSCO oversight. The state's life sciences corridor offers dedicated zones for battery suppliers serving diagnostic and therapeutic device manufacturers. Genome Valley's precision manufacturing ecosystem supports thin-film and micro-cell fabrication for sensor networks.
India Battery Cell Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue advanced chemistry specialization and gigafactory scale. The market exhibits tiered concentration with heritage lead-acid manufacturers defending replacement-driven volumes while lithium-ion specialists capture growth segments. Three archetypes dominate: diversified industrial conglomerates with electrochemical heritage, technology licensors partnering domestic assemblers, and venture-backed solid-state developers targeting premium automotive qualification. Capacity expansion and strategic technology licensing constitute the dominant competitive vectors, with PLI scheme disbursement timelines determining first-mover positioning.
Among heritage-anchored industrial groups, Exide Industries and Amara Raja Energy & Mobility occupy positions representing the lead-acid-to-lithium transition archetype. Panasonic Energy India exemplifies the foreign technology licensor model serving premium consumer electronics and power tool segments. Bharat Electronics Limited represents the public-sector defense-industrial complex entry point into specialized cell applications.
| Leading Market Players |
|---|
| Exide Industries |
| Amara Raja Energy & Mobility |
| Eastman Auto & Power |
| Su-Kam Power Systems |
| Artek Energy |
| Bharat Electronics Limited |
| Luminous Power Technologies |
| Panasonic Energy India |
| Maxvolt Energy Industries |
| Others |
Supply & Pricing Matrix
Electrochemical engineering talent scarcity in Gujarat's Dholera cluster widens labor-cost spreads between premium lithium-ion cell manufacturers and commodity lead-acid assemblers, compressing margin structures for players lacking PLI scheme qualification.
Pricing Analysis
Volume concentrates in lead-acid automotive starting-lighting-ignition cells where price competition is fierce, while lithium-ion cylindrical formats for premium consumer electronics command wider spreads. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified domestic production from uncertified imports and grey-market cells. Cost compression in the economy tier is intensifying because of lithium carbonate volatility and Chinese import competition. State transport undertakings exhibit highest price sensitivity through consolidated fleet procurement, whereas medical device OEMs under CDSCO oversight accept premiums for reliability assurance.
Supply Chain Analysis
Reverse-logistics flows for spent lead-acid batteries anchor Exide Industries' closed-loop recycling economics, with secondary lead recovery feeding domestic active material production. Cathode precursor concentrates in Chinese and South Korean supplier bases, while separator films and electrolyte salts draw from Japanese and Taiwanese manufacturers. Single-source vulnerability for lithium spodumene concentrate exposes Indian assemblers to Australian and Chilean export restrictions. Distribution runs through direct OEM contracting for automotive volumes and regional distributor networks for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification mandates and PLI scheme compliance costs erect a formidable barrier-to-entry moat, advantaging capitalized incumbents who can absorb dual-standard testing investments while marginalizing underfunded competitors.
For Market Incumbents: Anticipate lithium-ion substitution pressure by accelerating backward integration into cathode active material production within Gujarat's Dholera cluster. Secure multi-year offtake agreements with Maharashtra and Karnataka state transport undertakings before fleet procurement consolidates further. Defend lead-acid volume through dealer network lock-in for rural automotive replacement demand. For New Entrants and Emerging Players: Capture white-space in grid-scale energy storage systems tendered by Tamil Nadu and Rajasthan state distribution companies, where four-hour duration specifications favor new chemistry suppliers. Target medical device cell applications under CDSCO oversight as the most penetrable premium segment. Pursue technology licensing partnerships with foreign solid-state developers to bypass electrochemical engineering talent scarcity. For Investors and Strategic Acquirers: Re-rating potential sits with PLI scheme beneficiaries possessing secured lithium carbonate supply agreements given raw material cost volatility. Long-term viability favors players with demonstrated BIS-IEC dual certification capability and Dholera cluster manufacturing presence. Monitor PLI disbursement milestone achievement as the critical signal for capacity execution credibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Backward Integration | Gujarat chemical corridor proximity reduces logistics costs for NMC precursor production. |
| BIS-IEC Dual Certification Investment | Export-oriented facilities avoid forced retesting for European and ASEAN market access. |
| State Transport Fleet Direct Contracting | Maharashtra and Karnataka multi-year agreements displace fragmented aftermarket channels. |
| Solid-State Prototype Supply Agreements | Mahindra and Tata Motors premium SUV programs evaluate next-generation cell qualification. |
| Medical Device CDSCO Compliance Pathway | Hyderabad's pharmaceutical cluster generates specialized demand for implantable power sources. |
Research Methodology
Independent corroboration across cell manufacturing executives, PLI scheme administrators, and state transport procurement officers underwrites the qualitative findings. Primary fieldwork engaged gigafactory project developers in Gujarat, cathode material suppliers, and BIS certification auditors. Secondary validation drew from Ministry of Heavy Industries disbursement records, customs import data for lithium compounds, and CDSCO medical device filings. Bottom-up capacity build-up estimates triangulated against top-down demand projections from electric vehicle deployment targets.
Comparable-period anchoring to historical PLI scheme commitment timelines established the forecast window's baseline trajectory. The analytical framework segmented across chemistry type, end-use application, technology maturity, and distribution channel throughout the projection horizon. CAGRs were derived from installed capacity ramp rates and fleet electrification procurement schedules. Modeling incorporated lithium carbonate price elasticity, BIS protocol evolution assumptions, and state-level subsidy disbursement pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state technology commercialization timelines and Chinese export control policy shifts. Forecasts reflect documented assumptions regarding PLI beneficiary execution and raw material supply diversification. Practitioners should monitor BIS testing protocol draft releases and Karnataka lithium spodumene project development milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Portable Battery Station Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Low Temperature Battery Market
Batteries
Battery Maintainer Market
Batteries
Battery Pack Balancer Market
Batteries
North America Consumer Battery Market
Batteries
Portable Battery Market
Batteries
South America Consumer Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Breathing Battery Market
Batteries
Electric Battery Market
Batteries
Submarine Batteries Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Wireless Power Bank Market
Batteries
Micro Battery Market