
 Global Turbines Market | 2026-2036
Global Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Turbines Market Intelligence
China's extensive build-out of both renewable and gas-fired power capacity is reconfiguring the supply chain for large-frame turbines. GE Vernova leverages its advanced gas turbine technology to capture contracts for flexible power generation. Siemens Energy competes across both wind and combined cycle gas turbine segments, offering integrated power plant solutions. Mitsubishi Heavy Industries sustains its market position through a focus on high-efficiency industrial and utility-scale steam turbines.
A turbine is a rotary mechanical device that extracts energy from a fluid flow, using a rotor with precisely engineered blades to produce useful work. Its primary industrial purpose is driving generators for electricity production or providing mechanical drive for propulsion systems. Wind turbines represent the fastest-growing product segment due to global decarbonization mandates. Gas turbines, especially in combined cycle plants, are essential for grid stability and dominate the power generation application.
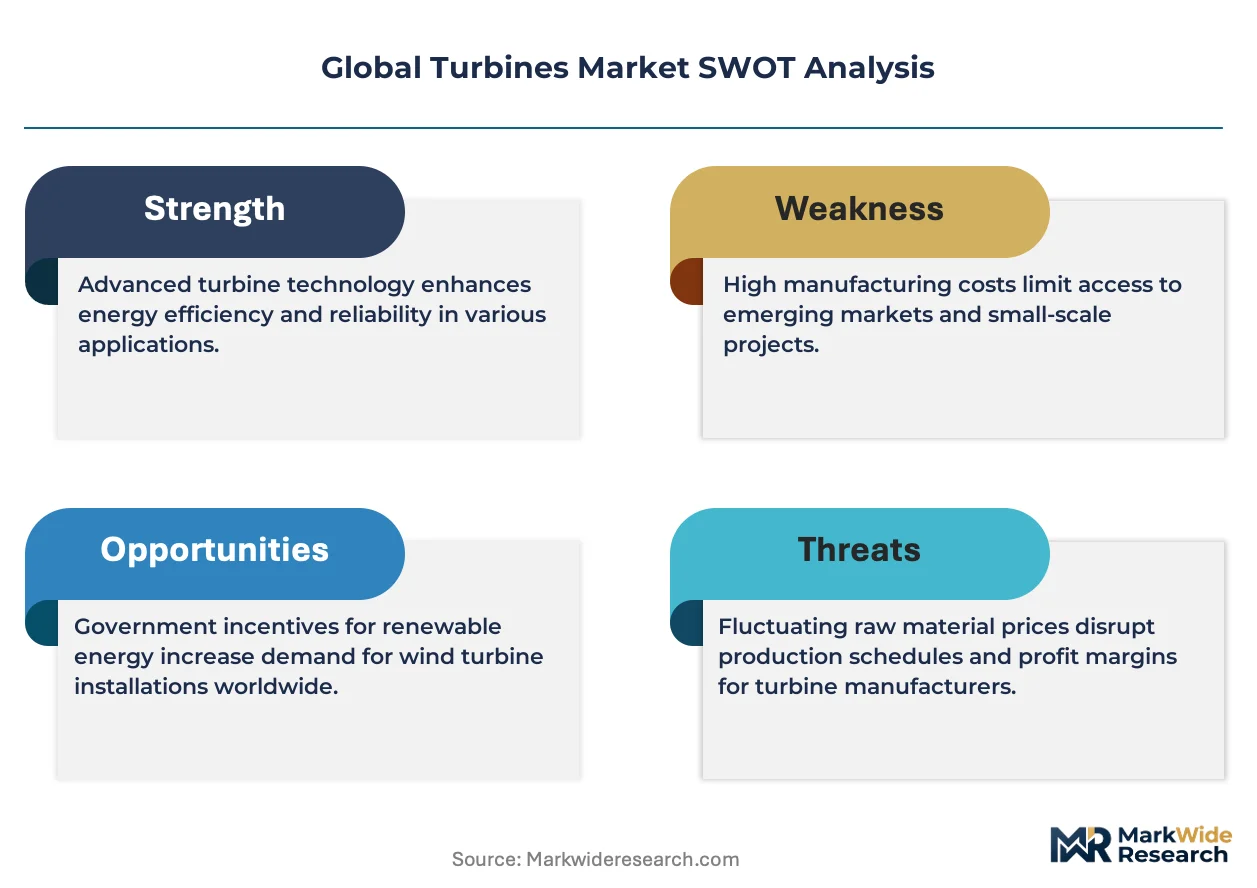
Regulatory frameworks fundamentally shape market direction, with the US EPA's emissions standards influencing gas turbine designs. The EU Green Deal and China's dual carbon goals directly incentivize investment in wind and hydro turbine projects. Navigating these divergent regional energy policies and their impact on technology selection is a central strategic challenge for all equipment manufacturers.
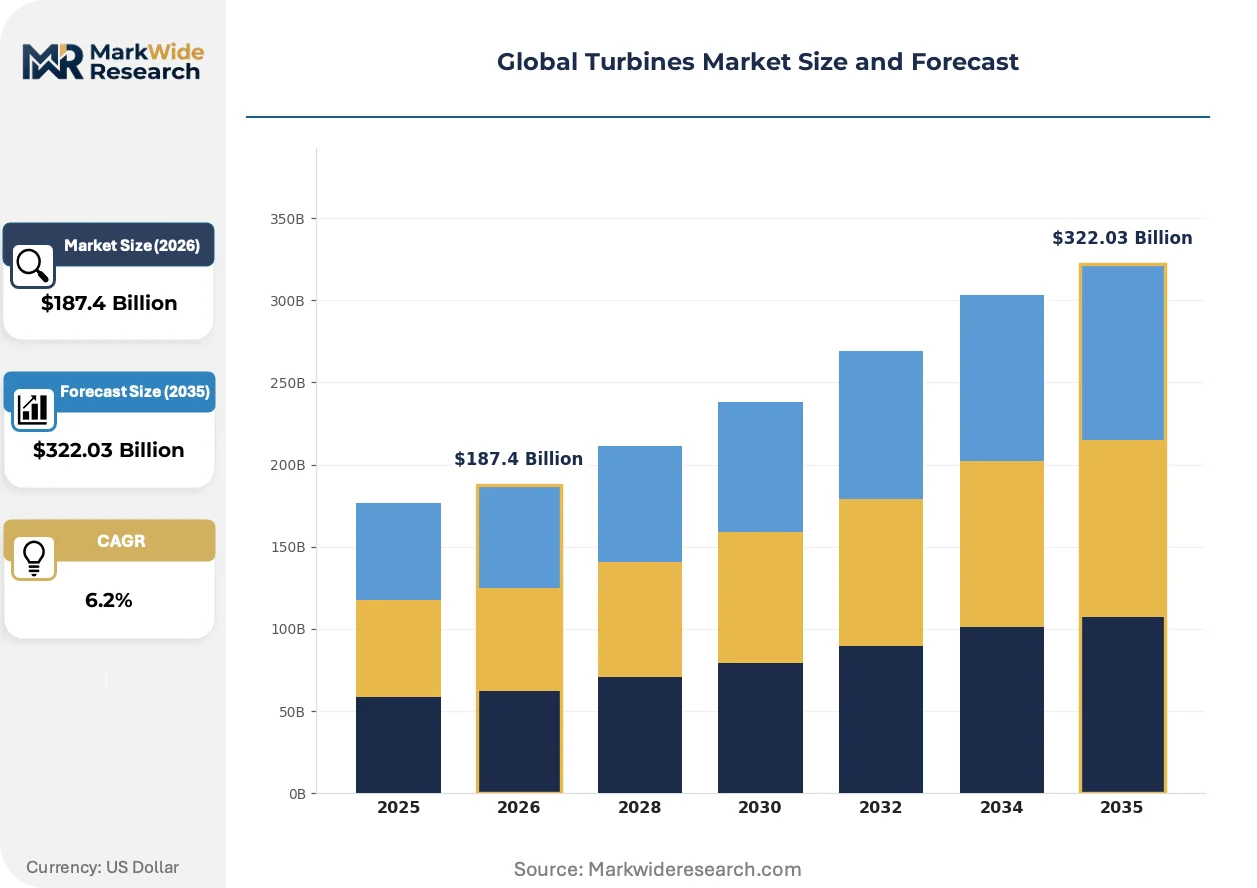
Market Dynamics
The fundamental market dynamic is the tension between global decarbonization mandates and the concurrent need for grid stability. This conflict simultaneously fuels investment in intermittent renewable sources like wind and in flexible, fast-ramping gas turbines for essential grid balancing.
Growth Catalysts
- Policy Frameworks:The EU Green Deal and its associated funding mechanisms directly accelerate utility-scale investment in onshore and offshore wind turbine projects to meet renewable energy targets.
- National Decarbonization Goals:China's dual carbon goals are driving unprecedented, state-led capacity additions across wind, hydro, and gas turbine segments to overhaul its energy infrastructure.
- Grid Modernization:Demand for grid stability services in markets with high renewable penetration creates a persistent need for advanced, high-efficiency combined cycle gas turbines to manage intermittency.
Market Restraints
- Input Material Volatility:Price fluctuations and supply concentration of rare earth elements, essential for permanent magnets in direct-drive wind turbines, create significant cost uncertainty for manufacturers.
- Technical Limitations:The inherent intermittency of wind and solar power generation constrains the pace of fossil fuel displacement, requiring parallel investment in dispatchable power sources or energy storage.
- Logistical Bottlenecks:The increasing physical size of turbine components, particularly for large-scale wind projects, strains existing port infrastructure, specialized transport fleets, and installation vessel availability.
Strategic Opportunities
- Hydrogen Fuel Transition:Developing and marketing hydrogen-ready gas turbines offers a pathway for asset owners to future-proof investments, enabling a switch to carbon-free fuel as production scales.
- Distributed Generation:Expanding microgrid and captive power projects in regions like Southeast Asia and sub-Saharan Africa creates new demand for smaller-scale, modular gas and hydro turbines.
- Incentive Programs:The US Inflation Reduction Act (IRA) contains production and investment tax credits that directly encourage domestic manufacturing and deployment of wind and other clean energy turbines.
Industry Challenges
- Specialized Talent Scarcity:A shortage of qualified engineers and technicians for commissioning, operating, and maintaining advanced-class gas turbines and large offshore wind farms creates operational delays.
- Capital-Intensive Logistics:The immense capital expenditure required for specialized vessels for offshore wind turbine installation and for upgrading port infrastructure to handle larger components limits project viability.
- Grid Integration Complexity:Integrating high volumes of variable renewable power from turbines into legacy transmission and distribution networks requires substantial and often slow-moving grid modernization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Turbines Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $322.03 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Wind Turbines, Hydro Turbines Application: Power Generation, Marine Propulsion, Industrial Processes, Oil & Gas Technology: Combined Cycle, Open Cycle, Renewable Energy, Cogeneration End User: Utilities, Manufacturing, Transportation, Renewable Energy Providers |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Rolls-Royce Holdings, Ansaldo Energia, Solar Turbines, Baker Hughes, Doosan Enerbility, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Turbines Market Strategic Shifts & Innovations
Digitalization and material science advancements are converging to enhance turbine efficiency, extend operational lifespans, and enable greater fuel flexibility. These innovations are critical for navigating evolving emissions regulations and grid requirements across the power generation and industrial sectors.
Additive manufacturing, specifically selective laser melting, allows for the creation of intricate internal cooling channels and complex geometries in turbine hot gas path components. Gas turbine manufacturers are rapidly adopting this for parts like fuel nozzles and blades to improve thermal performance and combustion efficiency. This advanced production capability is rendering obsolete certain traditional casting and forging processes for complex, high-value components, drastically reducing lead times.
Regulatory mandates are a primary force shaping technology roadmaps. The US EPA's stringent emissions standards for power plants, for example, impose strict limits on outputs of pollutants like nitrogen oxides. This directly impacts the gas turbine segment by forcing investment in advanced dry low-NOx combustion systems and post-combustion treatment technologies. Gas turbine design is now intrinsically linked to compliance with these evolving regional environmental rules.
A notable shift in purchasing behavior involves utilities and industrial operators moving away from simple equipment transactions toward performance-based long-term service agreements. This model disrupts the conventional parts and service business by bundling maintenance, monitoring, and performance guarantees into a single contract. The trend is most pronounced in North America and Europe, where power producers seek to transfer operational risk and lock in predictable maintenance costs.
Global Turbines Market Segmentation
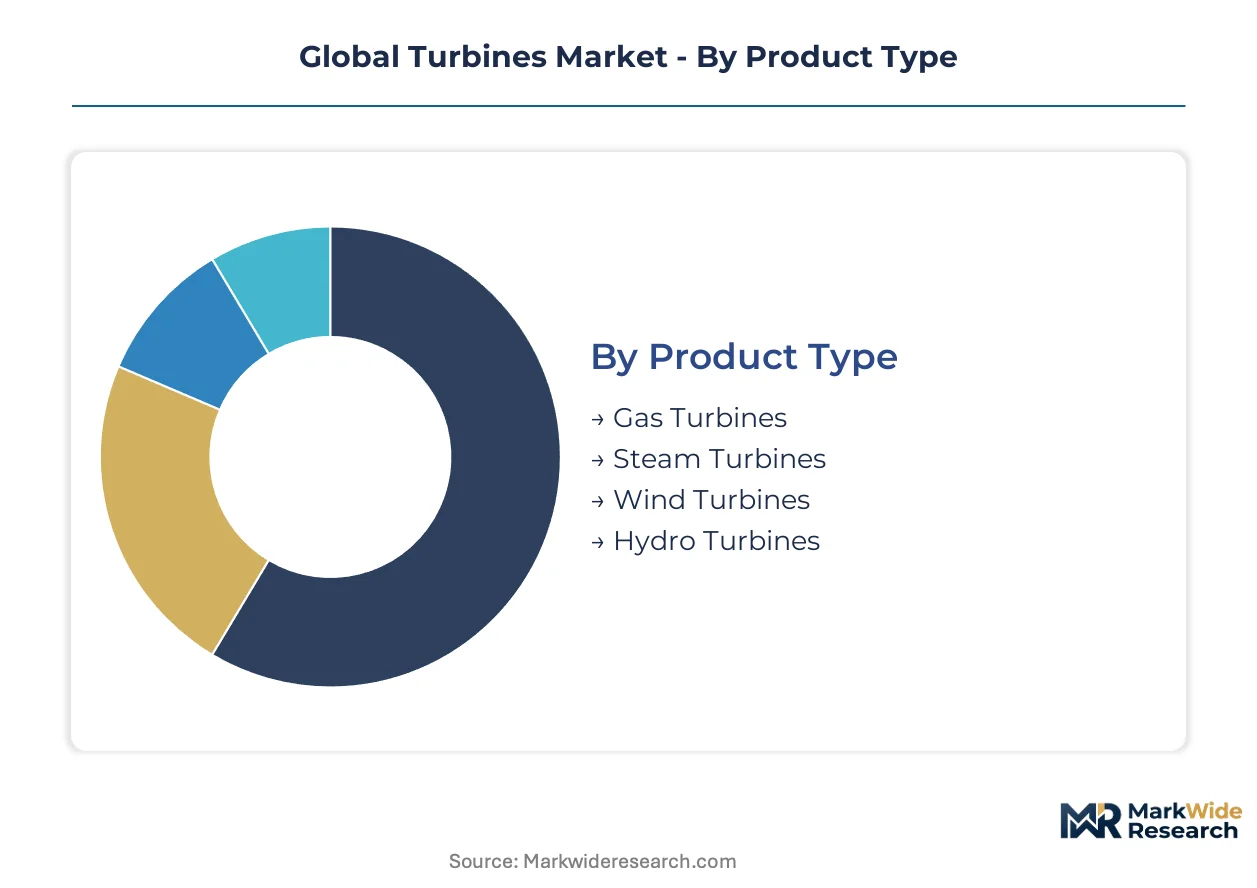
The global turbines market is highly diversified, driven by distinct energy sources, operational requirements, and end-user applications. Understanding these segments provides clarity on where investment capital is flowing and which technologies are gaining strategic importance. This segmentation highlights the core components and their deployment across the energy landscape.
Product Type:
The product type dimension categorizes turbines based on their primary energy source and operational mechanism.
- Wind Turbines:These devices convert kinetic energy from wind into mechanical power, primarily for electricity generation. Demand concentration is evident in China and Europe, propelled by the EU Green Deal and national decarbonization mandates.
- Gas Turbines:These internal combustion engines generate power through the combustion of natural gas or other gaseous fuels, often used in combined cycle configurations. Their deployment in power generation is critical for grid stability in markets with high renewable penetration, such as North America.
- Steam Turbines:These machines extract thermal energy from pressurized steam, converting it into rotational energy for electricity generation or mechanical drive. Mitsubishi Heavy Industries sustains its market position through a focus on high-efficiency industrial and utility-scale steam turbines.
- Hydro Turbines:These turbines harness the kinetic energy of flowing water to generate electricity, representing a mature and reliable renewable energy source. China's dual carbon goals are driving unprecedented capacity additions for hydro turbine segments.
Gas Turbines commands the established base. The steepest expansion runs through Wind Turbines.
Application:
Turbine deployment varies significantly across diverse industrial and utility applications.
- Power Generation:This application involves turbines driving electrical generators to produce electricity for grids and industrial facilities. It remains the largest segment, with demand for both baseload and flexible power sources globally.
- Industrial Processes:Turbines provide mechanical drive or process heat for various manufacturing operations, including chemical plants and refineries. Efficiency gains and captive power generation drive demand in sectors seeking energy independence.
- Marine Propulsion:Turbines power large vessels, including commercial ships and naval fleets, offering high power-to-weight ratios and reliability. This application demands robust and compact turbine designs for demanding oceanic environments.
- Oil & Gas:Turbines are essential for driving compressors and pumps in upstream, midstream, and downstream operations within the petroleum industry. Their use ensures the efficient extraction, transport, and processing of hydrocarbons.
Power Generation sees significant volume. Industrial Processes demonstrates robust expansion.
Technology:
Technological innovation dictates turbine operational efficiency and environmental compliance.
- Combined Cycle:This technology integrates gas and steam turbines to maximize efficiency by utilizing waste heat from the gas turbine to power a steam turbine. It is essential for grid stability and flexible power generation in markets like the US and Germany.
- Renewable Energy:This segment encompasses technologies like wind and hydro turbines, which convert natural, replenishable resources into electricity. Global decarbonization mandates and policy frameworks like the EU Green Deal are accelerating investment in these technologies.
- Open Cycle:These gas turbines operate in a simple cycle, often used for peaking power plants due to their fast-start capabilities. Their deployment provides rapid response to fluctuations in electricity demand.
- Cogeneration:Also known as combined heat and power (CHP), this technology produces both electricity and useful heat from a single fuel source. It offers significant energy efficiency improvements for industrial and commercial facilities.
Combined Cycle remains foundational for energy infrastructure, with Renewable Energy gaining momentum from policy incentives.
End User:
Turbine adoption patterns reflect the distinct operational needs of various end-user segments.
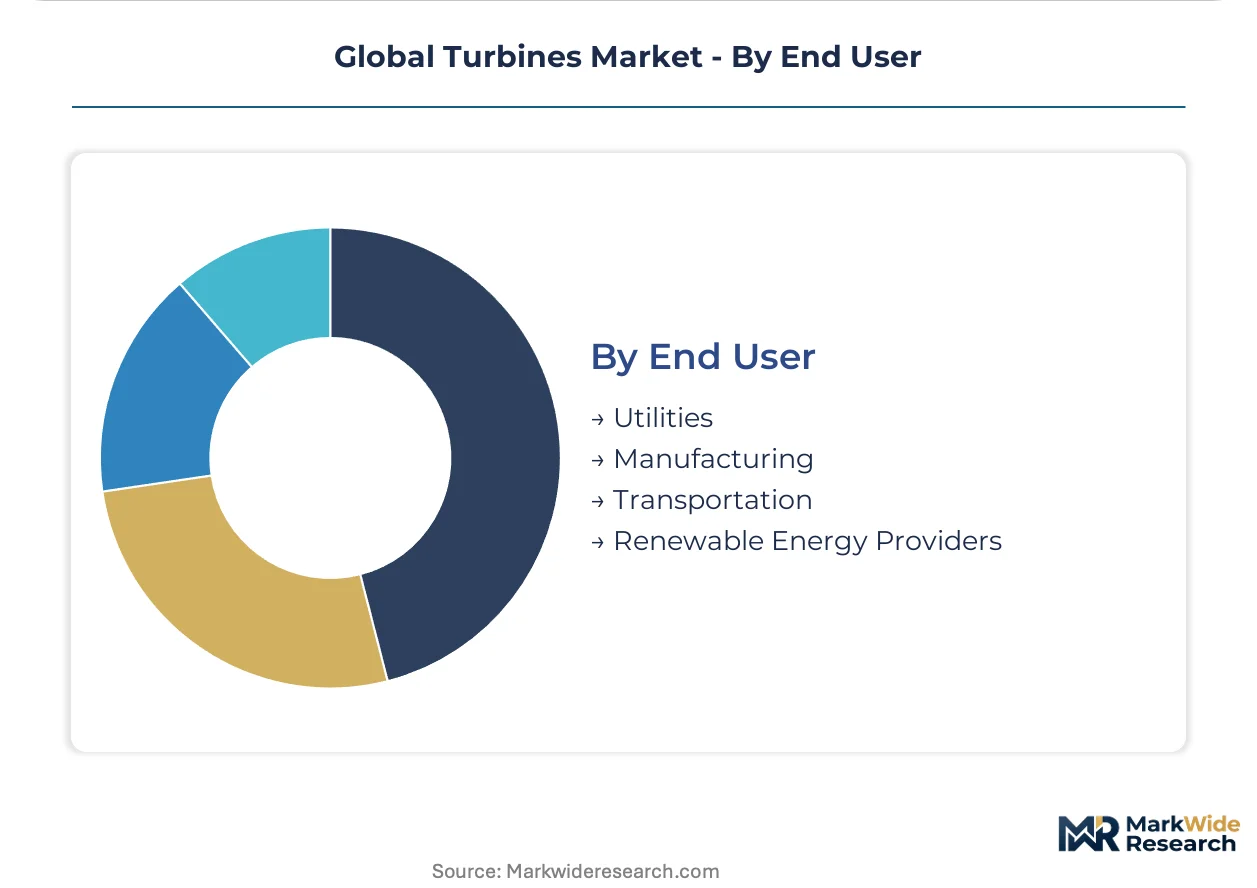
- Utilities:These entities manage large-scale power generation and distribution networks, requiring reliable and efficient turbines for baseload and peak power. Grid modernization efforts are influencing their procurement of advanced turbine technologies.
- Renewable Energy Providers:Companies specializing in wind, solar, and hydro power generation drive demand for turbines designed for clean energy production. Policy frameworks like China's dual carbon goals directly incentivize their investment.
- Manufacturing:Industrial manufacturers utilize turbines for on-site power generation, process heating, and mechanical drives to enhance operational efficiency. Distributed generation projects in Southeast Asia create new demand for smaller-scale turbines.
- Transportation:This segment includes marine and aviation applications where turbines provide propulsion for ships and aircraft. Specialized turbine designs cater to the stringent performance and reliability requirements of these sectors.
Traditional demand stems from Utilities, but Renewable Energy Providers exhibits the most dynamic growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global turbines market exhibits a concentrated demand landscape, particularly in regions undergoing significant energy infrastructure transformation. China's extensive build-out of both renewable and gas-fired power capacity drives substantial volume. This geographic concentration influences supply chain configurations and technology deployment strategies.
China
China's dual carbon goals accelerate demand for wind, hydro, and gas turbines across its vast energy infrastructure. The Ministry of Ecology and Environment (MEE) influences turbine designs through strict environmental standards. Large-scale capacity additions in provinces like Inner Mongolia reconfigure the supply chain for various turbine types.
United States
Demand for gas turbines for grid stability and wind turbines for decarbonization drives activity in the United States. The US Inflation Reduction Act (IRA) encourages domestic manufacturing and deployment of clean energy turbines. Investment in advanced combined cycle plants is prominent in Texas and California.
Germany
Germany's energy transition mandates significant investment in both wind and combined cycle gas turbine technologies. The EU Green Deal and national policies support utility-scale renewable energy projects. Offshore wind farm development in the North Sea region requires specialized turbine components and installation.
Japan
Japan sustains demand for high-efficiency industrial and utility-scale steam turbines, alongside strategic investments in gas turbines. The Ministry of Economy, Trade and Industry (METI) guides energy policy, promoting advanced power generation. Industrial clusters in regions like Kansai focus on turbine manufacturing and innovation.
India
India's expanding industrial base and power generation needs create consistent demand for various turbine types. The Central Electricity Authority (CEA) outlines long-term power generation plans, including renewable energy targets. Significant projects in states like Gujarat contribute to the national power grid expansion.
Global Turbines Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sub-assemblies for turbine construction. The global turbines market exhibits a tiered structure, with large, diversified industrial conglomerates dominating the high-value segments. Strategic archetypes include integrated power solution providers offering comprehensive plant solutions and specialized component manufacturers focusing on niche technologies. Portfolio diversification and strategic partnerships are common competitive moves to expand market reach.
Among global industrial conglomerates, GE Vernova and Siemens Energy exemplify integrated power solution providers, competing across wind, gas, and combined cycle segments. Mitsubishi Heavy Industries, a Japanese industrial giant, represents a focus on high-efficiency industrial and utility-scale steam turbines, sustaining its market position. These large players leverage extensive R&D capabilities and global service networks to maintain their market positions. Their offerings often include long-term service agreements, transferring operational risk and ensuring predictable maintenance costs for utilities and industrial operators.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Rolls-Royce Holdings |
| Ansaldo Energia |
| Solar Turbines |
| Baker Hughes |
| Doosan Enerbility |
| Kawasaki Heavy Industries |
Cost & Logistics Intelligence
Input material volatility, particularly for rare earth elements, directly determines pricing tier spreads and the global supply chain shape for turbine components. This concentration of critical raw materials creates significant cost uncertainty for manufacturers.
Pricing Analysis
US EPA's emissions standards dictate the pricing tier structure for gas turbines, emphasizing compliance and advanced technology. The dominant pricing model is project-based, often incorporating long-term service agreements for performance guarantees. Price differentiation drivers include turbine efficiency, fuel flexibility, and the integration of advanced dry low-NOx combustion systems. Pricing pressure stems from intense competition among global conglomerates and the continuous demand for higher energy conversion rates. Utilities demonstrate sensitivity to total cost of ownership, while renewable energy providers prioritize upfront capital expenditure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, reflecting the capital-intensive nature of turbine manufacturing. Geographic supply concentration for critical components centers on China for rare earth elements and large-scale wind turbine parts, while Germany and Japan specialize in high-efficiency gas and steam turbine components. Raw material dependencies include specialized alloys for hot gas path components and permanent magnets for direct-drive wind turbines. Logistical bottlenecks, driven by the increasing physical size of turbine components, represent a significant structural risk. Distribution runs through direct sales to utility companies and large project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global turbines market is experiencing a shift in buyer power, driven by the consolidation of large utility companies and the emergence of integrated renewable energy providers. This reconfigures procurement dynamics and demands tailored strategic responses from all market participants.
For Market Incumbents: Harden core technological advantages by accelerating R&D in hydrogen-ready gas turbines, addressing future fuel transition demands. Expand specialized talent pools for commissioning and maintenance of advanced-class turbines, mitigating operational delays stemming from talent scarcity. Invest in upgrading port infrastructure and specialized transport fleets for larger offshore wind components, countering logistical bottlenecks. This proactive stance defends market share against emerging competitors leveraging new fuel technologies and addresses grid integration complexity.
For New Entrants and Emerging Players: Pursue opportunities in distributed generation, targeting microgrid and captive power projects in Southeast Asia and sub-Saharan Africa. Focus on smaller-scale, modular gas and hydro turbines where established players have less competitive density. Develop specialized component manufacturing for additive manufacturing, leveraging advanced production capabilities for intricate turbine parts. A key go-to-market angle involves offering performance-based long-term service agreements, transferring operational risk to asset owners.
For Investors and Strategic Acquirers: The market sits at a dynamic growth phase that favors technology innovators and specialized component manufacturers with strong R&D pipelines. Long-term viability remains strong, anchored by global decarbonization mandates and the persistent need for grid stability. Acquisition targets should prioritize firms with proven expertise in advanced materials, additive manufacturing for turbine parts, or hydrogen fuel transition technologies. The signal to watch is the adoption rate of hydrogen-ready gas turbines in new power generation projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Development | Future-proofs gas turbine assets, enabling a transition to carbon-free fuel sources as production scales. |
| Offshore Wind Logistics Upgrade | Addresses logistical bottlenecks for large components, accelerating deployment of utility-scale wind projects. |
| Additive Manufacturing Adoption | Reduces lead times and improves thermal performance for complex hot gas path components. |
| Performance-Based Service Contracts | Transfers operational risk to manufacturers, ensuring predictable maintenance costs for utilities and operators. |
| Microgrid Solution Integration | Captures new demand for smaller-scale, modular turbines in underserved regions like Southeast Asia. |
Research Approach
Initial hypotheses were tested against primary input from utility planning officers, turbine design engineers, and supply chain managers, then refined. This involved combining insights from in-depth interviews with extensive secondary validation. Secondary sources included IEA reports, EIA data, company financial filings, and regulatory documents from US EPA and the EU Green Deal. A rigorous bottom-up and top-down triangulation process ensured data accuracy and comprehensive market understanding.
Demand-supply-balance models underpinned the analytical framework across the analysis window, integrating historical trends and future projections. The market was segmented by product type, application, technology, end user, and regional regulatory frameworks for granular analysis. Compound annual growth rates were derived through a combination of regression analysis and expert consensus. Key forecast inputs included projected renewable energy capacity additions and natural gas price forecasts.
Macroeconomic conditions sit as an overlay; deviation in global energy policy or commodity prices would shift the trajectory. Forecasts reflect documented assumptions, but unforeseen geopolitical events or rapid technological advancements could alter market dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
India Gas Generator Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
India Gensets Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Captive Power Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Steam Turbine Market
Power Generation
Algeria Power Market
Power Generation
Residential Solar Generator Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Solar Generator Market