
 Standard Modular Hydropower Market | 2026-2036
Standard Modular Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Standard Modular Hydropower Market Analysis
The gap between premium European-engineered modular systems and commodity Asian-manufactured units is recalibrating procurement patterns across utility tenders. ANDRITZ leverages its Austrian manufacturing base to sustain high-specification contracts for alpine runoff installations. Voith competes on integrated control systems that anchor long-term service agreements in Central European markets.
Standard modular hydropower denotes factory-assembled, containerized or skid-mounted turbine-generator sets with capacities typically below 10 MW, designed for rapid deployment without extensive civil works. These systems employ axial-flow or cross-flow turbines mated to synchronous generators with embedded digital controllers, serving remote communities and industrial off-takers seeking dispatchable renewable baseload. Grid-connected system types currently dominate order books, while hybrid configurations pairing modular hydro with battery storage represent the fastest-expanding segment as island utilities seek firm capacity. The technology dimension shows control systems capturing disproportionate margin pools due to firmware complexity and remote monitoring requirements.
The EU Green Deal and REPowerEU framework impose stringent lifecycle emissions thresholds on distributed generation assets, while the US EPA and FERC coordinate on small-scale hydro licensing reform to accelerate permitting timelines. India's CEA and Ministry of Power have issued revised technical standards for run-of-river modular installations under the country's renewable purchase obligation scheme. Stakeholders must monitor how evolving grid codes for distributed energy resources reshape interconnection requirements and equipment certification pathways.
Market Dynamics
Containerized turbine units are compressing deployment timelines from years to months, forcing civil engineering contractors and equipment vendors to restructure project delivery models around factory-integrated systems rather than site-built installations.
Growth Catalysts
- REPowerEU framework:The EU's distributed generation mandates tighten emissions thresholds for alpine runoff installations, accelerating replacement of aging diesel microgrids with modular hydro in Austrian and Italian valleys.
- Island grid operators:Southeast Asian archipelago utilities are procuring scalable low-head solutions to displace fuel-intensive thermal peaking plants, with the Philippines and Indonesia leading tender volumes.
- Cross-flow turbine advances:Improved blade geometries and composite materials are expanding viable head ranges, opening previously uneconomical run-of-river sites to commercial development.
Market Restraints
- Steel and copper input volatility:Generator stator windings and penstock fabrication depend on commodity metals whose price swings compress equipment margins during procurement cycles.
- European manufacturing concentration:Premium control system assembly clusters in Austria and Germany, creating supply vulnerability for non-European developers seeking high-specification digital controllers.
- Small-scale hydro licensing friction:US FERC and state environmental agencies maintain overlapping permitting requirements that extend pre-construction timelines despite federal streamlining efforts.
Strategic Opportunities
- Battery-hybrid configurations:Pairing modular hydro with lithium-ion storage creates firm capacity products that island utilities in the Caribbean and Pacific Islands now specify in integrated tenders.
- India's renewable purchase obligation:The CEA's revised technical standards for run-of-river installations create certified equipment pathways for foreign vendors to supply state electricity boards.
- Remote monitoring convergence:Embedded IoT sensors and edge computing are unifying predictive maintenance with SCADA systems, enabling OEMs to capture recurring revenue through long-term service contracts.
Industry Challenges
- Commissioning engineer scarcity:Specialized expertise in synchronous generator alignment and hydraulic governor tuning is concentrated among aging European technicians, constraining deployment velocity in emerging markets.
- IEC 61850 certification timelines:Grid code compliance for distributed energy resources requires extensive protocol testing that delays interconnection approvals by six to twelve months in multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standard Modular Hydropower Market |
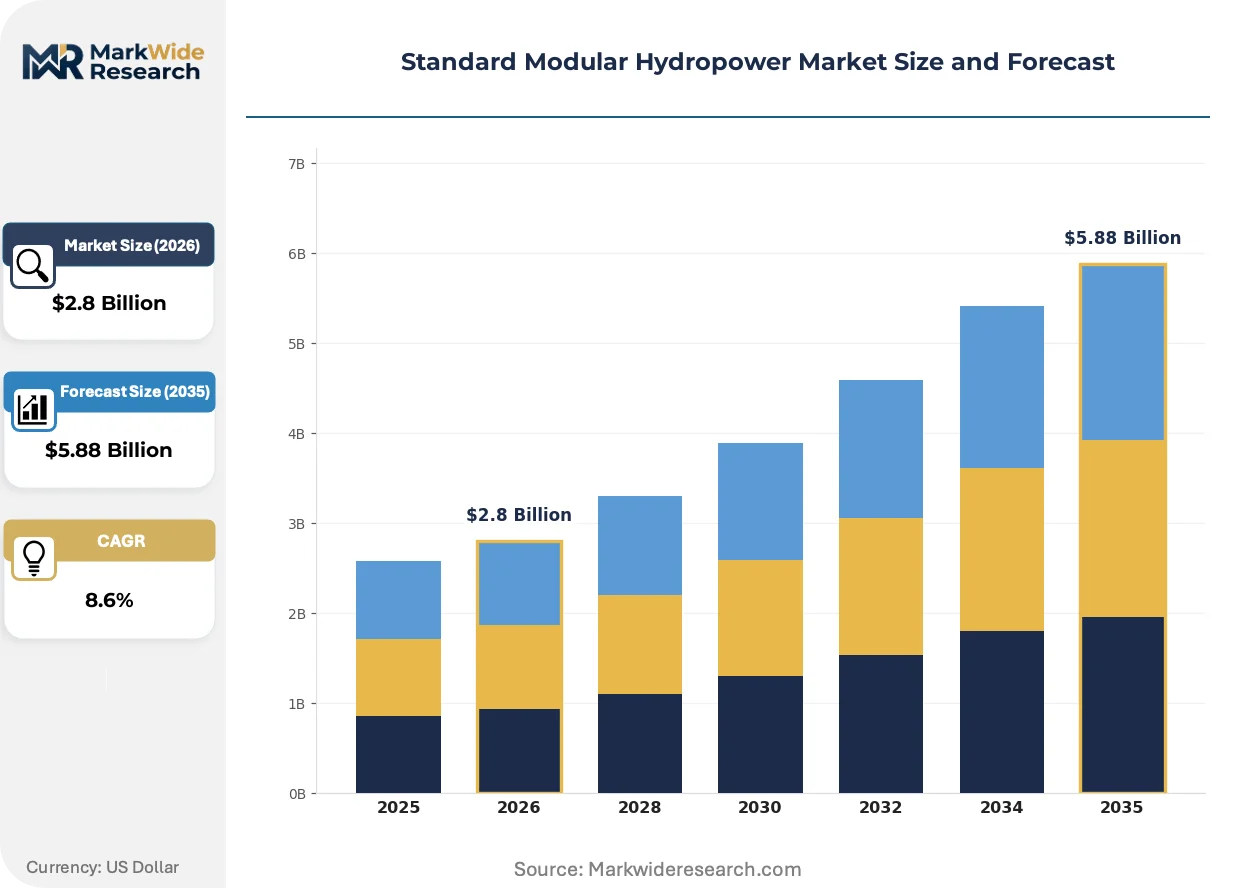
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Off-Grid, Grid-Connected, Hybrid, Pumped Storage Technology: Turbine, Generator, Control System, Inverter End User: Utilities, Industrial, Commercial, Residential Installation Type: New Build, Retrofit, Expansion, Modular Upgrade |
| Companies Covered | NuSTREEM, ANDRITZ, Emrgy Inc., General Electric, Voith, PowerSpout, Siemens, RusHydro, Mavel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standard Modular Hydropower Market Emerging Trajectories
Digital control architectures are displacing electromechanical governing systems across the installed base, while factory pre-assembly is compressing the traditional civil-mechanical-electrical handoff sequence that historically governed project risk allocation.
Integrated turbine-generator-control packages are unifying previously separate procurement streams into single-source contracts. Alpine utilities in Switzerland and Norway are specifying these systems for high-altitude runoff sites where logistical access limits on-site assembly options. This consolidation is compressing vendor margins on standalone component sales while expanding lifetime service attach rates.
The EU Green Deal's lifecycle emissions benchmarking is tightening material sourcing requirements for certified installations. Equipment destined for German and Austrian markets must now document embodied carbon in steel castings and concrete foundations, forcing foundries to adopt electric arc furnace production or lose qualification status. Cross-border suppliers are responding by regionalizing forging operations within the customs union.
Performance-based contracting is displacing traditional equipment purchase models among industrial off-takers. Mining operators in Chile and Peru now procure kilowatt-hour guarantees rather than turbine assets, transferring operational risk to OEMs and compressing supplier working capital cycles. This shift is most visible in remote extraction sites where grid instability previously forced captive diesel generation.
Standard Modular Hydropower Market Segmentation
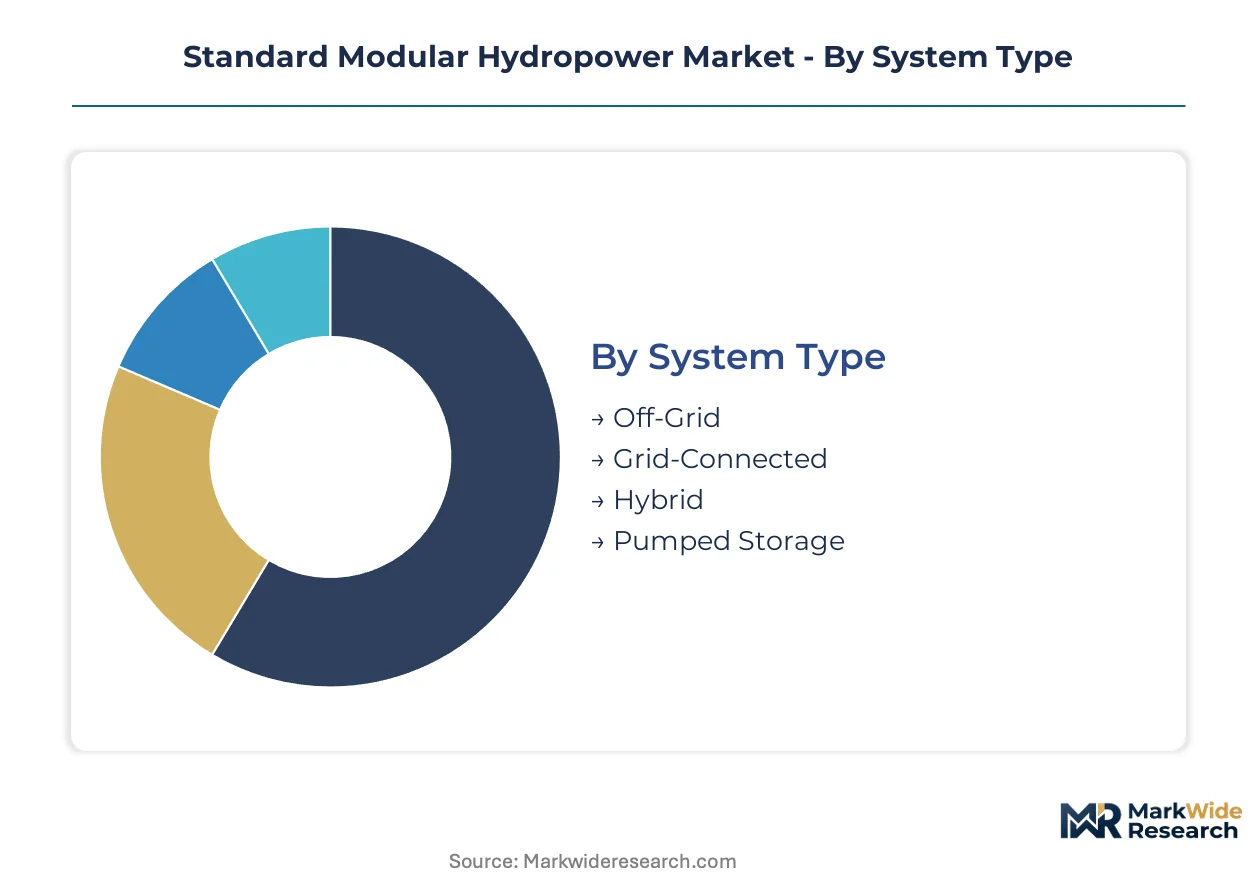
Segmentation reveals how procurement patterns diverge between remote electrification programs and grid-connected utility tenders. Each dimension—system architecture, core technology, end-use vertical, and deployment mode—carries distinct margin profiles and regulatory requirements that reshape vendor positioning.
System Type:
Replacement cycles for aging diesel microgrids are accelerating procurement of containerized turbine units across remote geographies.
- Grid-Connected:Synchronous generator sets with IEC 61850-compliant SCADA integration dominate utility-scale tenders in Central European alpine valleys. Austrian and Swiss procurement offices specify these systems for run-of-river sites where grid stability requirements mandate precise frequency regulation.
- Hybrid:Battery-coupled configurations pair cross-flow turbines with lithium-ion storage to deliver firm capacity products. Caribbean and Pacific Island utilities now mandate these integrated packages in tenders displacing fuel-intensive thermal peaking plants.
- Off-Grid:Skid-mounted axial-flow units serve mining camps and remote communities lacking transmission infrastructure.
- Pumped Storage:Modular reversible pump-turbine sets address diurnal load balancing in island grids with limited reservoir options.
Volume placements concentrate in Grid-Connected; the faster expansion belongs to Hybrid.
Technology:
Component selection determines lifecycle service revenue capture and certification pathway complexity.
- Control System:Embedded digital governors with edge-computing capabilities command premium pricing due to firmware complexity and remote monitoring requirements. EU Green Deal lifecycle emissions benchmarking forces documentation of embodied carbon in controller manufacturing, favoring European assembly clusters.
- Turbine:Cross-flow and axial-flow designs with composite blade geometries expand viable head ranges for previously uneconomical sites.
- Generator:Synchronous machines with permanent magnet rotors reduce excitation losses in small-capacity installations.
- Inverter:Grid-forming inverters enable weak-grid connection for remote installations with unstable distribution networks.
Margin pools concentrate in Control System; Turbine captures the steepest expansion trajectory from site accessibility improvements.
End User:
Customer type dictates risk allocation between capital expenditure and performance-based contracting models.
- Utilities:State electricity boards in India and archipelago cooperatives in Southeast Asia procure certified equipment under renewable purchase obligation schemes. The CEA's revised technical standards create qualified vendor lists that foreign OEMs must navigate.
- Industrial:Mining operators in Chile and Peru now procure kilowatt-hour guarantees rather than turbine assets, transferring operational risk to suppliers.
- Commercial:Agricultural processing facilities and eco-resorts seek sub-megawatt units for captive renewable baseload.
- Residential:Micro-hydro installations serve isolated dwellings and small community clusters in mountainous terrain.
Contract value concentrates in Utilities; Industrial is expanding most quickly through performance-based procurement adoption.
Installation Type:
Deployment mode selection reflects site constraints, existing infrastructure age, and regulatory permitting timelines.
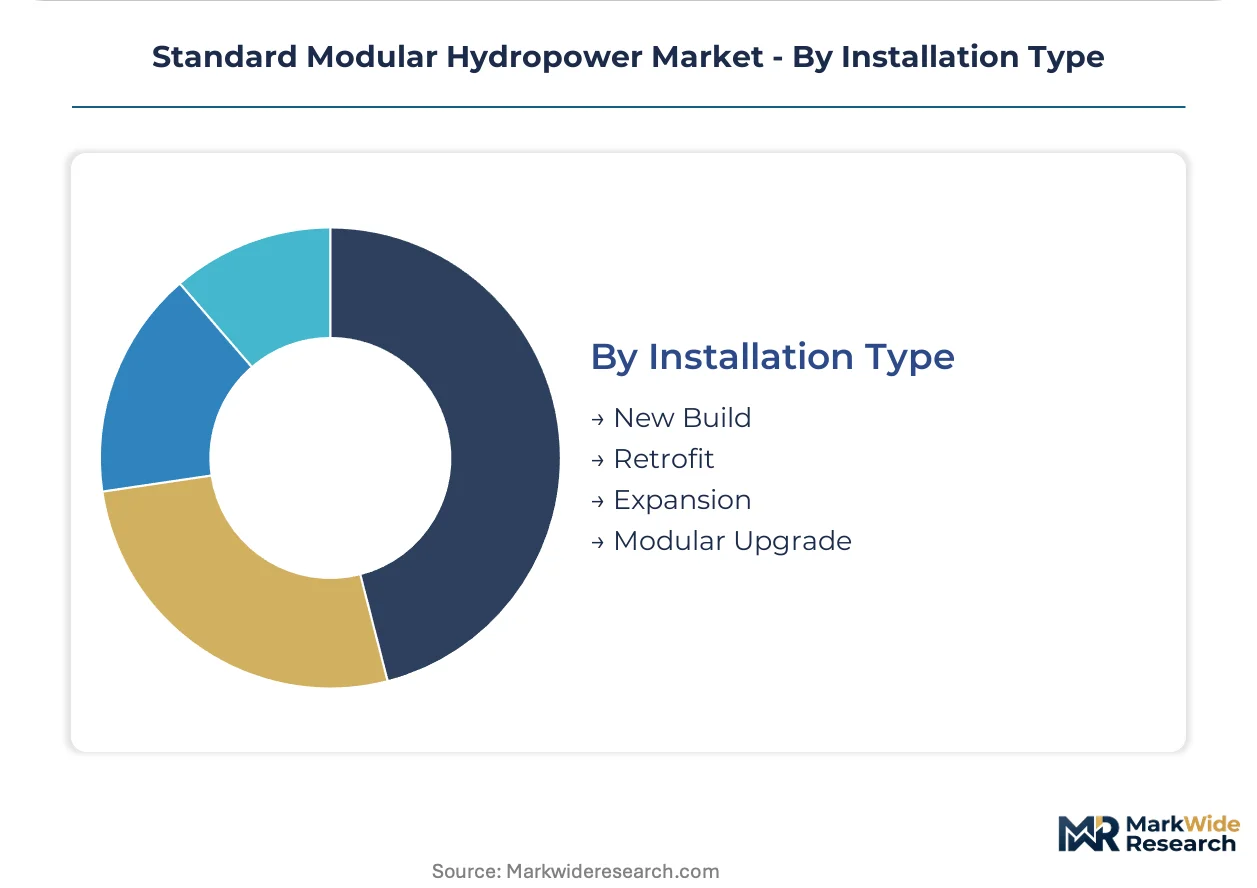
- Modular Upgrade:Containerized turbine-generator replacements compress deployment timelines from years to months at aging run-of-river sites. Alpine utilities in Italy and Austria favor this pathway where civil works remain intact but electromechanical equipment has exceeded technical life.
- New Build:Greenfield installations on previously undeveloped watercourses face extended environmental review despite streamlined small-hydro licensing reforms.
- Retrofit:Control system and governor replacements extend operational life of existing turbine runners without full generator replacement.
- Expansion:Capacity additions at existing hydropower sites leverage permitted water rights and transmission interconnections.
Project velocity concentrates in Modular Upgrade; New Build faces the greatest regulatory friction from overlapping permitting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graz anchors European manufacturing concentration for high-specification control systems, while Manila and Jakarta drive tender volumes for island grid applications across Southeast Asian archipelagos.
Austria
Alpine runoff installations in Tyrol and Styria accelerate procurement of containerized turbine-generator sets as utilities retire aging electromechanical equipment. The EU Green Deal lifecycle emissions benchmarking tightens material sourcing requirements for certified installations, forcing foundries to adopt electric arc furnace production. ANDRITZ leverages its Graz manufacturing base to sustain premium-margin contracts for high-head alpine sites.
Philippines
Island cooperatives in the Visayas and Mindanao regions tender scalable low-head solutions to displace fuel-intensive diesel peaking plants. The Department of Energy's renewable energy regulations mandate minimum local content thresholds for foreign equipment suppliers. Cebu-based engineering firms now specialize in rapid deployment logistics for containerized units across dispersed island grids.
Indonesia
State utility PLN accelerates rural electrification programs across Sulawesi and Papua with skid-mounted axial-flow installations. The Ministry of Energy and Mineral Resources revised technical standards for run-of-river modular systems under national renewable purchase obligations. Makassar has emerged as a procurement coordination hub for eastern archipelago installations.
United States
Remote mining operations in Alaska and the Mountain West procure off-grid modular hydro to reduce diesel dependence at extraction sites. FERC and state environmental agencies maintain overlapping permitting requirements that extend pre-construction timelines despite federal streamlining efforts. The Pacific Northwest hosts specialized commissioning engineer clusters for synchronous generator alignment.
India
State electricity boards in Himachal Pradesh and Uttarakhand tender certified equipment under revised CEA technical standards for run-of-river installations. The Ministry of Power's renewable purchase obligation scheme creates qualified vendor pathways for foreign OEMs. Dehradun serves as a technical certification hub for Himalayan runoff site assessments.
Standard Modular Hydropower Market Vendor Landscape
Premium-margin players sit above commodity-margin players across control system complexity and firmware certification tiers. The vendor base stratifies between Austrian-German engineering clusters specializing in IEC 61850-compliant SCADA integration and Asian fabricators competing on standardized turbine-generator packages. Three archetypes dominate: integrated technology conglomerates with captive power divisions, specialized hydropower engineering houses with alpine heritage, and emerging kinetic-hydro innovators targeting distributed generation niches. Competitive moves concentrate on geographic licensing partnerships for control system distribution and backward integration into permanent magnet generator manufacturing.
Among Austrian-German engineering specialists, ANDRITZ and Voith occupy positions within the premium-tier control system segment, while General Electric represents the integrated conglomerate archetype with cross-sector power generation capabilities. NuSTREEM exemplifies the kinetic-hydro innovation vector with its focus on distributed, low-head applications. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| NuSTREEM |
| ANDRITZ |
| Emrgy Inc. |
| General Electric |
| Voith |
| PowerSpout |
| Siemens |
| RusHydro |
| Mavel |
| Others |
Supply Flow & Price Mechanics
Factory pre-assembly of containerized turbine-generator sets is compressing project delivery timelines from years to months, simultaneously reducing on-site labor cost exposure and concentrating margin capture among Austrian-German engineering clusters with captive manufacturing infrastructure. This production-method transition rewards vendors with integrated foundry and controller assembly capabilities while penalizing site-dependent civil contractors.
Pricing Analysis
Kilowatt-hour guarantee contracts now anchor value-based pricing for mining operators in Chile and Peru, transferring operational risk from industrial off-takers to OEMs in exchange for premium rate structures. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified European control systems from commodity Asian-manufactured turbine packages. Cost compression in standard-tier equipment is intensifying because steel and copper input volatility erodes generator stator winding margins during procurement cycles. State electricity boards in India exhibit the highest price sensitivity due to renewable purchase obligation budget constraints, while alpine utilities in Austria and Switzerland prioritize firmware certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Graz, Manila, and Jakarta orchestrate hub-and-spoke patterns for containerized unit deployment across alpine valleys and Southeast Asian archipelagos. Manufacturing concentration in Austria, Germany, and China draws from specialized foundry capacity for steel castings, copper winding fabrication, and composite blade production. Single-source vulnerability in European control system assembly clusters threatens non-European developers seeking high-specification digital controllers. Distribution runs through utility procurement offices and state electricity board tender processes rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineer scarcity constrains deployment velocity, propping pricing power for vendors with captive technician training pipelines and long-term service attach rates.
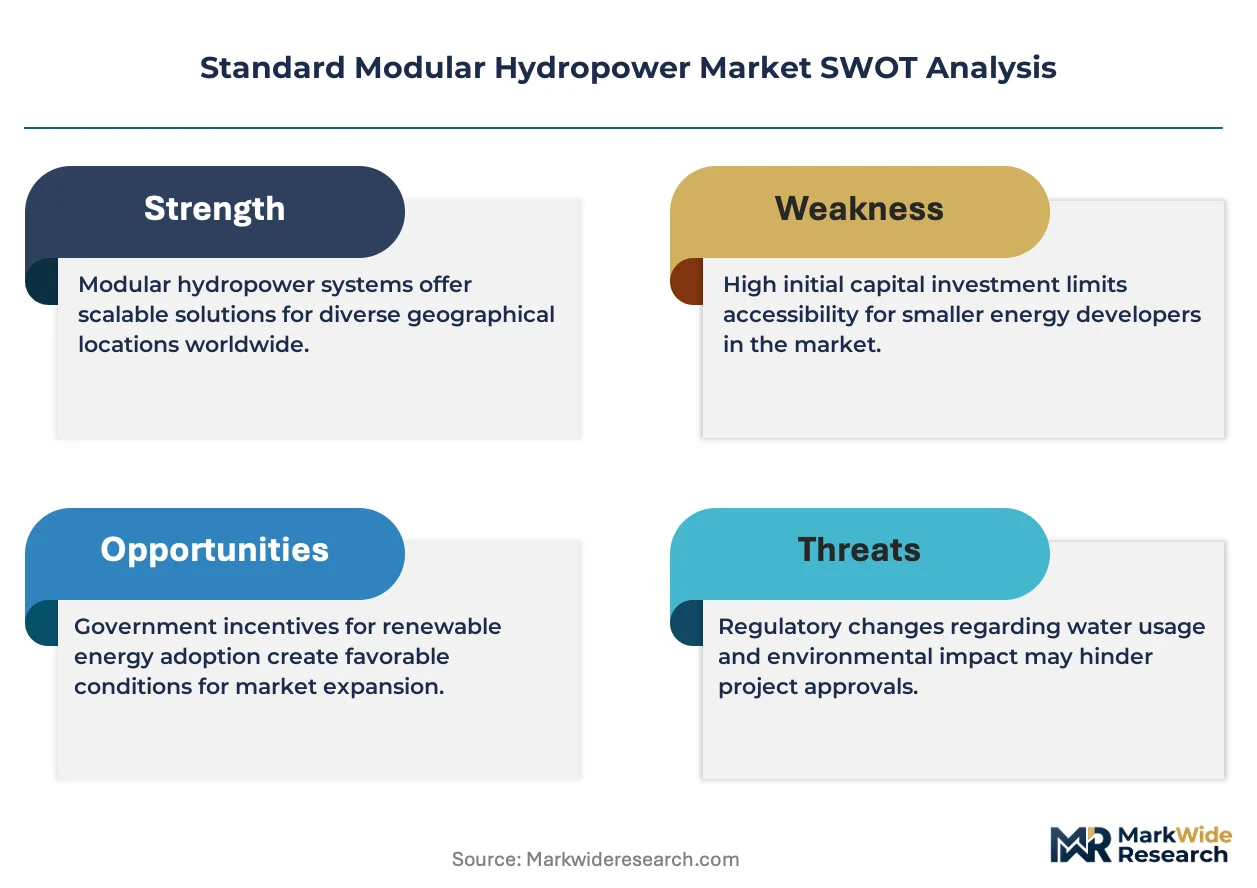
For Market Incumbents: Hedge against Asian commodity competition by deepening backward integration into permanent magnet generator manufacturing and securing exclusive distribution licenses for IEC 61850-compliant SCADA systems in Himalayan and alpine markets. Invest in certification pathways under India's CEA revised technical standards to defend qualified vendor list positioning against emerging kinetic-hydro innovators. For New Entrants and Emerging Players: The mid-tier pricing gap between premium European-engineered systems and commodity Asian units offers white-space entry for standardized cross-flow turbine packages with embedded edge-computing governors. Target island cooperatives in the Philippines and Indonesia with rapid-deployment logistics partnerships, leveraging local content threshold navigation as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated technology conglomerates seeking captive power division expansion. Long-term viability favors vendors with recurring revenue from remote monitoring convergence and predictive maintenance contracts. Watch for inflection in battery-hybrid tender specifications across Caribbean and Pacific Island utilities as the signal for firm-capacity product premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Control System Certification Investment | CEA and EU Green Deal compliance unlocks utility tender participation in India and alpine markets. |
| Battery-Hybrid Configuration Development | Island utilities in Caribbean and Pacific regions now mandate integrated storage in displacement tenders. |
| Regional Forging Operation Regionalization | Electric arc furnace adoption within EU customs union preserves qualification under lifecycle emissions benchmarking. |
| Remote Monitoring Platform Integration | Embedded IoT sensors unify predictive maintenance with SCADA, enabling recurring service revenue capture. |
| Commissioning Engineer Training Pipeline | Specialized expertise scarcity in synchronous generator alignment constrains competitor deployment velocity. |
Methodological Framework
Trade association filings, customs export records, and utility procurement databases formed the secondary backbone, supplemented by primary interviews with IPP project developers, EPC contractors, utility planning officers, and aftermarket service heads. Bottom-up and top-down triangulation validated equipment shipment volumes against tender award announcements and interconnection queue data.
Bottom-up modeling tracked individual project developments across system architecture, technology tier, end-use vertical, and deployment mode dimensions, while top-down analysis anchored aggregate market sizing to regulatory mandate trajectories under REPowerEU and India's renewable purchase obligation scheme. CAGRs were derived from segment-level deployment velocity and replacement cycle timing across the projection horizon, incorporating steel and copper commodity price assumptions and licensing timeline distributions.
Inputs from FERC, CEA, and EU Green Deal documentation were available through the study window; gaps in real-time commissioning engineer capacity data introduce uncertainty bands around deployment timeline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
United States Hydro Turbine Market