
 US Battery Energy Storage System Market | 2026-2036
US Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
US Battery Energy Storage System Market Insights
Utility procurement is rotating away from short-duration frequency regulation toward four-hour and longer-duration capacity services. Tesla leverages its integrated cell-to-pack manufacturing to compress system costs for utility-scale deployments. Fluence Energy competes through its proprietary software stack that optimizes dispatch across multiple revenue streams. Powin Energy anchors its position in the containerized segment with modular DC-block architectures that accelerate site commissioning.
A battery energy storage system comprises electrochemical cells, power conversion systems, and thermal management housed within protective enclosures, typically engineered for cycle lives exceeding 6,000 charge-discharge events at specified depth-of-discharge thresholds. Its primary commercial purpose is to time-shift electricity supply, arbitrage price differentials, and provide grid stabilization services. Li-ion chemistries dominate installed capacity owing to manufacturing scale and declining cell costs, while flow batteries capture niche utility-scale deployments where daily cycling exceeds twelve hours. The application mix tilts toward utility-scale projects that absorb the majority of capital deployment, with residential adoption trailing due to interconnection backlogs and net metering restructuring.
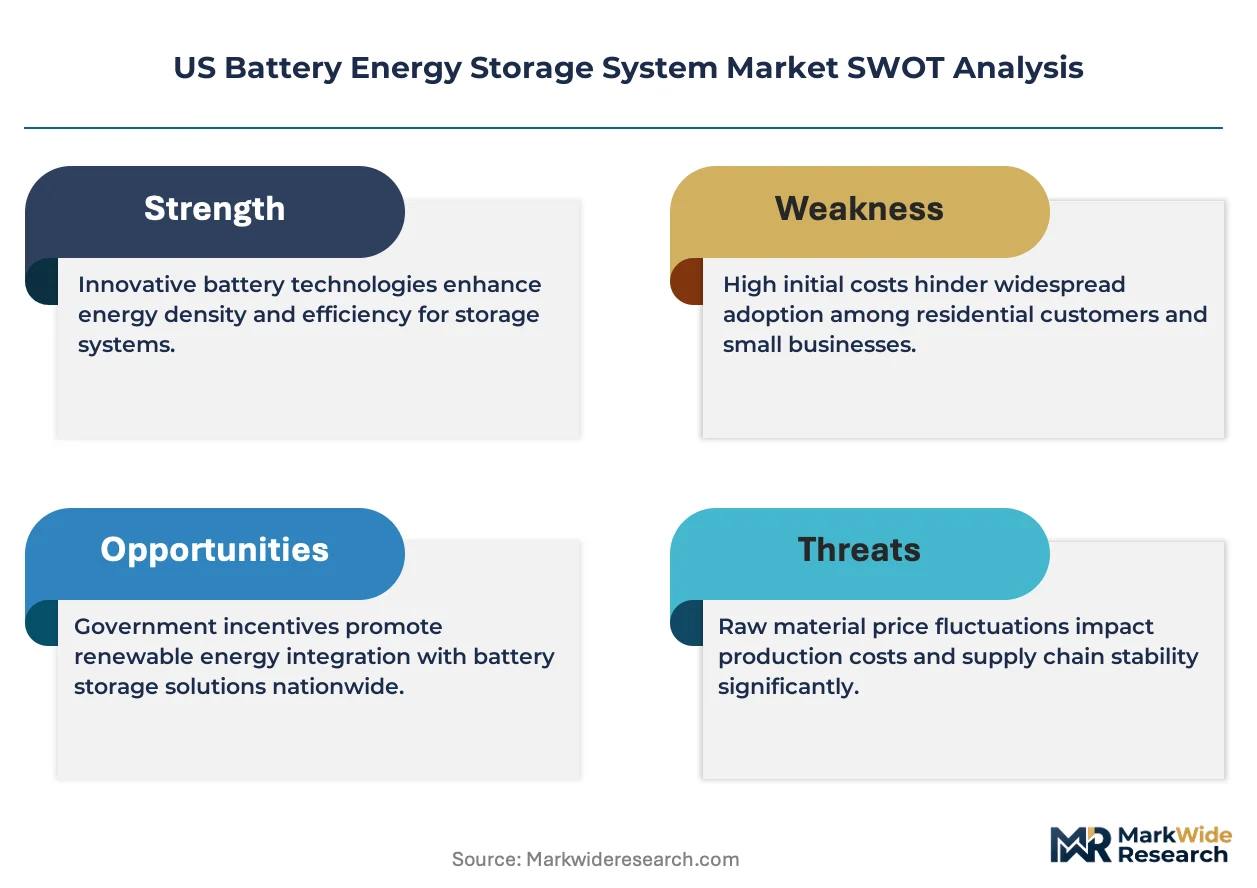
FERC Order 841 mandates wholesale market access for storage resources, while NERC reliability standards enforce cybersecurity and operational performance requirements that shape system design. The IRA's standalone storage ITC and domestic content bonus credits restructure procurement economics, favoring projects that incorporate North American-manufactured cells and modules. State public utility commissions in California, Texas, and New York impose resource adequacy obligations that directly translate to storage procurement targets. Stakeholders must monitor interconnection queue reform and domestic manufacturing buildout to assess supply security and cost trajectories.
Market Dynamics
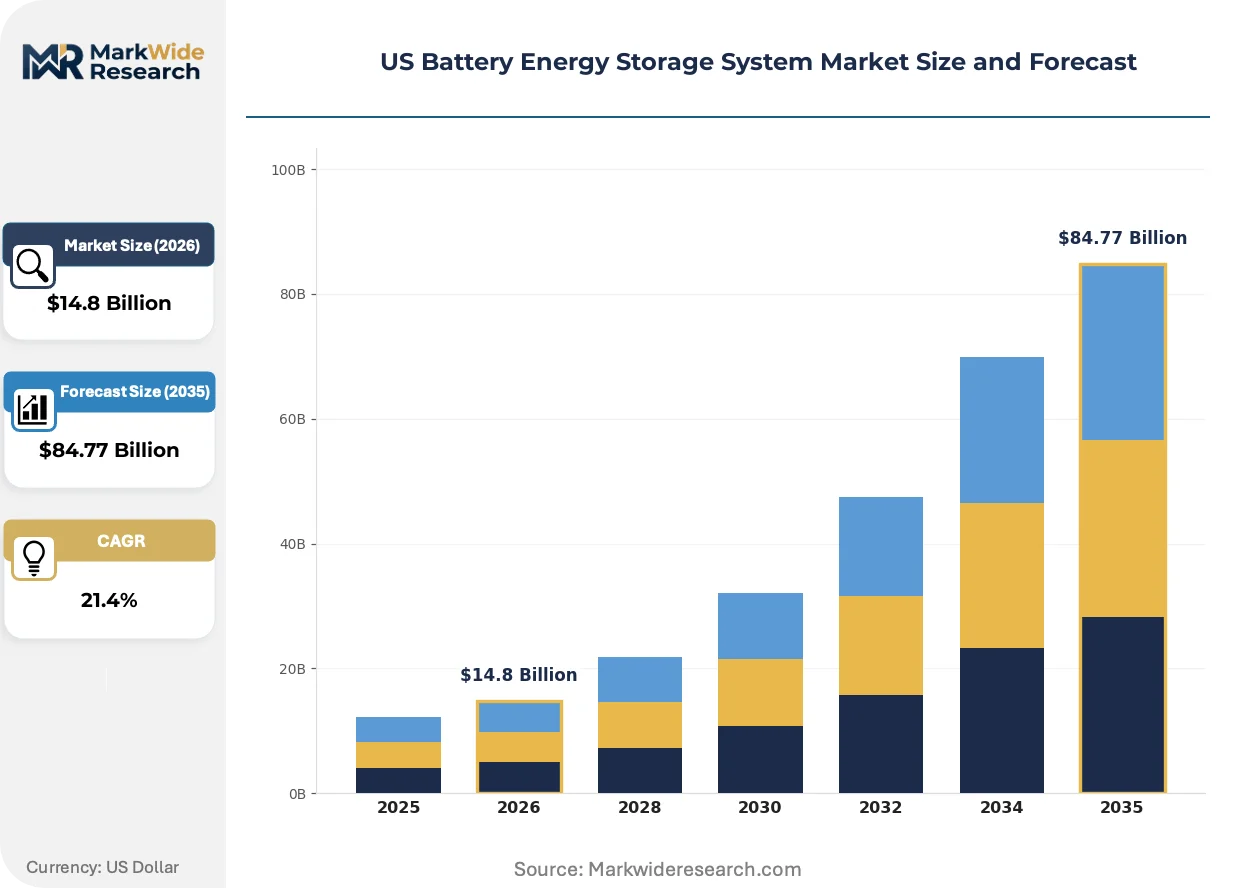
Utility procurement of front-of-the-meter storage is rotating toward longer-duration systems as state-level clean energy mandates harden and the Inflation Reduction Act's standalone storage investment tax credit restructures project economics across Texas, California, and Arizona.
Growth Catalysts
- IRA standalone storage ITC:The Inflation Reduction Act's dedicated tax credit for battery systems decoupled from solar generation activates merchant revenue stacking for utility-scale developers.
- Texas grid instability:ERCOT's price volatility events and transmission congestion create urgent dispatch needs for four-hour duration systems in the ERCOT West and South zones.
- Lithium iron phosphate chemistry:LFP cell architectures displace nickel-cobalt alternatives in utility procurement due to enhanced cycle stability and thermal safety profiles.
Market Restraints
- Interconnection queue backlogs:Regional transmission organizations impose multi-year study timelines that delay commercial operation dates for queued storage projects.
- Domestic cell supply concentration:North American manufacturing capacity for lithium-ion cells remains concentrated with limited qualified suppliers qualifying for domestic content bonus credits.
- Permitting fragmentation:County-level zoning ordinances and fire safety codes create inconsistent approval pathways across Arizona, California, and Texas jurisdictions.
Strategic Opportunities
- Texas merchant market expansion:ERCOT's energy-only market design enables uncapped price capture during scarcity events for battery operators with flexible trading desks.
- Flow battery long-duration niche:Vanadium redox systems capture daily cycling applications exceeding twelve hours where lithium-ion degradation economics falter.
- Behind-the-meter commercial aggregation:Virtual power plant platforms aggregate distributed storage assets for wholesale market participation under FERC Order 2222.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for inverter and power conversion system design concentrates with semiconductor and automotive competitors.
- Battery management system certification:UL 9540 and UL 1973 testing timelines extend eighteen to twenty-four months for novel cell formats and pack architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Battery Energy Storage System Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $84.77 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, Lead Acid, Flow Batteries, Sodium Sulfur Application: Utility-Scale, Commercial, Residential, Microgrid Installation Type: On-grid, Off-grid, Hybrid, Containerized End User: Utilities, Industrial, Homeowners, Renewable Energy Providers |
| Companies Covered | Tesla, Fluence Energy, The AES Corporation, LG Energy Solution, Samsung SDI, NextEra Energy, Powin Energy, Enphase Energy, Sonnen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Battery Energy Storage System Market Trends and Innovations
Technology trajectories in the US battery storage sector center on cell chemistry diversification, software-defined dispatch optimization, and modular system architectures that compress commissioning timelines for utility-scale deployments.
Lithium iron phosphate cell technology is fragmenting the utility-scale procurement landscape as developers prioritize cycle life over energy density. Texas and California utilities now specify LFP-dominant systems for four-hour duration projects. This chemistry shift is compressing nickel-cobalt-manganese supply chain dependencies while enabling domestic manufacturing qualification under IRA domestic content rules.
FERC Order 841 mandates wholesale market access for storage resources, compelling regional transmission organizations to reform tariff structures. The order requires ISOs and RTOs to remove barriers to storage participation in energy, capacity, and ancillary service markets. Texas and California grid operators are responding with fast-frequency response products and hybrid resource modeling protocols.
Merchant offtake structures are displacing traditional power purchase agreements as the dominant procurement model for utility-scale storage. Developers in Texas now retain merchant exposure to capture scarcity pricing while securing debt financing against contracted tolling arrangements. This shift concentrates in the ERCOT South zone where solar-storage hybrids optimize production tax credit capture with merchant energy sales.
US Battery Energy Storage System Market Segmentation
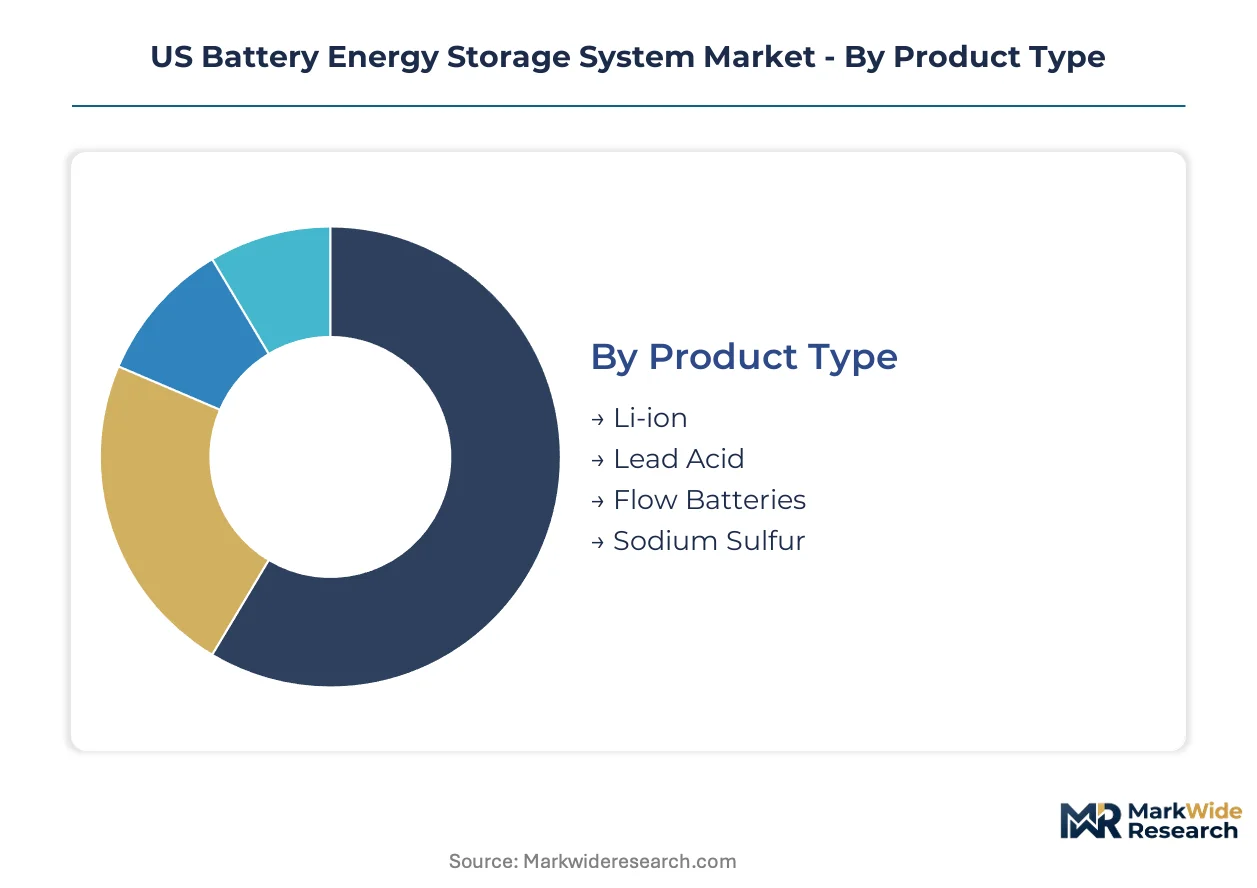
Segmentation reveals how IRA tax credit eligibility, FERC market access rules, and state resource adequacy mandates differentially shape procurement across chemistry types, installation configurations, and customer categories. Each dimension carries distinct regulatory loadings that determine project economics and deployment velocity.
Product Type:
FERC Order 841 and IRA domestic content bonus credits create divergent qualification pathways across electrochemical architectures, with thermal safety standards and manufacturing location determining incentive capture rates.
- Li-ion:Lithium iron phosphate cells dominate utility-scale procurement due to enhanced cycle stability and thermal safety profiles. Demand concentrates in Texas and California where four-hour duration systems qualify for standalone storage ITC and ERCOT scarcity pricing events.
- Flow Batteries:Vanadium redox systems capture daily cycling applications exceeding twelve hours where lithium-ion degradation economics falter. Arizona utilities specify flow chemistry for long-duration mandates under state clean energy standards.
- Lead Acid:Mature technology retains niche presence in off-grid residential and backup power applications where capital constraints outweigh cycle efficiency requirements.
- Sodium Sulfur:High-temperature sodium-sulfur chemistry serves utility-scale bulk storage in isolated grid configurations requiring multi-hour discharge duration.
Li-ion handles the majority of throughput; flow batteries are expanding most quickly on share as long-duration procurement accelerates.
Application:
Customer scale determines revenue stacking complexity, with larger installations accessing wholesale market products under FERC Order 841 while smaller assets aggregate through virtual power plant platforms.
- Utility-Scale:Front-of-the-meter projects exceeding 100 MW absorb the majority of capital deployment, leveraging merchant offtake structures in ERCOT and contracted tolling in CAISO to optimize IRA tax credit capture with wholesale market participation.
- Commercial:Behind-the-meter installations at industrial facilities and data centers aggregate through FERC Order 2222-compliant platforms for wholesale market access, with peak shaving and demand charge management driving adoption in high-electricity-cost states.
- Residential:Home battery systems trail utility-scale deployment due to interconnection backlogs and net metering restructuring in California and Arizona, though IRA residential clean energy credits sustain installation growth.
- Microgrid:Islanded or semi-islanded systems serve critical infrastructure, military installations, and remote communities where grid reliability failures or absence of transmission infrastructure create standalone economic cases.
Utility-scale commands deployment volume; commercial aggregation is gaining share fastest as virtual power plant platforms scale.
Installation Type:
Physical configuration shapes project development timelines, with modular architectures compressing commissioning schedules and hybrid designs optimizing co-located renewable capture.
- Containerized:Factory-integrated DC-block architectures accelerate site commissioning by reducing field assembly requirements. Texas and Arizona developers specify containerized systems to meet ERCOT and APS procurement deadlines.
- On-grid:Grid-connected installations dominate the addressable market, requiring interconnection agreements with regional transmission organizations and compliance with NERC reliability standards.
- Hybrid:Co-located solar-plus-storage configurations optimize production tax credit stacking with standalone storage ITC, concentrating in ERCOT South and California Imperial Valley where solar resource quality supports merchant revenue models.
- Off-grid:Standalone systems serve remote or reliability-constrained locations where transmission extension costs exceed battery capital expenditure, including rural Texas counties and Arizona tribal lands.
On-grid handles the majority of throughput; containerized formats are climbing the fastest on share as developers prioritize schedule compression.
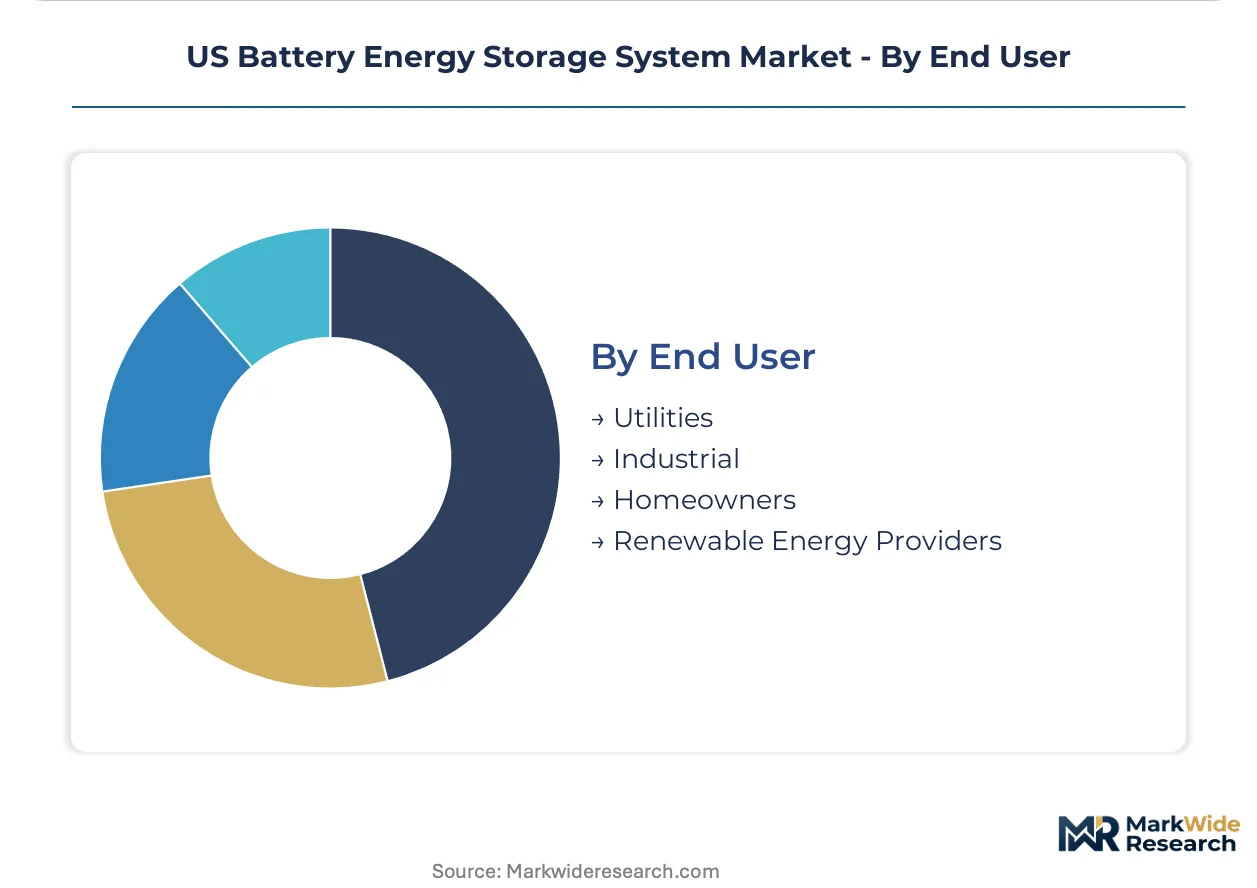
End User:
Procurement authority and balance sheet capacity segment the customer base, with regulated utilities leveraging cost-of-service recovery while competitive retailers and industrials pursue merchant exposure.
- Utilities:Investor-owned and public power utilities drive front-of-the-meter procurement through integrated resource plans and resource adequacy obligations, with California IOUs and Texas municipal utilities leading deployment.
- Renewable Energy Providers:Solar and wind developers co-locate storage to firm renewable output and capture IRA tax credit synergies, with Texas and Arizona renewable portfolios expanding fastest.
- Industrial:Manufacturing, data center, and mining operations deploy behind-the-meter storage for peak shaving, power quality, and backup power, with Texas petrochemical facilities and Arizona semiconductor fabs representing concentrated demand.
- Homeowners:Residential customers purchase systems through solar installers and direct-to-consumer channels, with California NEM 3.0 transition and Texas grid instability events sustaining interest despite interconnection delays.
Utilities handle the majority of throughput; renewable energy providers are gaining share fastest as solar-plus-storage hybrids proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with Texas municipal utilities, California investor-owned utilities, and Arizona public power districts. Each buyer archetype operates under distinct regulatory frameworks and resource adequacy obligations. Geographic deployment patterns track grid instability events, renewable curtailment zones, and state-level clean energy mandates.
Texas
ERCOT's energy-only market design enables uncapped price capture during scarcity events. The Public Utility Commission of Texas mandates winter storm preparedness standards that accelerate storage procurement. ERCOT West and South zones host concentrated deployment of four-hour duration systems serving solar-storage hybrids.
California
CAISO's duck curve challenges and renewable curtailment create urgent dispatch needs for evening peak shifting. The California Public Utilities Commission enforces resource adequacy obligations that translate directly to storage procurement targets. Imperial Valley and Central Valley clusters concentrate solar-plus-storage development optimizing IRA tax credit stacking.
Arizona
Arizona Public Service and Salt River Project procurement targets drive utility-scale deployment. The Arizona Corporation Commission imposes clean energy standards that mandate storage paired with renewable generation. Phoenix-Tucson corridor installations prioritize containerized systems for accelerated commissioning timelines.
Florida
Florida Power & Light and Duke Energy Florida integrate storage for hurricane resilience and peak demand management. The Florida Public Service Commission approves cost recovery mechanisms for grid modernization investments. Southeast Florida industrial zones deploy behind-the-meter systems for critical facility backup power.
New York
New York State Energy Research and Development Authority programs subsidize storage deployment for grid congestion relief. The New York Public Service Commission implements the Accelerated Renewable Energy Growth and Community Benefit Act storage targets. Long Island and Hudson Valley projects address transmission constraints into New York City load centers.
US Battery Energy Storage System Market Competitive Landscape
Player mix skews toward integrated cell manufacturers and independent power producers with captive development arms. Market structure concentrates around vertically integrated specialists controlling cell supply and software-defined dispatch platforms. Two strategic archetypes dominate: automotive-heritage cell producers leveraging manufacturing scale, and pure-play storage developers optimizing merchant revenue stacking. Competitive moves center on domestic manufacturing qualification for IRA domestic content bonus credits and strategic partnerships with regional transmission organizations for interconnection queue priority.
Within the integrated manufacturing tier, Tesla and LG Energy Solution represent archetypes of cell-to-system vertical control. Fluence Energy and Powin Energy exemplify independent system integrators competing through proprietary software architectures. NextEra Energy anchors the utility-affiliated developer segment with balance sheet capacity for merchant exposure.
| Leading Market Players |
|---|
| Tesla |
| Fluence Energy |
| The AES Corporation |
| LG Energy Solution |
| Samsung SDI |
| NextEra Energy |
| Powin Energy |
| Enphase Energy |
| Sonnen |
| Others |
Pricing and Supply Chain Analysis
Gigafactory-scale cell production in Nevada and Michigan compresses unit economics for domestic module assembly, concentrating procurement leverage with vertically integrated manufacturers while establishing price floors that independent system integrators struggle to match. IRA domestic content bonus credits amplify this scale advantage, rewarding projects that source North American-manufactured cells with incremental tax equity value that reshapes competitive bidding dynamics.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate utility-scale procurement, tying system pricing to Shanghai Metal Market benchmarks that introduce volatility into developer margins. Price differentiation rests on UL 9540A fire safety certification tier and after-sales service bundling, with certified premium systems commanding spreads over uncertified alternatives. Cost compression in the containerized segment is intensifying because module oversupply from Asian cell manufacturers feeds into aggressive EPC bidding. Merchant developers exhibit the least price sensitivity, prioritizing dispatch software capability over capital expenditure, while municipal utilities face hard budget constraints that force value engineering.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and Port of Houston fluctuate with container availability on the transpacific trade lane, injecting uncertainty into landed cost forecasts for imported power conversion systems. Cell supply concentrates in China, South Korea, and Japan, with North American cathode active material production scaling slowly in Tennessee and Quebec. The supply chain draws from lithium brine operations in Chile and Argentina, nickel laterite from Indonesia, and graphite from China. Single-source vulnerability in semiconductor-grade silicon carbide for inverters poses structural risk. Distribution runs through regional EPC contractors and direct OEM relationships with utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US battery storage market rewards firms that control scarce capabilities in power electronics engineering and interconnection queue navigation, with talent gaps in inverter design and FERC tariff expertise constraining expansion velocity for undercapitalized entrants.
For Market Incumbents: Shield market position through captive cell supply agreements with qualified domestic manufacturers and accelerated UL 9540A certification investment for novel pack architectures. The threat of merchant revenue compression from oversupplied ERCOT zones demands defensive consolidation of software-defined dispatch capabilities. Vertical integration into power conversion system design represents the critical lever for margin defense. For New Entrants and Emerging Players: Differentiate on long-duration flow battery chemistry for Arizona and California utility mandates exceeding eight-hour discharge requirements. The commercial behind-the-meter segment offers the most penetrable white space, with data center and semiconductor fab demand outpacing incumbent coverage. A software-first go-to-market angle, aggregating distributed assets through FERC Order 2222-compliant virtual power plant platforms, bypasses capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent power producers with contracted tolling arrangements and merchant trading desks, offering superior cash flow quality against pure hardware OEMs. Long-term viability over the next decade hinges on domestic content qualification and interconnection queue priority. Acquisition targets should exhibit captive development pipelines and software dispatch platforms. The signal to watch is FERC interconnection reform implementation, which would accelerate commercial operation dates and unlock trapped project value.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cell Manufacturing Buildout | Qualifies projects for IRA domestic content bonus credits and reduces tariff exposure. |
| Power Purchase Agreement Restructuring | Enables merchant revenue stacking with contracted floor pricing in ERCOT zones. |
| Software Dispatch Platform Licensing | Captures recurring revenue from optimized wholesale market participation across multiple ISOs. |
| Long-Duration Chemistry Partnership | Positions developers for Arizona and California mandates exceeding lithium-ion economic thresholds. |
| Interconnection Queue Priority Acquisition | Accelerates commercial operation dates and reduces carrying cost drag on capital deployment. |
Research Methodology
The analysis maps front-of-the-meter utility-scale, commercial behind-the-meter, residential, and microgrid deployment configurations, each validated through utility planning officers, independent power producer project developers, EPC contractors, and grid operators. Primary interviews with FERC tariff specialists and IRA tax equity advisors combined with secondary validation against EIA project databases, FERC interconnection filings, and state public utility commission procurement orders. Bottom-up project-level capacity aggregation and top-down macroeconomic scenario triangulation ensure cross-verified output consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation by electrochemical chemistry, application scale, installation configuration, and end-user procurement authority, with regional grid type and state regulatory framework as cross-cutting dimensions. CAGRs derive from capacity deployment curves, capital cost learning rates, and revenue stack evolution under FERC Order 841 implementation. Forecast inputs include interconnection queue velocity, domestic manufacturing capacity buildout timelines, and ERCOT scarcity pricing frequency.
The analysis sits within stated boundaries; outcomes outside sustained IRA credit extension, FERC market access rule enforcement, and lithium price stability would require recalibration. Forecasts reflect documented assumptions regarding interconnection reform progress and domestic cell supply scaling. Supply chain disruption, tariff regime shifts, or NERC cybersecurity standard escalation could materially revise deployment trajectories. Recalibration cycles align with material shifts in federal tax credit policy and regional transmission organization tariff reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Storage Inverter Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Ultracapacitors Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Australia Energy Storage Systems (ESS) Market