
 Africa Small Hydropower Market | 2026-2036
Africa Small Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Small Hydropower Market Outlook
Long-term operations and maintenance contracts is restructuring how equipment vendors monetize Africa's small hydropower fleet, shifting revenue from capital sales to recurring service streams. Voith Group leverages its regional service hubs to capture aftermarket revenue across East African installations. Statkraft anchors its competitive position through run-of-river expertise developed on Norwegian cascades adapted to African topography. General Electric competes by extending its digital hydro monitoring platform to remote African sites with limited grid connectivity.
Small hydropower denotes electricity generation facilities typically below 10 MW capacity utilizing flowing or stored water to drive turbines, with penstock materials ranging from welded steel to high-density polyethylene depending on head pressure and site accessibility. Run-of-river technology dominates African deployments due to lower civil works requirements and reduced environmental displacement compared with reservoir-based alternatives. Off-grid installations represent the fastest-growing installation type as rural electrification agencies prioritize standalone and hybrid configurations serving communities beyond centralized grid reach. The 101-500 kW capacity band captures concentrated margin pools where equipment standardization meets meaningful revenue per site.
Ethiopia's Ministry of Water and Energy, Uganda's Electricity Regulatory Authority, and Rwanda's Energy Group collectively shape market access through licensing frameworks, feed-in tariff structures, and environmental impact thresholds for sub-10 MW developments. These bodies increasingly require local content provisions and technology transfer commitments as conditions for generation permits. Stakeholders must monitor how evolving grid codes and cross-border power pool integration protocols redefine the economic viability of isolated versus interconnected small hydro assets.
Market Dynamics
Federal cascade development mandates in Ethiopia are compressing project timelines for sub-10 MW installations, while cross-border power pool protocols reshape interconnection economics across East African utilities.
Growth Catalysts
- Rural electrification frameworks:Kenya's Last Mile Connectivity Program and similar initiatives in Tanzania prioritize standalone mini-hydro for agricultural cooperatives requiring irrigation power.
- Ethiopia:Federal dam authorities now mandate renewable quotas in distributed generation procurement, accelerating tributary system developments below 10 MW.
- HDPE penstock materials:High-density polyethylene is displacing welded steel in remote sites with limited road access, reducing civil works requirements and installation labor.
Market Restraints
- Equipment supply concentration:European turbine manufacturers dominate precision casting capacity, creating lead-time vulnerability for African project developers.
- Local content mandates:Ethiopia's Ministry of Water and Energy requires technology transfer commitments that extend permitting timelines beyond 18 months.
- Grid integration standards:Evolving grid codes for cross-border power pool participation impose synchronization costs on isolated run-of-river assets.
Strategic Opportunities
- Rwanda:Rwanda Energy Group's feed-in tariff restructuring creates white space for hybrid solar-hydro configurations serving tea processing cooperatives.
- Digital monitoring convergence:Remote telemetry platforms combined with predictive maintenance algorithms reduce OPEX for off-grid installations with limited technician access.
- Uganda's licensing streamlining:The Electricity Regulatory Authority's revised environmental impact thresholds below 500 kW compress approval cycles for micro-hydro developers.
Industry Challenges
- Civil engineering skill scarcity:Qualified hydrological surveyors and intake structure specialists command premium wages across East African project sites.
- Legacy grid synchronization:Aging transmission infrastructure in rural Uganda and Tanzania requires costly frequency stabilization equipment for interconnected small hydro assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Small Hydropower Market |
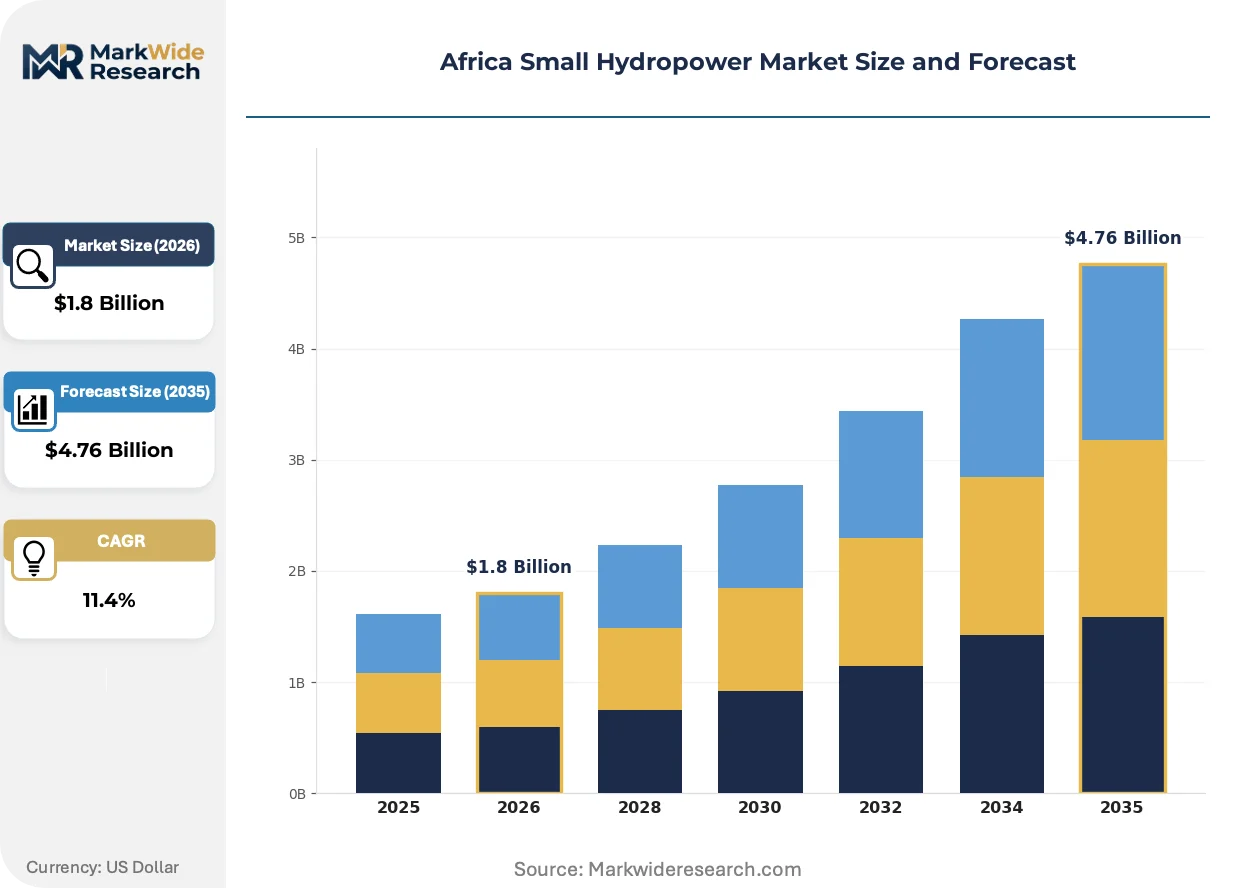
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Run-of-River, Reservoir-Based, Pumped Storage, Micro-Hydro End User: Agriculture, Industrial, Residential, Utilities Installation Type: On-Grid, Off-Grid, Standalone, Hybrid Capacity: 1-10 kW, 11-100 kW, 101-500 kW, 501-1,000 kW |
| Companies Covered | General Electric, Innergex, Statkraft, Natel Energy, SN Aboitiz Power, Voith Group, Siemens Energy, Gilbert Gilkes & Gordon Ltd, ANDRITZ, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Small Hydropower Market Strategic Shifts
Equipment standardization and digital service models are compressing cost structures while regulatory integration mandates reshape how developers structure ownership and O&M contracts across the continent.
Modular turbine-generator packages with factory-integrated control systems are overtaking site-assembled configurations in the 101-500 kW band. Agricultural cooperatives in Kenya and Tanzania are specifying these skid-mounted units to minimize on-site mechanical commissioning. The shift is overtaking traditional EPC contracting models and enabling developer-operators to retain long-term service revenue streams.
Uganda's Electricity Regulatory Authority has mandated standardized interconnection protocols for mini-grid assets feeding into the national grid. The framework requires synchronous generation equipment and remote dispatch capability, increasing capital outlays for run-of-river developers. Projects above 1 MW capacity face the steepest compliance adjustments as they must integrate with the regional power pool.
After-sales service unbundling is fragmenting traditional EPC relationships as equipment vendors separate hardware supply from long-term O&M contracts. East African utilities and agricultural cooperatives now negotiate performance-based service agreements independent of initial capital procurement. Rwanda's tea sector exhibits the most pronounced shift, with processors demanding guaranteed availability clauses rather than warranty coverage alone.
Africa Small Hydropower Market Segmentation
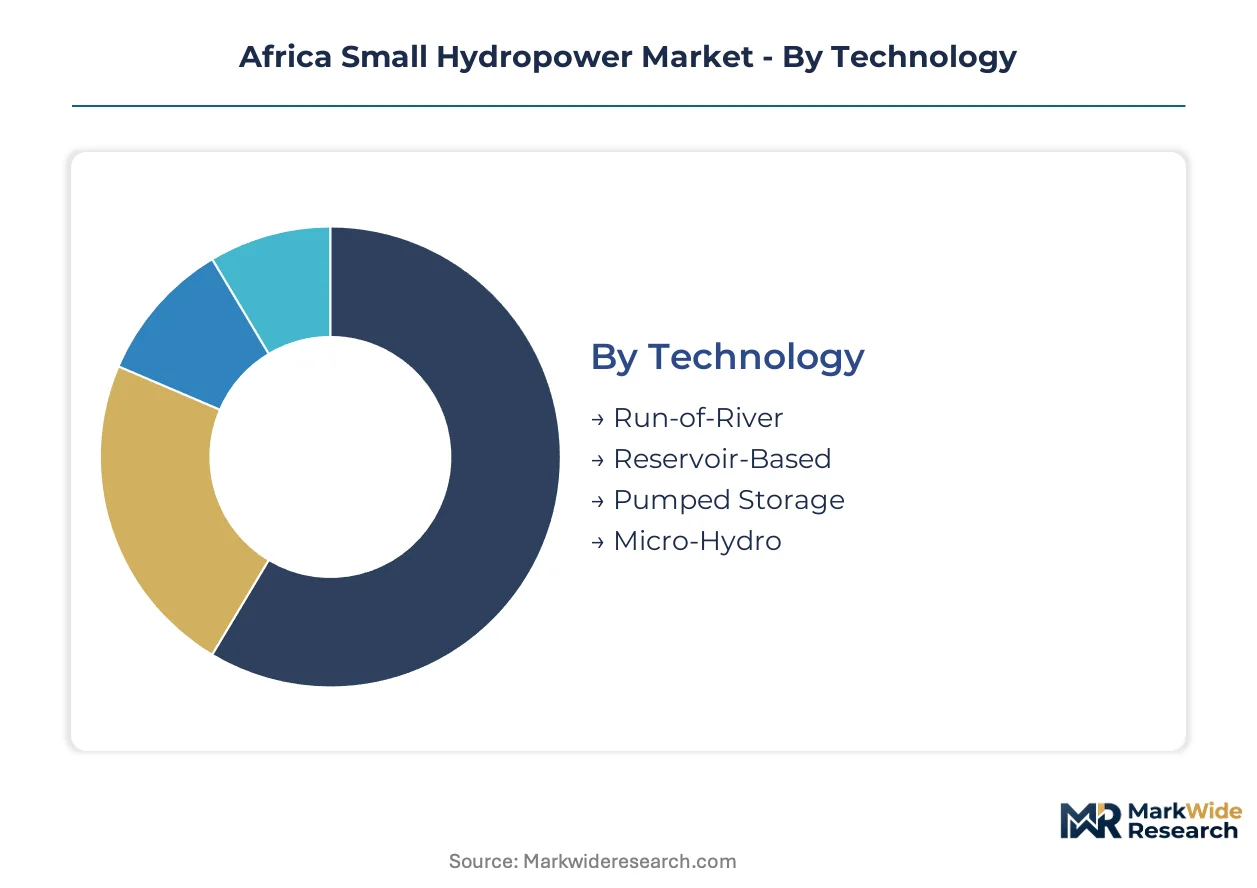
Technology choice determines civil works intensity and environmental permitting complexity across African small hydropower deployments. Installation type and capacity band selections directly shape financing structures and offtake contract terms for rural electrification projects.
Technology:
Technology selection governs head pressure requirements, seasonal flow variability tolerance, and sediment handling capabilities in African river systems.
- Run-of-River:Harnesses natural river flow without large impoundment, utilizing intake weirs and diversion channels to feed penstock systems. Ethiopian federal dam authorities prioritize this technology for tributary cascade developments below 10 MW, where reduced resettlement costs accelerate federal permitting timelines.
- Reservoir-Based:Creates artificial impoundments to store water and regulate generation output against seasonal inflow variation. Uganda's Electricity Regulatory Authority imposes stricter environmental impact thresholds on these installations, extending approval cycles beyond 18 months for developments above 500 kW.
- Pumped Storage:Reversible turbine configurations that pump water to upper reservoirs during off-peak periods for later generation release. Kenya's agricultural cooperatives rarely specify this technology due to dual civil works requirements and limited grid arbitrage opportunities in rural mini-grid contexts.
- Micro-Hydro:Sub-100 kW installations utilizing simplified turbine designs with minimal electro-mechanical complexity. Rwanda's tea processing cooperatives favor micro-hydro for isolated factory sites where distribution infrastructure does not reach.
Run-of-River leads on scale; Micro-Hydro leads on momentum.
End User:
Customer type segmentation reveals divergent procurement behaviors between state-linked offtakers and private agricultural operators.
- Agriculture:Irrigation pumping and processing power for cooperatives and commercial farms. Kenya's Last Mile Connectivity Program targets agricultural load centers for standalone mini-hydro, where daytime irrigation demand matches solar-hybrid generation profiles.
- Industrial:Mining operations, cement plants, and tea factories requiring baseload reliability. Ethiopian industrial parks near tributary systems negotiate direct power purchase agreements with run-of-river developers, bypassing utility intermediaries.
- Residential:Rural household electrification through mini-grid distribution. Tanzania's rural energy agency prioritizes off-grid configurations for residential clusters beyond 15 kilometers from existing transmission infrastructure.
- Utilities:National and regional power utilities procuring distributed generation for grid reinforcement. Uganda's national utility integrates small hydro into the regional power pool, requiring synchronous generation equipment and remote dispatch compliance.
Agriculture dominates installed capacity; Industrial commands premium tariffs.
Installation Type:
Grid integration status determines capital cost structures, revenue certainty, and equipment specification requirements for African developers.
- On-Grid:Direct interconnection with national or regional transmission infrastructure. Rwanda Energy Group's feed-in tariff restructuring favors on-grid configurations above 1 MW that can dispatch into the East African Power Pool.
- Off-Grid:Isolated generation serving discrete load centers without utility interconnection. Tanzania's rural electrification framework designates off-grid as the fastest-expanding installation category for communities beyond centralized grid reach.
- Standalone:Single-purpose generation assets dedicated to individual offtakers such as mines or factories. Ethiopian mining concessions increasingly specify standalone run-of-river plants to secure power supply independent of grid reliability.
- Hybrid:Combined solar, battery, and small hydro configurations optimizing renewable complementarity. Kenya's agricultural cooperatives specify hybrid systems to match irrigation pumping schedules with solar availability while maintaining hydro backup.
Off-Grid captures volume growth; Hybrid gains share fastest.
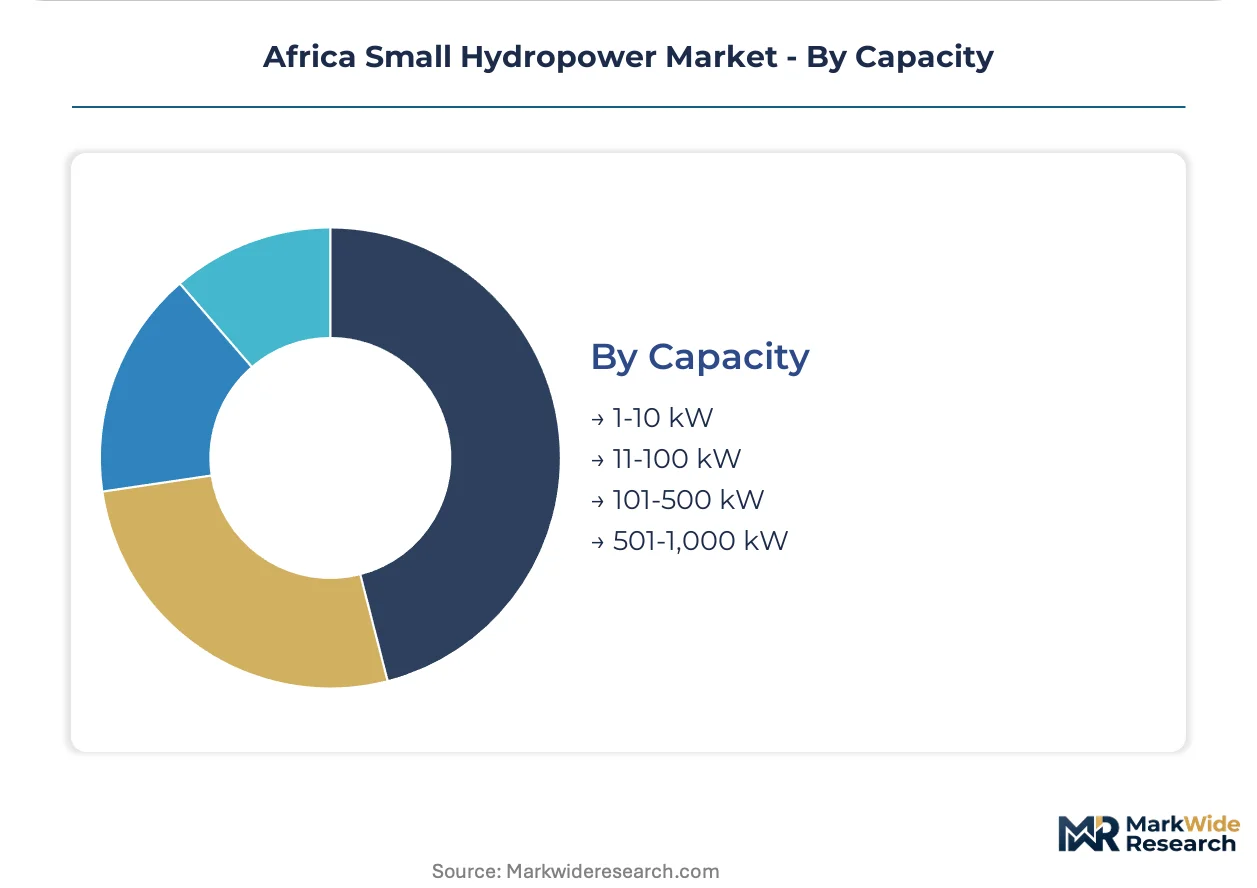
Capacity:
Scale thresholds trigger distinct regulatory pathways, equipment standardization opportunities, and financing instrument availability.
- 1-10 kW:Pico-hydro installations serving individual households or small community facilities. Rwanda's micro-hydro licensing exemptions apply to this band, compressing approval timelines below six months.
- 11-100 kW:Small commercial and community-scale generation with standardized turbine packages. Ugandan environmental impact thresholds exempt developments below 100 kW from full environmental and social impact assessments.
- 101-500 kW:The concentrated margin pool where factory-integrated skid-mounted turbine-generator packages achieve meaningful revenue per site. Ethiopian agricultural cooperatives specify this band for irrigation pumping stations requiring 200-400 kW continuous output.
- 501-1,000 kW:Mini-utility scale approaching regulatory thresholds for full licensing and grid code compliance. Tanzania's rural electrification agency channels development finance toward this band for district-level mini-grid anchors.
101-500 kW leads on commercial density; 501-1,000 kW shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethiopia's cascade development mandates contrast with Rwanda's feed-in tariff restructuring, revealing divergent policy pathways across East African small hydropower markets. Kenya and Tanzania pursue rural electrification through standalone mini-grids, while Uganda streamlines licensing for micro-hydro developers. These national frameworks collectively reshape procurement patterns for sub-10 MW installations.
Ethiopia
Federal dam authorities prioritize tributary system developments below 10 MW, where reduced resettlement costs accelerate permitting timelines. The Ministry of Water and Energy mandates local content provisions and technology transfer commitments as conditions for generation permits. Industrial parks near the Blue Nile tributaries negotiate direct power purchase agreements with run-of-river developers, bypassing utility intermediaries.
Kenya
Agricultural cooperatives drive demand for irrigation pumping stations in the 200-400 kW range, matching daytime load profiles with solar-hybrid configurations. The Last Mile Connectivity Program channels development finance toward standalone mini-hydro serving agricultural load centers. Tea processing clusters in the Rift Valley specify skid-mounted turbine-generator packages to minimize on-site mechanical commissioning.
Uganda
The Electricity Regulatory Authority's revised environmental impact thresholds exempt developments below 100 kW from full environmental and social impact assessments. Licensing streamlining compresses approval cycles for micro-hydro developers targeting rural electrification. Aging transmission infrastructure in the Western Region requires costly frequency stabilization equipment for interconnected small hydro assets feeding the regional power pool.
Rwanda
Rwanda Energy Group's feed-in tariff restructuring creates white space for hybrid solar-hydro configurations serving tea processing cooperatives. Micro-hydro licensing exemptions apply to sub-100 kW installations, compressing approval timelines below six months. Isolated factory sites in the Northern Province favor micro-hydro where distribution infrastructure does not reach.
Tanzania
The rural energy agency designates off-grid as the fastest-expanding installation category for communities beyond 15 kilometers from existing transmission infrastructure. Development finance channels toward the 501-1,000 kW band for district-level mini-grid anchors. Agricultural cooperatives in the Southern Highlands specify hybrid systems to match irrigation pumping schedules with solar availability.
Africa Small Hydropower Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with European turbine manufacturers dominating precision casting capacity while regional service hubs capture aftermarket revenue. The vendor base concentrates around three strategic archetypes: integrated industrial conglomerates with digital monitoring platforms, run-of-river specialists leveraging cascade expertise, and modular equipment fabricators supplying skid-mounted packages. Competitive moves center on long-term operations and maintenance contract unbundling and geographic expansion through regional service hub establishment.
Within the integrated industrial tier, General Electric exemplifies the digital convergence archetype through remote monitoring platform extension. Voith Group and Statkraft occupy distinct positions in the service and run-of-river specialization vectors respectively. These three companies represent the competitive positioning spectrum from capital equipment supply through recurring service revenue capture.
| Leading Market Players |
|---|
| General Electric |
| Innergex |
| Statkraft |
| Natel Energy |
| SN Aboitiz Power |
| Voith Group |
| Siemens Energy |
| Gilbert Gilkes & Gordon Ltd |
| ANDRITZ |
| Others |
Value Chain & Pricing Dynamics
HDPE penstock adoption across remote East African sites is simultaneously compressing installed cost curves and fragmenting procurement leverage among project developers. This materials transition redraws supplier power dynamics while federal local-content mandates in Ethiopia force technology transfer commitments that extend permitting timelines beyond eighteen months.
Pricing Analysis
Capacity additions in Ethiopia are reshaping price floors for run-of-river turbine packages as federal cascade mandates accelerate tributary developments below ten megawatts. Project-based contracting dominates, with price differentiation resting on equipment standardization levels and after-sales service bundling. Cost compression in the one-hundred-one to five-hundred-kilowatt band is intensifying because factory-integrated skid-mounted configurations displace site-assembled alternatives. Agricultural cooperatives exhibit highest price sensitivity, while mining concessions commanding standalone configurations tolerate premium positioning.
Supply Chain Analysis
Freight costs from European turbine manufacturers to East African project sites consume disproportionate capital budgets given limited precision casting capacity outside Germany, Austria, and Switzerland. Equipment supply draws from welded steel and high-density polyethylene penstock producers, synchronous generation component fabricators, and digital monitoring platform developers. Single-source vulnerability concentrates in precision turbine casting capacity controlled by European specialists. Distribution runs through EPC contractors and emerging developer-operators retaining long-term service revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa small hydropower market compounds steadily as rural electrification agencies channel development finance toward off-grid configurations beyond centralized grid reach.
For Market Incumbents: Lock in aftermarket revenue through regional service hub establishment before modular equipment fabricators capture long-term O&M contracts. Defend against Voith Group's service network expansion by anchoring predictive maintenance algorithms to remote telemetry platforms. Prioritize technology transfer partnerships satisfying Ethiopia's Ministry of Water and Energy local-content mandates. For New Entrants and Emerging Players: Digital-channel routes through remote monitoring platform licensing offer lowest-friction entry into established EPC relationships. Target Rwanda's tea processing cooperatives demanding guaranteed availability clauses rather than warranty coverage alone. Penetrate Uganda's micro-hydro licensing streamlining below one hundred kilowatts where environmental impact exemptions compress approval cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among modular equipment fabricators supplying skid-mounted turbine-generator packages to agricultural cooperatives. Long-term viability frames around recurring service revenue capture displacing capital sales dependency. Monitor Ethiopia's federal cascade development mandates as inflection indicator for tributary system procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Hub Establishment | Voith Group leverages East African hubs to capture aftermarket revenue across installed base. |
| Technology Transfer Partnership | Equipment vendors satisfy Ethiopia's Ministry of Water and Energy permitting conditions through local-content commitments. |
| Digital Monitoring Platform Extension | General Electric extends remote telemetry capabilities to sites with limited grid connectivity. |
| Hybrid Configuration Development | Kenya's agricultural cooperatives specify solar-hydro systems matching irrigation pumping schedules. |
| Micro-Hydro Licensing Streamlining | Uganda's Electricity Regulatory Authority exempts sub-one-hundred-kilowatt developments from full impact assessments. |
Study Parameters
Bottom-up agricultural cooperative demand modeling reconciled against top-down equipment supply tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combine with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation between stakeholder demand signals and manufacturer capacity disclosures ensures segmentation integrity.
Historical trendline analysis across capacity installations, technology adoption patterns, and regulatory approval timelines informs projection frameworks. Segmentation dimensions modeled span technology type, installation configuration, capacity tier, and end-use sector across the analysis window. CAGRs derive from fitted trend extrapolation adjusted for federal mandate acceleration and licensing streamlining impacts. Forecast inputs incorporate run-of-river deployment velocity and HDPE penstock substitution rates.
Regulatory reversal, equipment supply disruption, and grid integration standard evolution are the dominant revision risks to projection assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
United States Hydro Turbine Market