
 United States Hydropower Market | 2026-2036
United States Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hydropower Market Analytics
The Inflation Reduction Act is consolidating investment tax credit eligibility around projects with environmental compliance certifications. Duke Energy Corporation leverages its regulated utility footprint to anchor pumped storage development across the Southeast. NextEra Energy competes through vertical control over development, construction, and long-term power purchase agreements. GE Renewable Energy specializes in digital turbine upgrades that extend asset life without greenfield construction.
United States hydropower encompasses turbine-generator sets, penstock systems, and control infrastructure that convert gravitational water flow into grid-synchronous electricity, typically operating at 50-60 Hz with head heights ranging from low-head run-of-river installations below 30 meters to high-head reservoir systems exceeding 300 meters. Pumped storage technology dominates new capacity additions due to its grid stabilization function, while run-of-river installations occupy mature watersheds where environmental review constrains greenfield development. Retrofit and upgrade installations concentrate margin pools as owners seek to boost output from existing dams without triggering new federal permitting cycles.
FERC licensing requirements and EPA Clean Water Act Section 404 permits shape project timelines and capital commitments across all development categories. The Department of Energy's Grid Deployment Authority and state renewable portfolio standards in California, New York, and Colorado create overlapping compliance obligations that filter project economics. Stakeholders must monitor FERC's evolving approach to closed-loop pumped storage exemptions and state-level storage procurement mandates to align capital allocation with the fastest regulatory pathways.
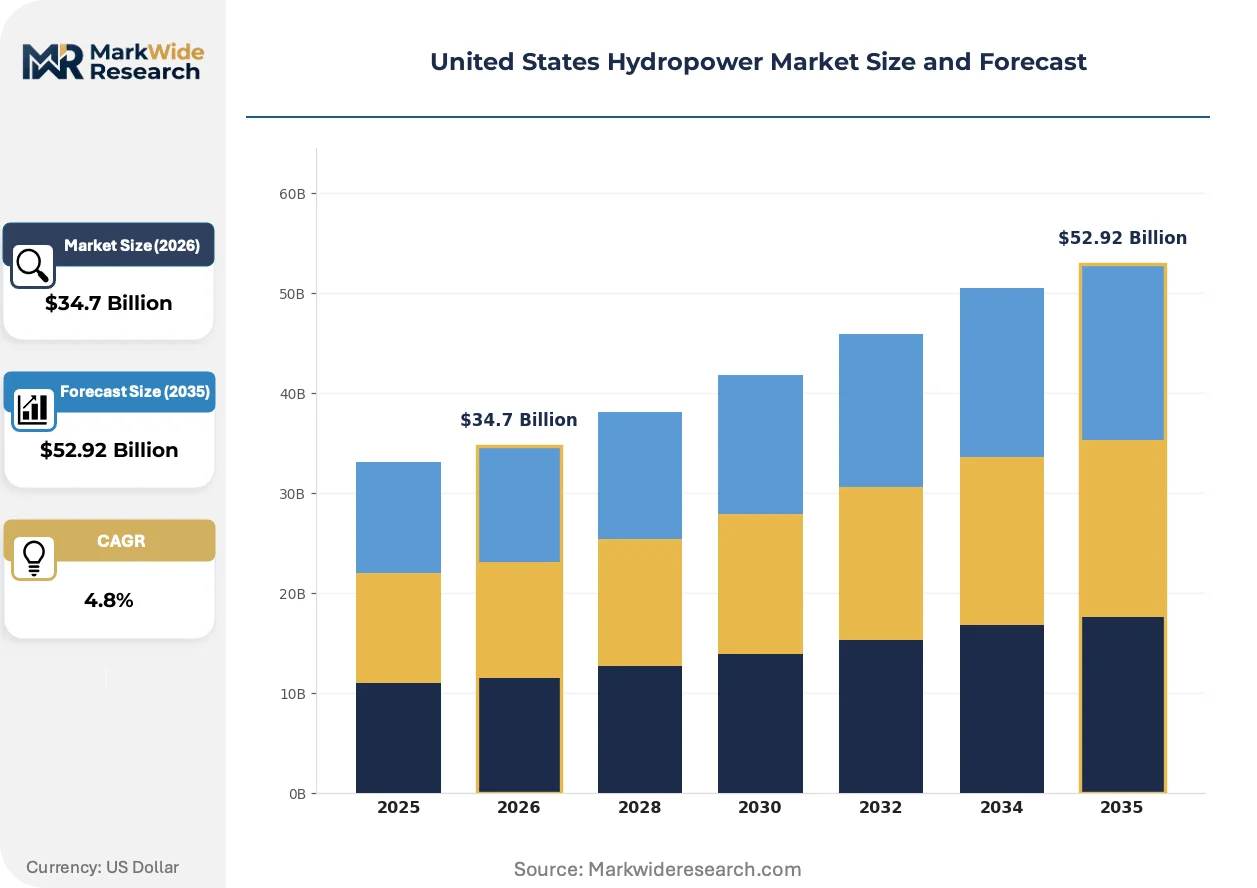
Market Dynamics
FERC's streamlined licensing framework for closed-loop pumped storage is compressing project approval timelines from years to months, redirecting capital toward retrofit cycles rather than greenfield construction.
Growth Catalysts
- Grid Modernization Mandates:Public utilities in the Pacific Northwest are channeling rate-base investments into capacity additions at existing federal hydropower sites, bypassing new environmental review cycles.
- California RPS Storage Procurement:State-level renewable portfolio standards now embed pumped storage eligibility, creating guaranteed offtake channels for developers with operational assets.
- Closed-Loop Exemption Pathway:FERC's categorical exclusion for closed-loop pumped storage eliminates individual licensing requirements, accelerating project finance timelines.
Market Restraints
- Steel and Concrete Input Volatility:Penstock fabrication and dam construction face commodity price swings that erode fixed-price EPC contract margins.
- Environmental Review Concentration:EPA Clean Water Act Section 404 permits remain concentrated in Army Corps district offices with backlogged application queues.
- Intermittent Generation Substitution:Utility-scale solar-plus-storage bids are capturing peak-shaving contracts that historically flowed to pumped storage developers.
Strategic Opportunities
- Southeastern RTO Formation:Emerging organized capacity markets in the Carolinas and Southeast create new revenue streams for grid-stabilizing assets.
- Digital Turbine Retrofits:Sensor-embedded runner replacements and AI-driven flow optimization enable output gains without structural modifications.
- Inflation Reduction Act Tax Credits:Investment tax credit eligibility for projects with environmental compliance certifications lowers effective capital costs.
Industry Challenges
- Specialized Turbine Machinist Shortage:The workforce capable of precision casting and welding for Francis and Kaplan runners is aging out without sufficient apprenticeship pipeline replacement.
- Legacy Control System Integration:Digital governor retrofits must interface with electromechanical protection relays installed decades prior, creating commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hydropower Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Run-of-River, Pumped Storage, Reservoir, Small-Scale Application: Utility-Scale Generation, Distributed Generation, Off-Grid Solutions, Ancillary Services Installation Type: New Build, Retrofit, Upgrade, Expansion End User: Public Utilities, Independent Power Producers, Industrial Users, Government Entities |
| Companies Covered | GE Renewable Energy, Siemens Energy AG, Andritz AG, Voith GmbH & Co. KGaA, Duke Energy Corporation, Pg&E Corp, Georgia Power Company, NextEra Energy, Avangrid, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hydropower Market Evolving Landscape
Digitalization of hydropower assets is compressing maintenance cycles and enabling predictive interventions that extend mechanical component life beyond original design specifications.
Variable-speed pump-turbine technology is consolidating grid stabilization functions previously split across multiple asset classes. Independent system operators with high renewable penetration are procuring these units for frequency regulation services. The technology is consolidating market share in projects where rapid ramping capability commands capacity market premiums.
FERC's integrated licensing process reforms are compressing the timeline between preliminary permit and construction authorization for closed-loop facilities. Developers in the Pacific Northwest and Rocky Mountain states are routing projects through this pathway to avoid individual environmental impact statements. The reform is consolidating developer interest in off-stream reservoir configurations rather than conventional riverine development.
Utility procurement departments are unbundling long-term power purchase agreements from equipment supply contracts, forcing turbine OEMs to compete on aftermarket service margins rather than upfront capital recovery. Investor-owned utilities in Texas and the Midwest are piloting availability-based contracting that transfers operational risk to service providers. This shift is most visible in markets where merchant exposure has produced volatile realized energy prices.
United States Hydropower Market Segmentation
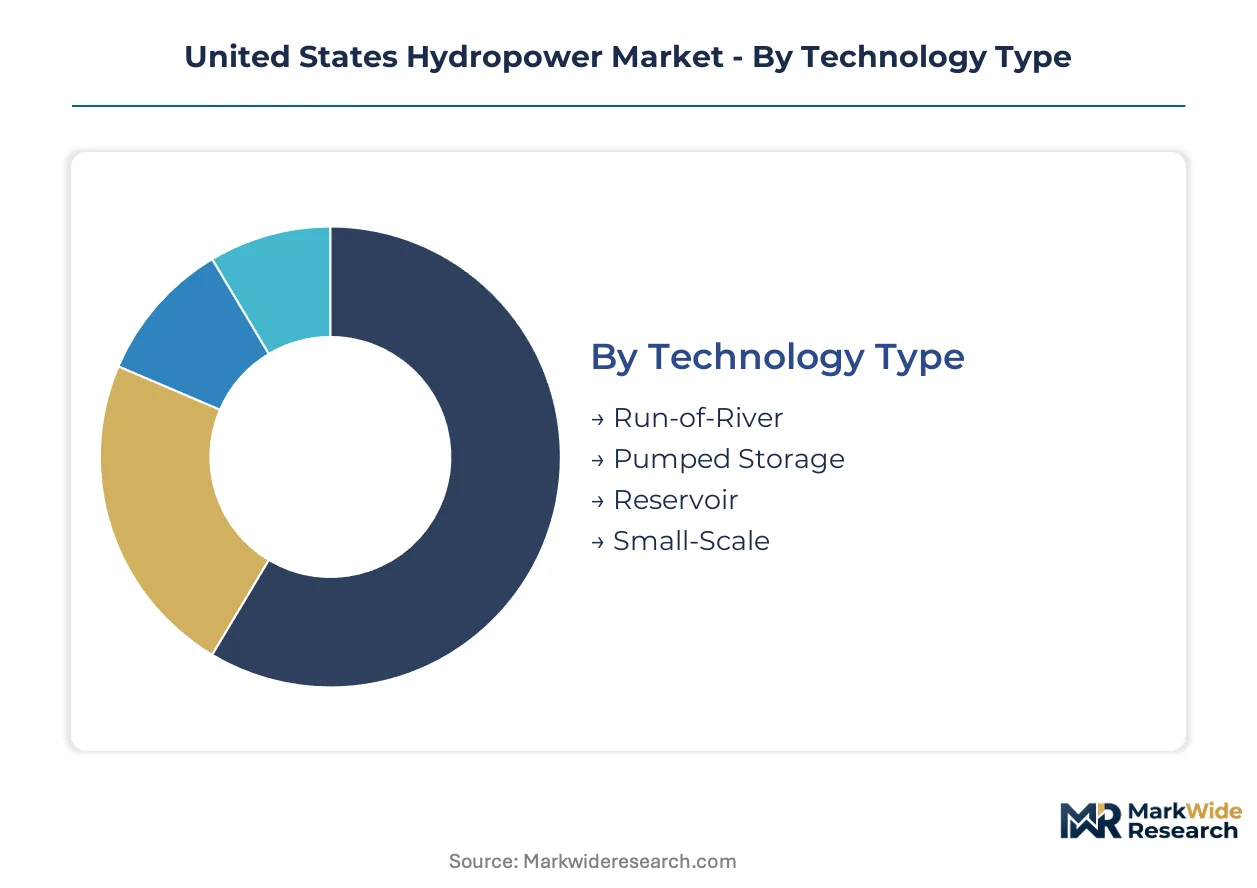
Hydropower asset segmentation determines capital recovery timelines, regulatory pathway selection, and equipment procurement strategy. Technology type governs licensing complexity while installation type dictates margin structure for engineering contractors.
Technology Type:
Volume concentrates in legacy reservoir infrastructure while premium pricing attaches to grid-stabilizing pumped storage configurations.
- Run-of-River:Continuous-flow systems operate without large impoundments, utilizing natural river gradients for base-load generation. Washington and Oregon utilities favor retrofits here to bypass new FERC environmental review cycles.
- Pumped Storage:Closed-loop configurations with upper and lower reservoirs enable load-shifting and frequency regulation services. California ISO procurement mandates are accelerating demand for these grid-stabilizing assets.
- Reservoir:Large impoundment systems dominate existing federal infrastructure across the Pacific Northwest.
- Small-Scale:Sub-10 MW installations serve distributed generation needs in rural watersheds with limited transmission access.
Mature deployment sits with reservoir systems. Newer deployment is concentrated in pumped storage.
Application:
Utility-scale generation commands the capital base while ancillary services deliver the fastest margin expansion.
- Utility-Scale Generation:Grid-synchronous installations exceeding 50 MW feed bulk power systems. Public utilities in the Pacific Northwest anchor procurement through rate-base modernization programs.
- Ancillary Services:Frequency regulation, spinning reserves, and voltage support monetize operational flexibility. ERCOT and CAISO market designs reward rapid-ramping capability with capacity premiums.
- Distributed Generation:Sub-utility scale assets serve municipal and cooperative load centers.
- Off-Grid Solutions:Remote industrial sites and isolated communities deploy run-of-river micro-installations.
Revenue stability clusters with utility-scale generation. Margin expansion is accelerating fastest in ancillary services.
Installation Type:
Retrofit cycles dominate current capital deployment while greenfield construction faces permitting headwinds.
- Retrofit:Turbine runner replacements and generator rewinds extend asset life without structural modifications. Duke Energy and NextEra Energy are channeling capital here to avoid new FERC licensing timelines.
- Upgrade:Digital governor installations and penstock efficiency improvements boost output from existing dams. GE Renewable Energy specializes in sensor-embedded runner replacements that optimize flow dynamics.
- New Build:Greenfield construction remains concentrated in closed-loop pumped storage exempt from individual FERC licensing.
- Expansion:Capacity additions at existing federal sites leverage pre-approved environmental clearances.
Capital deployment concentrates in retrofit. Upgrade installations are gaining share fastest as digital turbine technology matures.
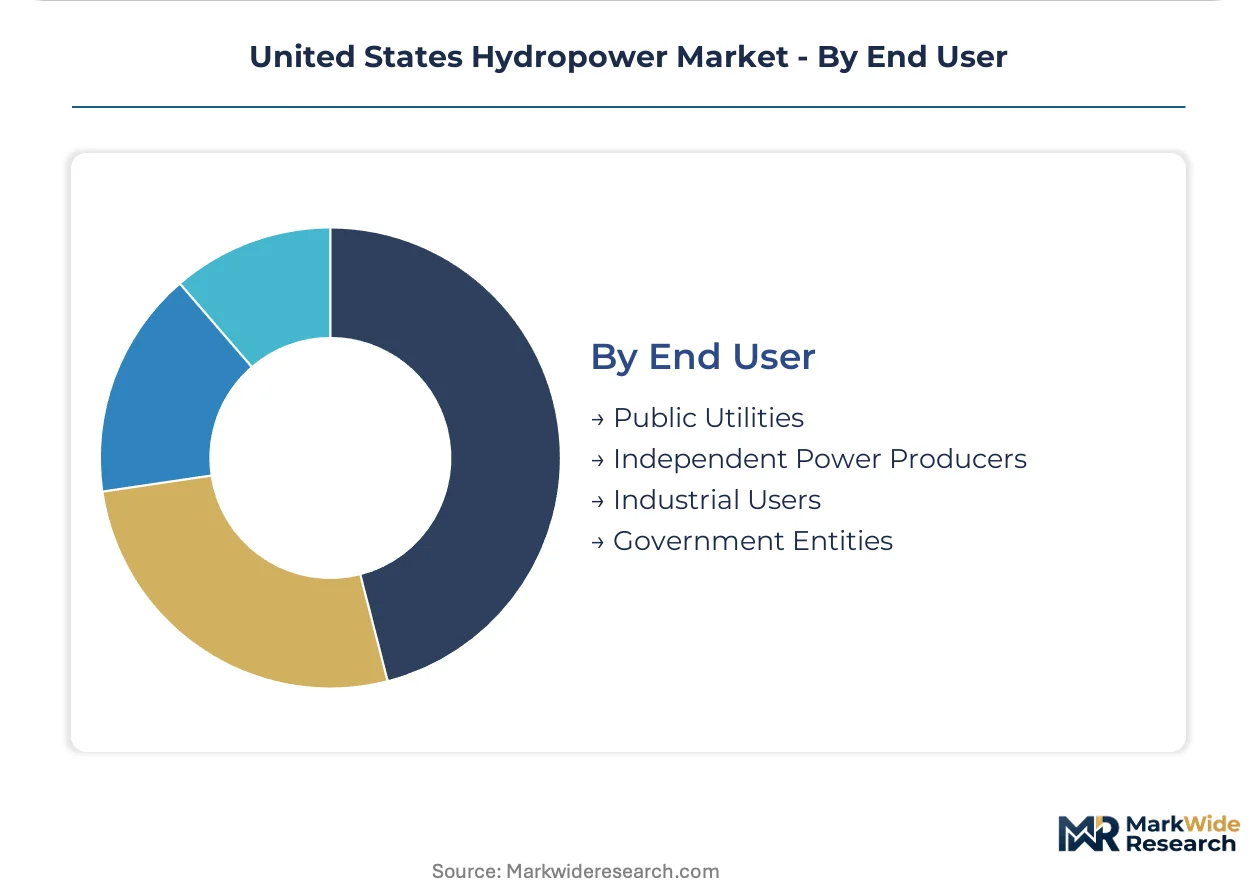
End User:
Public utilities control rate-base funding while independent power producers pursue merchant exposure.
- Public Utilities:Regulated entities deploy ratepayer-funded capital across multi-decade asset horizons. Bonneville Power Administration and Tennessee Valley Authority anchor procurement through federal infrastructure programs.
- Independent Power Producers:Merchant developers negotiate long-term power purchase agreements with offtake certainty. These entities dominate closed-loop pumped storage development in deregulated markets.
- Industrial Users:Aluminum smelters and data center operators procure behind-the-meter hydropower for load-following needs.
- Government Entities:Federal agencies and military installations pursue energy security through captive generation assets.
Project finance volume clusters with public utilities. Development velocity is accelerating fastest among independent power producers exploiting streamlined FERC exemptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment tax credits under the Inflation Reduction Act concentrate capital deployment in states with pre-existing federal hydropower infrastructure. State renewable portfolio standards create divergent procurement obligations across regional transmission organizations.
Pacific Northwest
Washington and Oregon utilities anchor retrofit spending at Bonneville Power Administration sites. FERC licensing exemptions for closed-loop pumped storage accelerate project timelines in this watershed-rich region. Seattle-based engineering firms specialize in digital turbine upgrades that bypass new environmental review cycles.
California
CAISO procurement mandates for grid-stabilizing assets drive pumped storage development in the Sierra Nevada foothills. State renewable portfolio standards embed storage eligibility, creating guaranteed offtake channels for developers. Los Angeles Department of Water and Power channels rate-base investments into capacity additions at existing federal sites.
Southeast
Carolinas and Tennessee Valley Authority territory see emerging organized capacity market formation for frequency regulation services. Duke Energy leverages its regulated utility footprint to anchor pumped storage development across this region. Atlanta-based contractors specialize in penstock fabrication for closed-loop reservoir configurations.
Southwest
Arizona and Nevada concentrate utility-scale solar-plus-storage bids that compete for peak-shaving contracts historically flowing to pumped storage. NV Energy pursues hybrid renewable-hydro procurement to meet state clean energy targets. Phoenix-area developers pilot availability-based contracting that transfers operational risk to service providers.
Mountain West
Colorado renewable portfolio standards and Wyoming wind integration needs create demand for rapid-ramping grid stabilization assets. Rocky Mountain states route closed-loop projects through FERC's streamlined licensing pathway to avoid individual environmental impact statements. Denver-based independent power producers dominate merchant development in this deregulated market segment.
United States Hydropower Market Competitive Landscape
European turbine OEMs anchor the equipment supply tier; North American utilities hold the developer-operatorship tier. The market presents a bifurcated structure with consolidated fabrication at the global level and fragmented ownership at the regional level. Three archetypes dominate: vertically integrated utilities, independent power producers, and specialized equipment vendors. Competitive moves concentrate on strategic partnerships between utilities and OEMs, plus portfolio diversification into digital retrofit services.
Among European-based fabricators, GE Renewable Energy, Siemens Energy AG, and Andritz AG occupy positions across the turbine-generator supply chain. These entities exemplify the equipment-specialist archetype that competes on aftermarket service margins rather than upfront capital recovery. Duke Energy Corporation and NextEra Energy represent the utility-developer tier, anchoring project finance through regulated rate-base mechanisms and long-term power purchase agreements. Voith GmbH & Co. KGaA sits within the precision-machining specialist segment, serving runner replacement cycles that extend asset life without structural modifications.
| Leading Market Players |
|---|
| GE Renewable Energy |
| Siemens Energy AG |
| Andritz AG |
| Voith GmbH & Co. KGaA |
| Duke Energy Corporation |
| Pg&E Corp |
| Georgia Power Company |
| NextEra Energy |
| Avangrid |
| Others |
Value Network & Pricing Analysis
Utility procurement departments unbundling long-term power purchase agreements from equipment supply contracts force turbine OEMs to compete on aftermarket service margins rather than upfront capital recovery, compressing pricing power across the equipment tier while elevating service-based revenue streams.
Pricing Analysis
Short lead-time premiums for Francis and Kaplan runner replacements command 15-25% markups over standard-schedule fabrication, while spot inventory of penstock-grade steel plate trades at discounts when utility procurement cycles lag. Project-based contract structures dominate greenfield pumped storage, with pricing stratifying across premium digital-turbine retrofits, standard runner replacements, and economy-tier control system upgrades. Cost compression in the standard equipment tier intensifies as European fabricators idle capacity amid North American utility budget delays. Municipal utilities and rural electric cooperatives exhibit highest price sensitivity, while merchant independent power producers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for critical castings and forgings mandate that utilities qualify both European and Asian suppliers for turbine runners, though precision-machining capability concentrates in Germany, Austria, and Japan. Raw material dependencies span high-grade steel plate from South Korea and Japan, copper winding wire from Chile and Peru, and specialized bearing alloys from Sweden and Germany. Single-source vulnerability persists in large-diameter penstock fabrication, where domestic capacity at Gulf Coast and Pacific Northwest facilities faces order backlogs extending 18-24 months. Distribution runs through engineering-procurement-construction contractors who bundle equipment, installation, and commissioning services for utility rate-base treatment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States hydropower market operates as a supply-constrained environment where specialized turbine machinist shortages and precision-casting bottlenecks prop pricing for runner replacement cycles regardless of demand fluctuations.
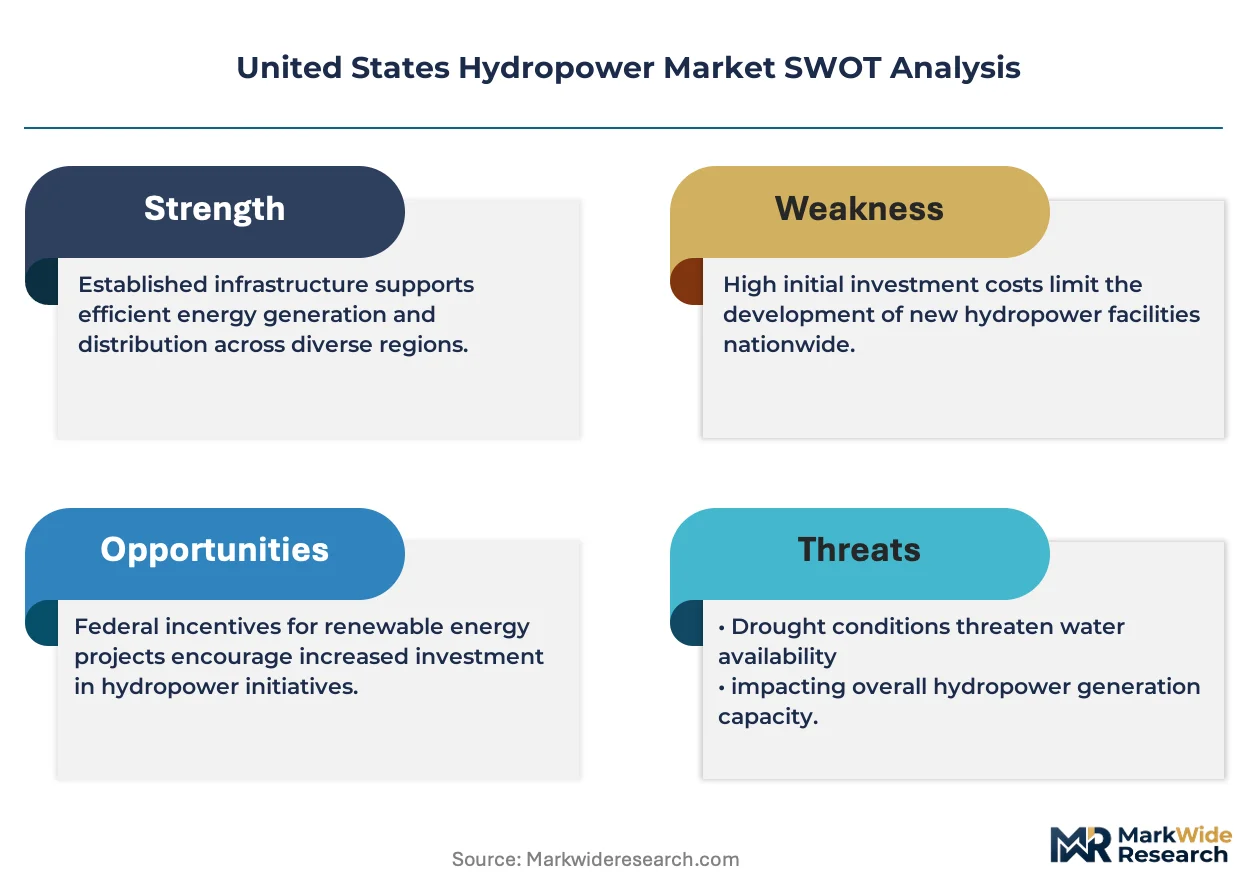
For Market Incumbents: Acquire distressed pumped storage development portfolios from developers stalled at FERC preliminary permit stage. Consolidate regional service capabilities through captive machining facilities in the Pacific Northwest and Southeast to defend against European OEM aftermarket encroachment. Certification investment in EPA Clean Water Act compliance documentation creates differentiation as environmental review timelines lengthen. For New Entrants and Emerging Players: Enter via digital turbine retrofit specialization, targeting municipal utilities in the Mountain West with sensor-embedded runner replacements that bypass new federal permitting. The most penetrable segment sits with sub-50 MW run-of-river installations where incumbent OEMs underinvest in aftermarket presence. Go-to-market execution should anchor on availability-based contracting that transfers operational risk from utility balance sheets. For Investors and Strategic Acquirers: The window for entry favors independent power producers with advanced-stage closed-loop pumped storage projects in FERC's streamlined licensing pathway. Long-term viability rests on grid stabilization revenue streams from organized capacity markets in the Carolinas and Texas. Watch FERC's evolving approach to closed-loop exemptions as the inflection signal for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Turbine Retrofit Program | GE Renewable Energy's sensor-embedded runner replacements extend asset life without structural modifications. |
| Closed-Loop Pumped Storage Development | FERC's categorical exclusion pathway accelerates project finance timelines for exempt configurations. |
| Availability-Based Service Contracting | Texas and Midwest utilities transfer operational risk to service providers amid merchant price volatility. |
| Southeastern RTO Market Formation | Carolinas capacity markets create new revenue streams for frequency regulation assets. |
| Environmental Compliance Certification | Inflation Reduction Act tax credit eligibility consolidates around projects with EPA Section 404 permits. |
Research Methodology
FERC licensing databases, EIA generation statistics, and utility regulatory filings formed the secondary backbone, cross-referenced against primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across the Pacific Northwest, California, and Southeast regions. Bottom-up project-level data on capacity additions, retrofit cycles, and procurement timelines were triangulated with top-down macro indicators including state renewable portfolio standard compliance obligations and federal infrastructure spending flows.
Bottom-up modeling aggregated individual project economics across technology type, installation category, and end-user segment, while top-down validation anchored on Department of Energy forecasts and regional transmission organization interconnection queue data. CAGRs were derived from regression analysis of historical capacity deployment patterns against regulatory milestone achievement rates. Key forecast inputs included FERC licensing approval velocity, steel and concrete commodity price indices, and state-level storage procurement mandate stringency across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EPA permit backlogs or sudden shifts in utility-scale solar-plus-storage cost competitiveness. Deviation in FERC's enforcement posture toward closed-loop exemptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Pumped Hydro Storage Market