
 Hydraulic Hoist Market | 2026-2036
Hydraulic Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Hoist Market Intelligence
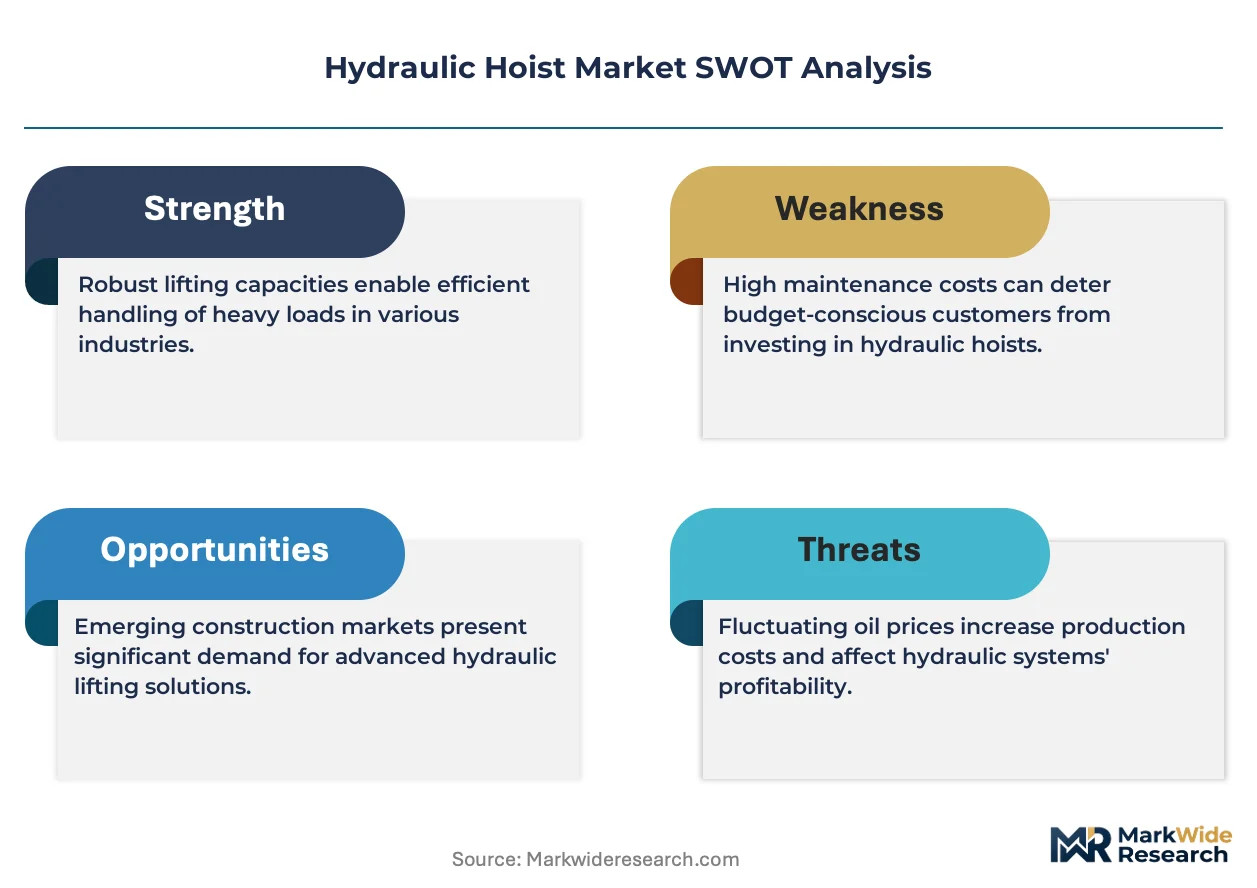
The EU Green Deal's machinery efficiency mandates is restructuring procurement criteria across European manufacturing plants and warehousing facilities. Konecranes leverages its electro-hydraulic technology leadership to capture premium contracts in Nordic shipbuilding yards. Columbus McKinnon anchors its position through backward integration into high-pressure cylinder manufacturing for North American mining operations.
A hydraulic hoist converts fluid pressure into mechanical lifting force through piston-driven or ram-based mechanisms, typically operating at system pressures between 1500 and 5000 PSI to move loads from one ton to several hundred tons vertically or at inclined angles. Wire rope hoists dominate heavy-lift construction and mining applications where load stability across long lifts matters most, while chain hoists retain cost advantages in manufacturing plants and warehousing facilities requiring frequent positioning cycles. Electro-hydraulic technology leads the technology dimension due to precision control demands in automated fabrication lines, whereas pneumatic-hydraulic systems compete in explosive-environment mining operations where spark suppression governs equipment selection.
OSHA lifting equipment standards in the United States and REACH chemical compliance for hydraulic fluids in Europe jointly elevate aftermarket service requirements and fluid specification costs for fleet operators. China's GB standards for construction machinery safety, administered by SAMR, create certification barriers that favor domestic producers in public infrastructure tenders. Buyers must weigh total cost of ownership against acquisition price as efficiency regulations tighten and fluid management costs escalate across operating environments.
Market Dynamics
The EU Green Deal's machinery efficiency mandates are forcing OEMs to redesign hydraulic architectures around regenerative energy recovery and higher-pressure circuit designs, compressing development cycles while opening premium pricing tiers for compliant equipment.
Growth Catalysts
- Electro-hydraulic precision control:Automated fabrication lines in automotive and aerospace sectors demand sub-millimeter positioning accuracy that only closed-loop electro-hydraulic systems deliver.
- Australian mining fleet expansion:Surface and underground contractors are replacing pneumatic units with explosion-proof electro-hydraulic hoists to meet stricter ignition hazard protocols.
- REACH hydraulic fluid compliance:Biodegradable synthetic formulations now mandated for European construction equipment are extending service intervals and reducing total fluid lifecycle costs.
Market Restraints
- High-pressure steel forging concentration:Cylinder-grade seamless tubing supply concentrates among a handful of German and Japanese specialty mills, creating input bottlenecks during demand surges.
- Sealing compound cost volatility:Fluorocarbon elastomer prices fluctuate with fluorspar mining output, directly impacting maintenance kit economics for fleet operators.
- Pneumatic-hydraulic substitution ceiling:Explosive-environment mining operations retain spark-suppression requirements that limit full electrification of hoist systems.
Strategic Opportunities
- Chilean copper mine electrification:State-owned Codelco's decarbonization targets create demand for grid-tied electro-hydraulic units in pit operations previously served by diesel-powered equipment.
- Remanufactured component channels:Independent rebuilders in Poland and the Czech Republic are capturing aftermarket share through certified cylinder reconditioning programs.
- Digital twin integration:IoT-enabled predictive maintenance platforms are converging with hydraulic system diagnostics to offer uptime-guaranteed service contracts.
Industry Challenges
- GB standards certification timelines:China's SAMR-administered construction machinery safety approvals average 14-18 months, delaying market entry for non-domestic OEMs.
- Electro-hydraulic technician scarcity:The intersection of fluid power and programmable logic control expertise remains underdeveloped in vocational training pipelines across North American and European maintenance networks.
- Legacy system integration friction:Retrofitting regenerative hydraulic circuits into existing crane architectures requires custom manifold engineering that extends project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Hoist Market |
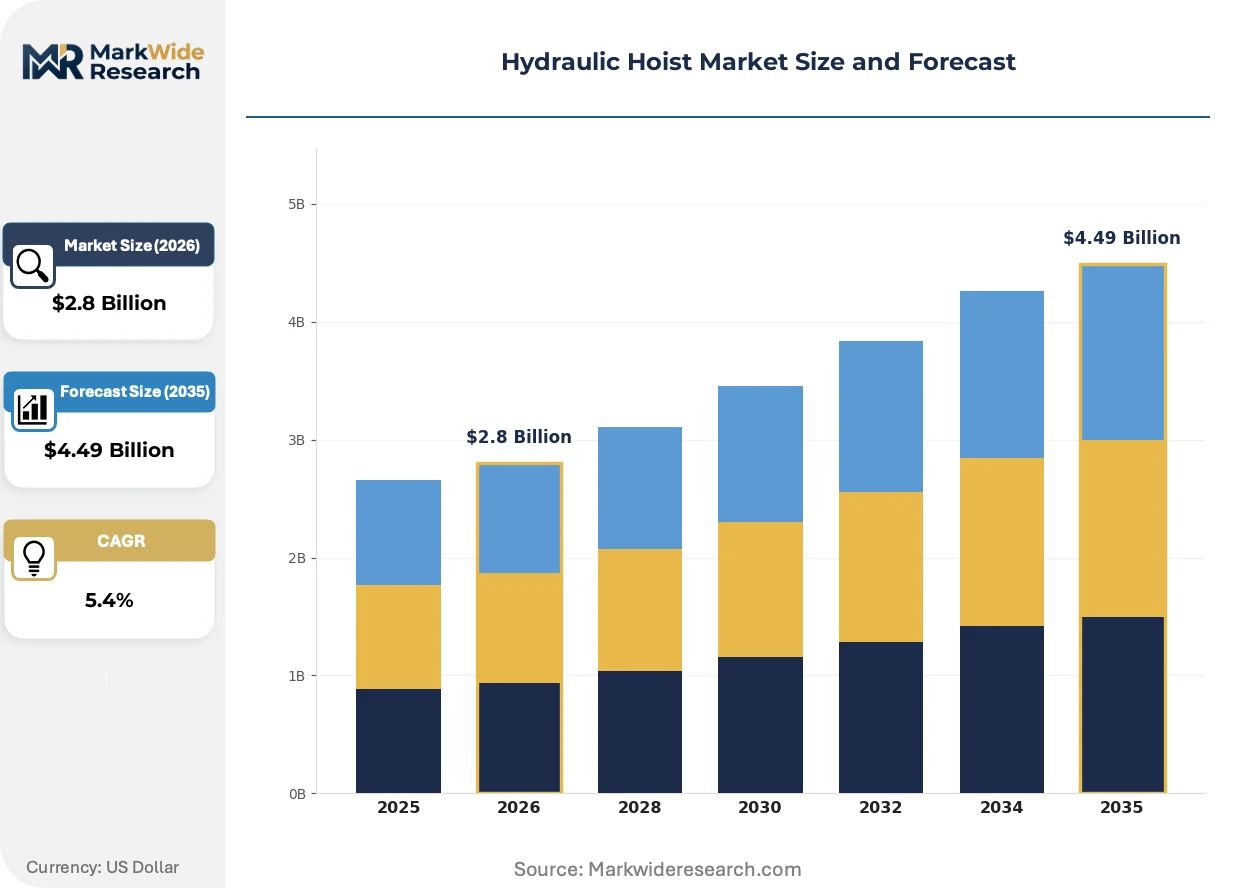
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Hoists, Wire Rope Hoists, Chain Hoists, Telescopic Hoists, Portable Hoists Technology: Electro-Hydraulic, Manual Hydraulic, Pneumatic-Hydraulic, Electric Motor Drive, Hydraulic Cylinder Application: Construction Projects, Shipbuilding Yards, Mining Operations, Manufacturing Plants, Warehousing Facilities End User: Heavy Equipment Suppliers, Shipbuilders, Mining Contractors, Industrial Fabricators, Logistics Companies |
| Companies Covered | Konecranes, Terex Corporation, Columbus McKinnon, Harrington Hoists, Ingersoll Rand, KITO Corporation, Liebherr, ABUS Crane Systems, Demag Cranes and Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Hoist Market Strategic Shifts & Innovations
Digitalization of hydraulic system monitoring is compressing maintenance intervals while enabling performance-based contracting models that transfer operational risk from end-users to equipment suppliers.
Variable displacement pump technology with load-sensing feedback is automating pressure modulation across multi-hoist crane configurations. European port operators in Rotterdam and Hamburg are retrofitting ship-to-shore cranes with these systems to cut energy consumption during intermittent lifting cycles. The technology is automating operator workload reduction while extending component service life through demand-matched fluid delivery.
OSHA's updated crane and derrick standard for construction is mandating anti-two-block and load moment indicators on all new hydraulic hoist installations. Equipment rental fleets in Texas and Florida are accelerating compliance retrofits ahead of enforcement deadlines. Wire rope hoist categories face the steepest compliance cost escalation due to integrated sensor requirements.
Buyers are consolidating supplier relationships around single-source maintenance agreements that bundle fluid analysis, seal replacement, and telemetry monitoring. Mining contractors in Western Australia are leading this transition, displacing transactional parts purchasing with fixed-cost-per-ton-lifted contracts. This restructuring concentrates purchasing power among integrated service providers and marginalizes independent component distributors.
Hydraulic Hoist Market Segmentation
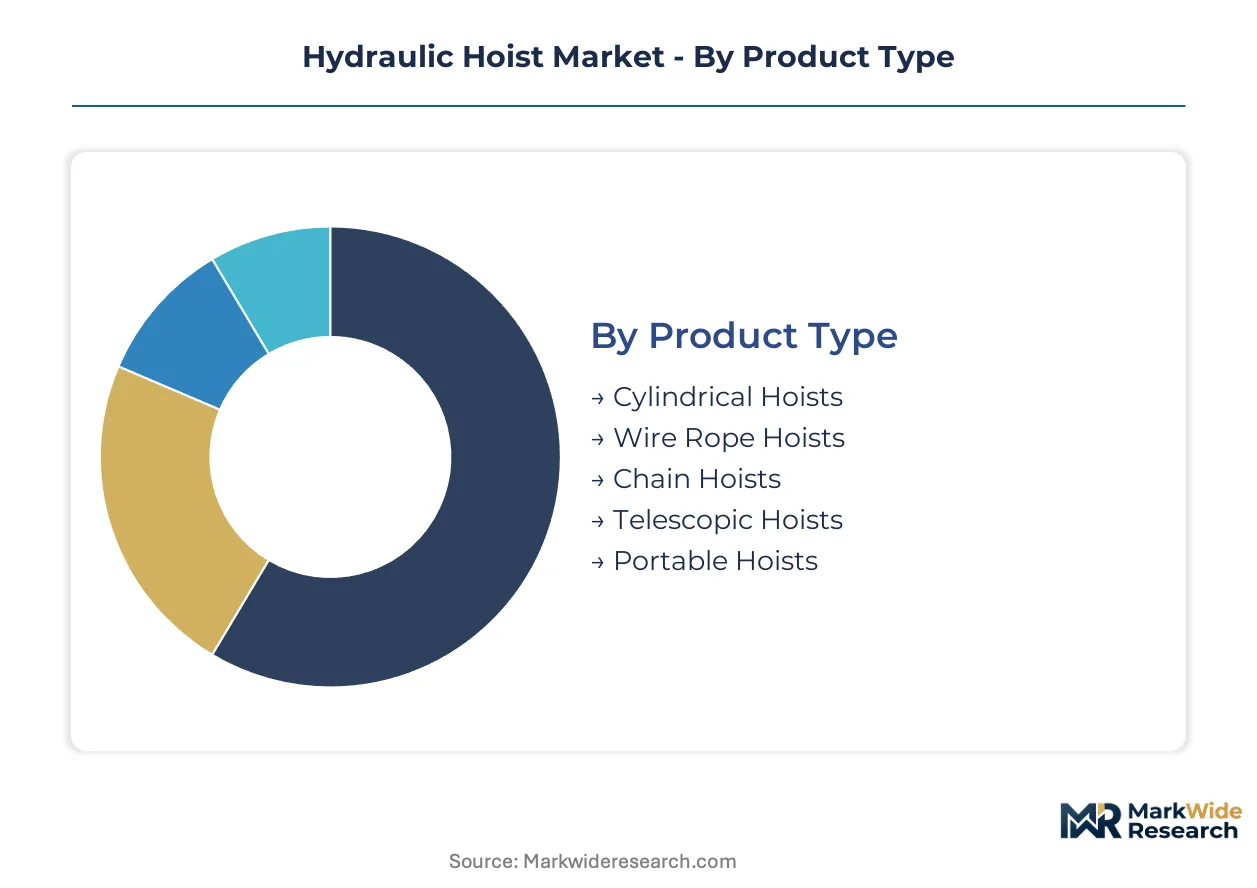
Hydraulic hoist segmentation reveals distinct procurement patterns across standalone lifting systems versus embedded crane architectures. Specification differences between wire rope and chain mechanisms drive fundamentally different maintenance economics and replacement cycles across end-use environments.
Product Type:
Standalone hoists command premium pricing in heavy-lift applications, while embedded cylinder systems integrate into larger material handling infrastructure with different margin structures.
- Wire Rope Hoists:Multi-drum configurations with galvanized or stainless steel cables handle loads exceeding 100 tons across extended vertical lifts. Mining contractors in Western Australia specify these units for pit-to-surface ore transport where load sway control governs safety protocols.
- Chain Hoists:Alloy steel link chains operate through pocket wheel mechanisms at lower duty cycles than rope alternatives. Manufacturing plants around Stuttgart and Milan deploy these for frequent positioning tasks where precision outweighs maximum lift capacity.
- Cylindrical Hoists:Piston-rod assemblies in seamless steel housings deliver force in single-axis applications.
- Telescopic Hoists:Staged cylinder extensions enable compact retracted dimensions with extended reach.
- Portable Hoists:Self-contained power units with wheeled bases serve temporary construction sites and maintenance operations.
Volume placements concentrate in Wire Rope Hoists; the faster expansion belongs to Telescopic Hoists.
Technology:
Control system sophistication separates price tiers, with closed-loop electro-hydraulic architectures commanding multiples over open-loop manual alternatives.
- Electro-Hydraulic:Servo-valve control systems with programmable logic interfaces achieve positioning accuracy within millimeters. Automated fabrication lines at aerospace suppliers in Toulouse and Hamburg mandate these systems for composite panel placement where tolerance stack-up affects assembly fit.
- Pneumatic-Hydraulic:Spark-suppressed actuation combines compressed air power with hydraulic force multiplication. Underground coal operations in Queensland specify these units where methane accumulation risks prohibit electrical ignition sources.
- Manual Hydraulic:Hand-pump reservoirs with directional valves serve low-frequency maintenance tasks.
- Electric Motor Drive:Direct mechanical lifting without fluid power conversion suits clean-room environments.
- Hydraulic Cylinder:Simple ram mechanisms integrated into custom fixtures for single-purpose lifting.
Procurement volumes favor Electro-Hydraulic systems; Pneumatic-Hydraulic configurations are climbing the fastest on mining safety mandates.
Application:
Site conditions determine specification intensity, with marine corrosion environments and underground explosive atmospheres imposing the most severe material and sealing requirements.
- Mining Operations:Explosion-proof enclosures with flame-path sealing withstand abrasive dust and ignition hazards. Chilean state-owned copper producers are retrofitting pit cranes with electro-hydraulic units to meet diesel displacement targets under national decarbonization commitments.
- Shipbuilding Yards:Marine-grade coatings and stainless steel hardware resist salt spray across decades of service. Nordic builders in Gothenburg and Turku specify these for hull block assembly where tidal lift schedules compress construction windows.
- Construction Projects:Temporary installations with rapid deployment requirements dominate infrastructure development.
- Manufacturing Plants:Repetitive duty cycles with integrated automation drive specification toward precision control variants.
- Warehousing Facilities:High-bay storage retrieval systems prioritize speed over maximum load capacity.
Equipment shipments concentrate in Construction Projects; Mining Operations show the steepest expansion trajectory on fleet electrification programs.
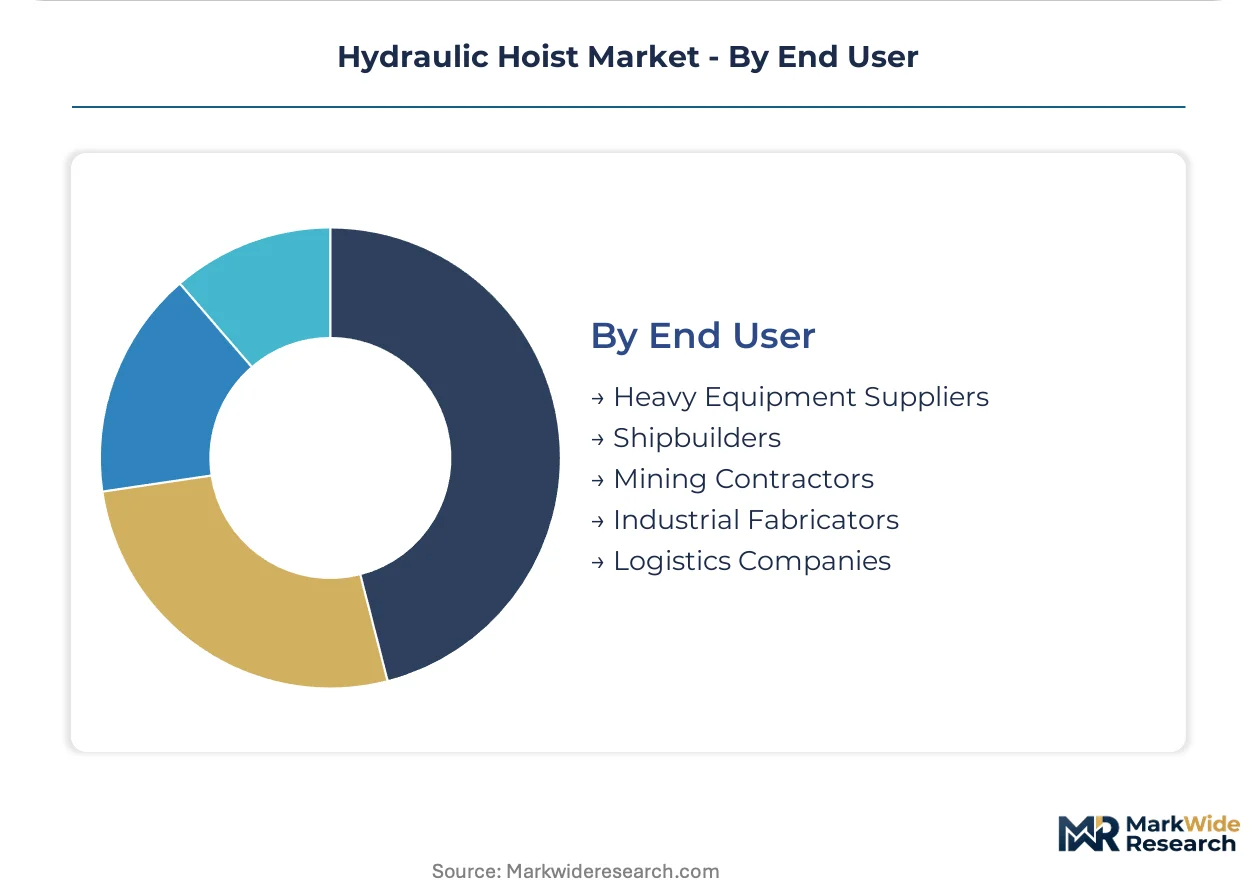
End User:
Customer scale and technical capability determine whether procurement favors integrated service contracts or component-level purchasing.
- Mining Contractors:Large fleet operators with captive maintenance infrastructure negotiate performance-based contracts with uptime guarantees. Western Australian iron ore producers are consolidating supplier relationships around single-source agreements covering fluid analysis, seal replacement, and telemetry monitoring.
- Shipbuilders:Project-based procurement with vessel-specific lifting requirements drives custom engineering engagement. Korean and Japanese yards specify integrated crane-hoist systems where classification society approval governs design acceptance.
- Heavy Equipment Suppliers:OEM integration of hoists into larger machine architectures.
- Industrial Fabricators:Mid-scale operations with intermittent lifting needs favor rental and lease arrangements.
- Logistics Companies:E-commerce fulfillment networks drive demand for high-speed retrieval systems in automated warehouses.
Contracting activity concentrates among Mining Contractors; Logistics Companies are gaining share fastest on warehouse automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of hydraulic hoist components while Australia and Chile consume the heaviest-duty units for mining extraction. European demand concentrates on precision-controlled systems for automated manufacturing.
China
Heavy equipment manufacturing clusters around Xuzhou and Changzhou supply both domestic construction projects and export markets. SAMR-administered GB standards for construction machinery safety create certification barriers that favor domestic producers in public infrastructure tenders. Local fabricators are expanding electro-hydraulic production lines to meet efficiency mandates under the country's dual carbon goals.
Australia
Surface and underground mining contractors in Western Australia and Queensland are replacing pneumatic units with explosion-proof electro-hydraulic hoists. The country's national occupational health and safety regulator enforces strict ignition hazard protocols in coal and iron ore operations. Perth-based fleet operators are consolidating supplier relationships around single-source maintenance agreements covering fluid analysis and telemetry monitoring.
Chile
State-owned copper producer Codelco's decarbonization targets are driving demand for grid-tied electro-hydraulic units in pit operations previously served by diesel-powered equipment. The national mining regulator oversees equipment certification for explosive atmospheres in underground extraction. Antofagasta and Calama mining districts are retrofitting crane fleets with regenerative hydraulic systems to meet corporate emissions commitments.
Germany
EU Green Deal machinery efficiency mandates are pushing OEMs toward higher-pressure hydraulic systems with regenerative capabilities. ECHA-administered REACH compliance for biodegradable synthetic hydraulic fluids extends service intervals and reduces total fluid lifecycle costs. Stuttgart manufacturing plants deploy chain hoists for frequent positioning tasks where precision outweighs maximum lift capacity.
United States
OSHA's updated crane and derrick standard mandates anti-two-block and load moment indicators on all new hydraulic hoist installations. Equipment rental fleets in Texas and Florida are accelerating compliance retrofits ahead of enforcement deadlines. Houston and Gulf Coast shipyards specify marine-grade wire rope hoists for hull block assembly where tidal lift schedules compress construction windows.
Hydraulic Hoist Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive hoist divisions alongside specialized lifting equipment manufacturers. Tiered positioning separates precision-control specialists serving aerospace automation from volume suppliers of standardized mining units. Two dominant competitive moves are reshaping positioning: backward integration into high-pressure cylinder manufacturing to secure input supply, and geographic expansion through distribution partnerships in Chilean and Australian mining districts.
Among European-based industrial groups, Konecranes and Liebherr occupy positions at the premium-systems tier where electro-hydraulic technology leadership captures contracts in Nordic shipbuilding yards. Columbus McKinnon anchors the North American specialist archetype through in-house production of high-pressure components for mining operations. These three exemplify how regional regulatory specialization—EU Green Deal compliance, OSHA safety mandates, SAMR certification requirements—creates distinct competitive footholds that resist easy cross-border replication.
| Leading Market Players |
|---|
| Konecranes |
| Terex Corporation |
| Columbus McKinnon |
| Harrington Hoists |
| Ingersoll Rand |
| KITO Corporation |
| Liebherr |
| ABUS Crane Systems |
| Demag Cranes and Components |
| Others |
Cost & Logistics Intelligence
Regenerative hydraulic system adoption simultaneously compresses manufacturing costs and concentrates procurement leverage among OEMs with captive cylinder production. EU Green Deal efficiency mandates force tier-two fabricators toward higher-pressure architectures they cannot source economically, widening the pricing gap between integrated and assembly-dependent suppliers.
Pricing Analysis
Margin tightening in standard-grade hoists reflects REACH-compliant fluid formulation premiums and fluorocarbon seal cost volatility. Three-tier pricing structure across premium electro-hydraulic, standard wire rope, and economy chain configurations tracks certification grade and after-sales bundling intensity. Cost-down pressure on pneumatic-hydraulic units accelerates because mining safety mandates restrict their addressable market. Logistics companies exhibit highest price sensitivity due to commoditized warehouse retrieval specifications, while Australian mining contractors accept premium positioning for uptime-guaranteed service contracts.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for aftermarket seal kits and cylinder assemblies. Manufacturing gravity centers on Germany and Japan for seamless high-pressure tubing, China for cast iron pump housings, and South Korea for precision servo valves. Input costs hinge on fluorspar mining output for sealing compounds and specialty steel billet availability. Single-source vulnerability concentrates in German and Japanese cylinder-grade tubing mills. Distribution runs through OEM-captive service networks in mining districts and independent industrial distributors in manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-hydraulic precision control is displacing legacy pneumatic systems across explosive-environment mining operations, creating asymmetric reward structures for technology leaders versus component assemblers.
For Market Incumbents: Lock in backward integration into high-pressure cylinder manufacturing to neutralize seamless tubing supply bottlenecks. Deepen certification pre-positioning under China's SAMR-administered GB standards before enforcement timelines harden. Defensive consolidation around remanufactured component channels in Central Europe captures aftermarket share from independent rebuilders. For New Entrants and Emerging Players: Enter via Chilean copper mine electrification programs where Codelco's decarbonization targets displace incumbent diesel-equipment relationships. Target portable hoist rental networks in Texas and Florida construction corridors where OSHA compliance retrofits accelerate equipment turnover. Go-to-market leverage rests on digital twin integration partnerships with predictive maintenance platform providers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking electro-hydraulic technology access. Long-term viability favors specialists with captive high-pressure forging capacity and established SAMR certification pathways. Watch for inflection when Australian mining contractors consolidate single-source maintenance agreements beyond critical mass, signaling purchasing power concentration that squeezes component distributor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Konecranes and Columbus McKinnon secure seamless tubing supply against German and Japanese mill bottlenecks. |
| Regenerative Hydraulic System Development | EU Green Deal compliance opens premium pricing tiers for Rotterdam and Hamburg port operator retrofits. |
| Digital Twin Platform Partnership | IoT-enabled predictive maintenance contracts transfer operational risk from Western Australian mining contractors to OEMs. |
| SAMR Certification Pre-Positioning | Early GB standards compliance accelerates market entry for non-domestic OEMs in Xuzhou and Changzhou supply chains. |
| Remanufactured Component Channel Buildout | Polish and Czech rebuilders capture aftermarket share through certified cylinder reconditioning programs. |
Research Approach
Independent corroboration across maintenance directors at Western Australian iron ore operations, OEM procurement teams in Stuttgart and Milan, and aftermarket service heads in Perth and Antofagasta underwrites the qualitative findings. Secondary validation draws from customs records of hydraulic component trade flows, SEC filings of listed lifting equipment manufacturers, and SAMR certification databases. Bottom-up triangulation across equipment shipment volumes and top-down reconciliation against mining capital expenditure disclosures anchor the demand assessment.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product type, technology architecture, application intensity, and end-user scale. CAGRs derive from curve-fitting historical shipment patterns against mining fleet electrification timelines and EU regulatory phase-in schedules. Industry-specific forecast inputs incorporate Codelco decarbonization commitments and OSHA enforcement deadline modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorspar supply disruption or extended SAMR certification delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Drag Chain for Machine Market