
 Slow Speed Shredding Machines Market | 2026-2036
Slow Speed Shredding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Slow Speed Shredding Machines Market Analysis
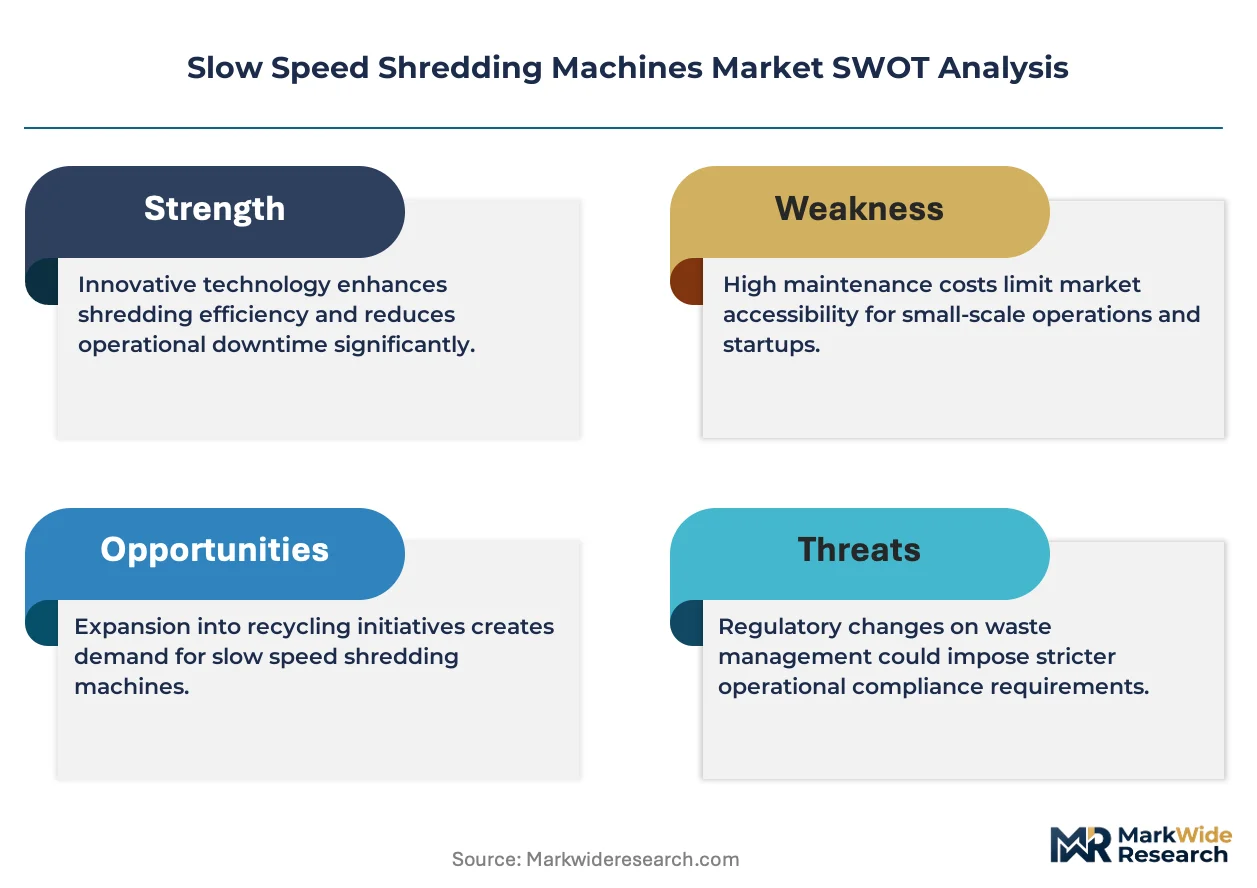
REACH compliance is shifting the cost-of-entry calculus for shredder manufacturers serving European recycling facilities. SSI Shredding Systems leverages its vertical integration to control blade metallurgy and warranty terms. Vecoplan AG anchors its position through electric-drive technology leadership in plastic recycling lines. Terex Corporation competes on manufacturing scale across North American wood processing installations.
Slow speed shredding machines employ low-RPM, high-torque rotors—typically 20–40 RPM with torque ratings exceeding 100,000 Nm—to shear bulky waste without generating hazardous dust or heat ignition risks. These systems reduce feedstock to uniform particle sizes for downstream sorting, washing, and pelletizing in recycling operations. Dual shaft configurations dominate metal recycling applications where grab-and-tear action handles entangled automotive scrap. Electric technology leads in plastic recycling due to energy efficiency and reduced hydraulic fluid maintenance. Granulators represent the fastest-growing product category as post-consumer film and fiber streams require finer particle reduction ahead of extrusion.
EPA emission standards under the Clean Air Act shape shredder enclosure and dust-collection requirements in US metal recycling yards. EU F-Gas Regulation and CE marking directives constrain hydraulic system refrigerant choices and electrical safety design for machines sold across Europe. China's MEE enforces noise and particulate limits at provincial recycling hubs. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions alter the volume and composition of feedstock arriving at shredding facilities.
Market Dynamics
Dual-shaft electric-drive technology is concentrating procurement power among municipal waste authorities and industrial recyclers who demand higher throughput with lower emissions profiles. Equipment buyers now prioritize torque consistency and energy efficiency over upfront capital cost.
Growth Catalysts
- EU Green Deal landfill diversion mandates:German municipal authorities accelerate shredder procurement to meet binding waste reduction targets.
- China's MEE provincial enforcement:Stricter scrap processing standards at industrial recycling hubs drive equipment upgrades.
- Post-consumer film streams:Rising volumes of flexible plastic packaging require granulation ahead of extrusion lines.
Market Restraints
- High-alloy blade metallurgy costs:Specialized steel formulations for abrasive feedstock create input price volatility.
- Hydraulic system refrigerant constraints:EU F-Gas Regulation limits fluid choices and complicates cross-border equipment certification.
- Electric torque motor supply concentration:Dependence on limited permanent magnet sources creates procurement risk.
Strategic Opportunities
- Extended producer responsibility frameworks:France's packaging waste reforms expand obligated feedstock volumes reaching shredding facilities.
- Smart torque monitoring systems:IoT-enabled predictive maintenance converges with electric-drive architectures to reduce unplanned downtime.
- Secondary wood processing in Poland:Underpenetrated biomass pellet preparation creates white space for slow-speed shear technology.
Industry Challenges
- Rotor balancing technician scarcity:Specialized mechanical alignment skills for high-torque assemblies outpace vocational training output.
- CE marking timeline compression:Accelerated electrical safety reviews strain notified body capacity for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slow Speed Shredding Machines Market |
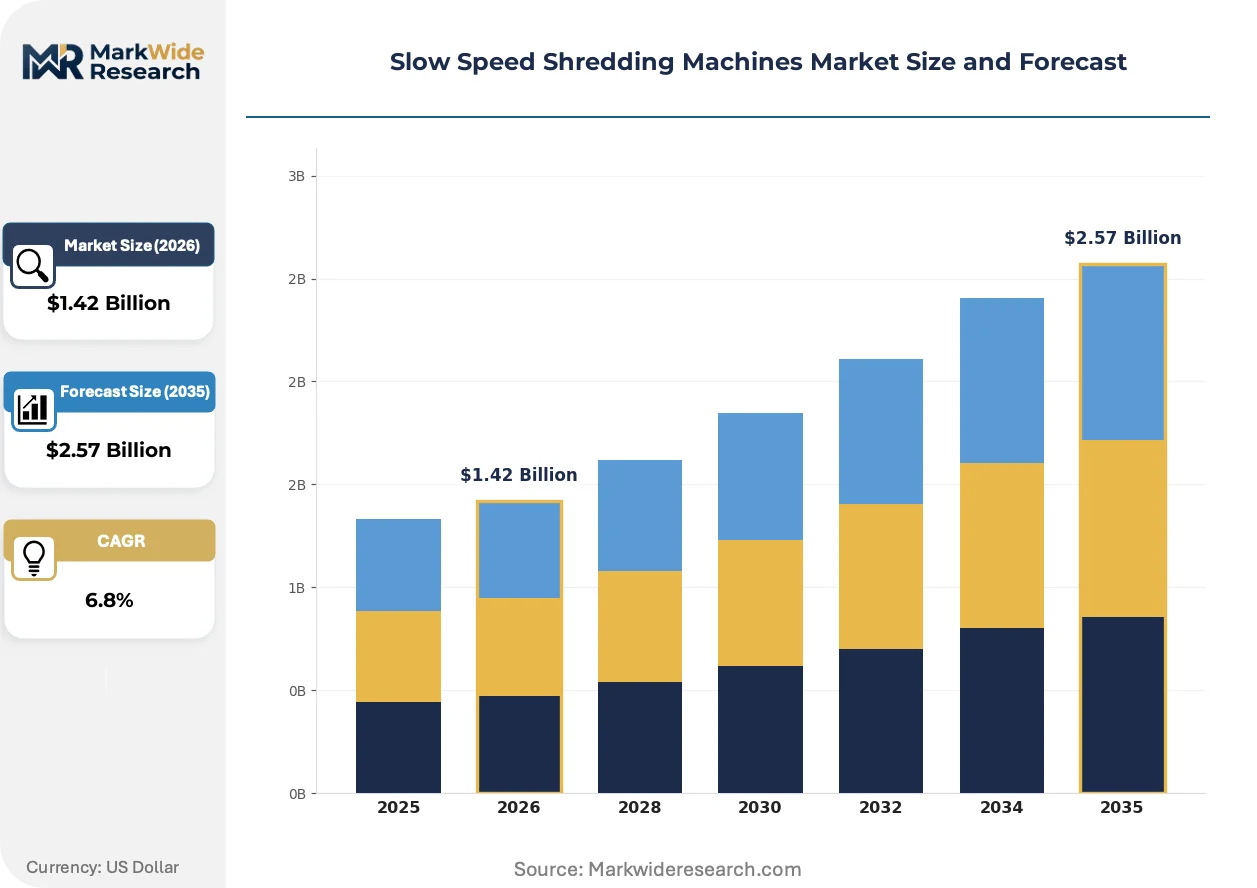
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Shaft, Dual Shaft, Granulators, Shredder Blades Application: Plastic Recycling, Wood Processing, Paper Shredding, Metal Recycling End User: Manufacturing, Waste Management, Construction, Recycling Facilities Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | SSI Shredding Systems, Inc., Terex Corporation, EDGE Innovate (NI) Ltd, GENOX Recycling Tech Co., Ltd., Komptech Group, LINDNER-RECYCLINGTECH GMBH, Williams Patent Crusher and Pulverizer Co., Inc., Granutech-Saturn Systems, Vecoplan AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slow Speed Shredding Machines Market Emerging Trajectories
Electrification of drive systems is reshaping competitive positioning around energy efficiency and maintenance intervals. Manufacturers differentiate through integrated control architectures rather than mechanical specifications alone.
Permanent magnet synchronous motor technology is decentralizing power transmission design in slow-speed shredding equipment. Plastic recycling operators in the Netherlands and Belgium adopt these systems to eliminate hydraulic fluid contamination risks. The shift is compressing demand for conventional gearbox-and-pump configurations across European film processing lines.
REACH substance restrictions are forcing reformulation of blade coating chemistries and hydraulic seal compounds. Equipment suppliers serving European metal recycling yards must document full material composition for ECHA registration. Dual-shaft configurations face particular scrutiny due to complex lubrication system architectures.
Service contract unbundling is fragmenting buyer-supplier relationships in North American wood processing installations. Large sawmill operators now procure rotor assemblies and control modules through separate channels rather than turnkey systems. The pattern concentrates in Pacific Northwest facilities seeking operational flexibility amid volatile lumber demand cycles.
Slow Speed Shredding Machines Market Segmentation
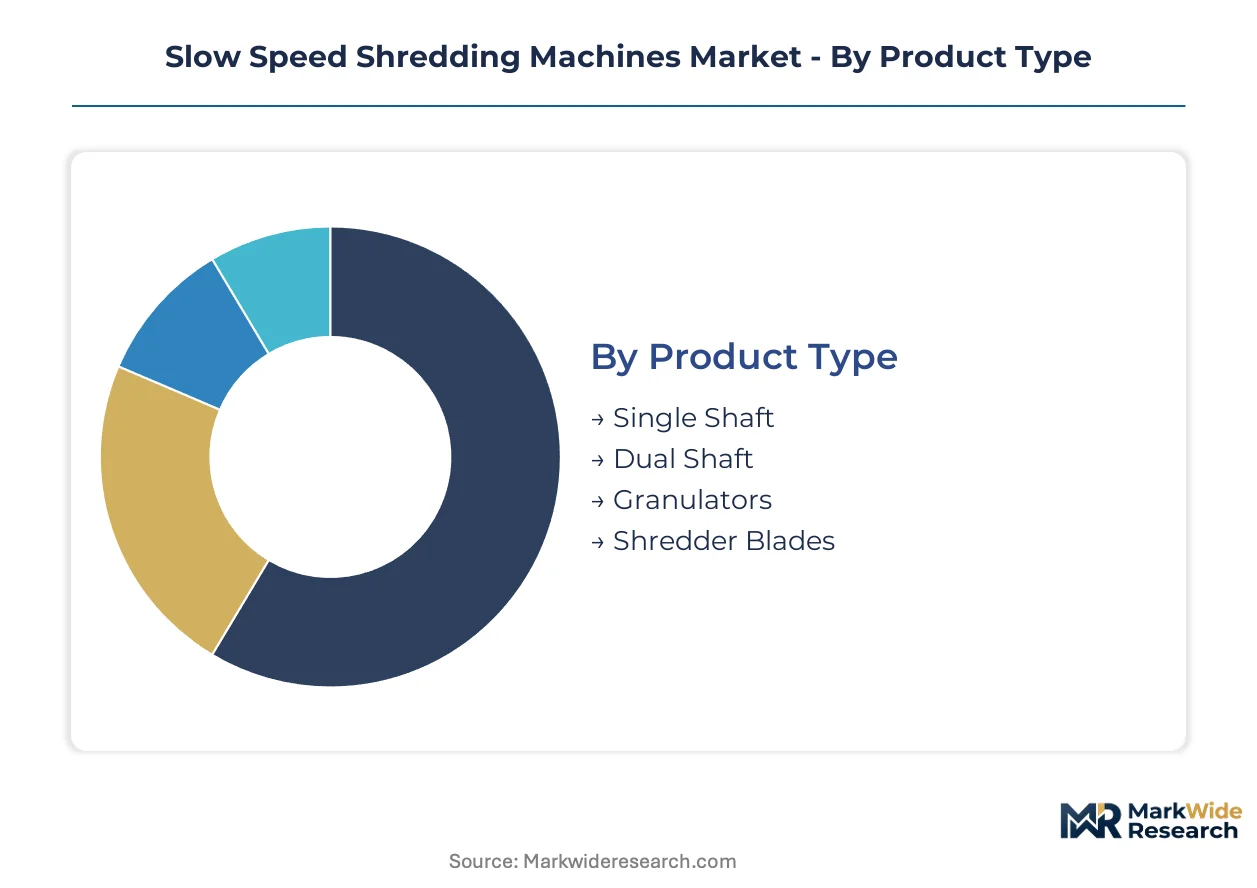
Slow speed shredding machines fragment across four structural dimensions. Product configuration determines torque delivery and particle uniformity. Application requirements dictate blade metallurgy and enclosure specifications. End-user scale shapes procurement patterns and service contract structures. Technology choice locks in energy profiles and maintenance intervals.
Product Type:
CE marking complexity varies sharply across configurations. Dual-shaft systems face extended electrical safety reviews due to interlocking rotor controls. Granulators trigger REACH substance scrutiny for blade coatings. Single-shaft designs clear notified bodies faster with simpler lubrication architectures.
- Single Shaft:One rotor with stationary bed knives produces consistent particle sizing for homogeneous feedstock. Demand concentrates in German paper processing plants where uniform fiber length determines downstream pulping efficiency. Operators favor these systems for lower capital outlay and reduced balancing complexity.
- Dual Shaft:Counter-rotating shafts with intermeshing hooks execute grab-and-tear action on entangled scrap. Municipal waste authorities in China's Jiangsu province specify these for bulky mixed waste streams ahead of mechanical sorting. The configuration dominates metal recycling where torque consistency prevents jamming on automotive hulks.
- Granulators:High-speed supplementary reduction for film and fiber streams requiring sub-10mm particles. Post-consumer plastic operators in Belgium deploy these ahead of extrusion.
- Shredder Blades:Consumable wear components in specialized high-alloy formulations. Blade replacement cycles drive recurring revenue for service providers.
Leading the category by volume: Dual Shaft. Expanding most quickly: Granulators.
Application:
Margin profiles diverge based on feedstock abrasiveness and contamination risk. Metal recycling commands premium pricing for hardened blade packages. Plastic recycling squeezes margins through energy efficiency requirements.
- Plastic Recycling:Film, fiber, and rigid container reduction demands particle uniformity for extruder feeding. Netherlands-based operators specify electric-drive granulators to eliminate hydraulic fluid contamination in food-contact recycled pellet production. EU F-Gas Regulation accelerates displacement of refrigerant-dependent hydraulic systems in this segment.
- Wood Processing:Primary and secondary biomass preparation for pellet fuel and panel board. Pacific Northwest sawmills in the US deploy slow-speed shear technology for bark and offcut processing amid volatile lumber demand cycles.
- Paper Shredding:Document destruction and pulping preparation. German municipal collection points specify noise-attenuated enclosures for urban installation.
- Metal Recycling:Automotive hulk and white goods fragmentation. China's MEE particulate limits at provincial hubs drive enclosure upgrades.
Highest margin capture: Metal Recycling. Steepest volume climb: Plastic Recycling.
End User:
Procurement sophistication scales with operational scale. Manufacturing integrates shredding into continuous process lines. Waste management authorities bundle equipment into multi-year service concessions.
- Manufacturing:In-plant scrap recovery for plastics processors and paper mills. Internal recycling loops demand uptime guarantees and rapid blade change protocols.
- Waste Management:Municipal and commercial collection authorities. German landfill diversion mandates accelerate capital deployment.
- Construction:C&D debris processing for aggregate recovery. Site mobility requirements favor compact hydraulic configurations.
- Recycling Facilities:Dedicated sorting and preprocessing plants. China's industrial recycling corridor enforces equipment upgrades through provincial environmental bureau inspections.
Dominant procurement volume: Waste Management. Fastest contract growth: Recycling Facilities.
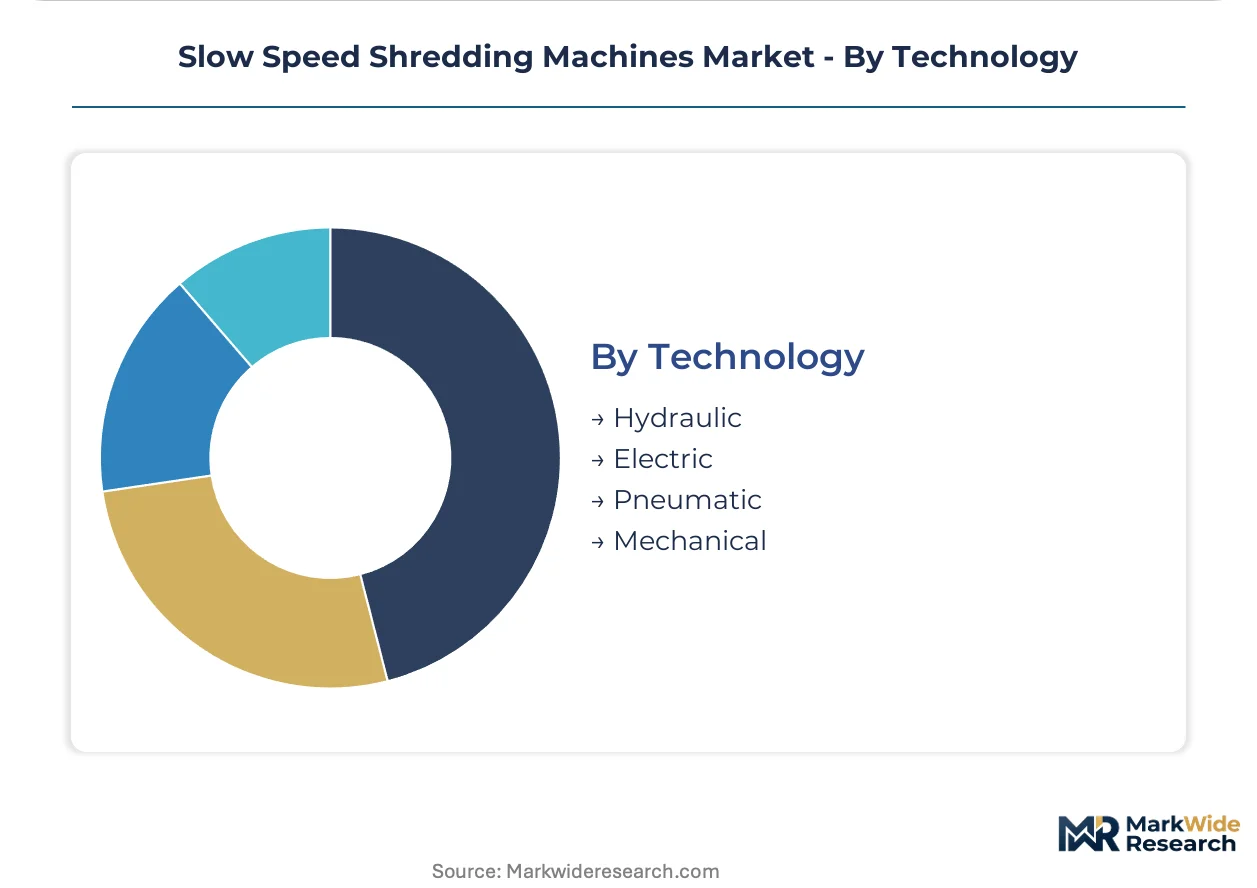
Technology:
Supply chain concentration constrains technology choice. Permanent magnet motor availability limits electric-drive expansion. Hydraulic fluid chemistry faces REACH reformulation pressure.
- Hydraulic:Established torque density for heavy-duty metal shredding. EU F-Gas Regulation restricts refrigerant choices in cooling circuits.
- Electric:Permanent magnet synchronous motors eliminate fluid maintenance and improve energy efficiency. Plastic recycling operators in Belgium and the Netherlands lead adoption.
- Pneumatic:Limited deployment in explosion-sensitive environments. Niche applications in chemical plant waste processing.
- Mechanical:Direct-drive gearbox configurations for cost-sensitive wood processing. Polish biomass pellet plants favor these for operational simplicity.
Installed base leader: Hydraulic. Gaining share fastest: Electric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in Germany's municipal waste sector, China's industrial recycling corridor, and the US Pacific Northwest wood processing belt. Equipment buyers in these markets prioritize torque consistency and emissions compliance over capital cost minimization.
United States
EPA Clean Air Act enforcement shapes shredder enclosure specifications at metal recycling yards in Ohio and Indiana. Pacific Northwest sawmills deploy slow-speed shear technology for bark processing amid volatile lumber demand cycles. California's C&D debris regulations accelerate electric-drive adoption in construction waste applications.
Germany
Municipal authorities in Bavaria and North Rhine-Westphalia expand dual-shaft procurement to meet binding EU Green Deal landfill diversion targets. REACH compliance shifts blade metallurgy sourcing decisions for equipment serving European recycling facilities. The Rhine-Ruhr industrial cluster hosts concentrated service provider networks for high-torque rotor maintenance.
China
MEE provincial enforcement in Jiangsu and Zhejiang drives equipment upgrades at industrial recycling hubs processing automotive scrap. Stricter particulate limits necessitate enclosure retrofits at existing shredding facilities. The Yangtze River Delta concentration of plastic recyclers specifies electric-drive granulators for food-contact pellet production.
Netherlands
Post-consumer film operators in Rotterdam and Eindhoven lead permanent magnet synchronous motor adoption to eliminate hydraulic fluid contamination risks. EU F-Gas Regulation accelerates displacement of refrigerant-dependent systems in plastic recycling lines. The Randstad logistics corridor enables rapid blade replacement service contracts.
Poland
Secondary wood processing facilities in Silesia and Greater Poland create white space for slow-speed shear technology in biomass pellet preparation. Underpenetrated markets favor mechanical direct-drive configurations for operational simplicity. Warsaw-based distributors consolidate procurement relationships with German equipment suppliers.
Slow Speed Shredding Machines Market Vendor Landscape
German and Austrian producers anchor one tier of precision-engineered equipment; US and Chinese fabricators hold volume positions in cost-sensitive segments. The vendor base splits between consolidated multi-product conglomerates and specialized shredding technology houses. Three archetypes dominate: vertically integrated metallurgy controllers, electric-drive technology leaders, and manufacturing scale operators. Competitive moves concentrate on strategic partnerships for permanent magnet supply security and geographic expansion into underpenetrated biomass processing markets.
Within the integrated technology tier, SSI Shredding Systems, Inc. exemplifies upstream control over blade formulation and warranty structures. Vecoplan AG occupies a position as electric-drive architecture specialist serving European film recycling lines. Terex Corporation represents manufacturing scale concentration across North American wood processing installations. These three anchors illustrate how competitive differentiation now converges on energy efficiency and predictive maintenance integration rather than mechanical specifications alone.
| Leading Market Players |
|---|
| SSI Shredding Systems, Inc. |
| Terex Corporation |
| EDGE Innovate (NI) Ltd |
| GENOX Recycling Tech Co., Ltd. |
| Komptech Group |
| LINDNER-RECYCLINGTECH GMBH |
| Williams Patent Crusher and Pulverizer Co., Inc. |
| Granutech-Saturn Systems |
| Vecoplan AG |
| Others |
Supply Flow & Price Mechanics
Rotor balancing technician scarcity in Germany's Rhine-Ruhr industrial cluster widens labor-cost differentials between premium precision-engineered equipment and economy-tier fabrications. REACH compliance documentation requirements for blade metallurgy create fixed-cost barriers that compress margins at the standard tier while protecting premium pricing power.
Pricing Analysis
Volume concentrates in dual-shaft hydraulic configurations while margin capture sits with electric-drive granulators serving food-contact plastic recycling. Three-tier pricing structure across premium certified, standard compliant, and economy-tier equipment reflects CE marking complexity and blade alloy grade differentiation. Cost compression in the hydraulic tier intensifies because EU F-Gas Regulation refrigerant constraints eliminate low-cost fluid alternatives. Municipal waste authorities in Germany exhibit lowest price sensitivity due to landfill diversion mandate urgency; Polish biomass pellet plants demonstrate highest sensitivity favoring mechanical direct-drive simplicity.
Supply Chain Analysis
Regional distribution centers in Germany, Austria, and the United States anchor hub-and-spoke patterns for blade replacement logistics and rotor assembly fulfillment. Permanent magnet synchronous motors draw from concentrated rare earth processing in China, while high-alloy blade steel sources from German and Austrian metallurgy specialists. Single-source vulnerability in permanent magnet supply creates procurement risk for electric-drive expansion. Distribution runs through OEM-direct channels for large municipal contracts and specialized distributor networks for aftermarket blade and service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance registration and CE marking electrical safety reviews erect barrier-to-entry moats favoring incumbents with established ECHA documentation and notified body relationships.
For Market Incumbents: Acquire permanent magnet supply agreements or captive magnet processing capacity to secure electric-drive expansion against rare earth procurement risk. Deepen backward integration into blade metallurgy formulation to control warranty cost exposure on abrasive metal recycling applications. Consolidate service provider networks in China's Yangtze River Delta to capture MEE-driven retrofit demand. For New Entrants and Emerging Players: Begin with mechanical direct-drive configurations for Poland's underpenetrated biomass pellet preparation market where operational simplicity outweighs energy efficiency requirements. Target secondary wood processing facilities in Silesia with cost-optimized shear technology avoiding electric-drive supply chain complexity. Pursue blade replacement service contracts as entry wedge before full system penetration. For Investors and Strategic Acquirers: Re-rating potential sits with electric-drive technology specialists given EU F-Gas Regulation acceleration of hydraulic system displacement. Long-term viability over a five-to-ten year horizon favors vendors with integrated control architectures and IoT-enabled predictive maintenance capabilities. Monitor MEE provincial enforcement intensity in Jiangsu and Zhejiang as inflection indicator for Chinese equipment upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Supply Security Partnership | Locks in rare earth access for electric-drive expansion ahead of competitor procurement. |
| Smart Torque Monitoring System Integration | Converges IoT predictive maintenance with electric architectures to reduce unplanned downtime. |
| CE Marking Fast-Track Certification Investment | Compresses notified body timeline for European market entry against capacity-constrained rivals. |
| Biomass Pellet Processing Geographic Expansion | Captures white space in Poland's underpenetrated secondary wood preparation corridor. |
| Blade Metallurgy Backward Integration | Controls high-alloy formulation costs and warranty exposure on abrasive automotive scrap applications. |
Methodological Framework
Multi-period observation of municipal procurement volumes, MEE enforcement actions, and blade replacement cycle frequencies anchored the trend analysis, supplemented by interviews with maintenance directors at German recycling facilities, OEM procurement teams in China's industrial corridor, aftermarket service heads at Austrian equipment suppliers, and plant engineers at Netherlands plastic recycling operators. Secondary validation drew from EU ECHA registration databases, EPA Clean Air Act enforcement records, Chinese provincial environmental bureau inspection disclosures, and customs trade data on high-alloy steel formulations. Bottom-up equipment shipment tracking and top-down waste stream volume estimates were triangulated for segment sizing.
Input-output matrices mapped torque demand by application against motor and gearbox supply capacity across the projection horizon. Segmentation dimensions modeled include product configuration, feedstock abrasiveness grade, end-user operational scale, and technology energy profile. CAGRs were derived from installed base turnover rates and regulatory-driven replacement demand. Forecast inputs incorporated EU Green Deal landfill diversion trajectory assumptions and China's dual carbon policy enforcement intensity variations.
Underlying measurement precision varies by segment; electric-drive adoption rates in plastic recycling carry tighter precision than hydraulic system displacement timelines in metal shredding. Forecasts reflect documented assumptions regarding REACH substance restriction evolution and permanent magnet supply concentration persistence. Periodic stress-testing of base assumptions against MEE inspection frequency data and notified body capacity expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Cable Conduit Market