
 Solar Pile Driving Equipment Market | 2026-2036
Solar Pile Driving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Pile Driving Equipment Market Insights
Telematics-enabled fleet management is realigning how solar pile driving equipment gets sold, shifting transactions from hardware-only to subscription-augmented contracts. Vermeer leverages its North American dealer network to bundle remote diagnostics with machine sales. XCMG anchors its competitive stance on manufacturing scale across hydraulic and vibratory product lines. Movax differentiates through specialized side-grip vibratory attachments optimized for uneven terrain.
Solar pile driving equipment comprises mounted or tracked machinery that delivers percussive, vibratory, or static force to embed steel, concrete, or composite piles into substrate for photovoltaic array foundations, typically operating at 10-40 tons of impact energy depending on soil classification and pile specification. Hydraulic pile drivers currently occupy the largest product category due to torque adaptability across clay, sand, and rocky formations, while semi-automated equipment represents the fastest-growing technology segment as developers target labor cost reduction and positional accuracy within two-centimeter tolerances. Static pile drivers retain niche dominance in noise-sensitive European jurisdictions where urban-periurban solar installations face strict decibel limits.
Germany's KBA enforces machinery safety certification under EU CE marking and the Machinery Directive, compelling export-oriented manufacturers to validate electromagnetic compatibility and operator guarding systems. India's BIS mandates equipment conformity for government-tendered solar park projects, effectively filtering market access for non-certified suppliers. China's GB standards and MIIT industrial policy channel domestic procurement toward locally manufactured pile driving platforms. Stakeholders must monitor how evolving national content requirements and carbon-border adjustment mechanisms reshape equipment sourcing decisions across multi-jurisdictional project portfolios.
Market Dynamics
Foundation automation is compressing project timelines for utility-scale solar installations, forcing equipment manufacturers to integrate GNSS-guided positioning and real-time soil analytics directly into pile driving platforms. This structural shift favors vendors capable of delivering centimeter-grade accuracy under variable geotechnical conditions.
Growth Catalysts
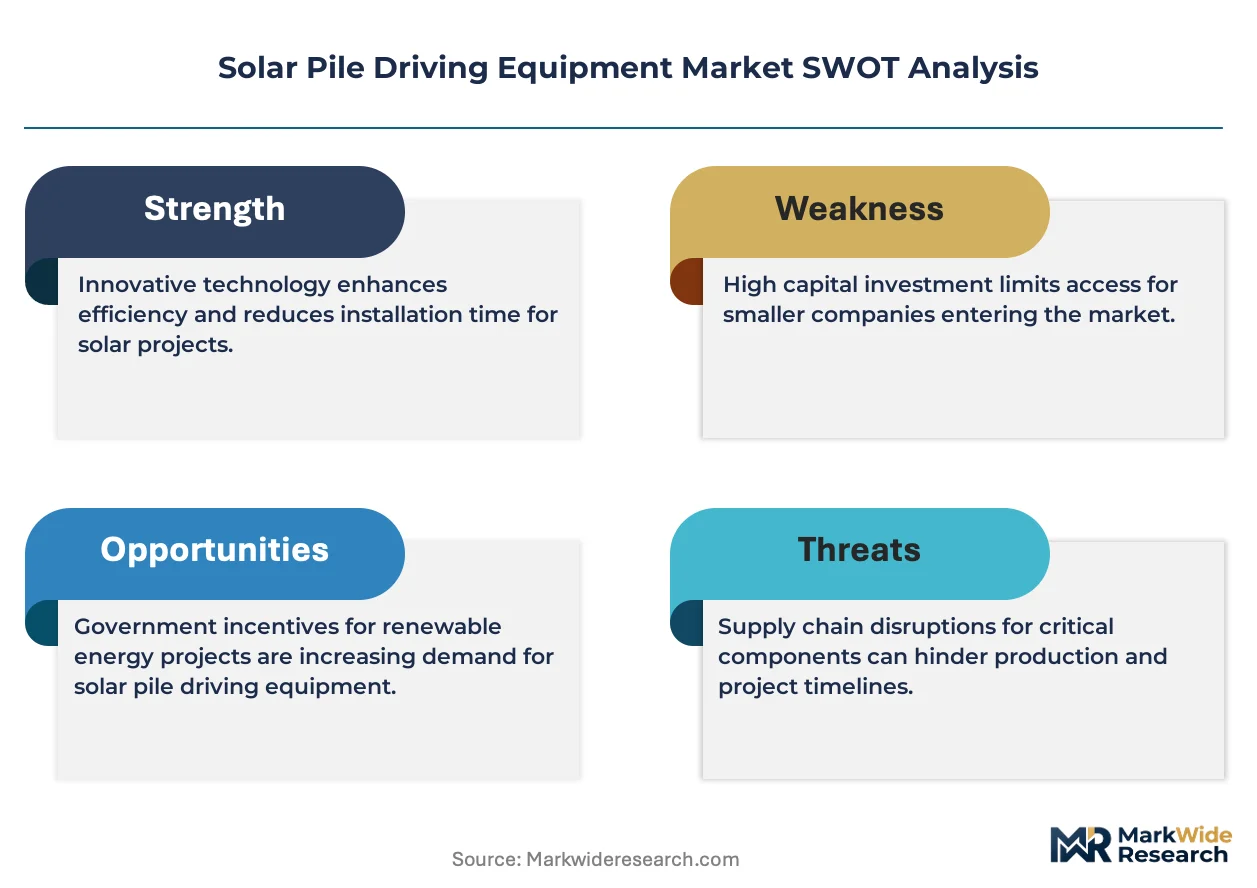
- India's PLI scheme for solar manufacturing:Domestic content incentives are channeling capital toward localized pile driving fleet procurement, particularly in Rajasthan and Gujarat solar parks.
- Semi-automated positioning systems:Two-centimeter tolerance requirements from Germany's KBA certification are accelerating replacement cycles for legacy hydraulic equipment.
- Utility-scale procurement concentration:Gigawatt-scale developers in Australia are consolidating vendor relationships around telematics-enabled fleet management contracts.
Market Restraints
- Steel price volatility:Fluctuations in high-grade structural steel input costs compress margin predictability for equipment manufacturers serving price-sensitive Asian markets.
- China's MIIT industrial policy:Domestic procurement mandates for GB-certified platforms restrict market access for non-Chinese suppliers in the world's largest equipment manufacturing base.
- Static pile driver technical ceiling:Noise-suppressed European installations face force-output limitations that extend project duration on dense substrate sites.
Strategic Opportunities
- Periurban solar in noise-sensitive jurisdictions:Germany's urban decibel limits create white space for electric-hybrid pile driving platforms with sub-75 dB operating signatures.
- Subscription-augmented contracts:Telematics bundling is displacing pure hardware transactions, enabling recurring revenue capture from remote diagnostics and predictive maintenance.
- Composite pile materials:Corrosion-resistant fiberglass-reinforced polymers are penetrating coastal solar installations in Australia where saline substrate accelerates steel degradation.
Industry Challenges
- GNSS technician scarcity:Precision-guided equipment deployment requires operators trained in real-time kinematic positioning systems, creating recruitment bottlenecks in emerging solar markets.
- Multi-jurisdiction certification timelines:Simultaneous CE marking, BIS conformity, and KBA validation extend product launch cycles by 14-18 months for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Pile Driving Equipment Market |
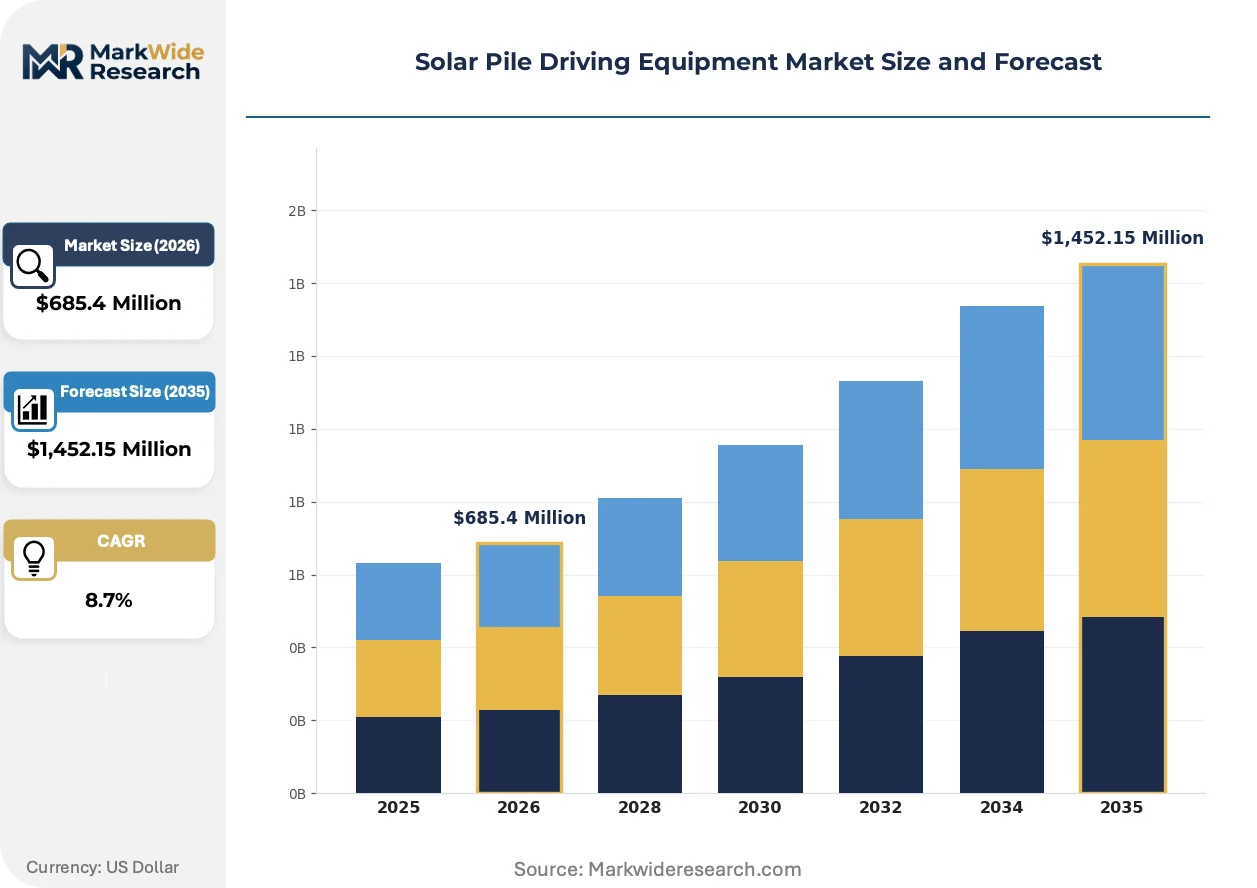
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pile Drivers, Pneumatic Pile Drivers, Vibratory Pile Drivers, Static Pile Drivers Application: Solar Farms, Ground Mount Systems, Floating Systems, Carport Systems End User: Construction Companies, Renewable Energy Developers, Utility Providers, Government Projects Technology: Mobile Equipment, Fixed Equipment, Semi-Automated Equipment, Manual Equipment |
| Companies Covered | GAYK Baumaschinen GmbH, International Attachments Inc., Vermeer, FABU, BAYO.S, XCMG, Baishun Machinery, Hercules, Movax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Pile Driving Equipment Market Trends and Innovations
Electrification and digital integration are redefining equipment value propositions, compressing the boundary between machinery sales and ongoing service relationships. Vendors now compete on data architecture rather than impact energy specifications alone.
Vibratory side-grip attachments are expanding into rocky and uneven terrain applications previously dominated by percussive hydraulic systems. Australian and Indian developers operating on variable geotechnical sites are adopting these platforms at accelerated rates. The technology is expanding into new substrate categories that were historically excluded from vibratory methods, compressing the addressable market for traditional impact drivers.
China's GB standards and MIIT industrial policy are tightening electromagnetic compatibility requirements for exported machinery. Manufacturers must validate shielding systems and operator guarding against revised testing protocols before accessing government-tendered solar park projects. Hydraulic platform suppliers targeting Chinese domestic procurement are most affected, redirecting R&D expenditure toward compliance engineering.
Buyer concentration among gigawatt-scale developers is unbundling after-sales service from equipment purchase contracts. Large solar EPCs in the United States and India are negotiating standalone remote monitoring subscriptions with preferred vendors, displacing traditional dealer-mediated support relationships. This restructuring is most visible in Rajasthan and Gujarat, where consolidated procurement power enables direct vendor negotiation.
Solar Pile Driving Equipment Market Segmentation
Foundation specifications and geotechnical variability drive equipment selection across solar installations. Procurement patterns diverge sharply between utility-scale developers optimizing fleet utilization and distributed installers prioritizing equipment mobility.
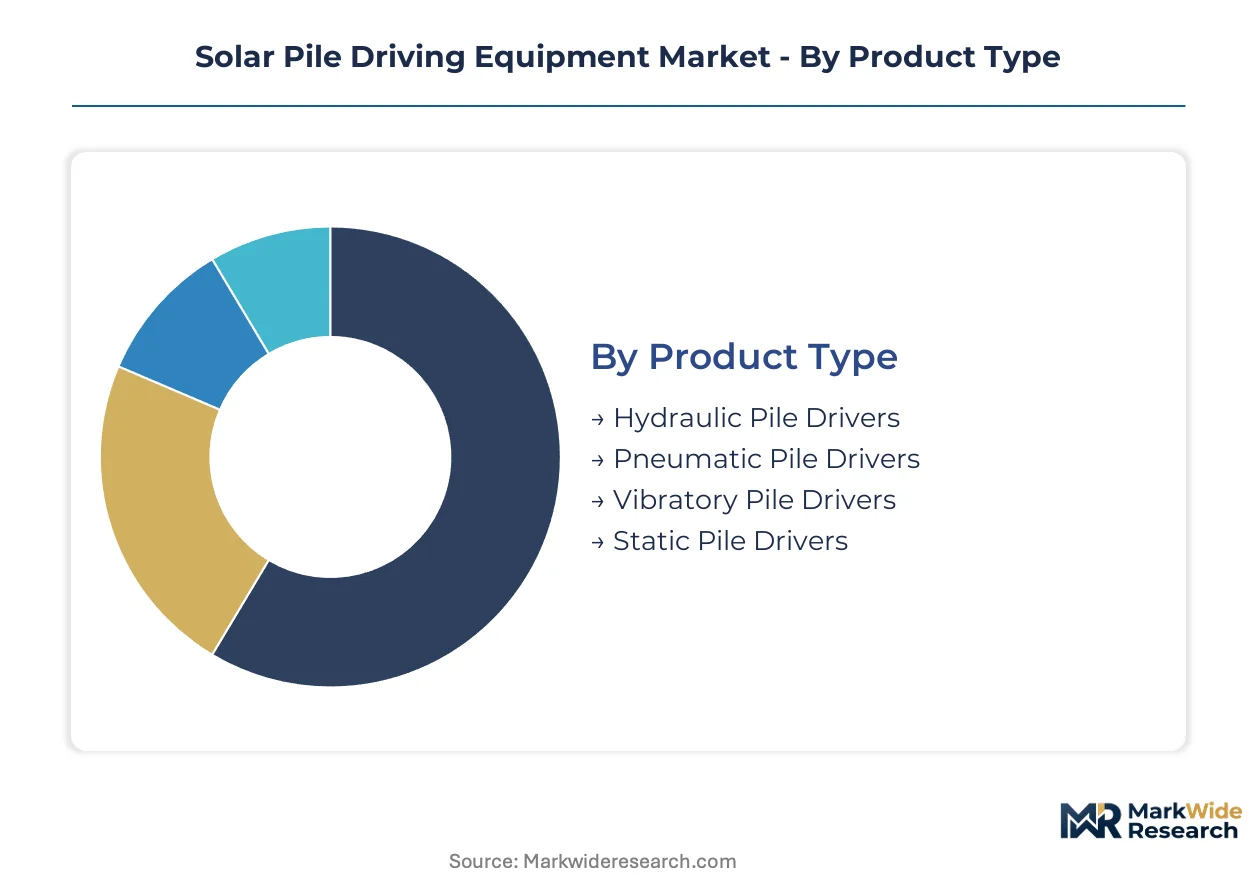
Product Type:
Soil classification and noise constraints dominate buyer calculus, with torque requirements and decibel limits filtering viable options.
- Hydraulic Pile Drivers:Deliver percussive force through piston-driven impact mechanisms operating at 10-40 tons of energy. Rajasthan and Gujarat solar parks deploy these platforms across clay and rocky substrates where adaptability trumps speed. India's BIS certification mandates structural validation for government-tendered projects.
- Vibratory Pile Drivers:Generate high-frequency oscillations through eccentric rotating masses to liquefy surrounding soil and reduce penetration resistance. Australian developers favor these for coastal installations where saline conditions accelerate steel degradation and installation speed governs project economics.
- Pneumatic Pile Drivers:Compressed-air systems delivering controlled impact sequences for precision-sensitive applications. Compressed-air infrastructure dependency limits deployment to established construction corridors.
- Static Pile Drivers:Apply continuous downward pressure without percussive or vibratory disturbance. Germany's urban decibel limits below 75 dB mandate these platforms for periurban solar arrays despite force-output constraints on dense substrates.
Volume sits with hydraulic platforms; growth tilts toward vibratory systems expanding into rocky terrain previously excluded from their addressable market.
Application:
Scale economics and foundation complexity stratify equipment specifications across installation types.
- Solar Farms:Utility-scale arrays exceeding 100 MW require automated pile driving fleets capable of 300-500 installations daily. Gigawatt-scale developers in Australia consolidate vendor relationships around telematics-enabled contracts with predictive maintenance bundling.
- Ground Mount Systems:Distributed commercial and industrial installations demand equipment mobility across variable terrain. Semi-automated positioning systems with two-centimeter GNSS tolerance penetrate this segment fastest.
- Floating Systems:Marine pile driving platforms adapted for reservoir and coastal floating photovoltaic foundations. Corrosion-resistant specifications and wave-load engineering differentiate equipment requirements.
- Carport Systems:Urban parking canopy installations with restricted working envelopes and noise sensitivity. Electric-hybrid platforms with sub-75 dB signatures gain traction in European municipal procurement.
Revenue concentrates in solar farms; steepest expansion trajectory belongs to floating systems as reservoir-based photovoltaic deployment accelerates.
End User:
Procurement sophistication and fleet ownership models diverge across buyer categories.
- Construction Companies:Generalist contractors cross-deploy equipment across solar and traditional foundation work. Equipment utilization rates and multi-project amortization drive purchasing decisions.
- Renewable Energy Developers:Specialized solar EPCs with captive pile driving fleets. Rajasthan and Gujarat developers leverage consolidated procurement power for direct vendor negotiation displacing dealer intermediation.
- Utility Providers:Vertically integrated power generators with long-term infrastructure maintenance obligations. Lifecycle cost modeling and spare parts availability dominate vendor selection.
- Government Projects:Public-tendered solar parks with domestic content mandates and certification requirements. India's PLI scheme channels capital toward localized fleet procurement with BIS conformity filtering market access.
Equipment ownership clusters with renewable energy developers; subscription-augmented contracts penetrate fastest among utility providers.
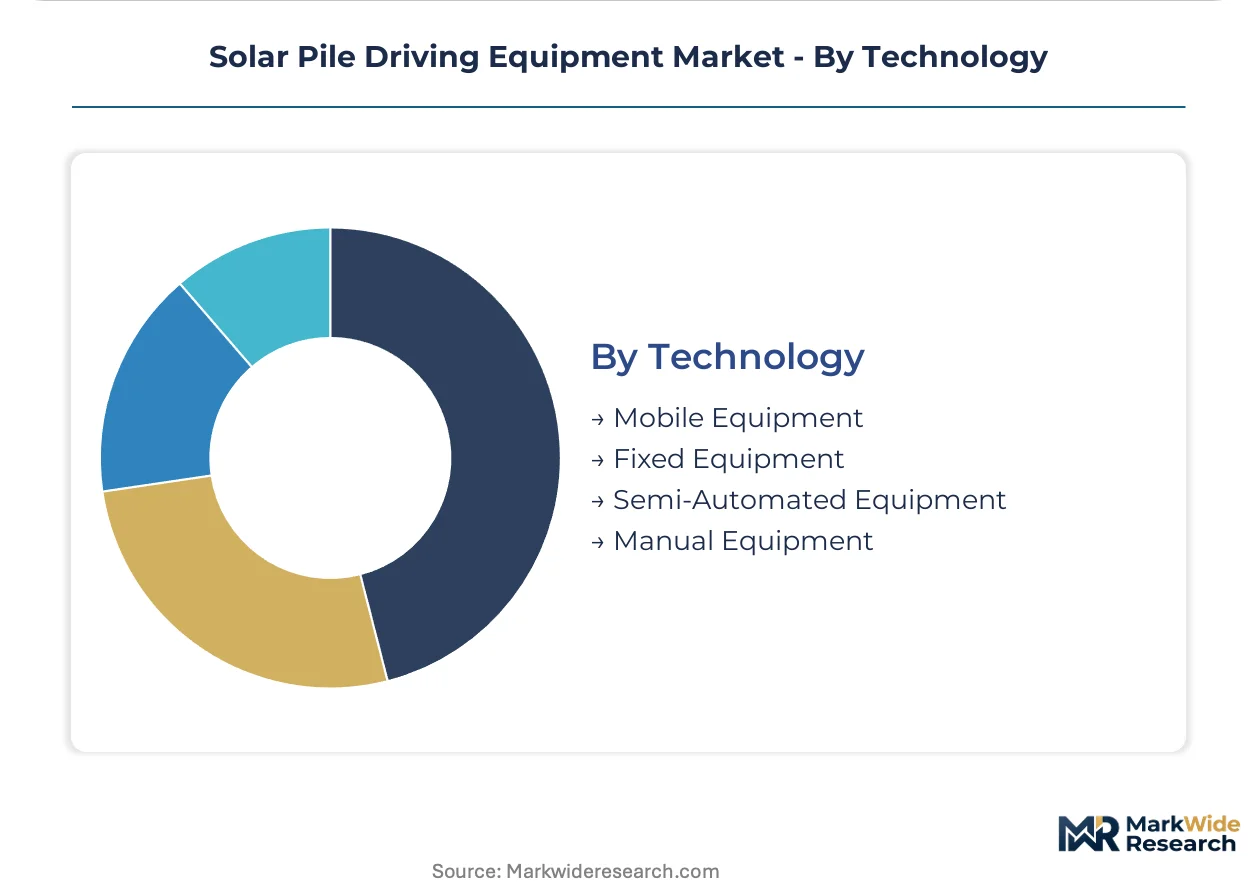
Technology:
Automation intensity and positional accuracy requirements stratify platform investment levels.
- Semi-Automated Equipment:GNSS-guided positioning with real-time kinematic correction achieving two-centimeter tolerances. Germany's KBA certification mandates precision validation, accelerating replacement cycles for legacy hydraulic platforms.
- Mobile Equipment:Tracked or wheeled carriers with rapid site-to-site redeployment capability. Variable geotechnical conditions in Australian and Indian markets favor these platforms for project portfolio flexibility.
- Fixed Equipment:Stationary installations for high-volume production line pile driving. Limited to manufacturing facilities and pre-assembly yards with established substrate profiles.
- Manual Equipment:Operator-controlled systems without automated positioning or force modulation. Price-sensitive Asian markets retain limited deployment for small-scale distributed installations.
Installed base remains manual and mobile; capability investment flows toward semi-automated platforms as labor cost reduction and certification compliance reshape procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan and Gujarat anchor solar pile driving equipment procurement in India, where gigawatt-scale solar parks concentrate foundation automation demand. Equipment manufacturers face divergent regulatory regimes across major markets, forcing multi-jurisdictional certification strategies.
United States
Utility-scale developers in Texas and California consolidate procurement around telematics-enabled fleet management contracts. The FERC interconnection queue backlog pushes EPCs toward faster foundation timelines. Arizona and Nevada solar clusters drive replacement demand for legacy hydraulic platforms.
Germany
Periurban solar arrays face KBA-enforced decibel limits below 75 dB, mandating static pile drivers for noise-sensitive installations. The EU Green Deal accelerates renewable infrastructure deployment across Bavaria and North Rhine-Westphalia. Berlin-Brandenburg municipal tenders specify electric-hybrid operating signatures.
India
Rajasthan's Bhadla and Gujarat's Pavagada solar parks require thousands of driven piles per site, channeling PLI scheme capital toward localized fleet procurement. BIS certification filters market access for government-tendered projects. Domestic content incentives reshape equipment sourcing toward locally manufactured platforms.
Australia
Coastal installations in Queensland and New South Wales favor vibratory systems where saline substrate accelerates steel degradation. TGA-equivalent state-level machinery safety requirements govern electromagnetic compatibility validation. Gigawatt-scale developers negotiate direct vendor relationships displacing traditional dealer intermediation.
China
MIIT industrial policy channels domestic procurement toward GB-certified pile driving platforms, restricting market access for non-Chinese suppliers. Yangtze River Delta manufacturing clusters export electromagnetic compatibility-validated machinery under revised testing protocols. Dual carbon goals accelerate renewable infrastructure foundation deployment.
Solar Pile Driving Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the solar pile driving equipment market. The vendor base stratifies between integrated machinery manufacturers and specialized attachment developers. Three archetypes dominate: diversified construction equipment conglomerates, precision-guided automation specialists, and regional fabrication houses serving price-sensitive Asian markets. Competitive moves concentrate on telematics bundling and multi-jurisdiction certification acceleration.
Within the diversified equipment tier, XCMG and Vermeer exemplify scale-driven manufacturing breadth across hydraulic and vibratory product lines. Movax occupies a specialist position through side-grip vibratory attachments optimized for uneven terrain applications. These three anchors represent contrasting strategic postures—Chinese manufacturing scale, North American dealer-network bundling, and Finnish attachment specialization—each capturing distinct procurement preferences across utility-scale and distributed solar segments.
| Leading Market Players |
|---|
| GAYK Baumaschinen GmbH |
| International Attachments Inc. |
| Vermeer |
| FABU |
| BAYO.S |
| XCMG |
| Baishun Machinery |
| Hercules |
| Movax |
| Others |
Pricing and Supply Chain Analysis
High-grade structural steel input costs cascade through three pricing tiers before reaching utility-scale developers in Rajasthan and Gujarat, with European KBA-certified platforms commanding premiums over Indian BIS-compliant alternatives and unbranded regional fabrication.
Pricing Analysis
Throughput-based pricing anchors equipment valuation, with subscription-augmented contracts bundling telematics diagnostics and predictive maintenance displacing pure hardware transactions. Certification grade—CE marking for European export, BIS conformity for Indian government tenders, GB standards for Chinese domestic procurement—drives price differentiation between tiers. Cost compression in economy-grade hydraulic platforms is intensifying because steel price volatility erodes margin predictability for Asian manufacturers. Distributed commercial installers exhibit highest price sensitivity; gigawatt-scale developers with consolidated procurement power negotiate least.
Supply Chain Analysis
Hydraulic system components rest on German precision engineering houses, Chinese casting foundries, and South Korean electronics suppliers for GNSS guidance modules. Critical inputs include high-tensile steel forgings, eccentric rotating masses for vibratory mechanisms, and electromagnetic shielding alloys. Single-source vulnerability concentrates in German sensor suppliers validated for KBA electromagnetic compatibility protocols. Distribution runs through Vermeer's North American dealer network, XCMG's direct state-enterprise relationships in China, and consolidated direct vendor negotiations displacing intermediaries in Australian gigawatt-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semi-automated GNSS-guided positioning systems are displacing legacy hydraulic platforms, compressing replacement cycles as Germany's KBA mandates two-centimeter tolerance validation.
For Market Incumbents: Deepen backward integration into high-grade structural steel supply to buffer margin erosion from commodity volatility threatening price-sensitive Asian markets. Accelerate multi-jurisdiction certification engineering—simultaneous CE marking, BIS conformity, and KBA validation—to compress 14-18 month product launch cycles before emerging automation specialists capture precision-guided market share. For New Entrants and Emerging Players: Capture periurban solar installation white space in noise-sensitive German municipalities where electric-hybrid platforms with sub-75 dB operating signatures face limited incumbent competition. Target floating photovoltaic foundation equipment for Australian coastal reservoirs, where corrosion-resistant composite pile specifications and wave-load engineering create technical barriers favoring specialized entrants over diversified construction equipment conglomerates. For Investors and Strategic Acquirers: Subscription contract penetration exceeding hardware-only transactions is the leading indicator that recurring revenue capture from remote diagnostics and predictive maintenance is reshaping vendor valuation multiples. Target asset-light precision automation specialists with GNSS integration capabilities and established KBA validation pathways, avoiding capital-heavy hydraulic platform manufacturers exposed to steel price volatility. Watch for BIS certification requirement expansion into Rajasthan and Gujarat state-level tenders as signal of regulatory barrier escalation filtering market access.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Bundles Vermeer's remote diagnostics with hardware sales, displacing dealer-mediated support relationships. |
| Multi-Jurisdiction Certification Acceleration | Compresses CE marking, BIS conformity, and KBA validation timelines for export-oriented manufacturers. |
| Composite Pile Material Partnership | Enables corrosion-resistant fiberglass-reinforced polymer deployment in Australian saline coastal installations. |
| Electric-Hybrid Product Line Launch | Captures German periurban solar arrays facing KBA-enforced decibel limits below 75 dB. |
| Direct Vendor Relationship Consolidation | Displaces traditional dealer intermediation in Rajasthan and Gujarat gigawatt-scale procurement. |
Research Methodology
Independent corroboration across equipment manufacturer sales directors, solar EPC procurement leads, and aftermarket service heads underwrites the qualitative findings, validated against customs trade data, FERC interconnection queue filings, and Indian PLI scheme disbursement records. Bottom-up project pipeline aggregation triangulates against top-down manufacturing capacity surveys.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window, modeling equipment type, automation intensity, application scale, and end-user procurement sophistication as segmentation dimensions. CAGRs derive from installed base replacement cycles, new project development pipelines, and technology substitution elasticities, with steel price volatility and certification timeline compression as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to India's domestic content mandate expansion, China's MIIT procurement policy enforcement, and European carbon-border adjustment mechanism implementation. A concentrated set of regulatory triggers—BIS certification scope expansion, KBA electromagnetic compatibility protocol revision, and Australian TGA-equivalent state-level machinery safety harmonization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Plasma Cutting Machine Market