
 Forklift Work Platforms Market | 2026-2036
Forklift Work Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Work Platforms Market Analytics
Modular platform configurations is restructuring buyer procurement patterns across the forklift work platforms landscape. JLG Industries leverages its aerial equipment heritage to dominate integrated safety system offerings. Haulotte Group anchors European distribution through specialized height-adjustable designs. Manitou Group competes on manufacturing scale across standard and custom platform lines.
A forklift work platform is a steel or aluminum elevated work surface mounted on industrial forklifts, typically rated for loads between 500 and 1,000 pounds and heights reaching 20 to 40 feet, designed to transport personnel safely during maintenance, inventory, and installation tasks. Standard platforms occupy the largest volume share due to universal compatibility with Class II and Class III forklifts, while custom platforms capture premium margins from aerospace and energy sector specifications. Adjustable platforms represent the fastest-growing product type as facilities seek single-unit flexibility across variable rack heights.
OSHA mandates guardrail heights and toe board requirements that directly shape platform engineering specifications and buyer compliance budgets. ANSI certification protocols and ISO structural standards further segment suppliers by testing rigor and documentation depth. Stakeholders must monitor evolving state-level workplace safety amendments and insurance liability frameworks that increasingly reference third-party platform certification status.
Market Dynamics
OSHA compliance mandates and ANSI certification requirements are compressing procurement cycles as warehouse operators accelerate fleet modernization to avoid liability exposure. E-commerce fulfillment centers now specify third-party certified platforms as standard vendor qualification criteria.
Growth Catalysts
- E-commerce fulfillment expansion:United States distribution centers are retrofitting existing forklift fleets with ANSI-compliant work platforms rather than purchasing dedicated aerial lifts.
- OSHA guardrail mandates:The agency's updated fall protection directives require toe boards and mid-rails on all elevated personnel platforms, forcing replacement of legacy equipment.
- Modular aluminum construction:Lightweight alloy fabrication reduces forklift load capacity consumption, enabling single-unit deployment across variable rack heights.
Market Restraints
- Steel and aluminum price volatility:Input cost swings compress margin predictability for platform fabricators serving price-sensitive warehouse operators.
- Specialized welder scarcity:AWS D1.1 structural welding certification requirements limit qualified production capacity in North American fabrication shops.
- Scissor lift substitution:Self-propelled aerial work platforms compete directly for maintenance and installation tasks above 25 feet.
Strategic Opportunities
- Canadian provincial adoption gaps:Ontario and Quebec workplace safety boards are harmonizing standards with federal OSHA language, creating first-mover certification advantages.
- Rental fleet penetration:Equipment rental companies are adding work platforms to forklift attachment portfolios, expanding access for seasonal warehouse operators.
- IoT-enabled load monitoring:Integration of weight sensors and tilt alarms with existing warehouse management systems creates premium platform tiers.
Industry Challenges
- ANSI Z535 certification timelines:Third-party testing and documentation requirements extend product launch cycles by four to six months.
- Legacy forklift compatibility:Pre-2010 lift truck mast specifications lack standardized quick-attach interfaces, complicating platform retrofit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Work Platforms Market |
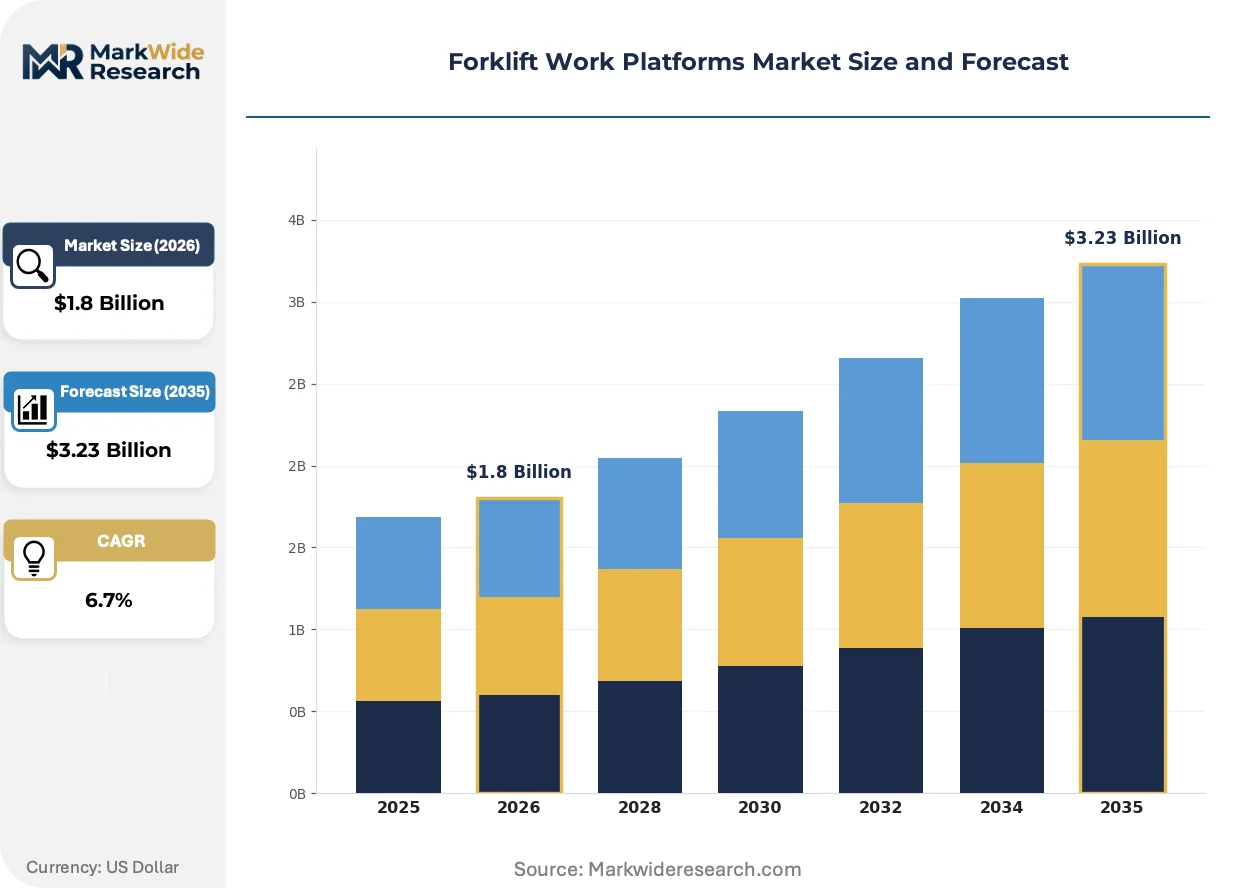
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Platforms, Adjustable Platforms, Folding Platforms, Custom Platforms Industry Vertical: Construction, Manufacturing, Warehousing, Distribution End User: Contractors, Maintenance Teams, Warehouse Operators, Retail Safety Standards: OSHA Compliant, ANSI Certified, ISO Certified, Others |
| Companies Covered | Manitou Group, Haulotte Group, JLG Industries, Terex Corporation, Aichi Corporation, Hunan Sinoboom Intelligent Equipment, Zhejiang Dingli Machinery, LGMG North America, MEC Aerial Work Platforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Work Platforms Market Evolving Landscape
Lightweight materials and integrated sensor systems are redefining platform engineering priorities. Fabricators now compete on data connectivity and single-unit flexibility rather than load capacity alone.
Aluminum-magnesium alloy framing is rewriting durability expectations for elevated work platforms. Regional grocery distribution networks in the Midwest are specifying these configurations for multi-shift operations. The material's corrosion resistance and weight reduction is compressing total cost of ownership calculations against traditional steel alternatives.
OSHA's updated Walking-Working Surfaces standard tightens guardrail height specifications for forklift-mounted platforms. Fabricators must redesign side-entry gates and toe board configurations to maintain compliance. Aerospace maintenance facilities in California and Washington are absorbing premium pricing for pre-certified configurations to accelerate deployment.
Rental-first procurement is displacing direct ownership among mid-size third-party logistics operators. United States-based equipment lessors are bundling platform attachments with forklift fleet contracts. This channel shift is most visible in Texas and Florida markets where seasonal demand volatility favors operational flexibility over capital deployment.
Forklift Work Platforms Market Segmentation
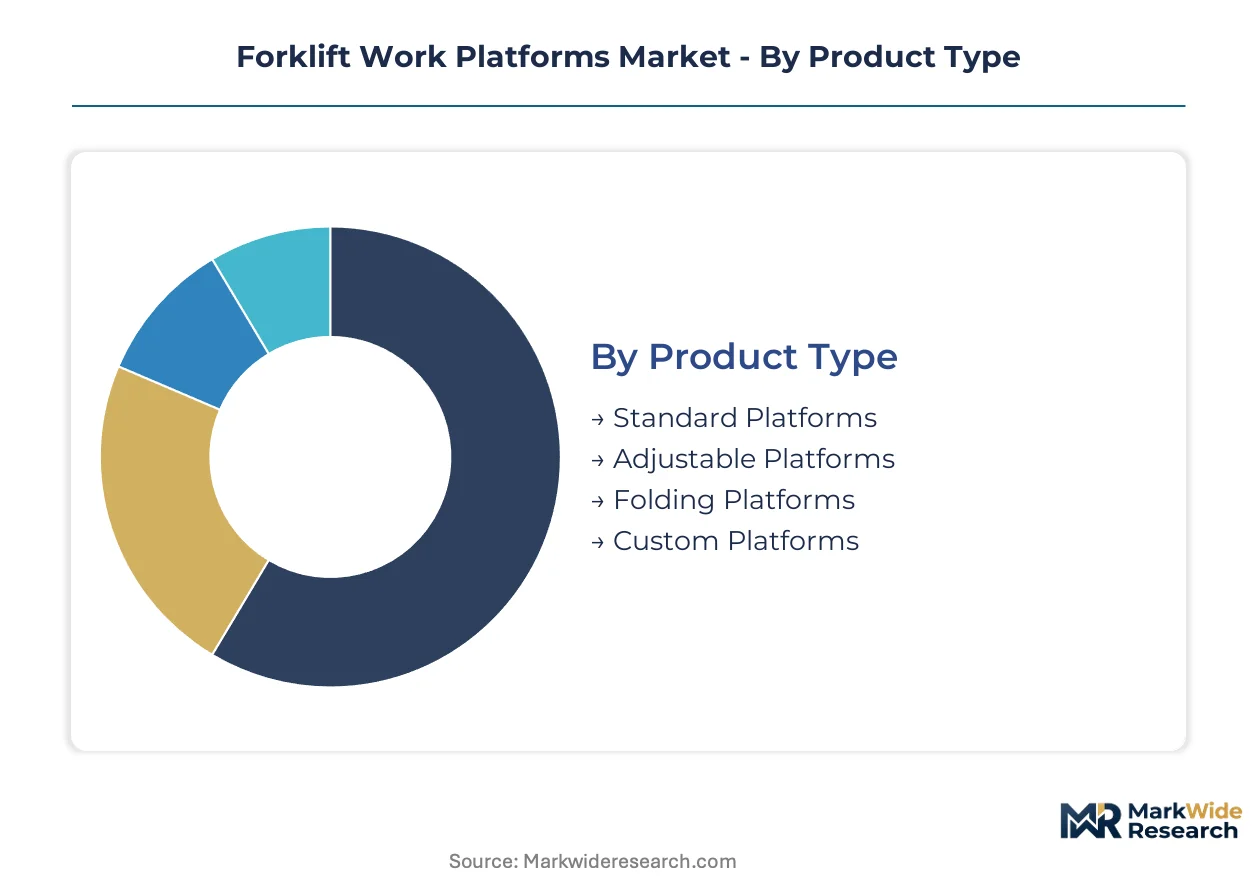
Platform specifications diverge sharply across operational environments. Capital allocation priorities differ between warehouse operators seeking fleet flexibility and aerospace contractors demanding certified custom fabrications. Procurement patterns cluster around safety certification tiers rather than price points alone.
Product Type:
Capital intensity peaks with custom engineered configurations requiring certified welding and third-party testing documentation. Standardized designs minimize upfront tooling investment but sacrifice margin capture.
- Standard Platforms:Universal steel or aluminum decks rated for 500-1,000 pound loads mount directly to Class II and III forklift masts without modification. Distribution centers in the United States specify these for inventory cycle counts and routine maintenance across uniform rack heights. OSHA guardrail mandates are accelerating replacement cycles for pre-2010 installations lacking toe board compliance.
- Adjustable Platforms:Telescoping or modular height configurations enable single-unit deployment across variable rack systems from 20 to 40 feet. Midwest grocery distribution networks absorb premium pricing for aluminum-magnesium alloy variants that reduce forklift capacity consumption. The flexibility premium justifies higher per-unit cost against dedicated standard units for each height tier.
- Folding Platforms:Collapsible side rails and hinged deck sections reduce storage footprint for seasonal operators. Texas and Florida rental fleets specify these for construction contractors with intermittent elevated access needs.
- Custom Platforms:Application-specific engineering serves aerospace maintenance hangars and energy sector infrastructure with non-standard dimensions or integrated tool mounting. California facilities pay certification premiums to compress deployment timelines.
Most installed capacity flows through Standard Platforms. Expansion is steepest in Adjustable Platforms.
Industry Vertical:
Application severity determines specification grade and replacement frequency. Heavy-duty cycles in outdoor construction degrade platforms faster than climate-controlled warehouse duty.
- Construction:Ruggedized steel platforms withstand weather exposure and rough terrain forklift operation. Contractors in Texas oilfield service corridors specify reinforced toe boards and expanded metal decking for debris shedding.
- Manufacturing:Precision assembly tasks demand vibration-dampened mounting interfaces and integrated electrical conduit routing. Automotive plants in the Midwest specify these for production line maintenance windows.
- Warehousing:High-frequency pick operations drive specification toward lightweight aluminum to preserve forklift battery runtime. E-commerce fulfillment centers mandate ANSI certification as vendor qualification criteria.
- Distribution:Cross-dock operations with seasonal volume spikes favor rental procurement over ownership. Third-party logistics operators in Florida consolidate platform attachments with forklift fleet contracts.
Warehousing commands the largest installed base. Construction shows the steepest specification upgrade trajectory as OSHA enforcement tightens.
End User:
Procurement authority and technical specification knowledge vary dramatically across user types. Maintenance teams influence engineering requirements more directly than purchasing departments.
- Contractors:Project-based demand favors rental channels and rapid deployment certification. General contractors in California absorb premium pricing for pre-certified platforms to avoid inspection delays.
- Maintenance Teams:Technical users specify integrated safety features including self-closing gates and tool tethering points. Manufacturing facility engineers in Washington State drive demand for ISO-certified structural documentation.
- Warehouse Operators:Fleet standardization priorities favor universal compatibility across mixed forklift populations. Regional grocery chains in the Midwest consolidate on single adjustable platform models.
- Retail:Limited technical staff drives preference for turnkey installation and operator training bundles. Big-box store distribution networks specify vendor-managed inventory programs.
Warehouse Operators deploy the most units. Maintenance Teams are gaining specification authority fastest as safety liability concentrates with technical decision-makers.
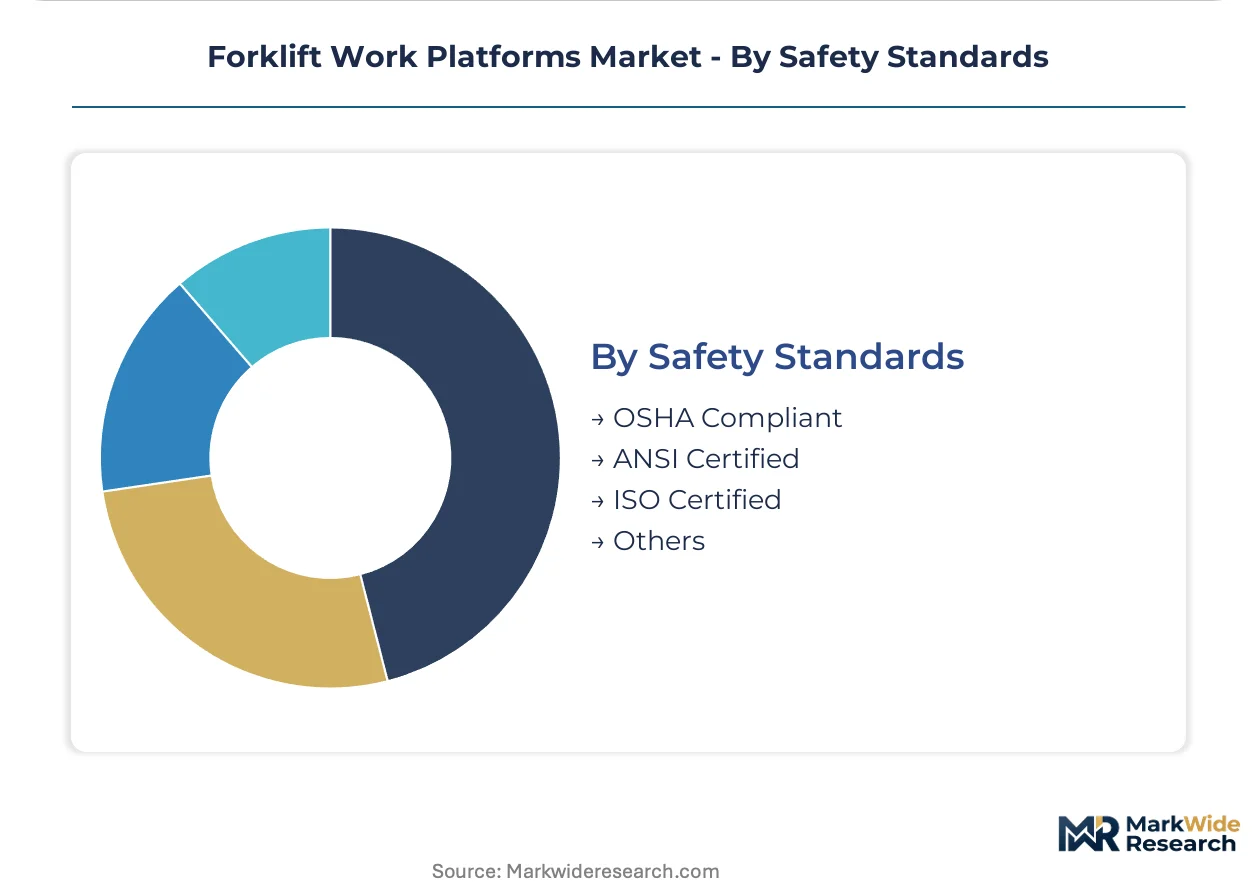
Safety Standards:
Certification tier functions as market segmentation mechanism, with testing rigor and documentation depth determining supplier qualification.
- OSHA Compliant:Minimum regulatory threshold covering guardrail heights, toe boards, and fall protection anchorage points. State-level workplace safety amendments in Ontario are harmonizing with federal language.
- ANSI Certified:Third-party structural testing and documentation extending product launch cycles by four to six months. E-commerce fulfillment centers now require this tier as standard vendor qualification.
- ISO Certified:International structural standards enabling cross-border equipment deployment for multinational operators. Aerospace maintenance facilities specify these for global fleet standardization.
- Others:Provincial or industry-specific certifications including Canadian provincial standards and energy sector operator qualifications.
OSHA Compliant units represent the largest installed base. ANSI Certified configurations are climbing the fastest as procurement policies formalize third-party testing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forklift work platforms originated in post-war American manufacturing plants, where steel-decked personnel carriers first mounted to industrial lift trucks. The industry's geographic footprint now tracks e-commerce fulfillment density and aerospace maintenance corridors across five core markets.
United States
OSHA compliance mandates and ANSI certification requirements are accelerating fleet modernization across distribution networks. The Department of Labor's updated Walking-Working Surfaces standard tightens guardrail specifications for elevated platforms. E-commerce fulfillment centers in the Inland Empire and Dallas-Fort Worth corridors specify third-party certified platforms as standard vendor qualification criteria.
Germany
Automotive production line maintenance windows drive specification toward vibration-dampened mounting interfaces. CE marking requirements and the EU Machinery Directive shape engineering documentation depth for cross-border equipment deployment. Stuttgart and Munich aerospace clusters absorb premium pricing for ISO-certified structural configurations to accelerate global fleet standardization.
Canada
Ontario and Quebec workplace safety boards are harmonizing provincial standards with federal OSHA language, creating first-mover certification advantages. Health Canada references ANSI Z535 protocols for industrial equipment safety assessments. Toronto and Montreal distribution networks are retrofitting existing forklift fleets with compliant work platforms rather than purchasing dedicated aerial lifts.
China
MIIT industrial equipment standards and GB structural certification protocols segment suppliers by testing rigor. The dual carbon goals initiative favors lightweight aluminum-magnesium alloy fabrication to reduce energy consumption. Yangtze River Delta manufacturing hubs specify modular height configurations for single-unit deployment across variable rack systems.
Japan
METI manufacturing modernization programs incentivize IoT-enabled load monitoring integration with warehouse management systems. JIS structural standards enable domestic certification for export-qualified fabricators. Nagoya automotive plants and Osaka distribution networks specify self-closing gates and tool tethering points for technical maintenance teams.
Forklift Work Platforms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and documentation rigor. The vendor base clusters around three strategic tiers: integrated aerial equipment heritage firms, specialized height-adjustable designers, and manufacturing-scale standard platform fabricators. Dominant competitive moves include strategic partnerships with equipment rental companies and geographic expansion through provincial safety standard harmonization.
Within the heritage-integrated tier, JLG Industries and Haulotte Group exemplify premium positioning through aerial equipment lineage and European distribution specialization. Manitou Group occupies a scale-driven position across standard and custom platform lines. Zhejiang Dingli Machinery and Hunan Sinoboom Intelligent Equipment represent Chinese manufacturing-scale archetypes serving cost-optimized procurement segments.
| Leading Market Players |
|---|
| Manitou Group |
| Haulotte Group |
| JLG Industries |
| Terex Corporation |
| Aichi Corporation |
| Hunan Sinoboom Intelligent Equipment |
| Zhejiang Dingli Machinery |
| LGMG North America |
| MEC Aerial Work Platforms |
| Others |
Value Network & Pricing Analysis
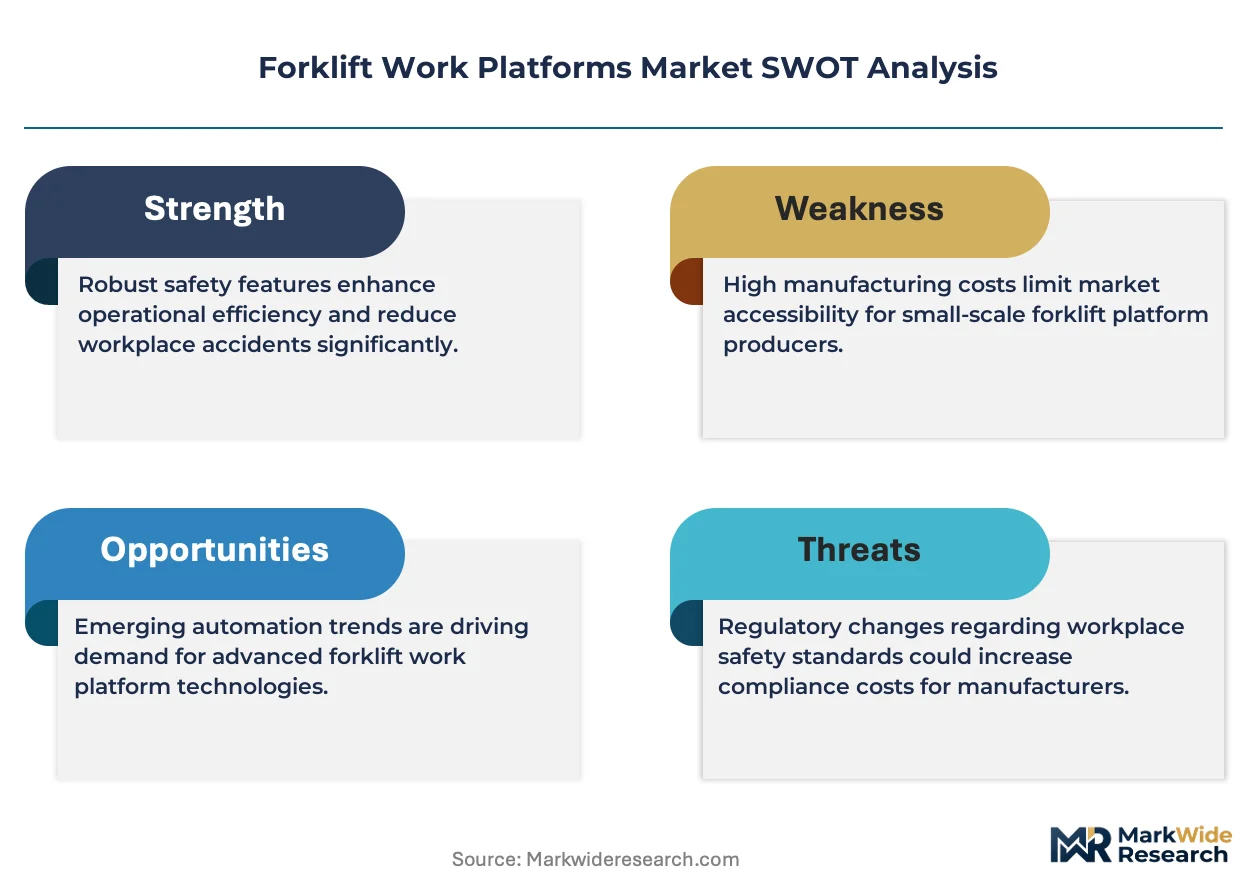
ANSI certification requirements from e-commerce fulfillment centers are forcing fabricators to absorb extended testing timelines and documentation costs, compressing margins on standard platforms while creating premium capture opportunities for pre-certified configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade and customization depth as primary differentiation drivers. Price erosion runs through economy-tier steel platforms as Chinese manufacturing-scale entrants compete on volume. Warehouse operators exhibit highest price sensitivity, while aerospace maintenance facilities absorb premium pricing for ISO-certified custom fabrications.
Supply Chain Analysis
Refurbishment flows from rental fleet rotations and trade-in programs create secondary supply channels for mid-market buyers. Manufacturing concentrates in the United States, China, and Germany, with aluminum-magnesium alloy sheet and structural steel tubing as core inputs. Single-source vulnerability around AWS D1.1 certified welding capacity constrains North American production expansion. Distribution runs through equipment rental companies and OEM attachment bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA's updated Walking-Working Surfaces standard creates replacement demand cycles that outpace organic growth.
For Market Incumbents: Anticipate scissor lift substitution above 25 feet by embedding IoT-enabled load monitoring into premium platform tiers. Backward integration into aluminum-magnesium alloy sourcing secures margin control against commodity volatility. ANSI Z535 certification investment creates defensible positioning as procurement policies formalize third-party testing requirements. For New Entrants and Emerging Players: Enter via Canadian provincial harmonization gaps in Ontario and Quebec, where workplace safety boards are adopting OSHA-aligned standards without established supplier relationships. Rental fleet penetration offers lowest customer acquisition cost against direct sales to capital-constrained seasonal operators. Pre-certified platform configurations accelerate deployment timelines for compliance-driven buyers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized height-adjustable designers possessing European CE marking documentation and North American ANSI certification dual qualification. Long-term viability hinges on regulatory enforcement consistency across jurisdictions. Monitor state-level workplace safety amendment adoption rates as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ANSI Certification Investment | Third-party testing documentation compresses sales cycles for e-commerce fulfillment procurement teams. |
| Rental Fleet Partnership | Equipment lessor bundling agreements expand addressable market for seasonal warehouse operators. |
| IoT Sensor Integration | Load monitoring and tilt alarm connectivity creates premium tier separation from commodity platforms. |
| Aluminum-Magnesium Alloy Transition | Lightweight fabrication reduces forklift capacity consumption and extends battery runtime for high-frequency operations. |
| Canadian Market Expansion | Provincial standard harmonization creates first-mover certification advantages in Toronto and Montreal distribution corridors. |
Research Methodology
Multiple input streams — maintenance director interviews, OEM procurement team discussions, rental fleet operator surveys, and aftermarket service head consultations — were reconciled against customs records, SEC equipment manufacturer filings, and OSHA enforcement databases. Bottom-up unit shipment estimates triangulated with top-down addressable market sizing.
Historical volume trajectories cross-referenced against panel input from plant engineers and distribution channel partners shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, industry vertical, safety certification tier, and end-user procurement authority. CAGRs derived from elasticity-adjusted replacement cycle analysis and e-commerce fulfillment center expansion pipelines.
Inputs from regulatory filing databases and equipment registration records were available through the study window; gaps in provincial enforcement intensity data introduce uncertainty bands around Canadian market penetration assumptions. Practitioners should monitor OSHA state plan adoption rates and insurance liability framework amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Global Linear Guide Market