
 Hydraulic Fittings Market | 2026-2036
Hydraulic Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Fittings Market Analysis
Asset-light leasing models for mobile hydraulic systems is reconfiguring how smaller fleet operators access high-performance fittings without capital deployment. Parker Hannifin leverages its captive distribution network to control specification standards across North American rental channels. Eaton anchors its position through backward integration into hose and coupling manufacturing, capturing margin pools that fragment competitors. Manuli Hydraulics specializes in thermoplastic solutions for subsea umbilicals, occupying a defensible niche where certification barriers limit rivalry.
Hydraulic fittings are precision-machined connection components, typically rated for dynamic pressures exceeding 6,000 psi, that create leak-free junctions between hoses, pipes, and actuators in fluid power systems. Manufacturing employs CNC turning of bar stock followed by zinc-nickel plating or passivation to resist corrosion in caustic operating environments. Hose fittings and adapters command the largest revenue share within product type segments, sustained by replacement cycles in aging construction and agricultural machinery fleets. Stainless steel material grades are gaining specification share in offshore and food-processing applications where carbon steel corrosion failures carry catastrophic cost consequences. Steel remains the volume backbone across industrial machinery and mobile equipment applications where cost sensitivity dominates procurement criteria.
ISO 19879 pressure-containment testing standards and SAE J514 dimensional specifications govern product interoperability and liability exposure for manufacturers serving multinational OEMs. The EPA's National Emphasis Program on hydraulic fluid spills and the EU Machinery Directive's leak-prevention mandates are elevating demand for zero-leak connection technologies across regulated jurisdictions. Stakeholders must monitor how carbon-border adjustment mechanisms reshape sourcing economics for forged steel fittings and cast brass components.
Market Dynamics
EU F-Gas Regulation and REACH compliance frameworks are compressing material specification windows for seal compounds, forcing manufacturers to requalify entire product lines or exit European supply chains.
Growth Catalysts
- Infrastructure stimulus packages:Emerging economies are expanding construction equipment fleets, intensifying OEM demand for high-pressure connection systems in excavators and loaders.
- REACH material mandates:The EU's chemical registration framework is accelerating substitution of legacy elastomers with fluoropolymer and HNBR seal compounds certified for extended temperature ranges.
- Subsea energy development:Thermoplastic solutions for umbilical systems are gaining specification share in offshore oil and gas installations where metal fatigue risks dominate operational concerns.
Market Restraints
- Alloy price volatility:Nickel and zinc input costs for plating processes fluctuate with London Metal Exchange spot markets, compressing margin stability for forged fitting producers.
- German supply concentration:Hydraulic system rebuild rates in Germany's industrial corridor exceed regional averages, creating dependency on a single geography for aftermarket volume.
- SAE J514 dimensional lock-in:Legacy thread specifications constrain design innovation for manufacturers seeking to differentiate on connection geometry rather than material grade.
Strategic Opportunities
- India infrastructure buildout:National highway and port modernization programs are expanding mobile equipment fleets beyond current service network coverage.
- Zero-leak connection technologies:EPA National Emphasis Program enforcement on hydraulic fluid spills is elevating demand for face-seal and flareless designs in regulated jurisdictions.
- IoT-enabled condition monitoring:Sensor integration with fitting assemblies creates predictive maintenance revenue streams alongside hardware sales.
Industry Challenges
- CNC machining talent scarcity:Precision turning of 6,000 psi-rated bar stock requires skilled operators that industrial regions struggle to retain.
- ISO 19879 certification timelines:Pressure-containment testing protocols extend product qualification cycles, delaying revenue recognition for new fitting geometries.
- Legacy system integration friction:Retrofitting zero-leak designs into aging agricultural machinery fleets demands adapter proliferation that complicates inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Fittings Market |
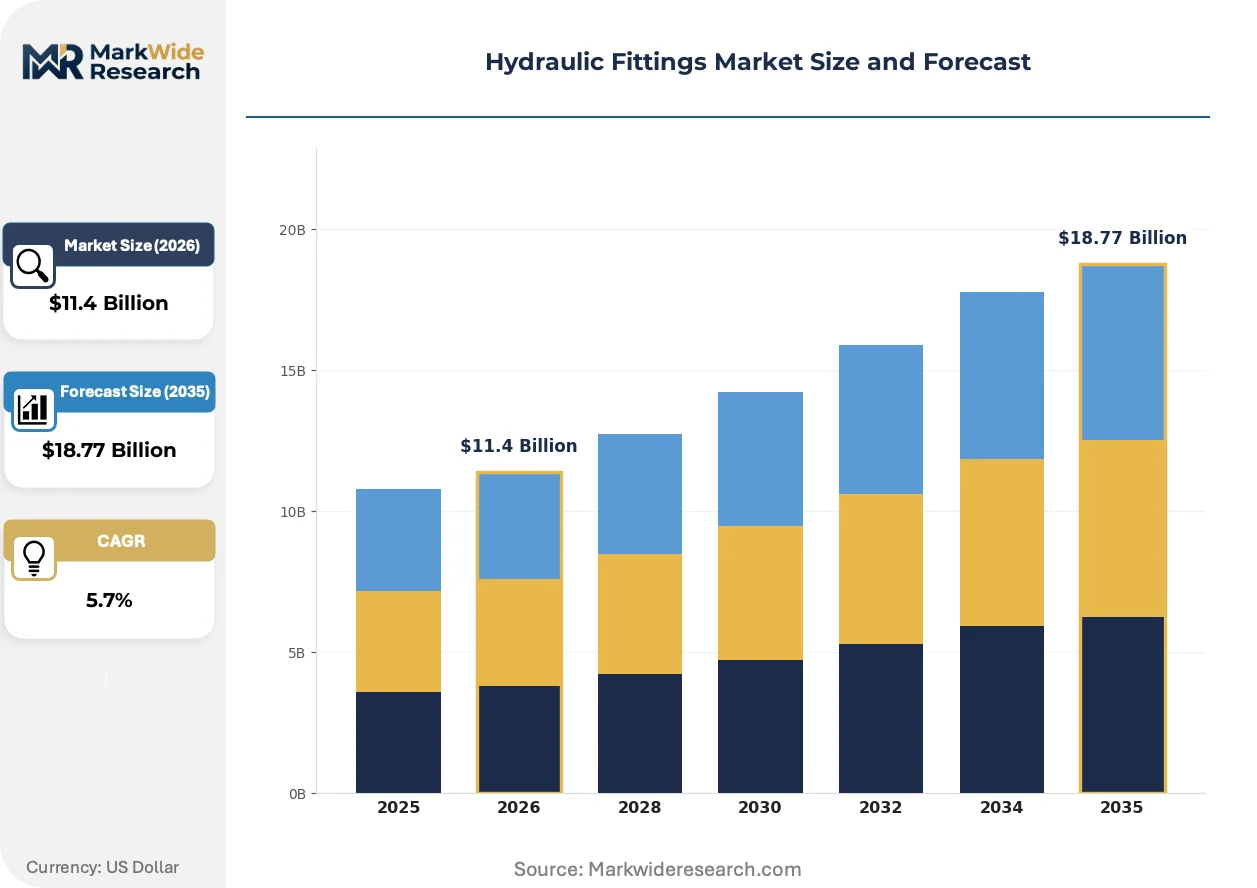
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adapters, Hose Fittings, Couplings, Pipe Fittings Material: Steel, Stainless Steel, Brass, Plastic Application: Construction Equipment, Oil & Gas, Agriculture, Industrial Machinery End User: Manufacturers, Contractors, Distributors, Maintenance Providers |
| Companies Covered | Parker Hannifin, Eaton, Manuli Hydraulics, Gates Corporation, Hansa-Flex, Alfagomma, Brennan Industries, Kurt Hydraulics, Ryco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Fittings Market Emerging Trajectories
Connection technology is migrating from metal-to-metal sealing toward engineered polymer interfaces, while regulatory pressure on fluid containment accelerates qualification requirements for next-generation designs.
Thermoplastic hose fittings are migrating from niche subsea applications into mainstream mobile equipment. Offshore umbilical manufacturers pioneered these solutions for corrosion immunity at depth. Construction OEMs in Scandinavia now specify thermoplastic couplings for excavators operating in coastal environments with high chloride exposure. This migration is compressing the addressable market for traditional zinc-nickel plated steel in premium segments.
EPA's National Emphasis Program on hydraulic fluid spills is elevating liability exposure for fleet operators. The enforcement mechanism targets visible leaks during routine inspections, creating immediate compliance costs. Food processing and municipal waste handling equipment in the US faces the strictest scrutiny, driving specification shifts toward face-seal and O-ring boss connection standards that eliminate thread-path seepage.
Asset-light leasing models are fragmenting traditional distribution channels for mobile hydraulic systems. Smaller fleet operators now access high-performance fittings through rental channels rather than capital purchase. This channel shift concentrates specification authority with captive distribution networks rather than end-user procurement departments. Germany's construction rental market exhibits the most advanced penetration of this model.
Hydraulic Fittings Market Segmentation
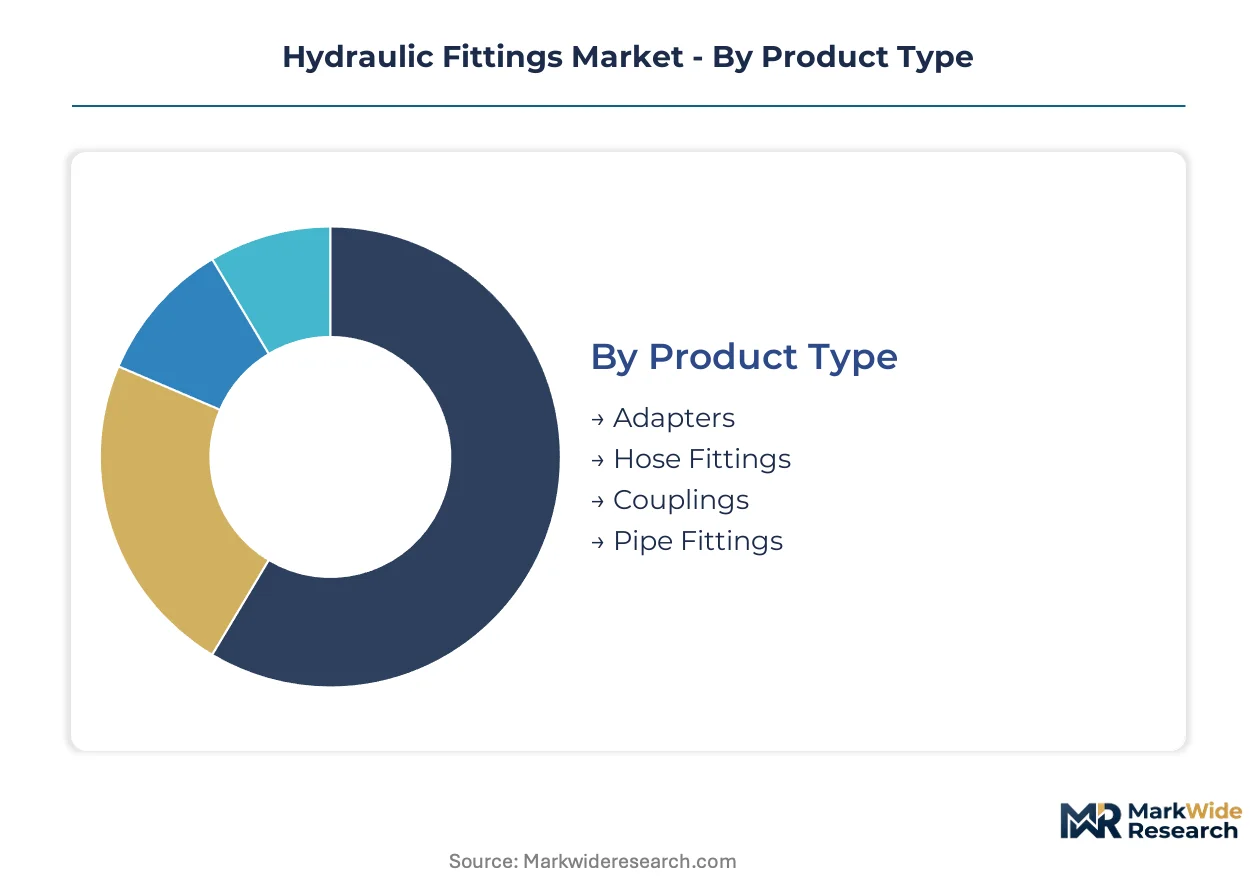
Hydraulic fittings serve pressure-rated connection functions across radically different operating environments. Segmentation reveals how material selection and geometry specifications diverge between mobile equipment fleets and fixed industrial installations.
Product Type:
Use-case spectrum spans permanent pipeline installations to frequent-disconnect mobile systems where thread geometry determines field serviceability.
- Hose Fittings:Crimped or reusable termination components engineered for flexible conduit attachment in high-vibration mobile equipment. Demand concentrates in construction equipment rebuild cycles across Germany's industrial corridor, where fleet operators prioritize rapid field replacement over permanent installation durability.
- Adapters:Thread-transition components bridging incompatible connection standards between OEM systems and aftermarket replacements. Specification authority is shifting toward rental channel distributors in Scandinavia as asset-light leasing models fragment traditional procurement hierarchies.
- Couplings:Quick-connect interfaces enabling tool changeover in multi-function hydraulic circuits.
- Pipe Fittings:Rigid-threaded junctions for permanent industrial plumbing with lower pressure-cycle frequency.
Established volume favors hose fittings; emerging adoption favors adapters as fleet complexity multiplies connection standard fragmentation.
Material:
Cost tier separation runs from commodity carbon grades through corrosion-resistant alloys to engineered polymers for specialized chemical resistance.
- Steel:Zinc-nickel plated bar stock machined to SAE J514 specifications remains the volume backbone across price-sensitive industrial machinery applications. Margin stability fluctuates with London Metal Exchange nickel spot pricing, compressing forged fitting producer profitability during input cost spikes.
- Stainless Steel:Austenitic and duplex grades specified where chloride-induced corrosion failures carry catastrophic operational consequences. Food processing installations in regulated US jurisdictions and offshore platforms in the North Sea drive specification share gains under EPA spill-prevention and EU Machinery Directive mandates.
- Brass:Cast and forged copper-zinc alloys for lower-pressure pneumatic and fluid power applications with moderate corrosion exposure.
- Plastic:Reinforced thermoplastic compounds penetrating mobile equipment through weight reduction and galvanic isolation benefits.
Steel dominates procurement tonnage; stainless steel climbs the fastest on regulatory pressure for extended service life in critical applications.
Application:
Volume concentration maps directly to capital equipment fleet scale and replacement part velocity in primary extraction and earthmoving sectors.
- Construction Equipment:Excavators, loaders, and cranes operating at 6,000 psi dynamic pressures with highest fitting replacement frequency. India's national highway and port modernization programs are expanding mobile equipment fleets beyond current authorized service network coverage, creating aftermarket supply gaps.
- Oil & Gas:Subsea umbilical and topside processing systems demanding thermoplastic solutions where metal fatigue risks dominate operational concerns. Manuli Hydraulics occupies a defensible niche through specialized certification barriers that limit rival entry.
- Agriculture:Tractor and implement hydraulic systems with seasonal usage patterns and extended replacement intervals.
- Industrial Machinery:Fixed manufacturing equipment with lower pressure-cycle counts but higher precision requirements.
Construction equipment generates the steepest replacement velocity; oil and gas commands the highest specification barriers.
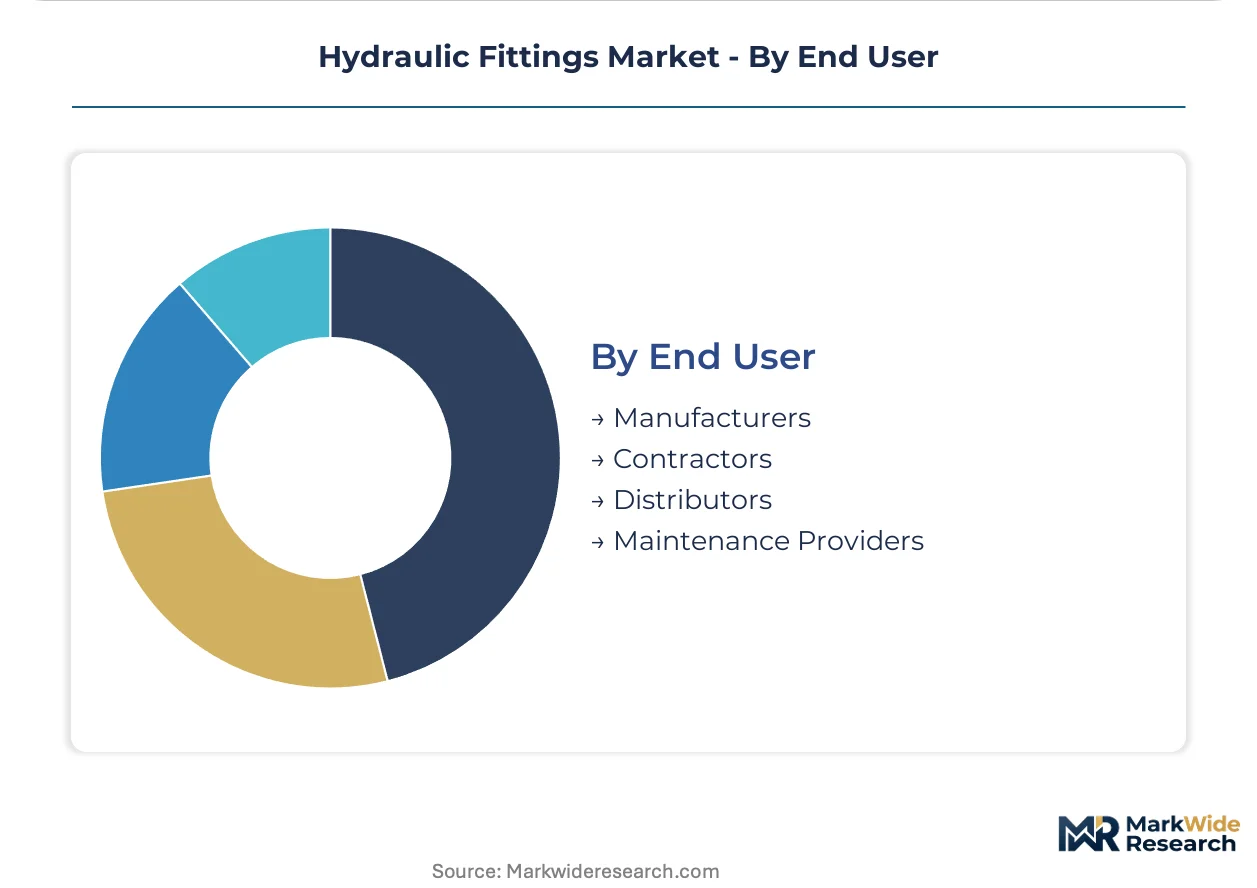
End User:
Procurement authority is fragmenting as rental channel intermediaries displace direct fleet operator purchasing in mobile equipment segments.
- Distributors:Authorized channel partners controlling specification standards through captive inventory and technical service relationships. Parker Hannifin leverages its captive distribution network to enforce interoperability requirements across North American rental channels, concentrating margin capture upstream.
- Maintenance Providers:Independent rebuild shops and OEM service operations with direct fitting specification authority during system overhaul events. Germany's hydraulic system rebuild rates exceed regional averages, creating aftermarket volume dependency on specialized service infrastructure.
- Manufacturers:OEM engineering departments setting initial equipment specifications for new machine builds.
- Contractors:Project-based fleet operators with variable procurement consistency and price sensitivity.
Distributors consolidate specification control; maintenance providers gain share fastest as fleet aging extends equipment service life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates aftermarket rebuild demand, while India's infrastructure expansion and the United States' spill-prevention enforcement create divergent procurement patterns across buyer archetypes.
Germany
Hydraulic system rebuild rates in Germany's industrial corridor exceed regional averages, driving aftermarket volume concentration. The EU F-Gas Regulation and REACH compliance frameworks tighten material specifications for seal compounds and surface coatings. Stuttgart and Munich anchor precision machining clusters where CNC turning capacity serves both domestic OEMs and export markets.
United States
Construction equipment fleets and food processing installations generate replacement fitting demand under strict liability exposure. The EPA's National Emphasis Program on hydraulic fluid spills elevates enforcement against visible leaks during routine inspections. Houston's energy corridor and Chicago's manufacturing belt concentrate distributor networks controlling specification standards.
India
National highway and port modernization programs expand mobile equipment fleets beyond current authorized service network coverage. The Bureau of Indian Standards (BIS) certification requirements shape import substitution patterns for high-pressure connection systems. Maharashtra and Gujarat host emerging fabrication capacity serving domestic construction OEMs.
China
Infrastructure stimulus and domestic construction equipment production scale drive procurement volume for SAE J514-specified components. The Ministry of Ecology and Environment (MEE) enforcement on industrial fluid containment elevates specification requirements in coastal manufacturing zones. The Yangtze River Delta concentrates both OEM assembly plants and precision machining subcontractors.
Brazil
Agricultural machinery fleets and mining equipment operations sustain replacement cycles for hose fittings and adapters. ANVISA regulatory frameworks influence material specifications for food-processing and pharmaceutical manufacturing applications. São Paulo state's industrial corridor anchors distributor networks serving the Mercosur region.
Hydraulic Fittings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into captive distribution networks, backward-integrated manufacturers, and niche certification holders. Three archetypes dominate: scale-driven specification setters, vertically integrated margin capturers, and defensible-niche specialists. M&A activity concentrates distribution assets, while capacity expansion targets thermoplastic production lines.
Among North American specification setters, Parker Hannifin and Eaton anchor channel-control positions. Parker Hannifin represents the captive distribution archetype, while Eaton exemplifies backward integration into hose and coupling manufacturing. Manuli Hydraulics occupies the defensible-niche position, specializing in subsea applications where certification barriers limit rival entry.
| Leading Market Players |
|---|
| Parker Hannifin |
| Eaton |
| Manuli Hydraulics |
| Gates Corporation |
| Hansa-Flex |
| Alfagomma |
| Brennan Industries |
| Kurt Hydraulics |
| Ryco |
| Others |
Supply Flow & Price Mechanics
Stuttgart's precision machining cluster anchors European supply capacity for 6,000 psi-rated hydraulic fittings, translating concentrated CNC turning expertise into pricing power for certified component producers serving multinational OEMs. REACH-mandated material requalification costs propagate downstream, compressing margins for non-compliant suppliers while consolidating premium tier positions among certification holders.
Pricing Analysis
Certification level (ISO 19879/SAE J514-grade) creates the primary spread between commodity zinc-nickel plated steel and validated zero-leak connection systems. Three-tier pricing structure across premium, standard, and economy levels reflects fluoropolymer seal compound costs, with face-seal designs commanding substantial premiums over legacy threaded alternatives. Cost compression in standard-grade segments intensifies as nickel spot volatility from London Metal Exchange feeds through plating process economics. Fleet operators in India's emerging infrastructure corridors exhibit highest price sensitivity, while North Sea offshore contractors prioritize leak-prevention certification over unit cost.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculations for forged steel fitting producers. Manufacturing gravity centers on China's Yangtze River Delta, Germany's Stuttgart-Munich corridor, and India's Maharashtra-Gujarat belt for precision-machined bar stock conversion. Raw material dependencies rest on London Metal Exchange-tracked nickel and zinc for plating processes, plus specialty HNBR and fluoropolymer compounds for REACH-compliant seals. Single-source vulnerability concentrates in subsea thermoplastic umbilical certification holders. Distribution runs through captive rental channel networks in North America and authorized service partnerships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision CNC machining talent scarcity constrains capacity expansion across all tier levels, privileging incumbents with established apprenticeship pipelines and locking new entrants into equipment-light thermoplastic niches.
For Market Incumbents: Insulate specification authority by deepening captive distribution control over rental channel procurement decisions, particularly in Germany's asset-light construction equipment market. Accelerate backward integration into fluoropolymer seal compound production to capture margin pools that REACH compliance is compressing for outsourced suppliers. Defend against thermoplastic substitution by investing in zinc-nickel plating process automation that sustains cost competitiveness against polymer alternatives in coastal corrosion environments. For New Entrants and Emerging Players: India's authorized service network gaps present the most penetrable white-space for aftermarket hose fitting supply, with national highway expansion outpacing OEM service infrastructure deployment. Target thermoplastic quick-connect couplings for Scandinavian coastal construction fleets where chloride exposure validates premium material substitution. Pursue BIS certification pathways early to secure import substitution positioning before domestic fabrication capacity matures in Maharashtra and Gujarat. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors controlling specification standards through technical service relationships rather than transactional component vendors. Long-term viability over a multi-year horizon favors acquisition targets with captive rental channel penetration and REACH requalification completion, avoiding stranded assets in legacy elastomer-dependent product lines. Monitor EPA National Emphasis Program enforcement intensity as the inflection signal for zero-leak technology specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compounds | Captures fluoropolymer margin pools that REACH mandates are concentrating among qualified suppliers. |
| Thermoplastic Production Line Expansion | Addresses subsea umbilical and coastal construction demand where metal fatigue risks dominate specifications. |
| IoT-Enabled Condition Monitoring Launch | Creates predictive maintenance revenue streams alongside hardware sales through sensor-integrated fitting assemblies. |
| India Service Network Partnership | Closes aftermarket supply gaps created by infrastructure fleet expansion beyond authorized coverage. |
| Zero-Leak Certification Investment | Secures specification share under EPA spill-prevention enforcement and EU Machinery Directive mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from listed component suppliers, ISO certification registries, and EPA enforcement records. Plant managers at precision machining facilities, procurement leads at construction equipment OEMs, aftermarket service heads at distributor networks, and regulatory affairs specialists at seal compound manufacturers provided operational validation. Bottom-up fitting shipment data triangulates against top-down construction equipment production estimates and hydraulic system rebuild rates.
Forecast inputs incorporate product type segmentation across hose fittings, adapters, couplings, and pipe fittings; material grade tiers from commodity steel through stainless and thermoplastic; application splits between construction equipment, oil and gas, agriculture, and industrial machinery; and end-user channel structures from captive distribution to independent maintenance providers. CAGRs derive from fitted trend extrapolation moderated by regulatory phase-in schedules and infrastructure stimulus disbursement patterns. Nickel spot price volatility and REACH requalification timelines feed through as sensitivity variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese fabricators or rapid thermoplastic technology substitution would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Global Hydraulic Equipment Market