
 ASEAN Construction Equipment Rental Market | 2026-2036
ASEAN Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Construction Equipment Rental Market Outlook
Equipment financing channels across Southeast Asia are reshaping how contractors access heavy machinery without balance-sheet ownership. Kanamoto Co. Ltd leverages its Japan-ASEAN logistics network to sustain rapid fleet redeployment between Thailand and Vietnam project clusters. Nishio Rentall anchors premium crane availability in urban high-rise zones where tower erection cycles demand just-in-time delivery. PT Coates Indonesia dominates Indonesian mining-adjacent construction with specialized earthmoving units that navigate terrain constraints conventional lessors avoid.
ASEAN construction equipment rental denotes the commercial provision of mobile and stationary machinery—typically powered by diesel or electric drivetrains with operating weights from 1.5 to 800 metric tons—on contractual terms spanning days to years, eliminating capital outlay for project owners. The primary industrial purpose centers on enabling civil engineering, building construction, and resource extraction without fixed-asset commitment across volatile project pipelines. Excavators lead equipment type demand due to versatility in trenching, demolition, and material handling across ASEAN's diverse topography. Long-term rental arrangements among contractors capture the deepest margin pools as fleet utilization rates stabilize beyond twelve-month tenures, while short-term contracts serve spike-driven infrastructure stimulus cycles with higher per-day yields but erratic scheduling.
Indonesia's Ministry of Public Works and Housing mandates periodic equipment safety certification under national construction standards, while Thailand's Department of Industrial Works enforces emissions compliance on diesel-powered rental fleets operating in Bangkok metropolitan zones. Malaysia's CIDB registration requirements restrict project participation to contractors utilizing certified machinery, effectively filtering informal equipment lessors from federally funded contracts. Stakeholders must monitor how Vietnam's emerging circular economy directives on machinery lifecycle accountability reshape residual value calculations and fleet retirement timelines.
Market Dynamics
Government-mandated build-transfer-operate frameworks across Indonesia, Thailand, and Vietnam are compressing capital expenditure windows for infrastructure contractors, forcing permanent fleet ownership toward variable rental structures.
Growth Catalysts
- Build-Transfer-Operate Frameworks:Indonesia's Ministry of Public Works and Housing mandates capital-light project delivery models that privilege rental over ownership for public infrastructure.
- Mechanized Construction Standards:Malaysia's CIDB registration requirements filter informal lessors from federal contracts, consolidating demand toward certified rental providers.
- High-Speed Rail Spillover:The Jakarta-Bandung corridor sustains multi-year excavator and mobile crane demand through new capital city relocation and supporting infrastructure.
Market Restraints
- Diesel Emissions Compliance:Thailand's Department of Industrial Works enforces Bangkok metropolitan zone restrictions on diesel-powered fleets, raising retrofit and replacement costs for legacy equipment.
- Equipment Safety Certification:Indonesia's periodic national construction standards create regulatory friction that informal lessors cannot navigate, reducing competitive pressure in secondary markets.
- Residual Value Uncertainty:Vietnam's emerging circular economy directives on machinery lifecycle accountability compress fleet retirement timelines and distort secondary market pricing.
Strategic Opportunities
- Electric Drivetrain Conversion:Battery-powered excavators in the 1.5-20 metric ton range open urban high-rise zones where emissions restrictions exclude diesel alternatives.
- Just-in-Time Tower Crane Logistics:Urban high-rise construction cycles in Ho Chi Minh City and Bangkok create demand for rapid-deployment crane availability without capital commitment.
- Long-Term Rental Margin Pools:Twelve-month-plus tenures stabilize fleet utilization rates and deepen contractor relationships beyond project-spike volatility.
Industry Challenges
- Certified Operator Shortages:Malaysia's CIDB-mandated mechanized standards outpace vocational training pipeline output, constraining fleet deployment velocity.
- Cross-Border Fleet Redeployment Complexity:Customs clearance and equipment homologation between Thailand and Vietnam disrupt rapid response to demand spikes.
- Terrain-Specific Equipment Specialization:Mining-adjacent earthmoving in Indonesia's outer islands requires customized undercarriage configurations that standard rental pools cannot supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Construction Equipment Rental Market |
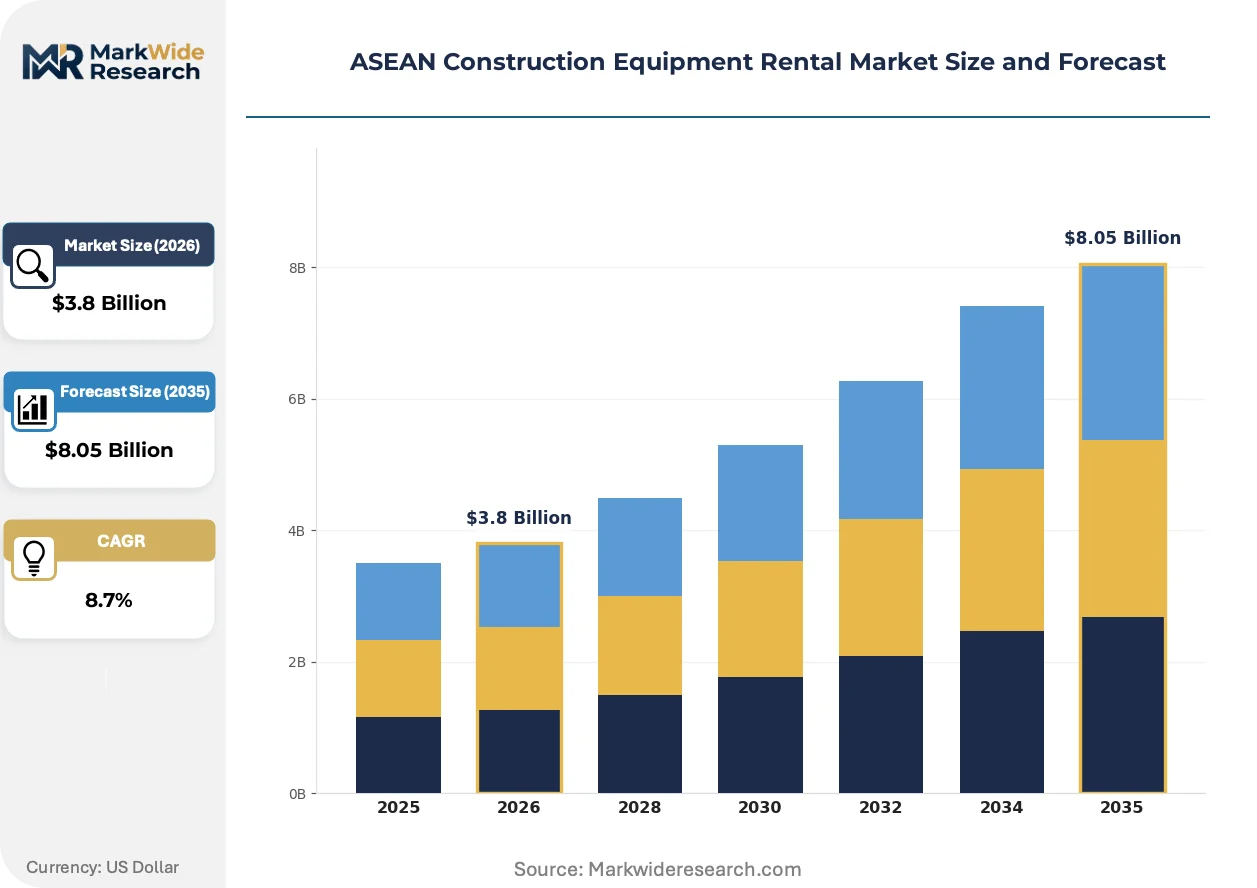
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Customer Type: Contractors, Construction Firms, Government Agencies, Individual Clients Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Transportation Services Deployment Model: On-Site, Off-Site, Hybrid, Remote Monitoring |
| Companies Covered | Rent (Thailand) Co. Ltd, Nishio Rentall, Kanamoto Co. Ltd, PT Coates Indonesia, Nikken Corporation, Aktio Co. Ltd, Tat Hong Holdings, Aver Asia, Sin Heng Heavy Machinery Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Construction Equipment Rental Market Strategic Shifts
Telematics integration and electrification are compressing the operational gap between owned and rented equipment, while regulatory emissions windows reshape fleet composition priorities.
Telematics-enabled predictive maintenance is rendering obsolete the traditional breakdown-repair model for rental fleet management. Indonesian contractors operating in Java's high-intensity corridors now expect real-time utilization dashboards as standard contract terms. This capability is compressing downtime penalties and shifting supplier selection toward data-integrated providers.
Thailand's Department of Industrial Works diesel emissions enforcement in Bangkok metropolitan zones is accelerating Euro-5 and electric equipment replacement cycles. Contractors face operating permit revocation for non-compliant machinery, forcing rental providers to front-load capital for fleet modernization. Tower crane and excavator categories face the steepest compliance cost gradients.
Project owners in Vietnam's northern industrial zones now unbundle equipment rental from operator provision, reversing the traditional bundled service model. Specialized earthmoving contractors with captive certified labor forces negotiate direct machinery-only contracts with rental providers. This pattern is most visible in Hai Phong and Quang Ninh province manufacturing corridor developments.
ASEAN Construction Equipment Rental Market Segmentation
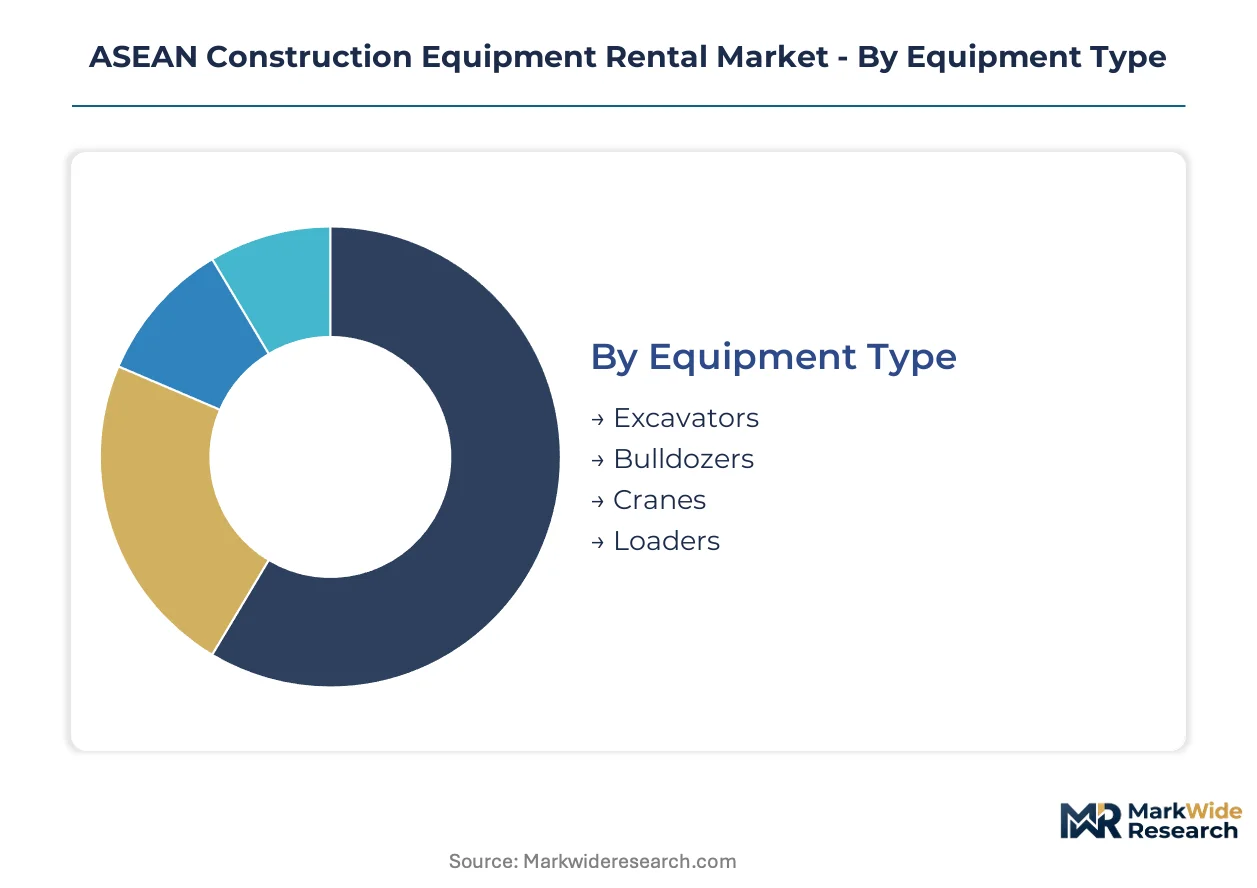
Segmentation in ASEAN construction equipment rental reveals how capital-light procurement strategies diverge across project scales and regulatory environments. Equipment type and service duration decisions directly reflect contractor responses to Indonesia's build-transfer-operate mandates and Malaysia's CIDB certification requirements.
Equipment Type:
Equipment type segmentation captures the functional specialization demanded by ASEAN's diverse topography and project complexity tiers.
- Excavators:Hydraulic and crawler configurations dominate trenching, demolition, and material handling across Indonesia's Java corridor and Vietnam's northern industrial zones. Jakarta-Bandung high-speed rail spillover and new capital city relocation sustain multi-year demand for 20-80 metric ton units with terrain-adaptive undercarriages.
- Bulldozers:Tracked dozers with ripper attachments serve mining-adjacent earthmoving in Indonesia's outer islands where conventional rental pools avoid terrain constraints. PT Coates Indonesia specializes in customized undercarriage configurations for these high-friction deployments.
- Cranes:Mobile and tower varieties anchor urban high-rise construction cycles in Bangkok and Ho Chi Minh City demanding just-in-time delivery without capital commitment.
- Loaders:Wheel and skid-steer formats support material handling in Malaysia's mechanized construction standards push under CIDB registration requirements.
Excavators command the established base. The steepest expansion runs through cranes serving vertical urbanization corridors.
Customer Type:
Customer segmentation reflects the capital constraint gradient from federally funded infrastructure to informal secondary markets.
- Contractors:Infrastructure contractors across Indonesia, Thailand, and Vietnam are expanding fleet outsourcing as government-backed build-transfer-operate frameworks tighten capital expenditure controls on public projects. Long-term rental arrangements among this group capture the deepest margin pools as fleet utilization rates stabilize beyond twelve-month tenures.
- Construction Firms:Private developers in Vietnam's Hai Phong and Quang Ninh manufacturing corridors increasingly unbundle equipment rental from operator provision, negotiating direct machinery-only contracts with specialized earthmoving contractors.
- Government Agencies:Indonesia's Ministry of Public Works and Housing mandates periodic equipment safety certification under national construction standards, filtering informal lessors from federally funded contracts.
- Individual Clients:Small-scale operators in secondary ASEAN markets face regulatory friction from emissions compliance and safety certification requirements that consolidated rental providers navigate more efficiently.
Contractors represent the revenue anchor. Construction firms are gaining share fastest through unbundled procurement models.
Service Type:
Service type segmentation tracks the shift from asset ownership to operational flexibility across project volatility profiles.
- Short-Term Rental:Spike-driven infrastructure stimulus cycles generate higher per-day yields but erratic scheduling, concentrated in Thailand's rapid-response urban construction and Vietnam's manufacturing corridor expansions.
- Long-Term Rental:Twelve-month-plus tenures stabilize fleet utilization rates and deepen contractor relationships beyond project-spike volatility, particularly in Indonesia's Java corridor sustained by multi-year capital city relocation infrastructure.
- Maintenance Services:Telematics-enabled predictive maintenance is rendering obsolete the traditional breakdown-repair model, with Indonesian contractors now expecting real-time utilization dashboards as standard contract terms.
- Transportation Services:Cross-border fleet redeployment between Thailand and Vietnam project clusters requires logistics integration that Kanamoto Co. Ltd leverages through its Japan-ASEAN network.
Long-term rental anchors provider profitability. Short-term rental is expanding most quickly through stimulus-responsive procurement.
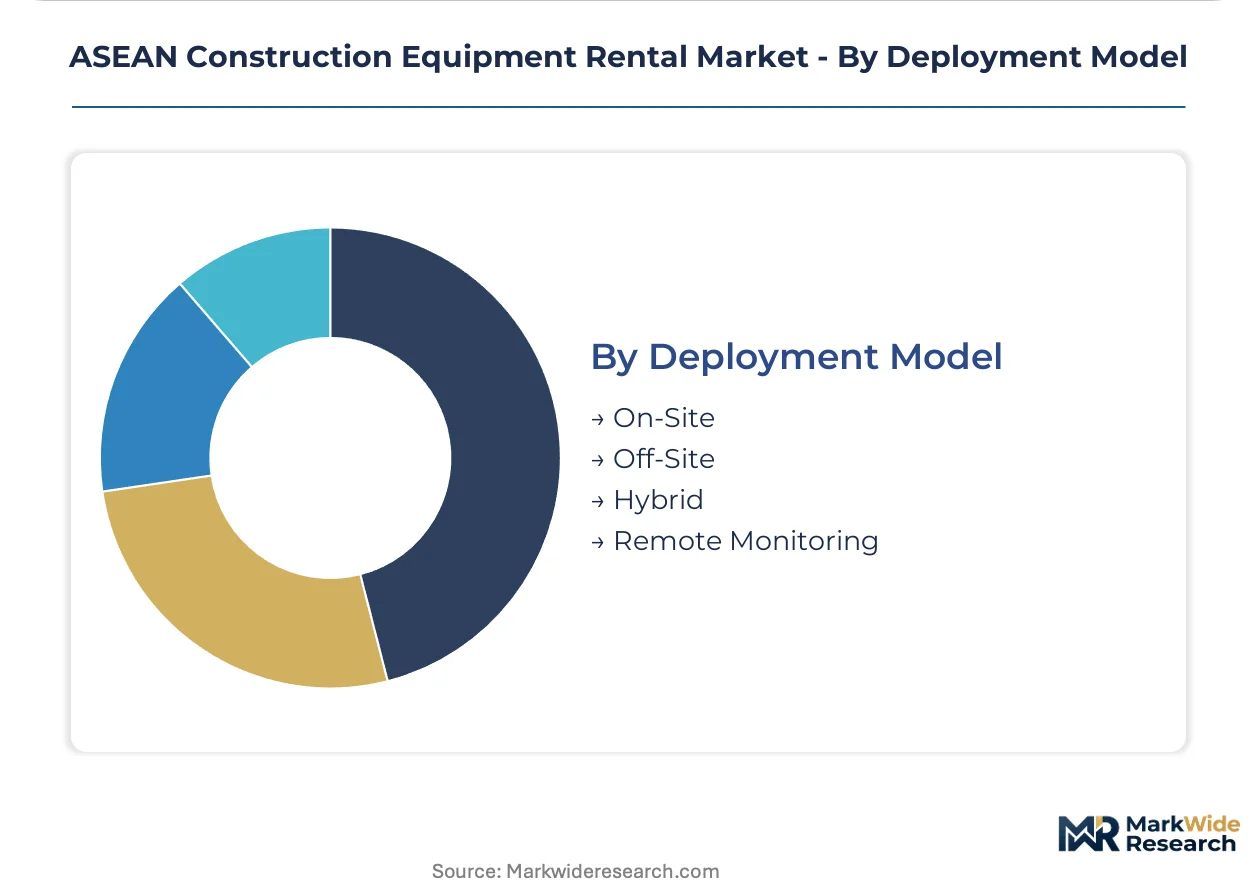
Deployment Model:
Deployment model segmentation captures the operational integration spectrum from physical presence to data-driven remote management.
- On-Site:Traditional equipment positioning dominates mining-adjacent construction in Indonesia's outer islands where terrain constraints demand immediate technical response and specialized operator presence.
- Off-Site:Centralized fleet staging with rapid mobilization protocols serves Bangkok metropolitan zone contractors facing Thailand's Department of Industrial Works diesel emissions enforcement and operating permit revocation risks.
- Hybrid:Combined physical and digital coordination models support tower crane logistics in urban high-rise zones where Nishio Rentall anchors premium availability through just-in-time delivery systems.
- Remote Monitoring:Telematics integration is compressing the operational gap between owned and rented equipment, with real-time utilization dashboards now standard in Indonesian high-intensity corridors.
On-site deployment holds the established base. Remote monitoring is climbing the fastest as telematics integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Public Works and Housing anchors the dominant geography through build-transfer-operate mandates that privilege rental procurement over capital ownership across Java corridor infrastructure.
Indonesia
Jakarta-Bandung high-speed rail spillover and new capital city relocation sustain multi-year excavator and mobile crane demand. The Ministry of Public Works and Housing mandates periodic equipment safety certification under national construction standards that filter informal lessors. Java corridor contractors concentrate fleet outsourcing in Surabaya and Bandung satellite zones where government-backed projects tighten capital expenditure controls.
Thailand
Bangkok metropolitan zone emissions enforcement accelerates Euro-5 and electric equipment replacement cycles among rental providers. The Department of Industrial Works enforces operating permit revocation for non-compliant diesel-powered machinery. Contractors in Greater Bangkok and Eastern Economic Corridor manufacturing zones face compressed capital windows through build-transfer-operate frameworks on public infrastructure.
Vietnam
Hai Phong and Quang Ninh province manufacturing corridors drive unbundled equipment rental procurement separated from operator provision. Emerging circular economy directives on machinery lifecycle accountability reshape residual value calculations and fleet retirement timelines. Northern industrial zone developers negotiate direct machinery-only contracts with specialized earthmoving contractors.
Malaysia
Construction Industry Development Board mechanized construction standards accelerate replacement of manual labor with rented excavators and mobile cranes. CIDB registration requirements restrict project participation to contractors utilizing certified machinery. Kuala Lumpur high-rise zones and Iskandar Malaysia development corridors consolidate demand toward certified rental providers filtered from federal contracts.
Singapore
Urban densification constraints and strict emissions standards concentrate demand for electric drivetrain equipment in compact site configurations. Build-to-order public housing cycles generate predictable long-term rental tenures that stabilize fleet utilization rates. Marina Bay and Jurong Lake District developments anchor premium crane availability through just-in-time delivery requirements.
ASEAN Construction Equipment Rental Market Competitive Environment
Japan-ASEAN logistics specialists and Indonesia-focused terrain specialists split the market between cross-border fleet mobility and localized mining-adjacent capabilities. The competitive structure consolidates around three strategic archetypes: integrated logistics networks enabling rapid redeployment, premium urban crane availability providers, and specialized earthmoving operators navigating terrain constraints. Dominant competitive moves include cross-border fleet redeployment optimization and telematics-enabled predictive maintenance integration.
Within the Japan-ASEAN logistics tier, Kanamoto Co. Ltd and Nishio Rentall exemplify network-anchored positioning. Kanamoto leverages its Japan-ASEAN logistics infrastructure to sustain rapid fleet redeployment between Thailand and Vietnam project clusters. Nishio Rentall occupies a position anchoring premium crane availability in urban high-rise zones where tower erection cycles demand just-in-time delivery. PT Coates Indonesia represents the terrain-specialist archetype, dominating Indonesian mining-adjacent construction with capabilities that navigate outer island constraints conventional lessors avoid.
| Leading Market Players |
|---|
| Rent (Thailand) Co. Ltd |
| Nishio Rentall |
| Kanamoto Co. Ltd |
| PT Coates Indonesia |
| Nikken Corporation |
| Aktio Co. Ltd |
| Tat Hong Holdings |
| Aver Asia |
| Sin Heng Heavy Machinery Limited |
| Others |
Value Chain & Pricing Dynamics
Japanese OEM manufacturing clusters in Aichi and Osaka prefectures anchor upstream equipment supply, concentrating margin capture with integrated lessors who control fleet procurement channels across Southeast Asian deployment zones. Rental providers with direct manufacturer relationships extract pricing power that fragmented secondary lessors cannot match, particularly for specialized earthmoving configurations demanded in Indonesia's outer islands.
Pricing Analysis
Equipment rental rates diverge sharply between Java corridor premium zones and secondary Indonesian markets, with Bangkok metropolitan emissions-compliant fleets commanding 15-20% premiums over legacy diesel units. Three-tier pricing structure across premium certified, standard compliant, and economy informal tiers reflects CIDB registration requirements in Malaysia and Indonesia's safety certification mandates. Pricing pressure stems from Euro-5 retrofit costs and electric drivetrain capital requirements, with small-scale contractors exhibiting highest price sensitivity and government-backed infrastructure contractors demonstrating lowest.
Supply Chain Analysis
Extended payment terms from Japanese and South Korean equipment manufacturers enable fleet expansion without immediate capital outlay, though currency exposure concentrates with ASEAN-based lessors. Manufacturing draws from Japan, South Korea, and China for hydraulic systems, engine blocks, and telematics modules. Single-source vulnerability runs through specialized undercarriage components for mining-adjacent deployments. Distribution runs through regional hub-and-spoke networks with centralized staging in Surabaya, Bangkok, and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
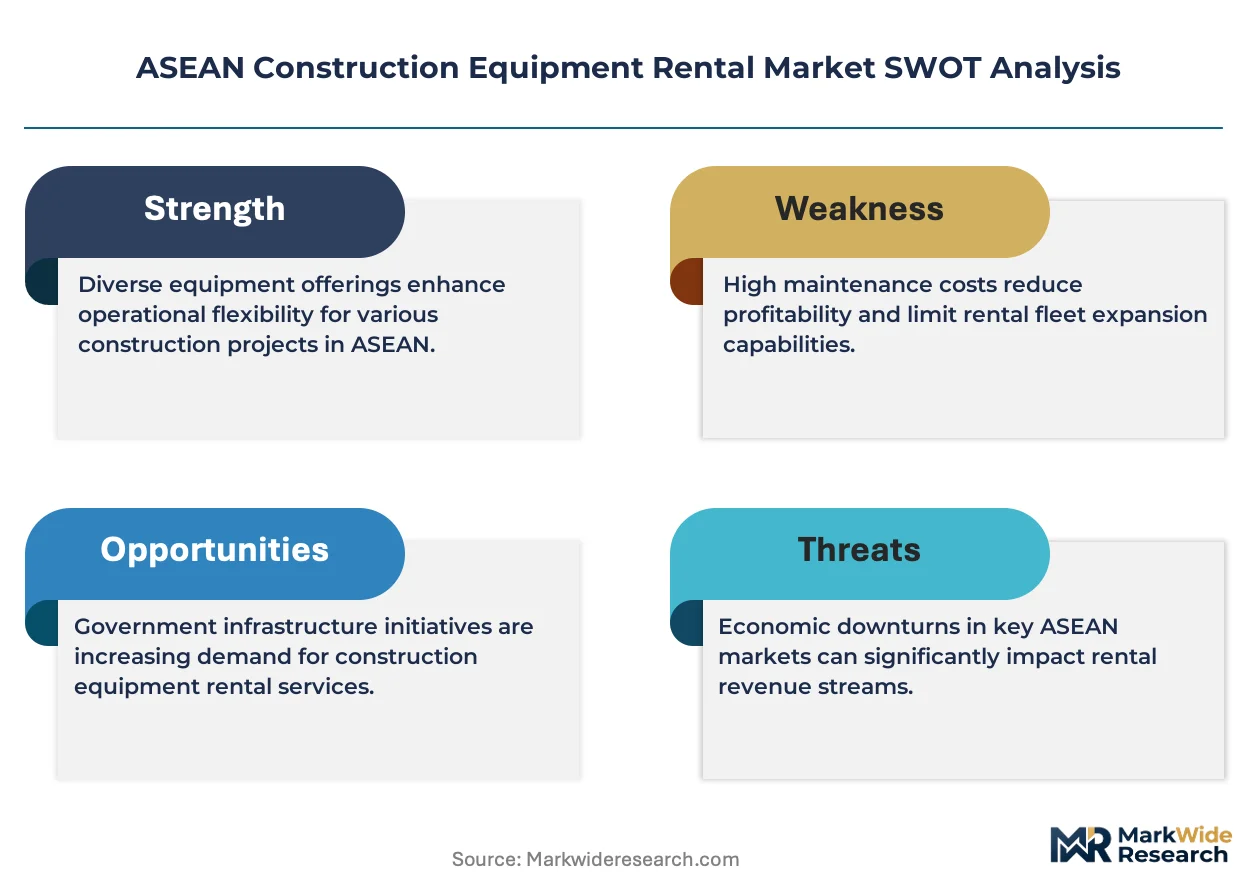
Electric drivetrain conversion and telematics integration are disrupting traditional rental economics, with Thailand's Department of Industrial Works emissions enforcement creating regulatory inflection that separates compliant from legacy fleet operators.
For Market Incumbents: Insulate core profitability by securing exclusive distribution agreements with Japanese OEMs for electric excavator ranges, while embedding predictive maintenance capabilities to lock in twelve-month-plus contractor relationships against emerging data-integrated competitors. For New Entrants and Emerging Players: Pursue unpenetrated terrain-specialist niches in Indonesia's outer island mining corridors where customized undercarriage configurations command premium rates, leveraging direct machinery-only contracts with specialized earthmoving contractors as the primary go-to-market pathway. For Investors and Strategic Acquirers: Capital is best deployed toward integrated logistics networks with Japan-ASEAN fleet mobility capabilities and telematics-enabled fleet management platforms, as long-term viability across the projection horizon hinges on cross-border redeployment velocity and data-driven utilization optimization. Monitor Vietnam's circular economy directive implementation as the critical inflection signal for residual value compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Bangkok emissions enforcement excludes non-compliant diesel alternatives from metropolitan zones. |
| Telematics Platform Integration | Indonesian contractors now mandate real-time utilization dashboards as standard contract terms. |
| Cross-Border Logistics Network Expansion | Thailand-Vietnam customs clearance optimization enables rapid response to demand spikes. |
| Long-Term Rental Contract Structuring | Twelve-month-plus tenures stabilize fleet utilization rates beyond project-spike volatility. |
| Specialized Terrain Equipment Development | PT Coates Indonesia's outer island capabilities demonstrate defensible niche positioning. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with fleet operations managers, procurement directors at infrastructure contractors, CIDB certification officers, and telematics platform engineers; and secondary validation through customs import records, construction project databases, equipment manufacturer shipment disclosures, and regulatory filing repositories. Bottom-up equipment deployment estimates triangulated against top-down infrastructure spending allocations.
Forecast inputs incorporated equipment type segmentation, service duration tiers, deployment model adoption patterns, and customer type procurement behaviors across the projection horizon. CAGRs derived from modeled fleet expansion trajectories, replacement cycle compression, and regulatory compliance cost pass-through assumptions. Specific inputs included diesel-to-electric conversion timelines, cross-border logistics friction coefficients, and terrain-specialist equipment penetration rates.
Sensitivities concentrate around emissions enforcement stringency in Thailand, circular economy directive finalization in Vietnam, and Japanese OEM electric equipment availability. Forecasts reflect documented assumptions regarding infrastructure stimulus continuity and contractor capital constraint persistence. Macroeconomic contraction, regulatory acceleration, or battery technology cost deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Global Excavators Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Construction Pump Market
Construction Equipment
Automatic Clay Brick Making Machine Market