
 Industrial Racking Systems Market | 2026-2036
Industrial Racking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Racking Systems Market Intelligence
The market's end-use profile is pivoting from traditional retail warehousing toward high-throughput e-commerce fulfillment centers. SSI SCHAEFER specializes in complex, automated systems for these advanced logistics facilities. In contrast, Frazier Industrial Company leverages its focus on structural steel pallet racks for heavy-duty industrial applications. Interlake Mecalux competes by offering a broad portfolio catering to both standard and custom requirements across various end-user segments.
Industrial racking systems are engineered steel structures designed for the high-density storage of palletized or bulk materials in warehouses and distribution centers. Key specifications include load capacity per beam level, seismic zone compliance, and the use of roll-formed or structural steel components. Selective pallet racks remain the dominant product type due to their versatility, but high-density drive-in racks are gaining share in cold storage applications. Steel is the primary material, though specialized flow racks often incorporate plastic and aluminum components for roller beds.
Product design and installation are governed by standards from organizations like the US Rack Manufacturers Institute (RMI) and adherence to local seismic codes. In Europe, CE marking is mandatory, signifying compliance with health and safety standards for systems sold within the European Economic Area. Workplace safety regulations from bodies like the US Occupational Safety and Health Administration (OSHA) also dictate rack inspection and maintenance protocols. Vendor selection increasingly depends on the ability to provide engineering support for seismic retrofitting and automation integration.
Market Dynamics
The industrial racking systems market is being reshaped by the dual pressures of automation integration and sustainability mandates. Demand for systems that support high-throughput robotics is converging with regulatory requirements like the EU's Corporate Sustainability Reporting Directive, forcing a fundamental re-evaluation of rack design, material, and lifecycle management.
Growth Catalysts
- E-commerce Logistics Expansion:The build-out of fulfillment and distribution centers, particularly in manufacturing-adjacent logistics hubs across Mexico and Poland, creates a continuous stream of large-scale greenfield projects requiring extensive racking installations.
- Sustainability Mandates:Regulations such as the EU's CSRD are influencing material specification, creating demand for racking systems made from recycled steel or designed for disassembly and reuse, which vendors can market as a compliance advantage.
- Automation Integration:The adoption of automated guided vehicles (AGVs) and robotic shuttles in warehouses necessitates higher-precision, more durable racking systems, driving upgrades from conventional selective racks to specialized, automation-ready designs.
Market Restraints
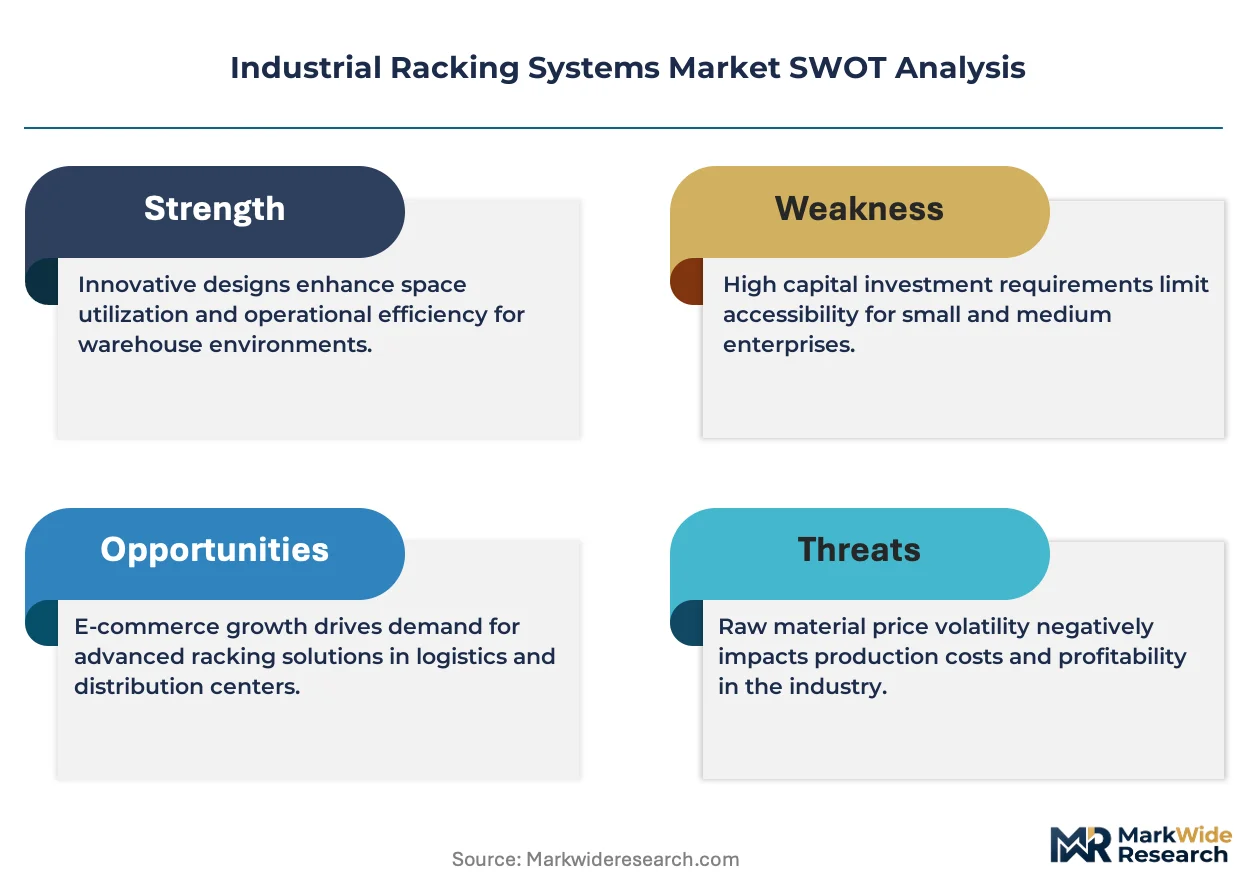
- Input Material Volatility:The market's heavy reliance on steel exposes it to significant price fluctuations and supply chain disruptions, complicating project bidding and eroding profit margins for manufacturers and installers.
- Seismic Compliance Complexity:Adherence to a patchwork of stringent and varied seismic design codes, such as those from the Rack Manufacturers Institute in the US and specific national standards in other regions, increases engineering costs and extends project timelines. *High Capital Expenditure: The significant upfront investment required for high-density, automated systems like AS/RS-integrated racking acts as a barrier for many small to medium-sized enterprises, limiting adoption to larger, well-capitalized firms.
Strategic Opportunities
- Micro-Fulfillment Systems:The growth of quick commerce creates an opportunity for compact, modular racking systems designed for small-footprint urban warehouses, a segment with distinct requirements from large-scale distribution centers.
- Integrated Sensor Technology:Incorporating IoT sensors into racking structures to monitor load status, detect impacts, and provide real-time structural health data presents a new value-added service for vendors, shifting focus from hardware to data solutions.
- Emerging Logistics Hubs:Expanding manufacturing and trade activity in Southeast Asian nations creates greenfield opportunities for racking installations, representing a new growth frontier for vendors seeking geographic diversification.
Industry Challenges
- Skilled Labor Scarcity:A shortage of certified welders, qualified installers, and structural engineers with expertise in seismic-compliant and automation-integrated racking systems creates installation bottlenecks and drives up labor costs.
- Legacy System Integration:Integrating modern, automated racking systems with older warehouse management software and existing facility infrastructure poses a significant technical challenge, often requiring costly and disruptive system-wide overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Racking Systems Market |
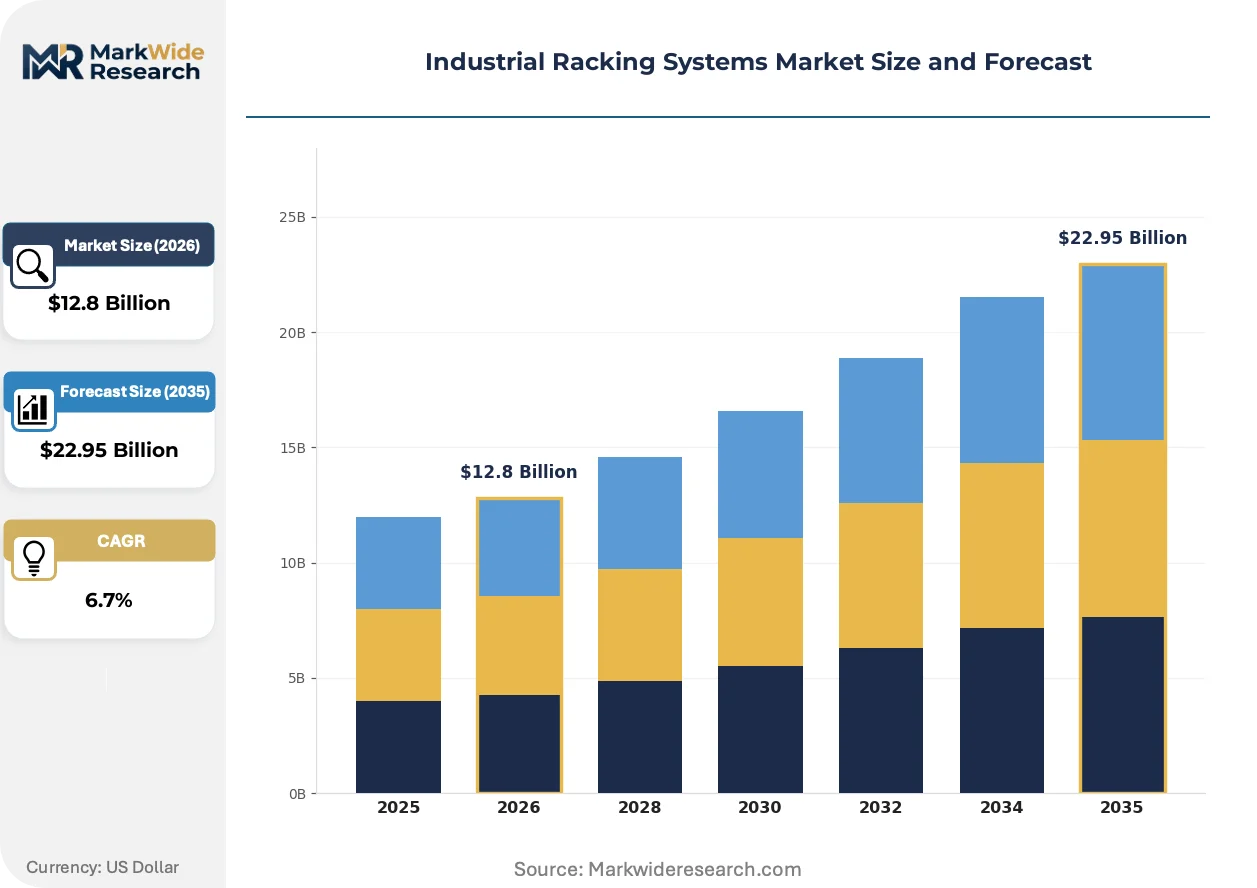
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallet Racks, Cantilever Racks, Drive-in Racks, Mezzanine Systems, Flow Racks Material: Steel, Plastic, Aluminum, Wire Mesh, Composite Application: Warehousing, Distribution Centers, Cold Storage, Manufacturing Facilities, E-commerce Fulfillment End User: Third-party Logistics Providers, Retail Chains, Food Processing Units, Automotive Suppliers, Electronics Manufacturers |
| Companies Covered | SSI SCHAEFER, UNARCO Material Handling, Inc., Steel King Industries, Inc., Advance Storage Products, Frazier Industrial Company, Ridg-U-Rak, Inc., Hannibal Industries, Speedrack Products Group, Ltd., Interlake Mecalux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Racking Systems Market Strategic Shifts & Innovations
System design is evolving from a focus on static storage density to an emphasis on dynamic product flow and data integration. Racking is becoming an active component within the broader automated logistics network, valued for its ability to enable speed and accuracy rather than just for its holding capacity.
Automated Storage and Retrieval Systems (AS/RS) provide high-density, robot-managed storage and picking. Adoption is accelerating within large-scale e-commerce and cold storage operations where throughput and space efficiency are critical. As a result, AS/RS-compatible racking is consolidating the market around vendors capable of delivering highly engineered, integrated systems, reducing the addressable market for suppliers of simple, standalone pallet racks.
The US Occupational Safety and Health Administration (OSHA) continues to emphasize standards for rack inspection, maintenance, and load capacity placarding. This regulatory focus compels warehouse operators to treat rack safety as a continuous operational priority, not a one-time installation concern. The distribution and manufacturing segments are most affected, responding by contracting for regular third-party rack inspections and prioritizing damage-resistant column designs in new purchases.
A transition from capital expenditure purchases toward more flexible operational models is becoming more apparent. This disrupts the traditional one-time sale by favoring vendors that can provide comprehensive leasing, maintenance, and reconfiguration services as part of a longer-term agreement. This trend is most pronounced within the third-party logistics (3PL) sector, especially in Europe, where adaptability to changing client needs is a core competitive advantage.
Industrial Racking Systems Market Segmentation
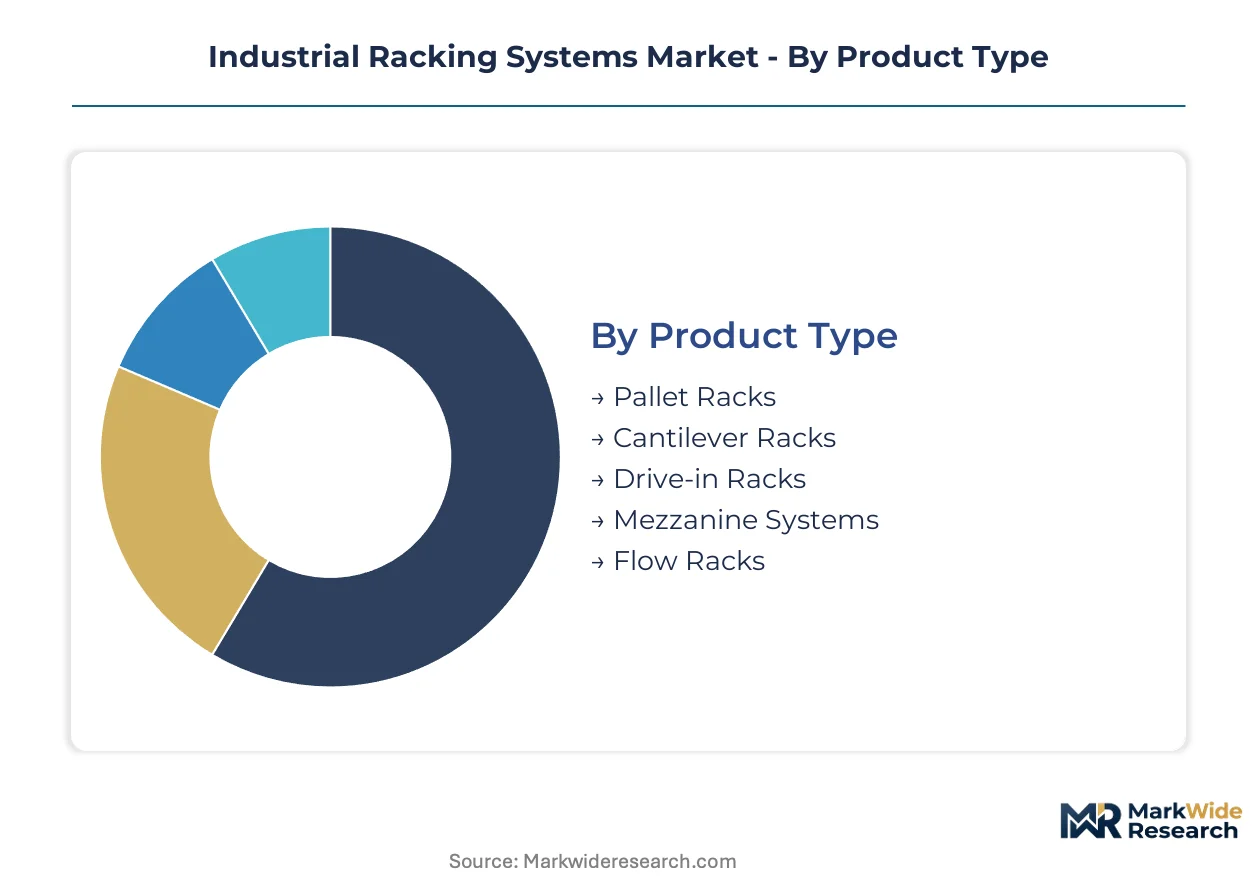
Segmentation within the industrial racking systems market reveals how diverse operational demands shape product design, material selection, and end-user adoption. Understanding these segments helps manufacturers tailor offerings to specific industry requirements, from high-density storage to automated retrieval systems.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, versatile solutions to custom-engineered systems for specialized storage requirements.
- Pallet Racks:These systems provide direct access to every pallet, utilizing roll-formed or structural steel components for durability. Demand concentrates in general warehousing and distribution centers, driven by the need for flexible inventory management.
- Drive-in Racks:Designed for high-density storage, these systems allow forklifts to drive into the rack structure, storing pallets several deep. Adoption is accelerating in cold storage applications across Europe, where maximizing cubic space for temperature-sensitive goods is critical.
- Cantilever Racks:Featuring arms extending from a central column, cantilever racks store long, bulky items like lumber or piping. Manufacturing facilities in Mexico frequently use these for raw material storage.
- Mezzanine Systems:These create elevated platforms within a warehouse, effectively doubling usable floor space for storage or office areas. E-commerce fulfillment centers employ mezzanines for separating picking and packing operations.
- Flow Racks:Incorporating inclined rollers or wheels, flow racks facilitate first-in, first-out (FIFO) inventory management by allowing goods to move by gravity. Food processing units utilize these for efficient product rotation.
Most installed capacity flows through Pallet Racks. Expansion is steepest in Drive-in Racks.
Material:
Material selection for industrial racking systems is driven by a balance of cost, load-bearing capacity, and environmental resistance.
- Steel:This material forms the backbone of most industrial racking systems due to its high strength-to-weight ratio and durability. New installations in Poland emphasize recycled steel content to meet EU CSRD mandates.
- Aluminum:Lightweight and corrosion-resistant, aluminum components are frequently integrated into specialized flow racks and automated systems for roller beds. Electronics manufacturers use aluminum for precision and cleanliness.
- Plastic:Used primarily for smaller components like roller wheels, trays, or protective elements within flow racks, plastic offers chemical resistance and reduced noise. Food processing units integrate plastic for hygiene considerations.
- Wire Mesh:Employed for decking, wire mesh provides improved airflow, sprinkler penetration, and visibility compared to solid shelves. Warehousing operations in the US prefer wire mesh for fire safety compliance.
- Composite:Emerging composite materials offer a balance of strength and reduced weight, finding niche applications in specialized environments. These materials are explored for their potential in seismic-resistant designs.
Steel remains the foundational material for most racking systems, while Aluminum provides lightweight solutions for dynamic applications.
Application:
The application landscape differentiates racking needs based on operational throughput, environmental conditions, and the specific nature of stored goods.
- E-commerce Fulfillment:These applications demand high-throughput, automation-compatible racking systems to support rapid order processing and shipping. Large-scale distribution centers in the US are investing heavily in these advanced setups.
- Cold Storage:Racking for cold storage requires specialized materials and designs to withstand sub-zero temperatures and prevent ice buildup. Food processing units in Europe are upgrading to high-density drive-in racks for these conditions.
- Warehousing:General warehousing applications encompass a broad range of storage needs, typically using selective pallet racks for versatile inventory access. Third-party logistics providers operate extensive warehousing facilities.
- Distribution Centers:These facilities focus on efficient product movement and cross-docking, often integrating various racking types to optimize flow. Retail chains utilize distribution centers to supply multiple store locations.
- Manufacturing Facilities:Racking systems in manufacturing support raw material storage, work-in-progress, and finished goods, often requiring heavy-duty or specialized cantilever racks. Automotive suppliers rely on robust systems for component storage.
Operations demanding high-speed order fulfillment increasingly rely on systems for E-commerce Fulfillment, whereas Cold Storage requires specialized designs for extreme temperatures.
End User:
End-user requirements for industrial racking vary significantly, reflecting diverse business models, inventory profiles, and operational scales.
- Third-party Logistics Providers:3PLs require highly adaptable and scalable racking solutions to manage diverse client inventories and fluctuating demand. European 3PLs frequently opt for leasing and maintenance services.
- Automotive Suppliers:These entities demand robust, high-capacity racking systems for storing heavy parts, components, and finished goods. Manufacturing hubs in Mexico see significant demand from automotive suppliers.
- Retail Chains:Retailers use racking in both their distribution centers and back-of-store storage areas, emphasizing space utilization and inventory accessibility. Large retail chains prioritize efficient replenishment systems.
- Food Processing Units:These end-users require racking systems that meet stringent hygiene standards and often operate in refrigerated or freezer environments. Stainless steel or plastic components are preferred for cleanliness.
- Electronics Manufacturers:Precision and protection from electrostatic discharge are key considerations for racking in electronics manufacturing and storage. Specialized flow racks and anti-static materials are common.
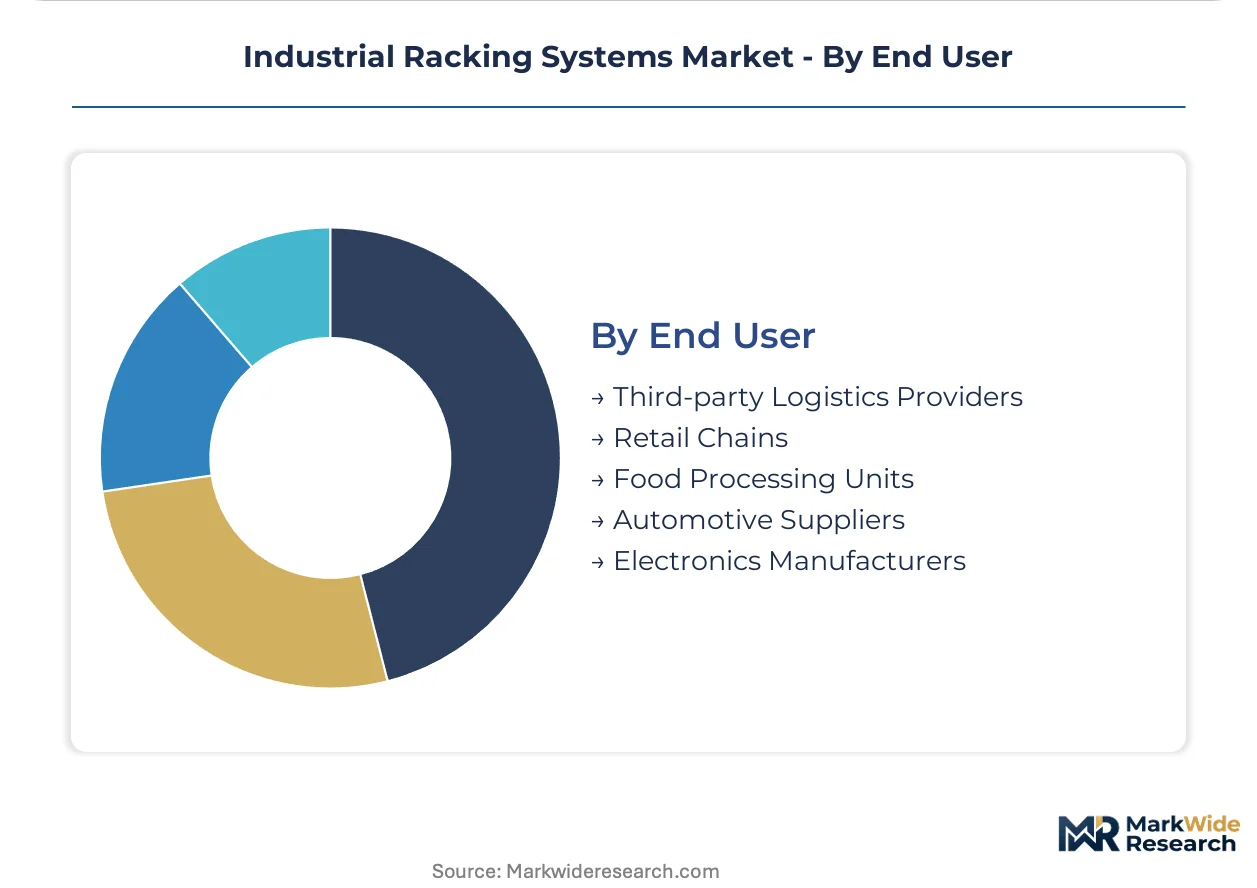
The need for flexible, scalable solutions defines demand from Third-party Logistics Providers, while Automotive Suppliers require robust systems for heavy components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence is influencing industrial racking system installations, with production shifting to optimize compliance costs and supply chain efficiency. The EU's Corporate Sustainability Reporting Directive (CSRD) is particularly impacting material selection, prompting investment in compliant systems within Europe. This also drives expansion in adjacent logistics hubs.
Mexico
Manufacturing facilities and expanding logistics hubs drive demand for industrial racking systems across Mexico. Adherence to local seismic codes dictates structural design, especially for heavy-duty applications. The Bajío Region, a prominent automotive manufacturing cluster, sees continuous investment in robust storage solutions for components and finished goods.
Poland
Poland experiences robust demand for racking systems, particularly from expanding e-commerce fulfillment centers. The EU's CSRD mandates influence material specification, with new installations emphasizing recycled steel content for sustainability compliance. Logistics hubs around Warsaw and Poznan are greenfield sites for extensive, modern racking installations.
United States
High-throughput e-commerce fulfillment and general warehousing needs propel racking demand across the United States. OSHA emphasizes continuous rack inspection and maintenance protocols, requiring operators to prioritize safety. Large-scale distribution centers, particularly in states like California, invest in seismic-compliant and fire-safe wire mesh decking.
Germany
Germany's advanced manufacturing sector and sophisticated logistics networks require high-precision, automation-ready racking systems. CE marking is mandatory for systems sold within the European Economic Area, ensuring health and safety compliance. Automotive suppliers and cold storage facilities in regions like Bavaria are upgrading to specialized, integrated storage solutions.
Vietnam
Expanding manufacturing and trade activity in Vietnam creates greenfield opportunities for industrial racking installations. Local building codes and international standards guide structural integrity and safety requirements for new facilities. Industrial parks near Ho Chi Minh City and Hanoi are seeing significant investments in warehousing infrastructure to support export-oriented production.
Industrial Racking Systems Market Key Industry Players
Automation integration and geographic expansion dominate the current competitive landscape for industrial racking systems. The market features a tiered structure, with global players offering complex, automated solutions alongside regional specialists. Competitive positioning is driven by the ability to provide engineering support for seismic retrofitting and comprehensive lifecycle services. Strategic partnerships and portfolio diversification are key competitive moves for vendors.
Specialists in integrated, automation-ready solutions include SSI SCHAEFER, a German company known for complex logistics systems that support high-throughput e-commerce fulfillment. Frazier Industrial Company, a US-based firm, exemplifies a focus on structural steel pallet racks for heavy-duty industrial applications, catering to robust storage needs in manufacturing. Interlake Mecalux, with its broad portfolio, occupies a position serving both standard and custom requirements across diverse end-user segments, from general warehousing to distribution centers. These firms anchor the market by addressing varied operational demands, showcasing distinct competitive strategies.
| Leading Market Players |
|---|
| SSI SCHAEFER |
| UNARCO Material Handling, Inc. |
| Steel King Industries, Inc. |
| Advance Storage Products |
| Frazier Industrial Company |
| Ridg-U-Rak, Inc. |
| Hannibal Industries |
| Speedrack Products Group, Ltd. |
| Interlake Mecalux |
| Others |
Cost & Logistics Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) gates qualified supply for new installations, allowing premium-tier pricing for compliant systems. This mandate influences material selection, creating demand for racking systems made from recycled steel or designed for disassembly and reuse.
Pricing Analysis
Distributor margins and project-based pricing dominate for large, custom-engineered racking systems. Standard components often follow a per-unit transactional model. Price differentiation stems from customization level, adherence to specific certifications like CE marking, and the provision of comprehensive after-sales service. Pricing pressure arises from input material volatility, particularly for steel. Small to medium-sized enterprises (SMEs) exhibit higher price sensitivity due to significant upfront capital expenditure, unlike large e-commerce firms investing in integrated automated solutions.
Supply Chain Analysis
Skilled labor availability in key manufacturing geographies, such as Poland and Mexico, impacts production capacity and costs. The supply of industrial racking systems concentrates in regions with robust steel production and advanced manufacturing capabilities, including Germany and the United States. The market primarily depends on steel as the foundational material, alongside aluminum and plastic for specialized components. Input material volatility, especially for steel, represents a significant supply chain risk. Distribution runs through direct sales for large-scale projects and established dealer networks for standard rack components, with leasing models gaining traction among third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, driven by regulatory divergence like the EU CSRD and varying labor costs between regions such as Europe and Southeast Asia.
For Market Incumbents:Deploy automation integration expertise to defend market share against specialized technology providers. Invest in research and development for AS/RS-compatible racking systems to meet the evolving demands of e-commerce fulfillment centers. Expand comprehensive lifecycle services, including leasing, maintenance, and retrofitting, to solidify relationships with third-party logistics providers. Prioritize engineering support for seismic retrofitting and compliance with standards from organizations like the US Rack Manufacturers Institute.
For New Entrants and Emerging Players:The EU's Corporate Sustainability Reporting Directive (CSRD) in Europe opens a window for specialized providers of sustainable racking solutions. Target the micro-fulfillment segment with compact, modular systems designed for urban warehouses. Integrate sensor technology into racking structures to offer real-time structural health data as a value-added service. Focus on emerging logistics hubs in Southeast Asian nations, where greenfield opportunities for warehousing infrastructure are abundant.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional specialists focused on traditional pallet rack manufacturing. The long-term viability of the market is strong, propelled by e-commerce expansion and automation adoption. Acquire firms with proven automation integration capabilities or specialized expertise in materials like seismic-resistant composites. The signal to watch is the increasing consolidation of smaller, regional players by larger vendors offering integrated automated warehouse solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Build new manufacturing facilities in emerging logistics hubs like Vietnam to support export-oriented production. |
| Product Development | Introduce AS/RS-compatible racking systems to capture growing demand from e-commerce fulfillment centers. |
| Service Diversification | Offer comprehensive leasing and maintenance services to third-party logistics providers in Europe. |
| Technology Integration | Embed IoT sensors into racking structures to provide real-time structural health data to warehouse operators. |
| Material Innovation | Develop systems using recycled steel content to meet EU CSRD sustainability mandates. |
Research Approach
Bottom-up e-commerce fulfillment modeling reconciled against top-down steel manufacturers tracking forms the analytical core of this study. The methodology involved extensive primary interviews with warehouse operators, logistics managers, procurement specialists, and structural engineers. Secondary validation drew from industry association reports, RMI standards, OSHA regulations, and EU CSRD guidelines, ensuring robust data triangulation.
The input-output matrix framework underpins the forecast, modeling market dynamics across the analysis window. Segmentation dimensions included product type, material, application, end-user, and regional economic growth patterns. Compound Annual Growth Rates were derived from historical trends and projected market drivers, utilizing forecast inputs such as e-commerce penetration rates and industrial construction spending.
Revisions become necessary when significant shifts in global trade policies, unforeseen supply chain disruptions, or rapid technological advancements materialize. Forecasts reflect assumptions regarding steel price stability and the continued enforcement of regulatory frameworks like seismic codes. Practitioners should monitor global economic indicators and regulatory updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Vertical Platform Lift Market