
 Global Crane and Hoist Market | 2026-2036
Global Crane and Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crane and Hoist Market Intelligence
European heavy equipment manufacturing capacity is consolidating around producers with advanced automation and electric powertrain capabilities. Liebherr leverages its extensive product portfolio to serve diverse end-markets from construction to shipbuilding. Konecranes specializes in industrial overhead cranes and port solutions, while Zoomlion Heavy Industry Science & Technology Co., Ltd. leads in high-capacity tower crane segments sold into developing economies.
Cranes and hoists are mechanical lifting devices engineered to move materials vertically and horizontally, utilizing components like drums, wire ropes, and sheaves. Their primary industrial function is to handle heavy loads in environments such as manufacturing plants, construction sites, and ports, where manual labor is impractical. Overhead cranes, powered by electric motors, represent a mature and high-volume category essential for indoor manufacturing and warehousing applications. Conversely, high-capacity tower cranes, critical for large-scale construction, command higher margins due to specialized engineering and installation requirements.
Operator safety and equipment integrity are governed by stringent regulations, including OSHA standards in the United States and mandatory CE marking in Europe. In China, compliance with specific GB standards for lifting machinery is essential for market access, influencing design and testing protocols. Future competitive advantage depends on integrating digital features like remote monitoring and predictive maintenance while adhering to evolving emissions and safety rules.
Market Dynamics
The convergence of stringent safety regulations and the demand for higher productivity in complex construction environments is the central force shaping the crane and hoist market. This pressure drives the integration of automation, telematics, and advanced engineering solutions.
Growth Catalysts
- Urban Infrastructure Investment:Large-scale public works projects in India and Southeast Asian nations, focused on transportation and urban development, require a significant volume of high-capacity mobile and tower cranes.
- Renewable Energy Expansion:The construction of onshore and offshore wind farms creates specific demand for specialized high-lift capacity crawler cranes and mobile cranes needed for turbine installation and maintenance.
- E-commerce Warehouse Automation:Proliferation of large-scale distribution and fulfillment centers drives consistent demand for indoor overhead cranes, workstation cranes, and electric hoists to support automated material handling systems.
Market Restraints
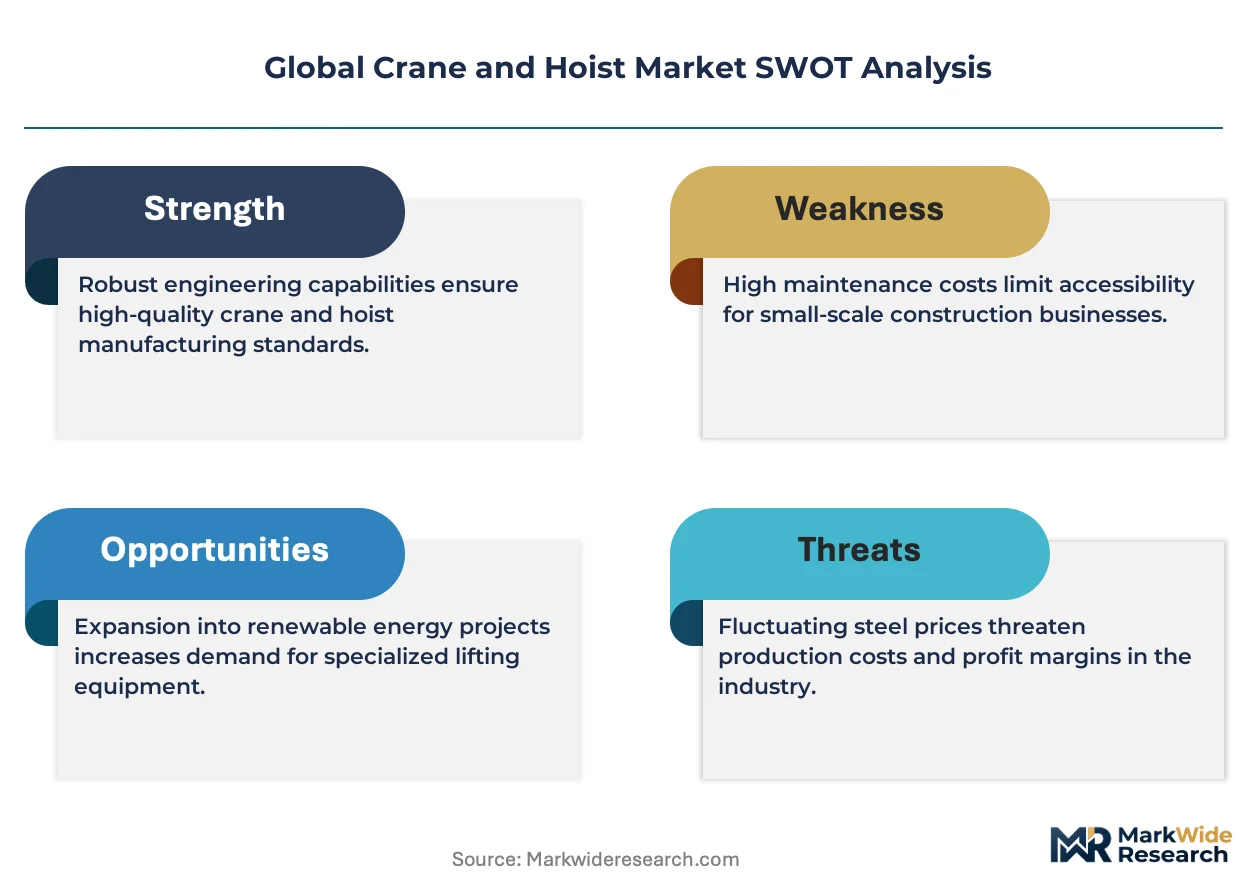
- Steel Price Volatility:Significant fluctuations in the global price of high-strength steel, a primary manufacturing input, directly impact equipment production costs and create margin pressure for manufacturers.
- Skilled Operator Deficit:A persistent shortage of certified crane operators and qualified service technicians across North America and Europe limits equipment utilization and increases operational labor costs for end-users.
- High Capital Expenditure:The substantial upfront investment required to purchase high-capacity tower cranes and large mobile cranes acts as a significant barrier for smaller construction firms and contractors.
Strategic Opportunities
- Aftermarket Service Models:Developing predictive maintenance and remote diagnostic services, enabled by integrated IoT sensors and telematics, creates valuable recurring revenue streams from the global installed base of equipment.
- Electric Powertrain Development:Investing in battery-electric and hybrid-electric mobile cranes provides access to projects in urban centers and regions with strict emissions standards, particularly within the European Union.
- Rental Fleet Modernization:Expanding rental service offerings allows contractors in emerging markets to access modern, technologically advanced equipment without the burden of direct ownership and large capital outlays.
Industry Challenges
- Divergent Certification Pathways:Navigating disparate and complex equipment safety and compliance standards, such as OSHA in the United States and CE marking in Europe, adds significant cost and time to product development and testing.
- Legacy Fleet Integration:On large construction sites, integrating new, digitally-enabled cranes with older, analog equipment fleets presents significant operational challenges related to data compatibility and workflow management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crane and Hoist Market |
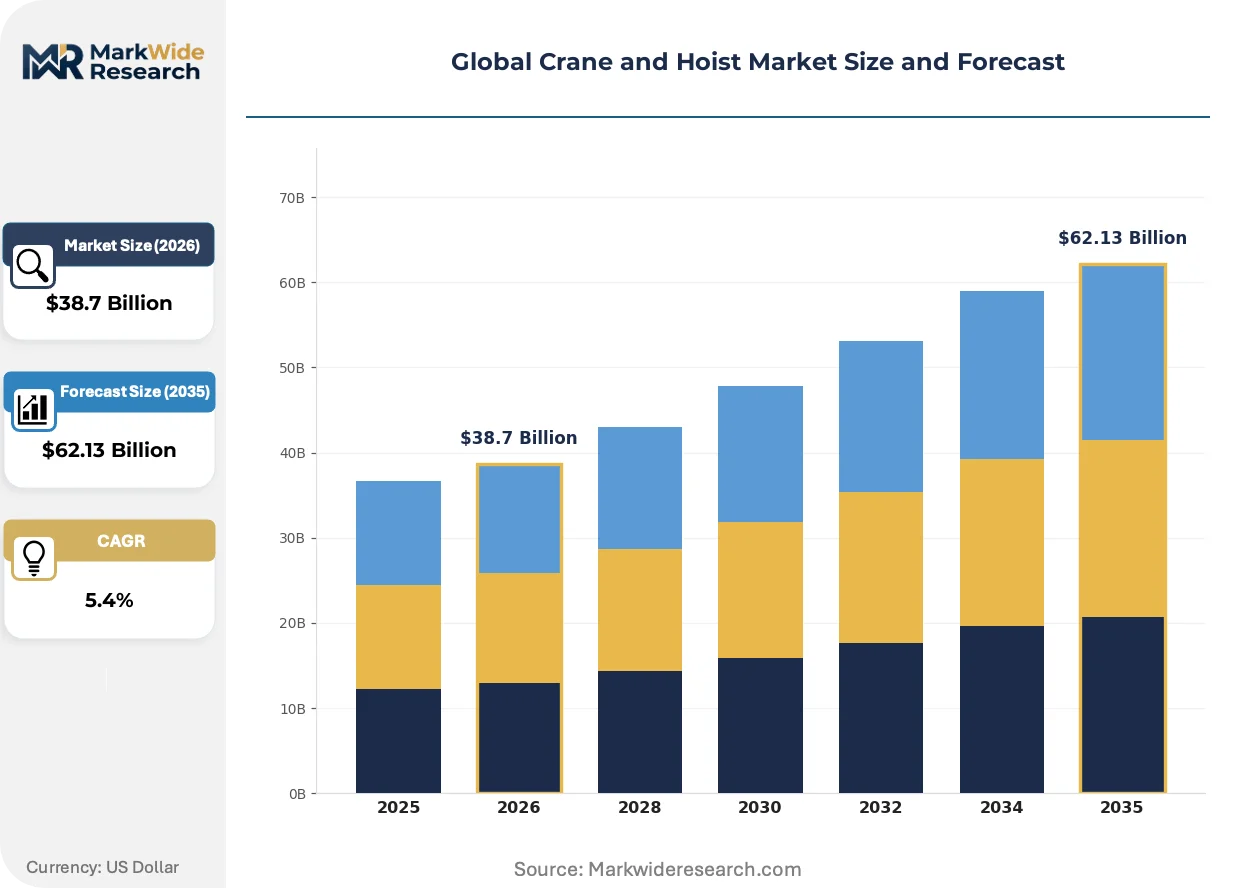
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Cranes, Tower Cranes, Jib Cranes, Gantry Cranes, Loader Cranes Technology: Electric Motor, Hydraulic, Pneumatic, Manual, Diesel Engine Application: Construction, Shipbuilding, Warehousing, Mining, Energy Production End User Industry: Manufacturing Plants, Logistics Providers, Heavy Equipment Rental, Infrastructure Projects |
| Companies Covered | Konecranes, Liebherr, Tadano Ltd., The Manitowoc Company, Inc., Zoomlion Heavy Industry Science & Technology Co., Ltd., Terex Corporation, Cargotec, Columbus McKinnon, PALFINGER AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crane and Hoist Market Strategic Shifts & Innovations
The integration of digital technologies is transforming crane and hoist operations from simple lifting tasks into data-driven logistical functions. This shift prioritizes operational intelligence, predictive uptime, and auditable compliance with worksite safety protocols, moving beyond raw lifting capacity as the sole differentiator.
Telematics and remote monitoring systems are digital platforms that collect real-time data on equipment performance, location, and diagnostics. Major construction firms and port operators are rapidly adopting these systems to manage large fleets and optimize asset utilization. This technology is expanding into the aftermarket, enabling predictive maintenance services and remote troubleshooting that reduce equipment downtime and lifetime operating costs.
Regulatory mandates like the European Union's updated Machinery Regulation are tightening requirements for safety-related control systems and cybersecurity. This compels manufacturers to integrate more robust, verifiable software and hardware safety features, validated through the CE marking process. High-capacity tower cranes and mobile cranes sold into the EU market are most affected, requiring redesigns of their electronic control and operator interface systems to ensure compliance.
Customer procurement patterns are evolving from outright equipment purchase toward long-term rental and leasing agreements, especially for specialized, high-value cranes. This trend elevates the strategic importance of large, multi-regional rental companies, disrupting traditional direct-to-customer sales channels. The shift is most pronounced in North American and European construction markets, where contractors prioritize capital expenditure management and fleet flexibility.
Global Crane and Hoist Market Segmentation
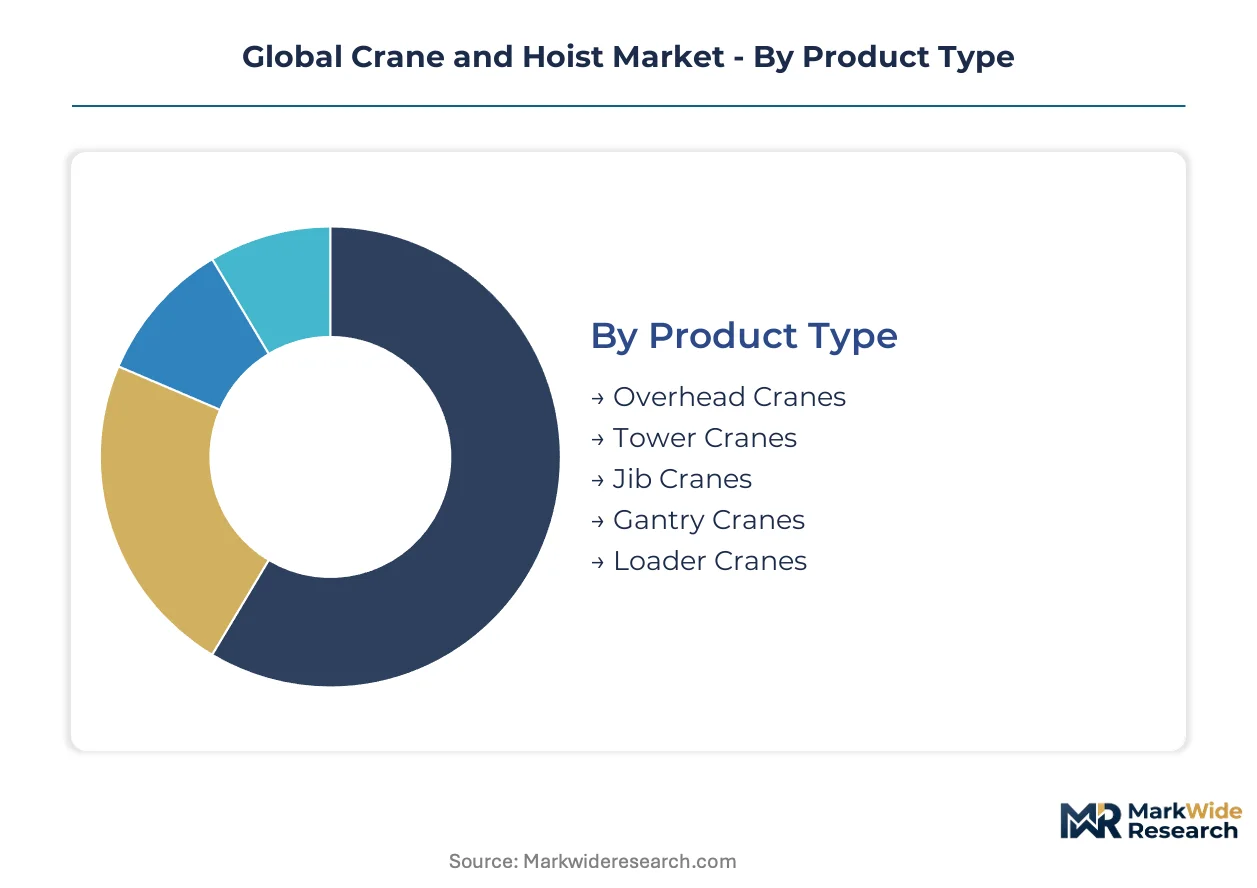
Market segmentation provides a granular view of the crane and hoist industry, delineating distinct product categories, technological applications, and end-user demands. Understanding these divisions allows manufacturers to tailor product development, allocate capital efficiently, and address specific operational requirements across diverse global markets.
Product Type:
The capital intensity of crane and hoist product types significantly influences their market penetration and operational footprint, with high-capacity units demanding substantial upfront investment and specialized infrastructure.
- Tower Cranes:These large, static cranes are engineered for high-rise construction, offering exceptional lifting height and reach, often requiring extensive site preparation and installation. Demand concentrates in India and Southeast Asian nations due to significant urban infrastructure projects.
- Overhead Cranes:Comprising a bridge, trolley, and hoist mechanism, these systems are essential for material handling within enclosed industrial facilities and manufacturing plants. Their demand is consistent in e-commerce warehouse automation projects across North America and Europe.
- Jib Cranes:Fixed-position cranes provide localized lifting solutions within a specific radius, commonly found in workshops, loading docks, and individual workstations.
- Gantry Cranes:These mobile or fixed cranes operate on rails or wheels, widely used in shipbuilding, container yards, and heavy fabrication for robust outdoor lifting.
- Loader Cranes:Vehicle-mounted hydraulic cranes facilitate material loading and unloading from trucks, serving construction, logistics, and utility sectors with flexible mobility.
Tower Cranes absorbs the bulk of installed capacity; Overhead Cranes is expanding most quickly.
Technology:
Operational efficiency and environmental compliance drive the technological choices within the crane and hoist market, with electric powertrains gaining traction in regulated urban environments.
- Electric Motor:Predominant in indoor overhead cranes and increasingly in mobile units, electric motors offer quiet operation, zero emissions, and precise control, aligning with stringent European Union environmental standards. Demand is particularly strong in automated warehouses and for urban construction in Germany.
- Hydraulic:This technology provides high power density and smooth, controlled movement, making it indispensable for mobile cranes, rough terrain cranes, and heavy lifting applications. Its robust nature is critical for large-scale construction projects in China.
- Diesel Engine:Primarily powers large mobile cranes and crawler cranes operating in remote or heavy-duty construction sites where continuous power and mobility are paramount.
- Pneumatic:Air-powered systems are utilized in environments requiring explosion-proof equipment or where spark avoidance is critical, such as certain chemical plants or hazardous material handling.
- Manual:Simple, human-powered hoists and light cranes offer cost-effective and basic lifting solutions for intermittent tasks or smaller loads in workshops.
Electric motor technologies are gaining market share due to emissions regulations, while hydraulic systems maintain their dominance in high-capacity mobile applications.
Application:
The diverse applications of cranes and hoists underscore their foundational role across industrial sectors, each demanding specific equipment characteristics and operational capabilities.
- Construction:This sector represents the largest application area, utilizing tower cranes, mobile cranes, and crawler cranes for infrastructure development, building erection, and specialized heavy lifting. Large-scale public works projects in India are a significant demand driver.
- Warehousing:Essential for material handling, inventory management, and order fulfillment in logistics centers and e-commerce distribution hubs, primarily employing overhead cranes and hoists. The proliferation of automated fulfillment centers in the United States drives this segment.
- Shipbuilding:Requires heavy-duty gantry cranes and large overhead cranes for assembling ship sections, moving heavy components, and launching vessels in shipyards.
- Mining:Utilizes robust lifting equipment for maintaining heavy machinery, handling raw materials, and supporting underground operations in extraction sites.
- Energy Production:Demands specialized cranes for the construction and maintenance of power plants, including nuclear, thermal, and renewable energy facilities like wind farms.
The Construction sector commands the largest share of crane and hoist deployment, with Warehousing exhibiting rapid expansion driven by e-commerce logistics.
End User Industry:
End-user industries dictate procurement patterns and technology preferences, ranging from long-term ownership by manufacturing giants to flexible rental models for project-based contractors.
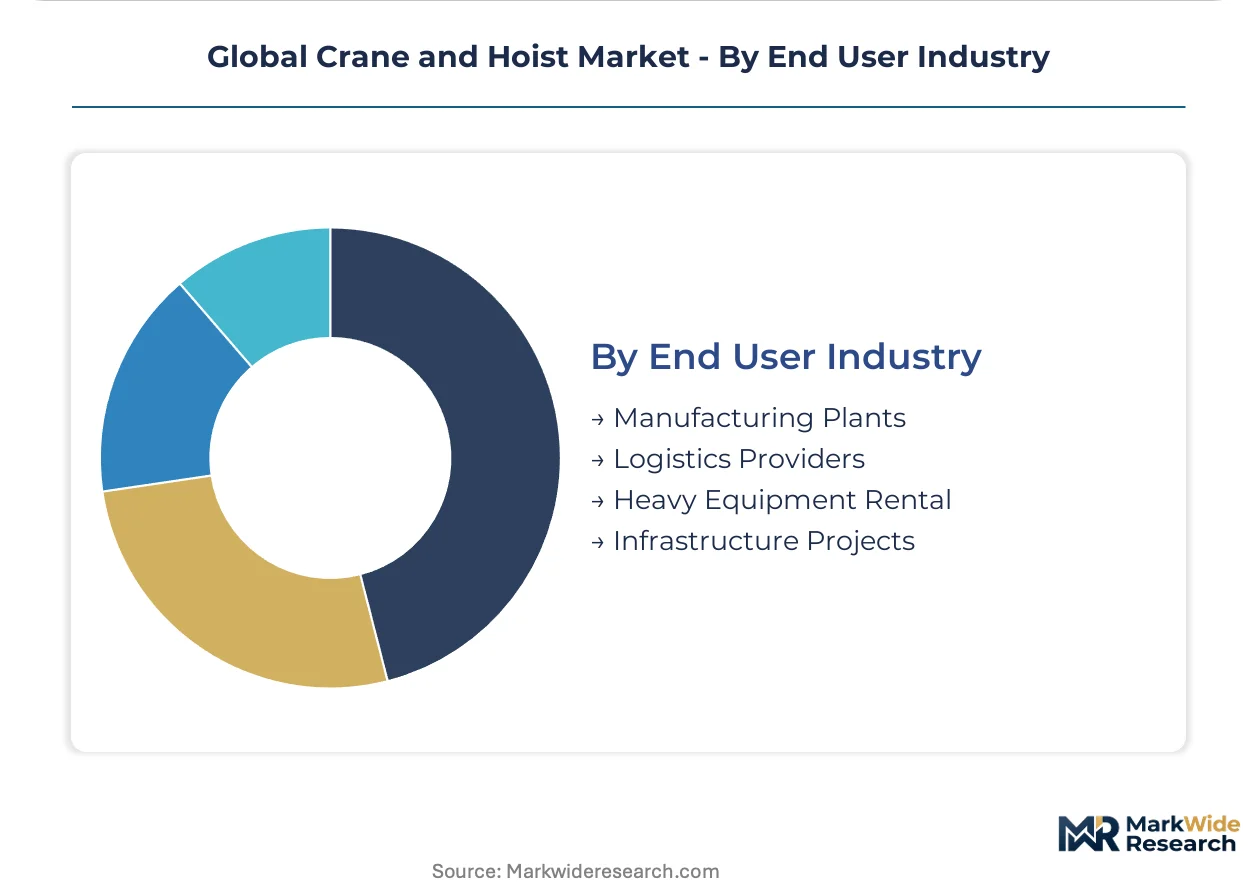
- Infrastructure Projects:These include large-scale public works such as bridges, roads, airports, and urban rail systems, which require extensive fleets of high-capacity mobile and tower cranes. Significant government and private investments in Southeast Asian nations are driving demand.
- Manufacturing Plants:Automotive, heavy machinery, and general manufacturing facilities rely on overhead cranes and hoists for assembly lines, material flow, and equipment maintenance. The German automotive industry consistently invests in advanced lifting solutions.
- Logistics Providers:Companies specializing in freight, warehousing, and supply chain management utilize cranes for container handling at ports and efficient material movement within distribution centers.
- Heavy Equipment Rental:Rental companies provide access to a wide range of cranes and hoists, offering flexibility and reducing capital expenditure for contractors on short-term or specialized projects.
Infrastructure Projects represent a primary demand source for high-capacity cranes, while the Heavy Equipment Rental segment is gaining traction due to evolving procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, a primary global producer of high-strength steel, anchors the raw material supply chain for the crane and hoist industry. Its significant domestic demand for heavy machinery also makes it a critical end-market. This dual role positions China as a central force in global crane and hoist market dynamics.
India
Urban infrastructure investment and large-scale public works projects drive demand for high-capacity mobile and tower cranes. The Indian government's "Make in India" initiative encourages domestic manufacturing, potentially influencing procurement patterns. Major urban centers like Mumbai and New Delhi are experiencing significant construction booms, requiring extensive lifting equipment.
Germany
Manufacturing plants, particularly in the automotive industry, consistently invest in advanced overhead cranes and electric hoists. Stringent European Union environmental standards accelerate the adoption of electric motor technologies in mobile units. Industrial clusters in Bavaria, such as Munich, are key centers for advanced lifting solution development and deployment.
United States
E-commerce warehouse automation and large-scale construction projects fuel demand for overhead cranes and high-capacity mobile cranes. OSHA standards dictate rigorous safety and operational requirements for all lifting equipment. Major logistics hubs, including those in the Midwest and California, prioritize efficient material handling systems.
China
Demand for high-capacity tower cranes and hydraulic systems is substantial due to ongoing large-scale construction and infrastructure development. Compliance with specific GB standards for lifting machinery is essential for market access and product design. Industrial zones in the Yangtze River Delta continue to be major manufacturing and deployment centers for heavy construction equipment.
Global Crane and Hoist Market Key Industry Players
Global majors compete with regional champions across technological capability and product portfolio in the crane and hoist market. The market structure is tiered, encompassing full-line global providers, specialized industrial players, and high-volume regional manufacturers. Key competitive moves include portfolio diversification and the integration of advanced automation and telematics technologies.
Specialists in specific lifting solutions, such as Finnish-based Konecranes and Chinese Zoomlion Heavy Industry Science & Technology Co., Ltd., define distinct market segments. Konecranes exemplifies expertise in industrial overhead cranes and port solutions, while Zoomlion Heavy Industry Science & Technology Co., Ltd. anchors the high-capacity tower crane segment in developing economies. Liebherr, a German group, represents a full-line provider with an extensive product portfolio serving diverse end-markets.
| Leading Market Players |
|---|
| Konecranes |
| Liebherr |
| Tadano Ltd. |
| The Manitowoc Company, Inc. |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Terex Corporation |
| Cargotec |
| Columbus McKinnon |
| PALFINGER AG |
| Others |
Cost & Logistics Intelligence
The London Metal Exchange (LME) steel rebar index, reflecting high-strength steel costs, directly influences manufacturing expenses for cranes and hoists. This volatility cascades through the supply chain, impacting equipment pricing across various product tiers.
Pricing Analysis
Warranty and extended service contracts often unbundle from the base equipment price, allowing for flexible procurement options. Project-based pricing dominates for high-capacity tower cranes, while per-unit transactional pricing characterizes overhead cranes. Price differentiation stems from specialized engineering requirements and the inclusion of advanced telematics features. Pricing softness reflects intense competition for large infrastructure projects in Southeast Asia, where smaller construction firms exhibit higher price sensitivity than large port operators.
Supply Chain Analysis
High-strength steel supply primarily rests on producers in China, Germany, and Japan, forming a critical raw material dependency. Electronic control units and hydraulic components represent other key inputs for modern crane manufacturing. A single-source vulnerability exists for specialized components, posing a structural risk to production schedules. Equipment distribution runs through a hybrid model, combining direct sales channels for major projects with extensive dealer networks and rental fleets for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crane and hoist market is currently in a technology-transition phase, with battery-electric powertrains displacing legacy diesel engines across several mobile unit segments. This shift creates distinct strategic imperatives for market participants.
For Market Incumbents:
To counter the threat of specialized new entrants offering advanced digital features, incumbents should deepen vertical integration into telematics software development. Consolidating manufacturing capacity around electric powertrain expertise in Europe strengthens compliance with emissions standards. Investing in comprehensive aftermarket service networks also secures recurring revenue streams against market commoditization.
For New Entrants and Emerging Players:
Predictive maintenance software platforms offer a technology-first wedge into the established crane and hoist market. Target underpenetrated segments like rental fleet modernization in North America with subscription-based diagnostic services. Offering specialized electric hoists for automated e-commerce warehouses in the United States provides another white-space opportunity. A direct-to-customer digital sales and support model can bypass traditional distribution channels.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor mid-sized component manufacturers in Germany specializing in electric motor technologies. The long-term viability of this market over a five-to-ten-year window remains strong, driven by global infrastructure needs. Acquisition targets should include firms with proven intellectual property in automation and remote operation systems. The signal to watch is the increasing share of electric crane units in major rental fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Battery-Electric Powertrains | This initiative aligns with European Union emissions regulations, expanding market access for mobile cranes in urban centers. |
| Expand Telematics and IoT Integration | Remote monitoring capabilities reduce equipment downtime and enable new aftermarket service models for large construction firms. |
| Develop Advanced Operator Assistance Systems | Enhancing safety protocols addresses stringent OSHA standards in the United States and improves operational efficiency on complex sites. |
| Optimize High-Strength Steel Procurement | Strategic sourcing mitigates steel price volatility, protecting manufacturing margins for tower crane producers. |
| Modernize Rental Fleet Offerings | Providing access to new technology without capital outlay boosts adoption among contractors in emerging markets like India. |
Research Approach
Multi-period observation of equipment sales volumes and project pipeline indicators anchored the trend analysis, supplemented by interviews with manufacturing plant managers and heavy equipment rental executives. Primary insights were validated against secondary data from national infrastructure reports and CE marking documentation. This approach utilized both bottom-up market sizing and top-down industry trend analysis for robust triangulation.
Segment-weighting across product type, technology, and application formed the core of the quantitative forecast framework over the projection horizon. This model also integrated regional infrastructure spending patterns and e-commerce warehouse expansion rates. Compound Annual Growth Rates (CAGRs) were derived through a regression analysis of historical market performance and projected demand drivers. Global steel price forecasts served as a key industry-specific input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical instability or unexpected raw material supply shocks. These forecasts reflect assumptions regarding sustained infrastructure investment and stable regulatory environments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Road Roller Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Rotomolding Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Global Crane Market
Construction Equipment
Overhead Cranes Market