
 Scissor Lift Market | 2026-2036
Scissor Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Scissor Lift Market Intelligence
A capital-intensity divergence between full-line manufacturers and specialized assemblers is reorganizing competitive tiers in the aerial work platform sector. JLG Industries leverages integrated boom and scissor manufacturing to sustain pricing power across rental channels. Haulotte Group anchors its position through European engineering standards and regional service density. Zhejiang Dingli Machinery specializes in cost-optimized electric platforms that compete aggressively in Asian and emerging markets.
A scissor lift is a mobile elevated work platform that uses linked, folding supports in a crisscross pattern to raise a work platform vertically, typically achieving working heights from 20 to 50 feet with load capacities between 500 and 2,500 pounds depending on model class. The mechanism relies on hydraulic or electric actuator systems to extend or retract the scissor stack, providing stable vertical access for personnel and tools in industrial and commercial environments. Electric scissor lifts now lead unit shipments in warehousing and retail maintenance segments where indoor emissions compliance restricts internal-combustion alternatives. Hydraulic platforms retain dominance in outdoor construction applications requiring higher load ratings and rough-terrain mobility. Medium platform sizes capture the largest margin pool by balancing rental fleet versatility against transport logistics efficiency.
ANSI A92 standards in the United States mandate load-sensing systems and tilt alarms that elevate engineering costs for new platform introductions. EN 280 certification across Europe imposes structural testing protocols that filter out lower-tier suppliers from regulated markets. OSHA inspection requirements and the EU Machinery Directive together shape replacement cycles by forcing documented maintenance trails. Stakeholders must monitor electrification cost curves against diesel-hybrid residual values when configuring multi-year fleet commitments.
Market Dynamics
Fleet electrification mandates and warehouse automation density targets are compressing replacement cycles and reshaping manufacturer order backlogs across the aerial work platform sector.
Growth Catalysts
- E-commerce fulfillment density:Warehouse operators in the United States are expanding vertical storage systems that require frequent elevated access, pulling electric scissor lift demand into multi-unit fleet contracts.
- ANSI A92 standards:Load-sensing and tilt-alarm mandates in North America are filtering out uncertified suppliers and consolidating procurement toward compliant equipment vendors.
- Lithium-ion traction systems:Battery chemistry improvements are extending duty cycles between charges, enabling electric platforms to displace diesel hybrids in outdoor applications previously reserved for internal combustion.
Market Restraints
- Steel and aluminum input volatility:Platform chassis fabrication depends on commodity metals whose price swings compress assembler margins during contract bidding periods.
- Hydraulic component concentration:Precision valve and pump sourcing clusters in German and Japanese industrial centers, exposing supply chains to single-point disruption risks.
- EN 280 certification friction:European structural testing protocols create eighteen-to-twenty-four month approval timelines that block fast product iteration for non-integrated manufacturers.
Strategic Opportunities
- India warehouse construction:Cold chain and logistics infrastructure buildouts in Maharashtra and Karnataka are generating first-time fleet demand from domestic 3PL operators.
- CSRD reporting alignment:European corporate sustainability disclosure rules are elevating electric platform preference in rental procurement specifications.
- Telematics-convergence:IoT-enabled fleet management systems are opening recurring software revenue streams atop equipment hardware sales.
Industry Challenges
- Certified technician scarcity:Hydraulic diagnostics and battery management system repair require specialized training pipelines that OEMs must build regionally.
- Multi-standard compliance overhead:Manufacturers serving both ANSI A92 and EN 280 jurisdictions face duplicated engineering validation costs per model variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scissor Lift Market |
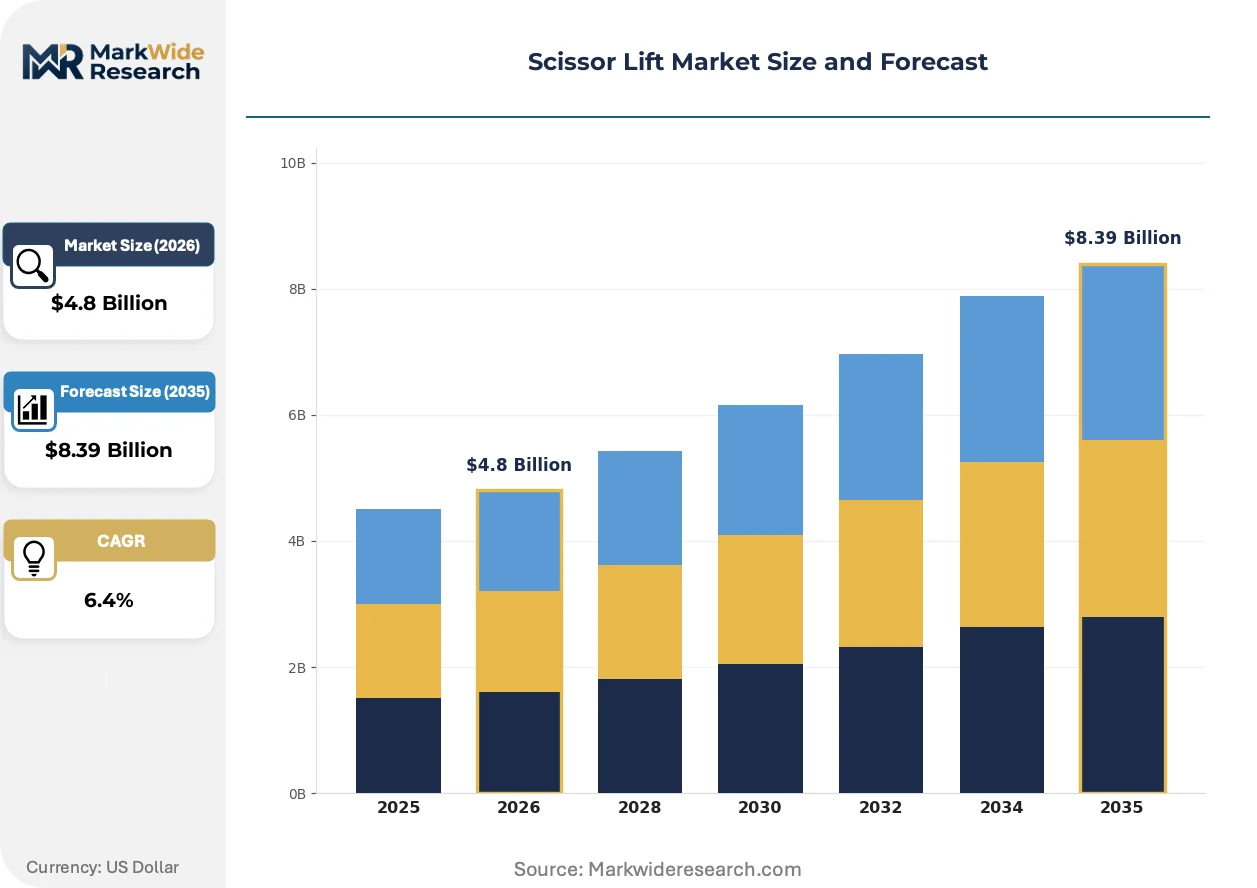
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Diesel, Pneumatic End User: Construction, Manufacturing, Warehousing, Retail Application: Maintenance, Installation, Cleaning, Inspection Platform Size: Small, Medium, Large, Extra Large |
| Companies Covered | JLG Industries, Terex Corporation, Linamar Corporation, Haulotte Group, Zoomlion Heavy Industry Science & Technology Co., Ltd., Zhejiang Dingli Machinery Co., Ltd., XCMG Construction Machinery Co., Ltd., Sinoboom Group Co., Ltd., MEC Aerial Work Platforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scissor Lift Market Strategic Shifts & Innovations
Equipment intelligence and powertrain diversification are redefining competitive differentiation in aerial work platforms, moving the basis of rivalry from lift capacity specifications toward total cost of ownership and data integration capabilities.
Lithium-iron-phosphate battery packs are fragmenting the traditional diesel-electric product hierarchy in scissor lift portfolios. Warehouse fleet managers in Germany and the Netherlands are specifying all-electric platforms for both indoor and semi-outdoor duty cycles. This chemistry shift is fragmenting residual value calculations and compressing payback period assumptions that previously favored diesel-hybrid architectures.
OSHA inspection documentation requirements are tightening maintenance record-keeping standards for rental fleets operating across state jurisdictions. Equipment lessors must now deploy digital audit trails to satisfy multi-state compliance verification. California and Texas construction corridors are experiencing the earliest enforcement intensity, forcing regional fleet operators to accelerate telematics adoption.
Rental channel consolidation is compressing manufacturer negotiation leverage in North American distribution. National equipment lessors are unbundling after-sales service contracts and bringing preventive maintenance in-house. This behavioral shift is most visible in Sun Belt metropolitan construction markets where multi-year fleet commitments now dominate procurement patterns.
Scissor Lift Market Segmentation
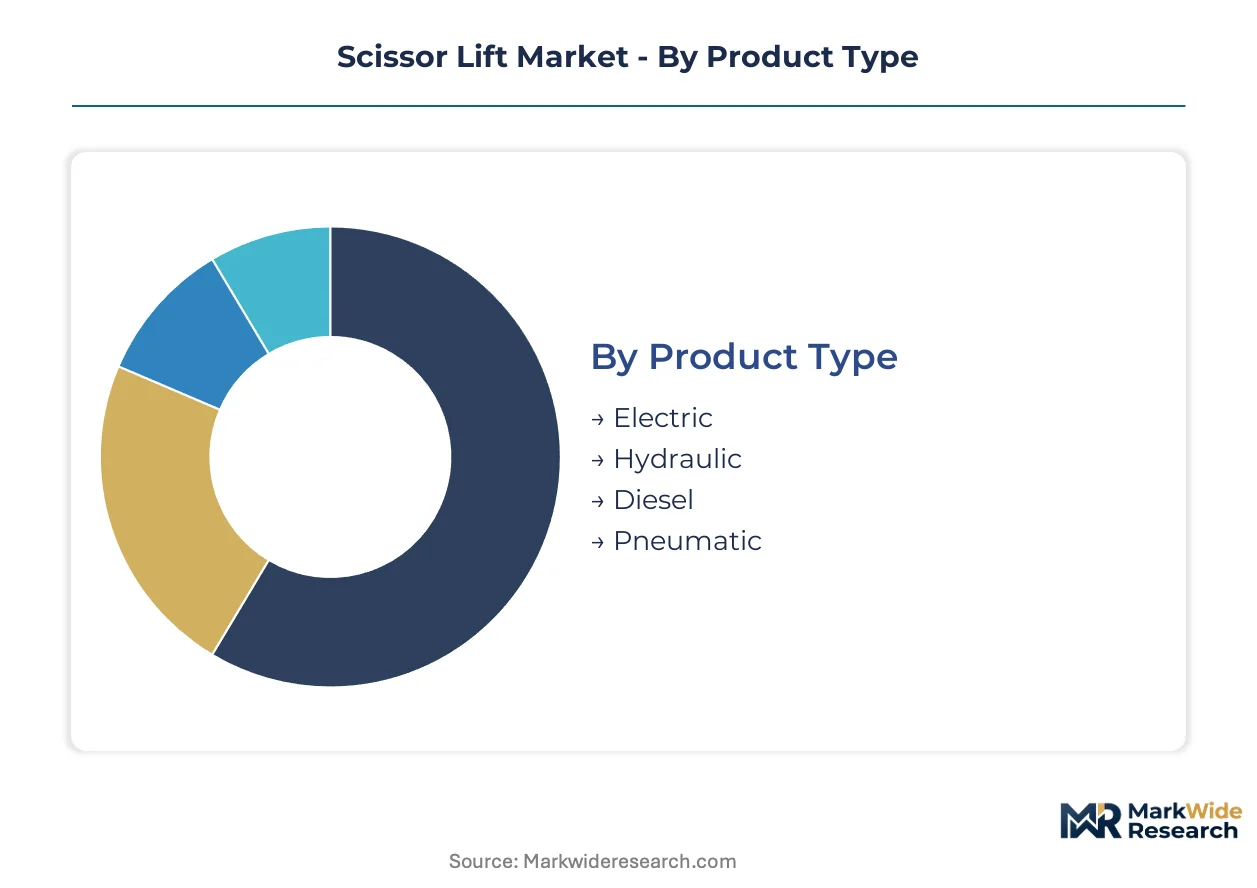
Scissor lift procurement patterns diverge sharply across powertrain technologies and platform specifications, with margin pools concentrating where electrification meets indoor emissions compliance. Fleet managers configure equipment selections against duty cycle intensity, vertical reach requirements, and regulatory jurisdiction rather than lift capacity alone.
Product Type:
Margin pools concentrate in electric platforms where battery chemistry improvements are extending duty cycles and displacing diesel alternatives in semi-outdoor applications previously reserved for internal combustion.
- Electric:Lithium-iron-phosphate battery packs deliver zero-emission operation with extended cycle life, capturing warehouse fleet demand in Germany and the Netherlands where CSRD reporting elevates electric specifications. Indoor emissions mandates in California and Texas construction corridors are accelerating rental channel conversion from diesel hybrids.
- Hydraulic:High-pressure fluid systems enable rough-terrain mobility and superior load ratings for outdoor construction sites, retaining dominance in Sun Belt metropolitan corridors where ANSI A92 stability requirements filter uncertified suppliers. Steel and aluminum input volatility compresses assembler margins during contract bidding periods.
- Diesel:Internal combustion powertrains serve remote job sites lacking electrical infrastructure, though residual value calculations are fragmenting as lithium-ion traction improves.
- Pneumatic:Compressed air systems operate in explosive atmosphere environments where spark ignition risks prohibit electric or diesel alternatives.
Electric holds installed capacity. Hydraulic is rotating up the share rankings in outdoor applications previously diesel-dependent.
End User:
Application intensity and fleet scale determine customer profitability, with multi-unit contracts from national lessors commanding preferential pricing against single-unit construction purchases.
- Construction:General contractors deploy rough-terrain platforms for structural work and facade installation, with procurement concentrating in United States Sun Belt corridors where OSHA inspection documentation requirements tighten maintenance record-keeping standards.
- Manufacturing:Assembly line maintenance drives demand for compact electric units with tight turning radius specifications, particularly in automotive and aerospace production facilities.
- Warehousing:E-commerce fulfillment density is pulling electric scissor lift demand into multi-unit fleet contracts as operators expand vertical storage systems requiring frequent elevated access.
- Retail:Big-box store operators specify low-floor-loading electric platforms for overnight maintenance windows in climate-controlled environments.
Construction dominates current fleet deployment. Warehousing is gaining share fastest as vertical storage systems proliferate.
Application:
Task duration and access frequency shape equipment configuration, with intermittent inspection duties favoring rental models against capital-intensive installation contracts.
- Maintenance:Preventive and corrective work on industrial equipment, building systems, and infrastructure assets constitutes the largest addressable use case across all end-user segments.
- Installation:New construction and retrofit projects require extended platform deployment with higher load ratings for material handling alongside personnel.
- Cleaning:Window washing and facade maintenance in commercial buildings demand compact footprints for urban site constraints.
- Inspection:Regulatory compliance verification and safety audits utilize platforms for elevated visual access without material handling requirements.
Maintenance commands the broadest fleet utilization. Installation is climbing the fastest as construction activity intensifies.
Platform Size:
Transport logistics efficiency and rental fleet versatility create margin concentration in mid-range specifications that balance reach capability against trailer towing requirements.
- Medium:Twenty to thirty-two foot working heights with deck dimensions accommodating two workers plus tools capture the largest margin pool by balancing rental fleet versatility against transport logistics efficiency. ANSI A92 load-sensing mandates elevate engineering costs for this specification band.
- Small:Compact platforms under twenty feet working height serve narrow-aisle warehousing and retail maintenance with zero-turn maneuverability.
- Large:Extended reach platforms between thirty-two and forty feet address industrial maintenance and commercial construction with elevated load requirements.
- Extra Large:Maximum height specifications exceeding forty feet serve specialized infrastructure and energy sector applications with custom outrigger configurations.
Medium platforms anchor rental fleet standardization. Large specifications are expanding most quickly in industrial maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European buyers prioritize EN 280 certification compliance over unit cost, while emerging market procurement centers on acquisition price with maintenance deferred to local service networks.
United States
Sun Belt metropolitan construction corridors in Texas, Florida, and Arizona drive fleet expansion for commercial and residential vertical buildouts. OSHA mandates load-sensing systems and tilt alarms under ANSI A92 standards, filtering uncertified suppliers from rental channels. Dallas-Fort Worth and Houston anchor the densest rental fleet concentrations, with national lessors consolidating multi-year procurement contracts.
Germany
Industrial maintenance and automotive assembly applications sustain demand for compact electric platforms with tight maneuverability specifications. The EU Machinery Directive and CSRD sustainability disclosure rules elevate electric platform preference in corporate procurement specifications. Stuttgart and Munich industrial corridors host the tightest service network densities for preventive maintenance contracts.
China
Urban renewal and logistics infrastructure buildouts pull demand across all platform size classes, with domestic assemblers competing aggressively on cost-optimized electric specifications. GB standards and MIIT industrial equipment regulations shape local certification requirements. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate both production capacity and fleet deployment for domestic 3PL operators.
India
Cold chain and e-commerce logistics infrastructure expansion in Maharashtra and Karnataka generates first-time fleet demand from domestic 3PL operators unfamiliar with aerial work platform procurement. BIS certification requirements and state-level factory safety inspectorates create compliance friction for imported equipment. Mumbai-Pune and Bengaluru logistics corridors are experiencing the steepest rental fleet growth as warehouse automation density targets accelerate.
United Kingdom
Commercial building maintenance and retail facility management sustain replacement demand for medium-height electric platforms. HSE regulations and post-Brexit machinery conformity assessment procedures extend approval timelines for non-UK manufacturers. London and Southeast England concentrate rental fleet utilization, with overnight maintenance windows in big-box retail driving specifications for low-floor-loading electric units.
Scissor Lift Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Full-line manufacturers with integrated boom and scissor capabilities command pricing power across rental channels, while specialized assemblers compete on cost-optimized specifications for price-sensitive segments. Two strategic archetypes dominate: integrated full-line suppliers with captive component production, and focused electric platform specialists leveraging battery chemistry improvements. Competitive moves concentrate on geographic expansion into underpenetrated warehouse automation markets and portfolio diversification toward telematics-enabled fleet management services.
Among North American integrated manufacturers, JLG Industries and Terex Corporation occupy positions representing full-line capability across boom and scissor categories. Haulotte Group anchors the European engineering standards tier. Zhejiang Dingli Machinery Co., Ltd. exemplifies the cost-optimized electric specialist archetype competing in Asian and emerging market procurement cycles.
| Leading Market Players |
|---|
| JLG Industries |
| Terex Corporation |
| Linamar Corporation |
| Haulotte Group |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Zhejiang Dingli Machinery Co., Ltd. |
| XCMG Construction Machinery Co., Ltd. |
| Sinoboom Group Co., Ltd. |
| MEC Aerial Work Platforms |
| Others |
Cost & Logistics Intelligence
Lithium-iron-phosphate battery chemistry substitution for diesel-hybrid powertrains is redrawing procurement geography toward Chinese cell manufacturers while compressing residual value premiums that previously anchored manufacturer pricing power. This dual displacement simultaneously elevates working capital requirements for fleet operators and fragments pricing coherence across rental channels.
Pricing Analysis
After-sales service contracts and preventive maintenance subscriptions now generate lifetime value multiples exceeding original equipment margins for integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ANSI A92 certification grade and telematics integration depth, with national rental lessors extracting volume discounts that compress assembler margins. Cost compression in the economy tier intensifies because Zhejiang Dingli and domestic Chinese assemblers compete aggressively on acquisition price. Single-unit construction buyers exhibit highest price sensitivity, while warehouse fleet managers prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Strategic stockpiling of hydraulic valve and pump components dominates inventory strategy among European and North American assemblers seeking insulation from German and Japanese supply concentration. Manufacturing capacity clusters in China, Germany, and the United States, with chassis fabrication drawing from steel and aluminum commodity markets exposed to price volatility. Single-source vulnerability in precision hydraulic component sourcing creates disruption exposure when geopolitical friction affects German-Japanese trade corridors. Distribution runs through national equipment lessors and regional rental houses that consolidate fleet procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through rental channel consolidation, with national lessors unbundling after-sales service and bringing maintenance in-house, fragmenting manufacturer margin capture across the value chain.
For Market Incumbents: Fortify captive component production of lithium-ion battery management systems and hydraulic actuator assemblies to defend against cost-optimized Chinese entrants. Deepen backward integration into steel chassis fabrication to buffer commodity volatility. Prioritize ANSI A92 certification investment as a barrier against uncertified suppliers filtering into Sun Belt metropolitan procurement. For New Entrants and Emerging Players: Anchor in India warehouse automation corridors where cold chain infrastructure buildouts generate first-time fleet demand from domestic 3PL operators unfamiliar with aerial work platform procurement specifications. Target Maharashtra and Karnataka logistics clusters with cost-optimized electric platforms certified to BIS standards. Pursue telematics-enabled fleet management software as a recurring revenue wedge alongside hardware sales. For Investors and Strategic Acquirers: CSRD reporting alignment in Europe reshapes the acquisition landscape by elevating electric platform specialists over diesel-dependent legacy portfolios. Long-term viability favors integrated manufacturers with captive battery supply chains and multi-standard engineering capabilities across ANSI A92 and EN 280 jurisdictions. Monitor lithium-iron-phosphate cost curves as the inflection signal determining residual value fragmentation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | IoT-enabled fleet management opens recurring software revenue streams atop hardware sales for rental lessors. |
| Lithium-Ion Powertrain Transition | Battery chemistry improvements displace diesel hybrids in outdoor applications previously reserved for internal combustion. |
| Multi-Standard Certification Investment | ANSI A92 and EN 280 compliance filters uncertified suppliers from regulated procurement channels in North America and Europe. |
| Backward Integration into Hydraulics | In-house valve and pump production reduces exposure to German-Japanese supply concentration risks. |
| India Market Entry Partnership | Domestic 3PL operators in Maharashtra and Karnataka generate first-time fleet demand for cold chain buildouts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, plant engineers at manufacturing facilities, OEM procurement teams, and aftermarket service heads at national rental lessors. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive implementation records, SEC 10-K filings of listed equipment manufacturers, and customs trade data on aerial work platform imports. Bottom-up unit shipment estimates triangulated against top-down fleet size modeling.
Across the analysis window, the forecasting framework modeled volume and value outputs by powertrain technology, platform size class, end-use segment, and regional regulatory cluster. CAGRs were derived from regression analysis of historical fleet replacement cycles against electrification mandate intensity and warehouse automation density targets. Industry-specific inputs included lithium-ion battery cost curve trajectories and EN 280 certification timeline assumptions.
Decision-makers should treat outputs as directional under assumptions of continued e-commerce fulfillment density expansion and stable commodity metal pricing; material deviation would warrant model refresh. Revision becomes warranted when electrification subsidy programs cross threshold intensity or when hydraulic component supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Stacker Crane Market