
 Global Metal Forming Machine Tools Market | 2026-2036
Global Metal Forming Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Forming Machine Tools Market Foresight
Buyer concentration among automotive OEMs is pivoting toward vertical integration of stamping and forging operations. Schuler AG dominates large mechanical press systems for high-volume vehicle platforms. TRUMPF Group leverages laser-hybrid forming technologies to differentiate its equipment portfolio for aerospace fabricators. Komatsu Industries Corp. anchors Asian supply chains through localized servo-electric press production.
Metal forming machine tools encompass mechanical, hydraulic, and electromechanical equipment designed to reshape sheet metal, bars, and billets through plastic deformation at forces ranging from tens to thousands of metric tons. These systems serve primary industrial purposes including automotive body panel stamping, aerospace structural forging, and precision electrical component drawing. Press brakes and servo-electric technology segments lead margin pools as fabricators prioritize energy efficiency and programmable repeatability. Rolling machines occupy mature replacement cycles in shipbuilding, while forging presses sustain premium pricing in heavy equipment and defense applications.
FDA equipment safety guidelines, EU machinery directives with CE marking requirements, and China's GB standards under SAMR collectively shape product certification pathways and cross-border equipment acceptance. Japan's METI energy efficiency benchmarks and India's BIS machinery safety codes further fragment compliance obligations for multinational suppliers. Stakeholders must monitor how carbon border adjustments and local content rules redirect capital deployment across precision manufacturing clusters.
Market Dynamics
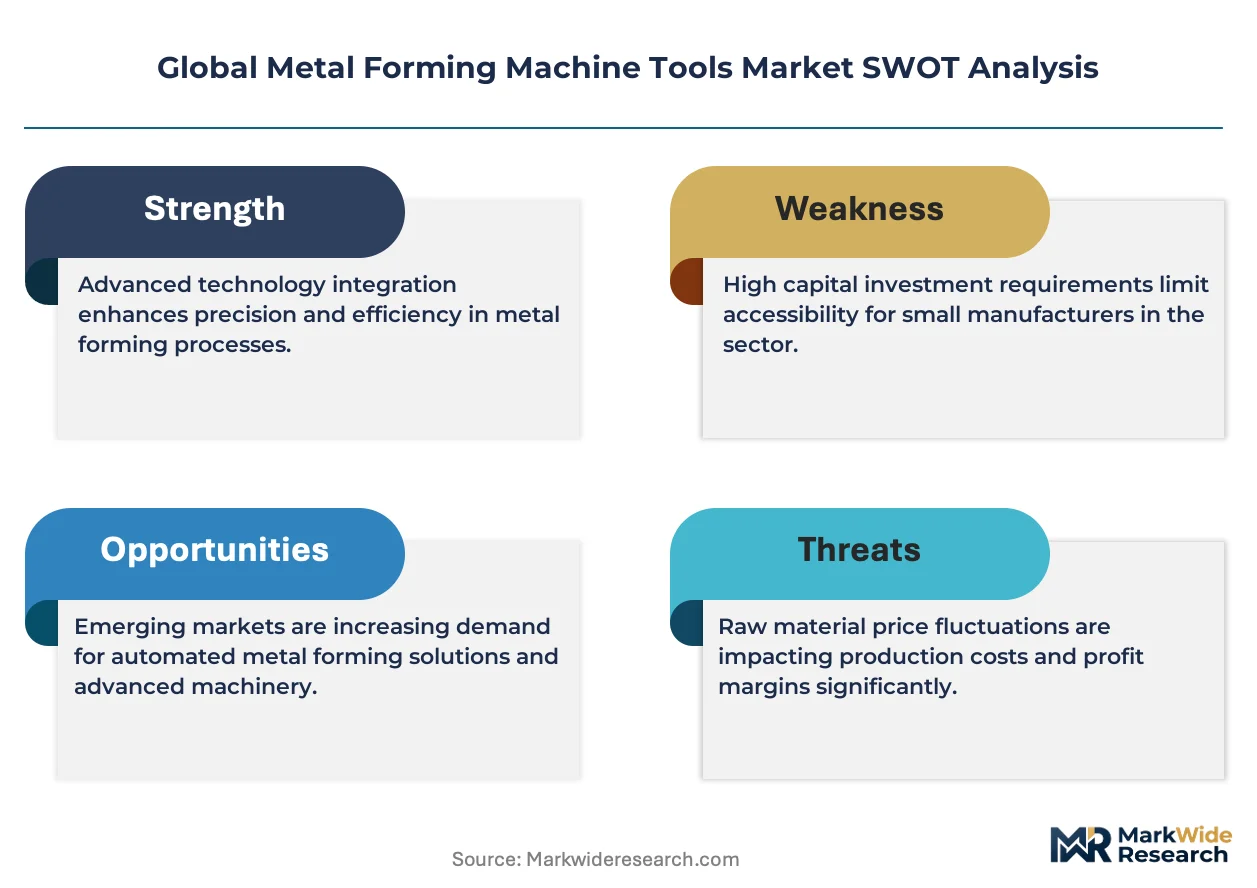
Servo-electric press technology is compressing hydraulic equipment margins while automotive OEMs pursue captive stamping capacity to insulate supply chains from tier-one supplier volatility.
Growth Catalysts
- EU Machinery Directive CE marking:Fabricators across Germany and Italy are retiring pre-2010 mechanical presses to meet updated safety interlock mandates, triggering replacement demand for certified servo-electric systems.
- Automotive lightweighting programs:Aluminum-intensive vehicle platforms require higher-tonnage hot forming presses, pulling investment toward 1,000+ metric ton servo-hydraulic hybrid configurations.
- China's dual carbon goals:Provincial energy efficiency audits under MEE guidelines are accelerating factory upgrades from conventional hydraulic presses to regenerative servo drives in Jiangsu and Guangdong manufacturing clusters.
Market Restraints
- Specialized steel alloy supply:Tooling-grade tungsten and molybdenum price volatility from concentrated Kazakh and Russian mining operations inflates die manufacturing costs by unpredictable margins.
- Control system import dependence:Precision motion controllers from German and Japanese suppliers create 14-22 week lead time exposure for Asian press builders lacking domestic alternatives.
- Skilled press operator scarcity:North American and Western European vocational training programs graduate insufficient technicians qualified in servo-electric programming and predictive maintenance protocols.
Strategic Opportunities
- India PLI scheme for auto components:Tier-two stampers in Pune and Chennai corridors qualify for capital equipment subsidies when deploying presses above 400 metric tons for export-bound chassis parts.
- Laser-hybrid forming convergence:Aerospace fabricators in Toulouse and Hamburg are piloting combined laser heating and servo press forming for titanium airframe components, opening premium equipment segments.
- Remanufactured press channels:Secondary markets for refurbished mechanical presses are consolidating through certified rebuild programs serving Mexican and Vietnamese metalworking SMEs.
Industry Challenges
- Multi-axis synchronization complexity:Automotive transfer press retrofits require reconciling legacy mechanical index drives with new servo motor controls, extending commissioning timelines.
- Cross-border certification fragmentation:Press builders exporting from Japan to the EU must reconcile METI energy benchmarks with CE machinery directives, duplicating testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Forming Machine Tools Market |
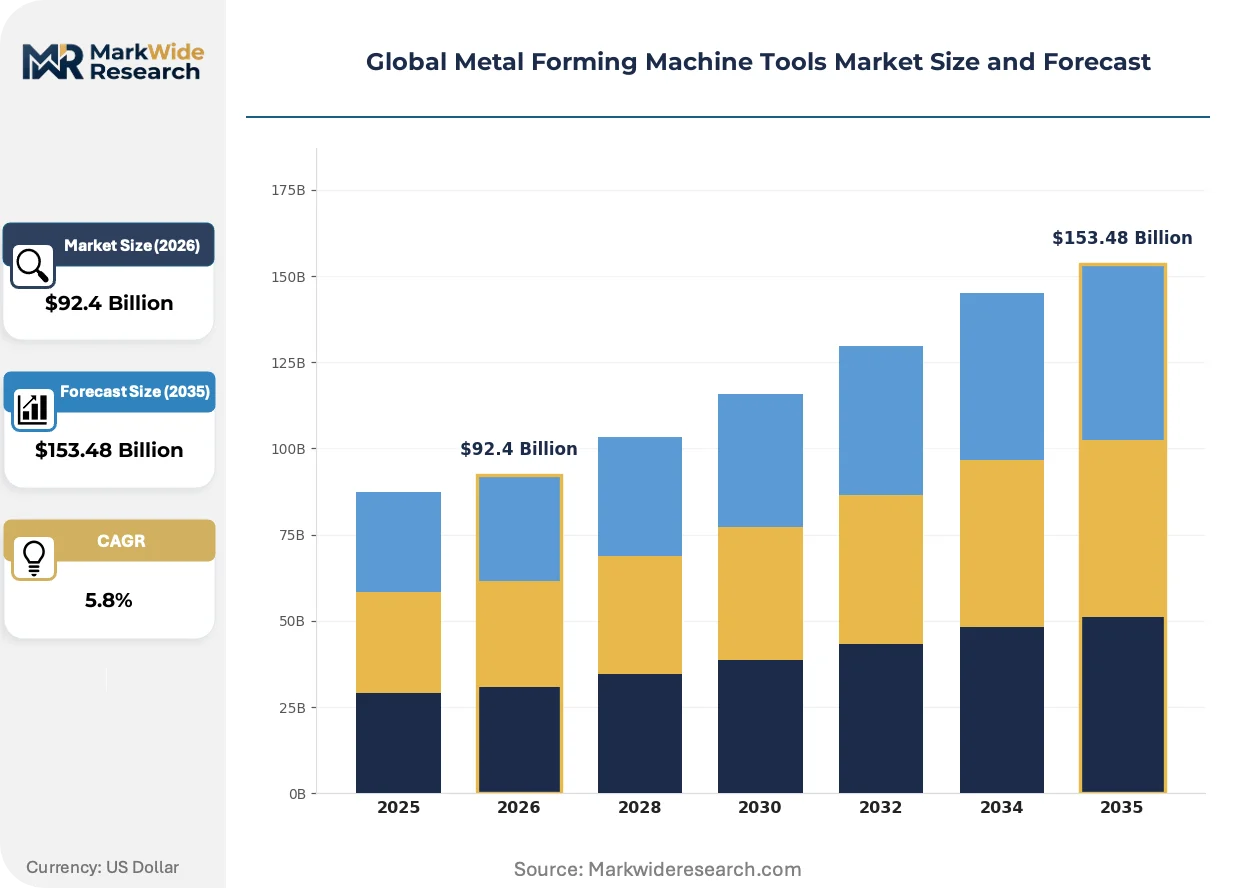
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
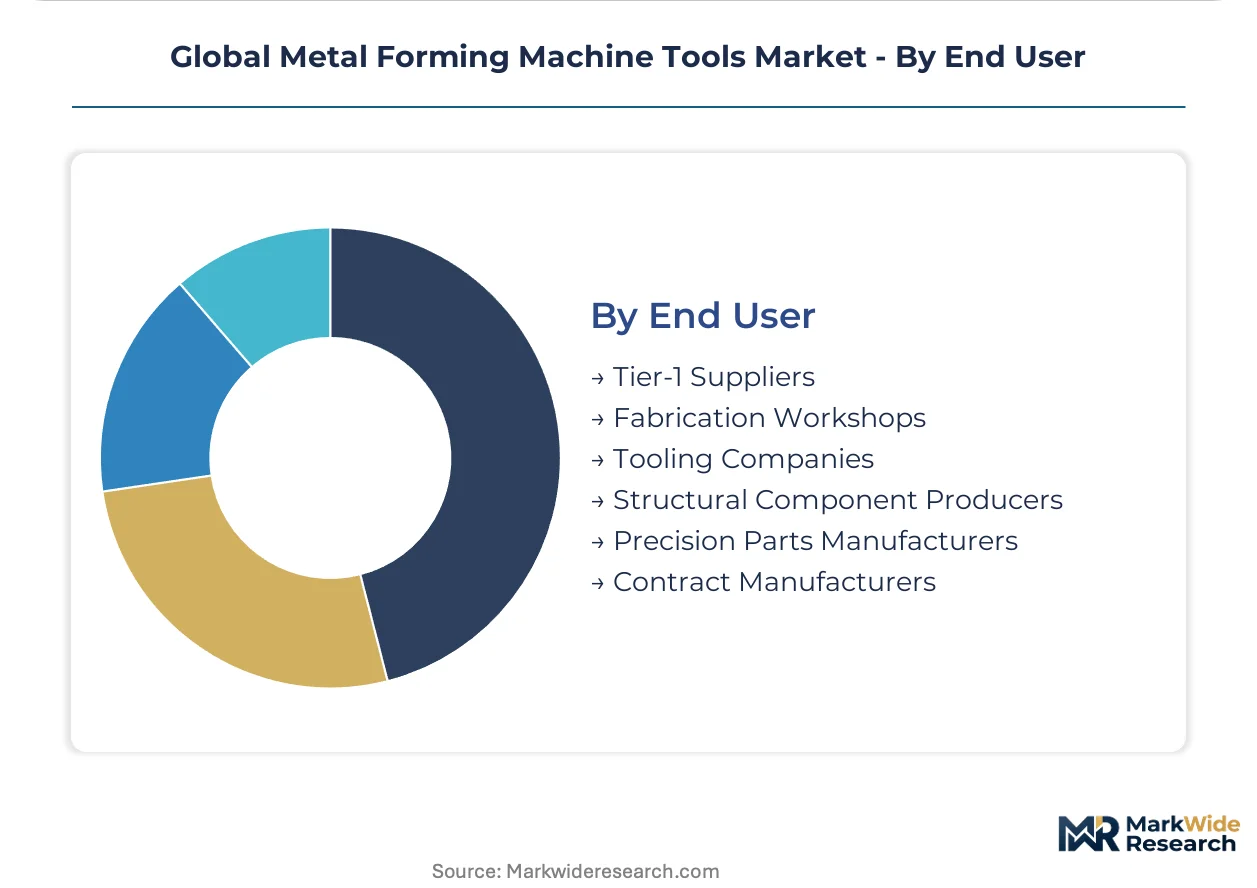
| Segmentation | Machine Type: Press Brakes, Hydraulic Presses, Mechanical Presses, Rolling Machines, Forging Presses, Others Technology: CNC Control, Hydraulic, Pneumatic, Mechanical, Servo Electric, Electromechanical Application: Automotive OEMs, Aerospace Fabrication, Shipbuilding Units, Electrical Equipment Manufacturers, Construction Firms, Heavy Equipment Makers End User: Tier-1 Suppliers, Fabrication Workshops, Tooling Companies, Structural Component Producers, Precision Parts Manufacturers, Contract Manufacturers |
| Companies Covered | TRUMPF Group, Amada Holdings Co., Ltd., Schuler AG, Fagor Arrasate, SMS Group GmbH, DMG Mori, AIDA Engineering, Ltd., Komatsu Industries Corp., Macrodyne Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Forming Machine Tools Market Shifts & Advancements
Digital thread integration and energy recovery systems are redefining equipment performance benchmarks. Forming operations now compete on kilowatt-hour per part metrics alongside traditional throughput measures.
Industrial IoT sensor arrays embedded in press frames are converging with cloud-based vibration analysis platforms. Tier-one automotive stampers in Stuttgart and Detroit deploy these systems to predict bearing failures 200-400 operating hours before catastrophic downtime. Real-time force monitoring is compressing preventive maintenance intervals from calendar-based to condition-based scheduling.
Japan's METI energy efficiency benchmarks now mandate regenerative braking systems on presses above 300 metric tons installed after 2024. Equipment suppliers must certify power consumption curves under standardized load profiles to qualify for domestic procurement programs. Korean and Taiwanese builders are adapting control architectures to meet these specifications for export competitiveness.
Outcome-based contracting is displacing traditional equipment purchase models among European aerospace subcontractors. Rolls-Royce and Safran suppliers now lease press capacity with guaranteed uptime clauses rather than owning depreciating assets. This shift concentrates risk with equipment financiers and OEM service organizations in Toulouse and Derby manufacturing corridors.
Global Metal Forming Machine Tools Market Segmentation
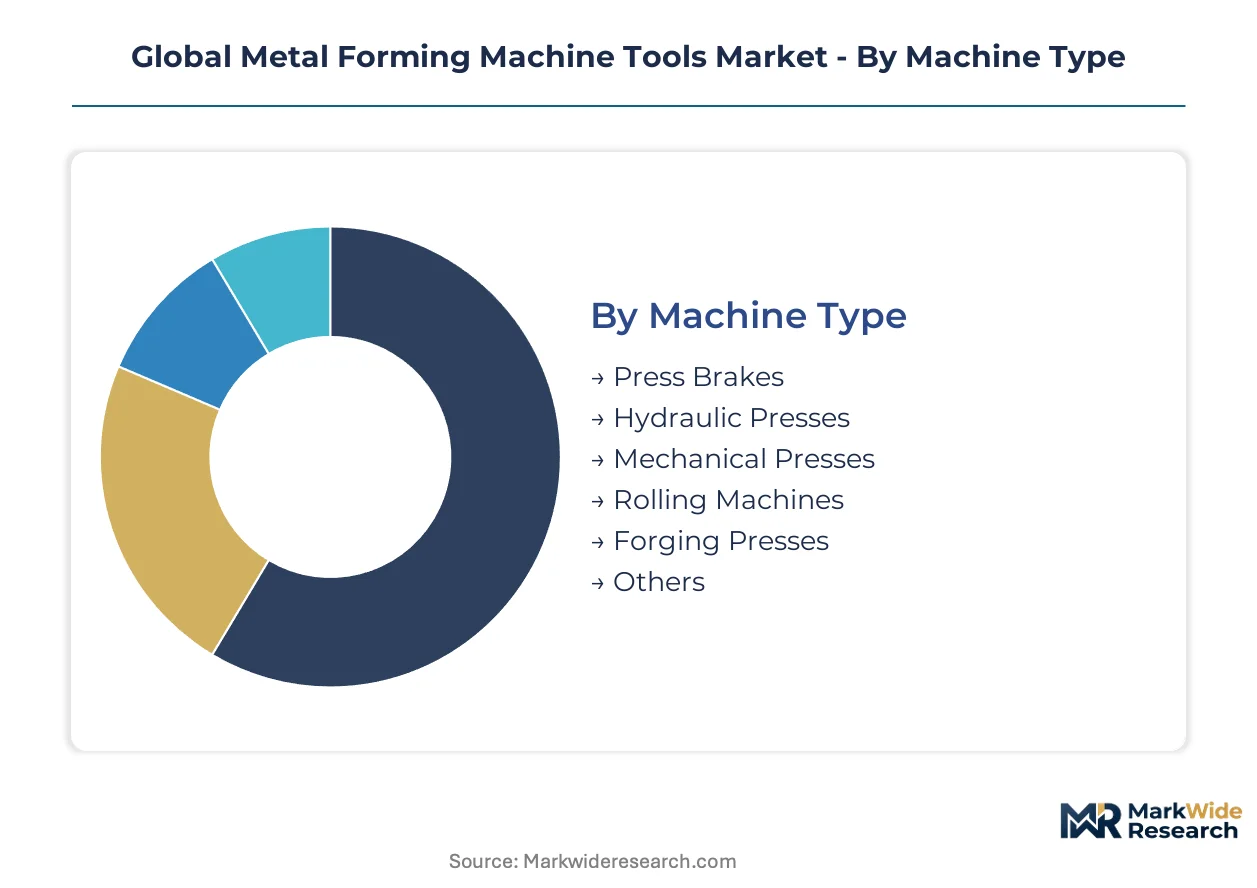
Equipment procurement patterns diverge sharply across machine types and control architectures, with certification requirements fragmenting supplier qualification pathways. Buyers prioritize segments offering the clearest compliance routes through overlapping machinery directives.
Machine Type:
CE marking under EU Machinery Directive and METI energy benchmarks in Japan impose divergent testing burdens across mechanical versus servo-electric architectures.
- Press Brakes:Electromechanical backgauge systems with programmable ram positioning dominate precision sheet metal fabrication. German and Italian OEMs specify these for automotive body-in-white operations requiring CE-certified safety interlocks.
- Hydraulic Presses:Fluid power systems delivering 200-2,000 metric tons for deep drawing and coining operations. China's MEE provincial audits are accelerating retirement of pre-2015 units in Jiangsu manufacturing clusters.
- Mechanical Presses:Flywheel-driven crank mechanisms for high-speed blanking remain prevalent in Mexican and Vietnamese stampers sourcing remanufactured equipment.
- Rolling Machines:Three-roll and four-roll configurations for plate forming in shipbuilding yards across South Korea and Japan.
- Forging Presses:Isothermal and hot forging systems for titanium aerospace components command premium pricing in Toulouse and Hamburg supply chains.
- Others:Specialized spinning, flow-forming, and incremental sheet forming equipment serving niche precision applications.
Leading the category by volume: Hydraulic Presses. Growing fastest: Press Brakes.
Technology:
Control system architectures determine energy recovery capabilities and programming complexity, with servo-electric platforms capturing margin pools from conventional hydraulic alternatives.
- CNC Control:Multi-axis programmable motion controllers enabling complex forming sequences with stored recipe management. Tier-one automotive stampers in Stuttgart and Detroit deploy these for predictive maintenance integration.
- Hydraulic:Proportional valve systems with variable displacement pumps face margin compression from regenerative servo alternatives.
- Pneumatic:Compressed air actuation for light-gauge forming and assembly press operations in electronics fabrication.
- Mechanical:Fixed-speed motor and clutch-brake combinations requiring substantial guarding upgrades for CE compliance.
- Servo Electric:Direct-drive ball screw and belt systems with regenerative braking capturing kinetic energy during deceleration cycles.
- Electromechanical:Hybrid architectures combining servo motors with mechanical advantage linkages for mid-tonnage applications.
Highest margin capture: Servo Electric. Steepest adoption trajectory: CNC Control.
Application:
End-use concentration determines equipment specification priorities, with automotive lightweighting programs pulling investment toward hot forming and aluminum-compatible press configurations.
- Automotive OEMs:In-house stamping operations for steel and aluminum body panels, with captive capacity expansion insulating supply chains from tier-one volatility.
- Aerospace Fabrication:Titanium and nickel superalloy forming for structural airframe components requiring isothermal press conditions.
- Shipbuilding Units:Heavy plate rolling and edge preparation equipment operating on mature replacement cycles.
- Electrical Equipment Manufacturers:Precision drawing and stamping for motor laminations, transformer cores, and switchgear housings.
- Construction Firms:Rebar processing and structural steel forming for commercial building frameworks.
- Heavy Equipment Makers:Large forging and welding preparation for mining and agricultural machinery chassis.
Dominant demand source: Automotive OEMs. Expanding most quickly: Aerospace Fabrication.
End User:
Customer scale and technical capability determine service contract structures, with outcome-based leasing gaining traction among European aerospace subcontractors lacking in-house maintenance expertise.
- Tier-1 Suppliers:High-volume stampers serving multiple OEM platforms with dedicated press lines and guaranteed capacity agreements.
- Fabrication Workshops:Job shops with mixed equipment portfolios serving construction and industrial machinery sectors on short lead times.
- Tooling Companies:Die and mold manufacturers requiring tryout presses for validation before production release.
- Structural Component Producers:Beam, channel, and angle formers for infrastructure and commercial building applications.
- Precision Parts Manufacturers:Medical device and electronics fabricators demanding micron-level repeatability from electromechanical systems.
- Contract Manufacturers:Electronics manufacturing services and white-label producers with flexible equipment requirements.
Largest installed base: Tier-1 Suppliers. Gaining share fastest: Precision Parts Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany, China, and the United States anchor equipment procurement volumes, with precision manufacturing clusters in Stuttgart, Shanghai, and Detroit driving specification standards for servo-electric press systems.
United States
Detroit-area stamping operations and Gulf Coast aerospace fabricators sustain demand for high-tonnage mechanical and servo-hydraulic presses. OSHA machinery guarding standards and EPA energy efficiency guidelines shape equipment certification requirements for domestic suppliers. The Southeast automotive corridor spanning Tennessee and South Carolina is attracting greenfield press installations as OEMs expand captive stamping capacity.
Germany
Stuttgart and Munich automotive clusters drive specification leadership for CE-certified servo-electric systems with integrated safety interlocks. The EU Machinery Directive mandates updated guarding protocols that are accelerating retirement of pre-2010 mechanical presses across Bavarian and Baden-Württemberg manufacturing zones. Hamburg aerospace subcontractors are piloting laser-hybrid forming equipment for titanium airframe components.
China
Jiangsu and Guangdong provincial manufacturing clusters face MEE energy efficiency audits that are forcing upgrades from conventional hydraulic to regenerative servo drive presses. SAMR GB standards and dual carbon goals under MIIT directives create compliance thresholds for domestic and imported equipment. Shanghai precision fabricators are expanding electromechanical press capacity for electric vehicle battery enclosure production.
Japan
Nagoya automotive suppliers and Osaka-area precision manufacturers sustain demand for METI-certified equipment with regenerative braking systems above 300 metric tons. METI energy efficiency benchmarks mandate standardized power consumption curves for domestic procurement eligibility. Chubu region press builders are adapting control architectures to capture export competitiveness in Korean and Taiwanese markets.
India
Pune and Chennai tier-two stampers qualify for PLI scheme capital subsidies when deploying 400+ metric ton presses for export-bound chassis components. BIS machinery safety codes and CEA electrical standards fragment compliance pathways for multinational suppliers entering the market. Gujarat automotive component corridors are attracting servo-electric press investments from Japanese and Korean equipment suppliers.
Global Metal Forming Machine Tools Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue servo-electric specialization and aftermarket service contracts. The vendor base stratifies across three tiers: multinational systems integrators with full product portfolios, regional specialists dominating single machine categories, and rebuilders capturing secondary market flows. Competitive dynamics center on technology licensing agreements and certified remanufacturing programs rather than pure price competition.
Within the multinational systems tier, Schuler AG and TRUMPF Group exemplify divergent strategic positioning—one anchoring large mechanical press systems for high-volume automotive platforms, the other leveraging laser-hybrid technologies for aerospace fabricators. Komatsu Industries Corp. represents the regional specialist archetype, with localized servo-electric production securing Asian supply chain positions. These three companies illustrate how geographic origin and technology focus determine competitive territory in fragmented procurement environments.
| Leading Market Players |
|---|
| TRUMPF Group |
| Amada Holdings Co., Ltd. |
| Schuler AG |
| Fagor Arrasate |
| SMS Group GmbH |
| DMG Mori |
| AIDA Engineering, Ltd. |
| Komatsu Industries Corp. |
| Macrodyne Technologies Inc. |
| Others |
Supply & Pricing Matrix
Tooling-grade tungsten and molybdenum from Kazakh and Russian mining operations feed through die manufacturers into three distinct pricing tiers for finished presses, with servo-electric systems commanding premiums over hydraulic alternatives while remanufactured mechanical units capture price-sensitive buyers in Mexico and Vietnam.
Pricing Analysis
Volume concentrates in hydraulic press transactions while margins pool in servo-electric and CNC-controlled electromechanical systems. Price differentiation hinges on CE certification tier and METI energy benchmark compliance, with uncertified pre-2010 mechanical presses facing steep depreciation. Cost compression in mid-tonnage hydraulic segments is intensifying because provincial MEE audits in China are accelerating factory upgrades. Tier-one automotive stampers in Stuttgart and Detroit exhibit lowest price sensitivity, while Mexican and Vietnamese job shops sourcing remanufactured equipment show highest elasticity.
Supply Chain Analysis
Refurbishment flows for mechanical presses from North American and European end-of-life assets into certified rebuild programs serving Mexican and Vietnamese metalworking SMEs illustrate reverse-logistics maturity. Precision motion controllers from Germany and Japan, combined with specialty steel alloys from Kazakhstan and Russia, anchor upstream dependencies. Distribution runs through OEM-direct channels for large automotive platforms and regional distributors for job shop segments. Single-source vulnerability in control system supply creates exposure for Asian press builders lacking domestic alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around servo-electric technology specialists as energy efficiency directives from METI, MEE, and EU Machinery Directive force hydraulic-dependent players into expensive retooling or exit.
For Market Incumbents: Extend service contract coverage into predictive maintenance platforms to capture recurring revenue from Rolls-Royce and Safran suppliers adopting outcome-based leasing models. Deepen backward integration into servo motor and regenerative drive production to reduce 14-22 week controller lead time exposure from German and Japanese suppliers. Secure CE certification pathways for legacy mechanical press retrofits to capture replacement demand from Bavarian and Baden-Württemberg manufacturing zones. For New Entrants and Emerging Players: Begin with certified remanufacturing programs for mechanical presses serving price-sensitive Mexican and Vietnamese SMEs, where secondary market consolidation creates white-space. Target India's PLI scheme corridors in Pune and Chennai for 400+ metric ton servo-electric deployments qualifying for capital equipment subsidies. Build go-to-market partnerships with Japanese and Korean equipment suppliers establishing Gujarat automotive component corridors. For Investors and Strategic Acquirers: METI's 2024 regenerative braking mandate for presses above 300 metric tons is the leading indicator that control architecture capabilities will determine acquisition premiums over the next decade. Target regional servo-electric specialists with localized production in Jiangsu and Guangdong manufacturing clusters. Monitor provincial MEE audit enforcement intensity as the signal for acceleration in China's factory upgrade cycle.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Licensing | Enables Asian press builders to meet METI energy benchmarks for export competitiveness. |
| Certified Remanufacturing Program | Captures secondary market flows from retiring North American and European mechanical assets. |
| Backward Integration into Control Systems | Reduces lead time exposure from German and Japanese precision motion controller suppliers. |
| Outcome-Based Service Contract | Aligns with Rolls-Royce and Safran supplier leasing models in Toulouse and Derby corridors. |
| PLI Scheme Corridor Investment | Qualifies tier-two stampers in Pune and Chennai for capital equipment subsidies on high-tonnage presses. |
Research Methodology
Document review covered customs and trade data from Jiangsu and Guangdong manufacturing clusters, METI energy efficiency benchmark filings, and EU Machinery Directive CE marking registries, complemented by interviews with maintenance directors at Stuttgart and Detroit automotive stampers, aftermarket service heads at Hamburg aerospace subcontractors, and plant engineers at Osaka-area precision manufacturers. Secondary validation drew from SEC 10-K disclosures of listed equipment suppliers, SAMR GB standard publications, and provincial MEE audit reports. Bottom-up equipment shipment data triangulated against top-down automotive production forecasts and aerospace fabrication capacity expansion announcements.
Segment-level projections across machine type, technology architecture, and end-use application were generated through the analysis window using multivariate regression against automotive lightweighting program announcements, provincial energy audit enforcement timelines, and PLI scheme disbursement patterns. CAGRs were derived from slope analysis of replacement cycle acceleration in pre-2010 mechanical press retirements and servo-electric adoption curves in German and Japanese procurement data. Industry-specific inputs included hot forming press specifications for aluminum-intensive vehicle platforms and laser-hybrid forming pilot timelines at Toulouse and Hamburg aerospace fabricators.
Raw material price volatility in Kazakh and Russian tungsten and molybdenum supply, control system import restriction escalations, and vocational training program output shortfalls in North American and Western European markets are the dominant revision risks to equipment demand forecasts. Practitioners should monitor provincial MEE audit intensity, METI benchmark update schedules, and PLI scheme eligibility modifications for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Bandsaw Machines Market
Tools
Mechanical Puller Market
Tools
Foam Engraving Machines Market
Tools
Mechanical Hand Tools Market
Tools
Portable Heat Press Machine Market
Tools
Yard Scraper Market
Tools
Europe Paint Spray Guns Market
Tools
Surface Planer Market
Tools
Pneumatic Marking Machines Market
Tools
Nail Gun Market
Tools
Paint Spray Guns Market
Tools
US Hitter Based Hand Tools Market
Tools
Cold and Hot Tool Steel Market
Tools
Cutting Tools Market
Tools
Post Drivers Market
Tools
Hand Saw Market