
 Elevator Ropes Market | 2026-2036
Elevator Ropes Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Ropes Market Analysis
A capital-intensity divergence between integrated steel producers and specialized wire rope manufacturers is rotating competitive advantage toward entities controlling upstream metallurgy. Bekaert leverages its in-house wire-drawing capabilities to secure premium-grade supply for high-rise applications. WireCo WorldGroup anchors its position through broad geographic manufacturing footprints across multiple continents. Gustav Wolf GmbH specializes in coated rope designs that command higher specification thresholds in European installations.
Elevator ropes are high-strength flexible cables, typically constructed from multiple strands of galvanized or stainless steel wire wound around a fiber or steel core, engineered to suspend and move elevator cars within hoistways at loads exceeding their rated breaking strength. Steel wire ropes dominate installed base volumes due to proven fatigue resistance under cyclic bending over sheave systems. Multi-strand designs lead product design categories for their balance of flexibility and load distribution in high-traffic commercial buildings. Synthetic fiber segments represent the fastest-growing material category as building operators seek reduced dead weight and extended service intervals in specialty elevator applications.
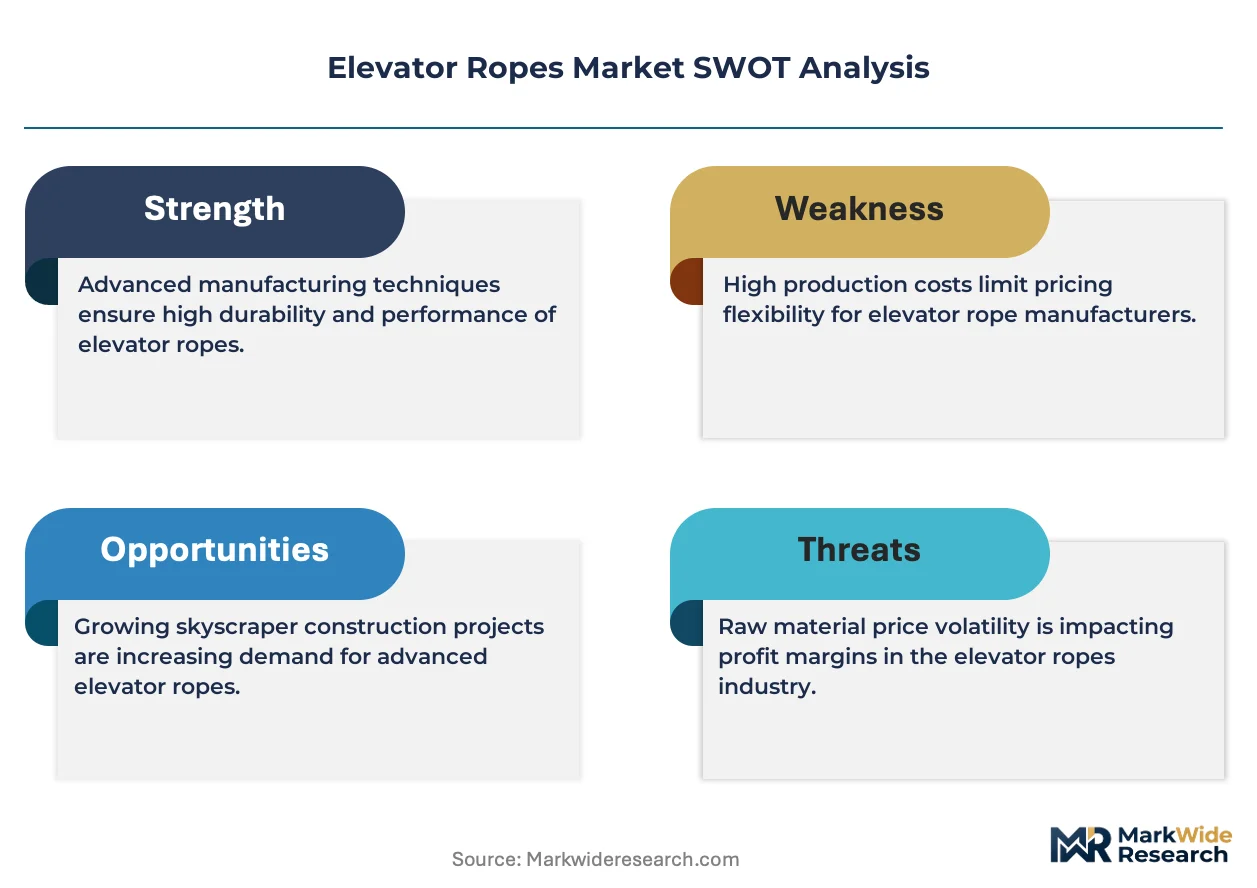
Regulators including China's SAMR with GB standards, the European Union through CE marking under the Machinery Directive, and the US OSHA elevator safety requirements collectively enforce minimum breaking strength, wear inspection intervals, and replacement criteria that directly shape procurement specifications. These frameworks elevate compliance costs for non-certified suppliers while creating protected demand channels for accredited manufacturers. Stakeholders must monitor evolving certification thresholds for synthetic and composite alternatives as code bodies evaluate performance equivalence against traditional steel benchmarks.
Market Dynamics
China's GB standards for elevator safety are tightening material certification requirements, rotating procurement power toward accredited suppliers with captive metallurgy capabilities while compressing margins for non-certified manufacturers.
Growth Catalysts
- High-rise residential construction:Vertical density acceleration across China's tier-one cities is generating concentrated demand for fatigue-resistant multi-strand rope designs rated for high-traffic commercial installations.
- SAMR certification mandates:China's State Administration for Market Regulation is elevating compliance thresholds that protect demand channels for suppliers meeting breaking strength and wear inspection protocols.
- Synthetic fiber innovation:Building operators in specialty elevator applications are specifying reduced dead weight alternatives to extend service intervals and lower maintenance burdens.
Market Restraints
- Steel wire price volatility:Galvanized and stainless steel input costs fluctuate with global metallurgy markets, compressing margin predictability for rope manufacturers without upstream control.
- Supply concentration in tier-one clusters:Demand gravity centers on Shanghai, Beijing, and Shenzhen, creating geographic dependency risk for producers lacking diversified regional footprints.
- Technical limitation in synthetic equivalence:Fiber core alternatives have not achieved full performance parity with steel wire under cyclic bending over sheave systems in high-load applications.
Strategic Opportunities
- Coated rope specialization:European specification thresholds for corrosion-resistant designs command premium positioning for manufacturers with advanced polymer application capabilities.
- Asia-Pacific high-rise pipeline:Residential tower construction in Mumbai, Jakarta, and Ho Chi Minh City represents underpenetrated volume for suppliers with GB-compliant certification.
- OSHA alignment potential:US elevator safety requirements create a pathway for certified manufacturers to access North American retrofit and replacement cycles.
Industry Challenges
- Metallurgy talent scarcity:Wire-drawing precision engineering expertise concentrates within legacy steel producers, constraining expansion for specialized rope manufacturers.
- Dual certification timelines:Parallel GB and CE marking compliance processes extend product launch cycles and elevate administrative overhead for multi-market suppliers.
- Legacy hoistway integration:Existing elevator infrastructure specifications limit rapid substitution of synthetic alternatives without sheave system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Ropes Market |
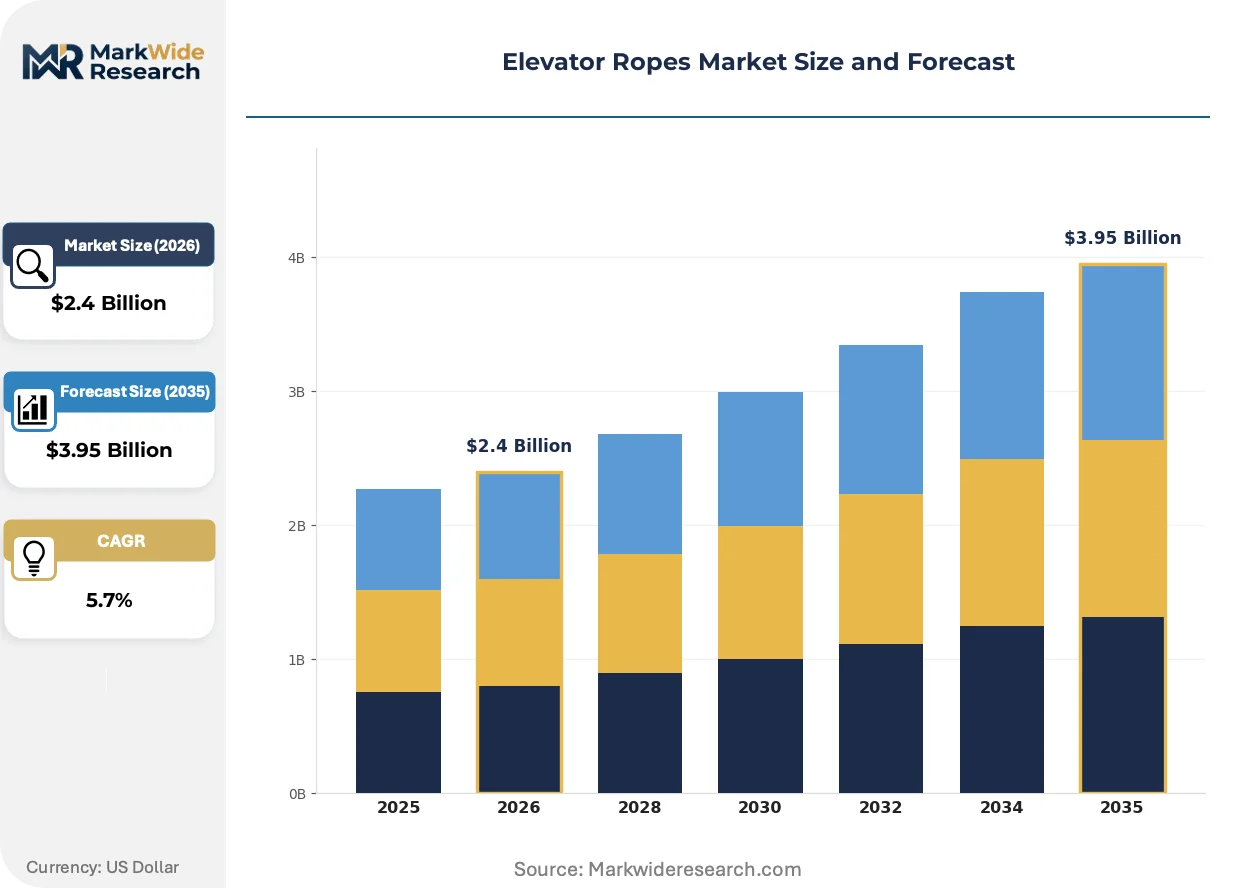
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel Wire, Synthetic Fiber, Composite, Others Application: Residential Buildings, Commercial Buildings, Industrial Elevators, Specialty Elevators Product Design: Single-Wire, Multi-Strand, Braided, Coated End User: Construction Companies, Elevator Manufacturers, Maintenance Service Providers, Facility Managers |
| Companies Covered | Tokyo Rope International, Brugg Group, WireCo WorldGroup, Bekaert, KISWIRE, Usha Martin Limited, Kobe Steel, ArcelorMittal, Gustav Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Ropes Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing traditional competitive advantages while elevating specification complexity across installation categories.
Aramid and carbon fiber composite rope constructions are displacing conventional steel wire in specialty low-rise and machine-room-less elevator installations. Boutique hotel chains and healthcare facility operators are piloting these alternatives to reduce structural load requirements. The technology is displacing established procurement patterns by enabling architects to specify lighter hoistway designs that reduce building core steel requirements.
REACH substance restrictions and the EU Machinery Directive's evolving CE marking protocols are elevating documentation burdens for coated rope suppliers serving European installations. Manufacturers must now certify polymer coating compositions against SVHC candidate lists before market entry. The regulatory pressure is compressing product development timelines while favoring incumbents with established chemical compliance infrastructure.
Building operators are unbundling rope replacement from full-service maintenance contracts, creating direct procurement relationships with certified manufacturers. Facility management firms in Germany and the Netherlands are leading this disintermediation, negotiating specification-grade purchases independent of OEM service agreements. The behavioral shift is most visible in commercial real estate portfolios where lifecycle cost modeling has displaced brand-loyal procurement practices.
Elevator Ropes Market Segmentation
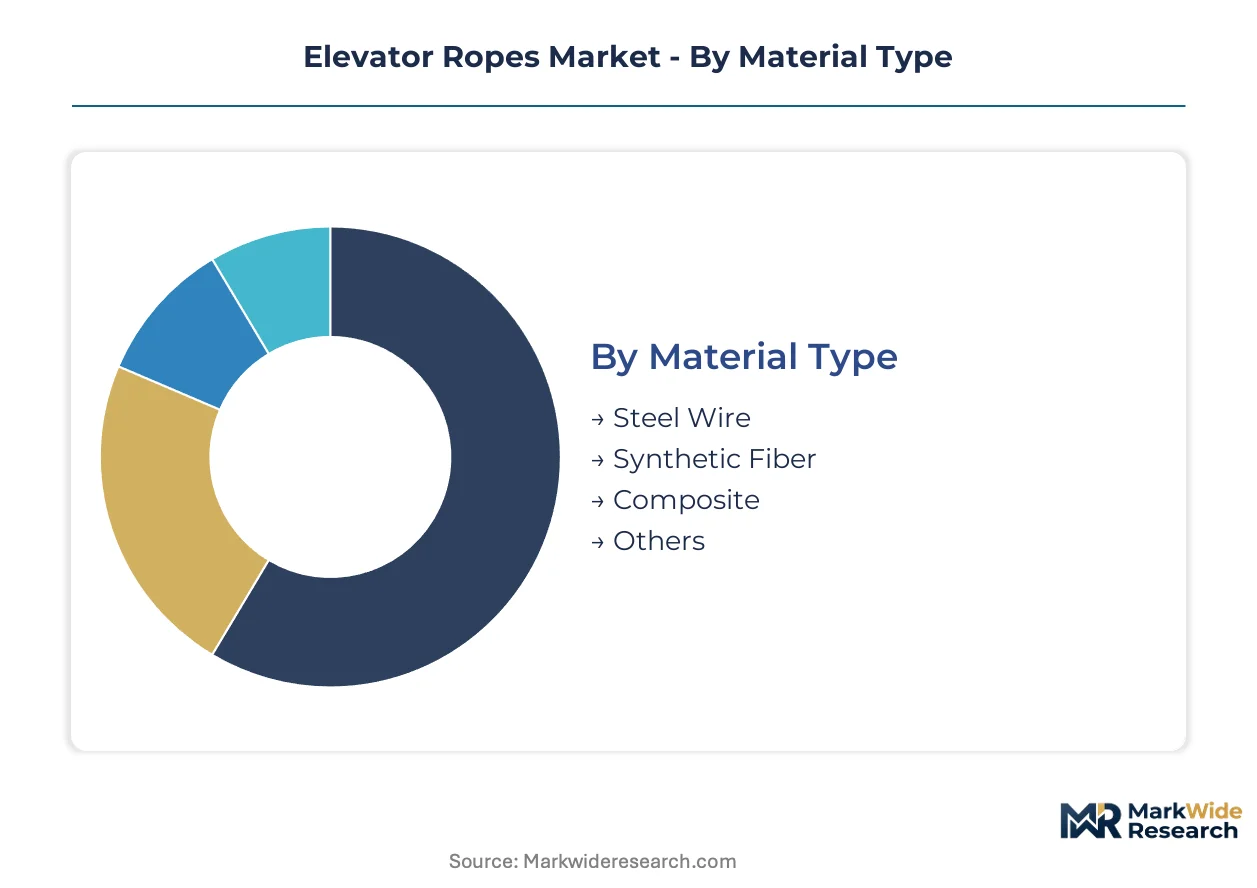
Segmentation in elevator ropes determines procurement channel access and specification complexity. Material composition dictates certification pathways, while end-user type shapes pricing power and contract structure.
Material Type:
Channel flow splits between OEM-integrated supply for steel wire and direct procurement for synthetic alternatives, with composite materials moving through specialized distributors serving retrofit applications.
- Steel Wire:Galvanized and stainless steel constructions deliver proven fatigue resistance under cyclic bending over sheave systems. Demand concentrates in Shanghai, Beijing, and Shenzhen high-rise residential towers where SAMR certification mandates protect accredited suppliers with captive metallurgy capabilities.
- Synthetic Fiber:Aramid and carbon fiber composites reduce dead weight and extend service intervals in specialty installations. Building operators in boutique hospitality and healthcare facilities specify these alternatives to enable lighter hoistway designs that cut structural steel requirements.
- Composite:Hybrid steel-fiber constructions balance load capacity with weight reduction for mid-rise commercial retrofits.
- Others:Experimental polymer-core designs remain limited to pilot installations pending full GB standard equivalency certification.
By volume, Steel Wire leads. By growth pace, Synthetic Fiber is ahead.
Application:
Cost tiering separates specification-grade commercial installations from price-sensitive residential projects, with industrial and specialty applications commanding premium margins through custom engineering.
- Residential Buildings:High-rise tower construction across China's tier-one cities generates concentrated demand for multi-strand designs rated for high-traffic duty cycles. Vertical density acceleration in Mumbai, Jakarta, and Ho Chi Minh City creates underpenetrated volume for GB-compliant suppliers.
- Commercial Buildings:Skyscraper installations require fatigue-resistant ropes with documented wear inspection protocols under EU Machinery Directive CE marking and OSHA elevator safety requirements. Facility management firms in Germany and the Netherlands are disintermediating procurement through direct manufacturer relationships.
- Industrial Elevators:Heavy-load freight applications prioritize breaking strength margins over flexibility specifications.
- Specialty Elevators:Machine-room-less and scenic lift designs drive adoption of coated and braided configurations.
Commercial Buildings capture the highest per-unit value. Residential Buildings dominate unit volume.
Product Design:
Margin distribution favors coated and braided variants in European markets, while multi-strand configurations anchor volume production for Asia-Pacific high-rise deployment.
- Multi-Strand:Multiple wire layers wound around fiber or steel cores balance flexibility with load distribution for high-traffic commercial buildings. This design category leads installed base volumes due to proven performance over sheave systems in cyclic bending applications.
- Coated:Polymer-applied surfaces command premium positioning in European installations where REACH substance restrictions and evolving CE marking protocols elevate documentation burdens. Manufacturers must certify coating compositions against SVHC candidate lists before market entry.
- Single-Wire:Basic configurations serve low-rise residential replacement cycles with minimal specification overhead.
- Braided:Interwoven strand architectures deliver enhanced stability for specialty elevator applications.
Multi-Strand holds the volume base. Coated ropes deliver the steepest margin expansion.
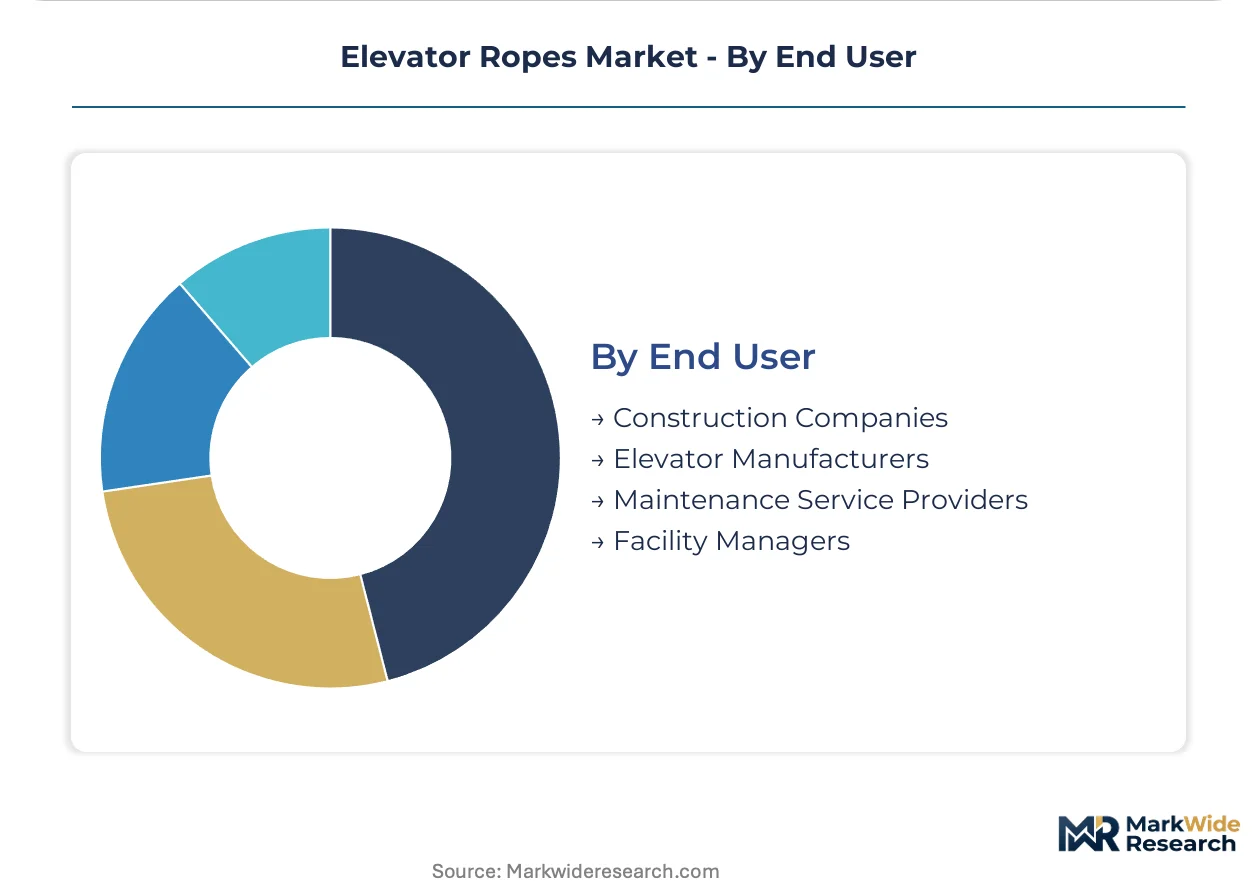
End User:
Customer type determines contract structure, with elevator manufacturers locking in multi-year supply agreements while facility managers drive spot-market disintermediation in mature European markets.
- Elevator Manufacturers:OEMs anchor demand through integrated supply chains, with Bekaert and WireCo WorldGroup securing long-term agreements via in-house wire-drawing capabilities and continental manufacturing footprints. These relationships rotate procurement power toward entities controlling upstream metallurgy.
- Facility Managers:Commercial real estate portfolio operators in Germany and the Netherlands are unbundling rope replacement from full-service maintenance contracts, negotiating specification-grade purchases independent of OEM agreements based on lifecycle cost modeling.
- Construction Companies:Project-based procurement concentrates in China's tier-one city clusters with compressed margin predictability.
- Maintenance Service Providers:Replacement cycle demand flows through certified distributor networks with SAMR and CE marking compliance requirements.
Elevator Manufacturers control new installation volume. Facility Managers are gaining share fastest in replacement procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European specification-grade markets while Chinese volume markets compress margins through certification mandates and supply concentration. German and Dutch facility managers command premium positioning through direct procurement relationships. China's tier-one cities rotate procurement power toward accredited suppliers with captive metallurgy capabilities.
China
Shanghai, Beijing, and Shenzhen generate concentrated demand for fatigue-resistant multi-strand rope designs in high-rise residential towers. SAMR certification mandates under tightening GB standards protect demand channels for accredited suppliers while compressing margins for non-certified manufacturers. Vertical density acceleration across these tier-one clusters creates geographic dependency risk for producers lacking diversified regional footprints.
Germany
Commercial real estate portfolio operators in Frankfurt and Munich are unbundling rope replacement from full-service maintenance contracts. REACH substance restrictions and evolving EU Machinery Directive CE marking protocols elevate documentation burdens for coated rope suppliers. Facility management firms negotiate specification-grade purchases independent of OEM agreements based on lifecycle cost modeling.
United States
OSHA elevator safety requirements create a pathway for certified manufacturers to access North American retrofit and replacement cycles. Building operators in Chicago and New York specify reduced dead weight alternatives to extend service intervals. The regulatory framework enforces minimum breaking strength and wear inspection intervals that directly shape procurement specifications.
Japan
Machine-room-less elevator installations in Tokyo and Osaka drive adoption of coated and braided configurations. METI standards and JIS certification requirements elevate compliance costs for non-certified suppliers. Boutique hospitality and healthcare facility operators pilot aramid and carbon fiber composite constructions to reduce structural load requirements.
India
Residential tower construction in Mumbai generates underpenetrated volume for GB-compliant suppliers with fatigue-resistant designs. BIS standards for elevator safety are tightening material certification requirements as vertical density accelerates. Project-based procurement concentrates in Maharashtra and Gujarat with compressed margin predictability for non-integrated manufacturers.
Elevator Ropes Market Vendor Landscape
Concentration sits with integrated steel producers and specialized wire rope manufacturers rotating competitive advantage toward entities controlling upstream metallurgy. The vendor base spans legacy European specialists, Asian volume producers, and diversified industrial conglomerates with captive wire-drawing capabilities. Three archetypes dominate: metallurgy-integrated conglomerates, geographic footprint specialists, and coated-rope specification leaders. Capacity expansion and strategic partnerships represent the dominant competitive moves as players seek GB and CE marking compliance across parallel certification timelines.
Within the metallurgy-integrated tier, Bekaert and ArcelorMittal occupy positions anchored by in-house wire-drawing capabilities and continental manufacturing footprints. WireCo WorldGroup exemplifies the geographic footprint specialist archetype through broad manufacturing distribution across multiple continents. Gustav Wolf GmbH represents the coated-rope specification leader archetype, with its German corporate structure signaling advanced polymer application capabilities for European installations. These three entities collectively illustrate how competitive positioning rotates toward upstream metallurgy control and certification infrastructure.
| Leading Market Players |
|---|
| Tokyo Rope International |
| Brugg Group |
| WireCo WorldGroup |
| Bekaert |
| KISWIRE |
| Usha Martin Limited |
| Kobe Steel |
| ArcelorMittal |
| Gustav Wolf GmbH |
| Others |
Supply Flow & Price Mechanics
Ninety-day raw material inventory buffers at integrated steel producers create asymmetric pricing power against specialized rope manufacturers lacking upstream metallurgy control. This inventory asymmetry concentrates margin capture within entities controlling wire-drawing capabilities while compressing returns for distributors dependent on spot-market galvanized steel purchases.
Pricing Analysis
The customization-premium spread between configured-to-order coated ropes and standard multi-strand configurations spans three certification tiers. Pricing stratifies across SAMR-accredited premium grades, CE-marked standard specifications, and economy-grade non-certified alternatives. Cost compression in the economy tier is intensifying because Chinese tier-one city procurement mandates are disqualifying uncertified suppliers. Elevator manufacturers exhibit lowest price sensitivity due to long-term OEM agreements, while construction companies in India's project-based channel demonstrate highest sensitivity to spot steel fluctuations.
Supply Chain Analysis
Strategic stockpile preferences dominate among integrated producers in Belgium, Japan, and South Korea, while just-in-time inventory governs specialized rope assemblers in Germany and Italy. Raw material dependencies draw from high-carbon wire rod, zinc for galvanization, and aramid fiber feedstock. Single-source vulnerability concentrates in Chinese wire rod supply serving Asia-Pacific demand clusters. Distribution runs through OEM-integrated channels for steel wire volumes and specialized distributors for synthetic retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elevator ropes market sits in a cyclical recovery anchored to high-rise residential construction pipelines across Asia-Pacific urban density clusters.
For Market Incumbents: Shield certified supply relationships by deepening captive metallurgy investments before SAMR tightens GB standard equivalency thresholds. Prioritize dual GB-CE marking compliance infrastructure to compress product launch cycles against competitors facing parallel certification delays. Channel control through direct facility management relationships in Germany and the Netherlands defends margin position against OEM disintermediation. For New Entrants and Emerging Players: Post-installation monitoring and predictive maintenance analytics represent an underserved service layer where incumbents under-serve. Target India's Mumbai residential tower pipeline with fatigue-resistant multi-strand designs certified to BIS standards ahead of vertical density acceleration. A specification-grade direct procurement partnership with European facility management firms offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because metallurgy-integrated mid-caps with captive wire-drawing capabilities command scarcity premiums in a certification-constrained environment. Acquisition targets should exhibit established chemical compliance infrastructure for REACH-coated rope segments and SAMR-accredited Chinese manufacturing presence. Watch synthetic fiber performance equivalence certification against traditional steel benchmarks as the inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Production | Captive metallurgy secures margin capture against galvanized steel price volatility. |
| Dual Certification Infrastructure Investment | Parallel GB and CE marking compliance compresses product launch cycles for multi-market suppliers. |
| Coated Rope Polymer Application Scale-Up | Advanced coating capabilities command REACH-compliant premium positioning in European installations. |
| Synthetic Fiber R&D Partnership | Aramid and carbon fiber composite development targets machine-room-less elevator substitution opportunities. |
| Direct Facility Management Channel Development | Disintermediated procurement relationships in Germany and the Netherlands bypass OEM service agreements. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with elevator OEM procurement directors, steel wire plant managers, and facility management executives across China, Germany, and the United States; and secondary validation through SAMR certification registries, EU Machinery Directive CE marking databases, and customs trade flows for high-carbon wire rod. Bottom-up volume estimates from installation counts and top-down value triangulation from manufacturer revenue disclosures were cross-referenced to constrain forecast variance.
Across the analysis window, projections were modeled by material type, application segment, product design configuration, and end-user channel structure. CAGRs were derived from regression-weighted historical growth patterns and forward-looking construction pipeline data. Industry-specific inputs included high-rise residential permit approvals in Chinese tier-one cities and European commercial real estate maintenance contract unbundling rates.
Forecasts assume regulatory continuity in China's SAMR certification regimes and the EU Machinery Directive; material policy shifts would require re-modeling. Synthetic fiber equivalency certification delays or abrupt steel price dislocations represent specific revision triggers. Revision becomes warranted when synthetic rope performance parity under cyclic bending achieves formal GB standard recognition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market