
 Angular Rubber Expansion Joints Market | 2026-2036
Angular Rubber Expansion Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Angular Rubber Expansion Joints Market Insights
EPA Lead and Copper Rule revisions are realigning the cost-of-entry calculus for suppliers serving North American municipal water infrastructure. Elaflex leverages its European manufacturing footprint to sustain export competitiveness across EPDM and chloroprene product lines. ContiTech AG anchors its position through deep integration with Continental AG's polymer research capabilities. Garlock Sealing Technologies differentiates via specialized high-temperature compounds for power generation clients.
Angular rubber expansion joints are flexible elastomeric connectors manufactured with molded or hand-built rubber bodies reinforced with textile or metallic cord, designed to absorb angular deflection, thermal expansion, and mechanical vibration in pressurized piping systems. EPDM compounds dominate water treatment and HVAC applications due to ozone resistance and potable water certifications, while nitrile variants lead in petrochemical and chemical manufacturing where hydrocarbon exposure is prevalent. The large diameter and custom fabricated size segment captures disproportionate margin pools given engineering-intensive specification work and lower price transparency.
FDA regulations govern food processing installations, EPA standards dictate potable water system materials, and EU REACH compliance shapes export eligibility for European and Asian manufacturers serving continental markets. The EU F-Gas Regulation indirectly pressures HVAC system redesigns, expanding specification opportunities for vibration-absorbing angular joints in refrigerant piping retrofits. Stakeholders must monitor evolving PFAS restrictions and their downstream impact on fluoroelastomer alternatives and substitution timelines across critical end-use certifications.
Market Dynamics
Refinery turnaround cycles and pipeline integrity mandates across the Gulf Coast petrochemical corridor are sustaining replacement volumes while tightening EPA drinking water standards force municipal procurement toward certified EPDM compounds.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal water utilities in the United States are accelerating specification of potable water-certified angular joints to comply with tightened infrastructure standards.
- EU F-Gas Regulation pressure:HVAC system redesigns across Germany and France are expanding specification opportunities for vibration-absorbing joints in refrigerant piping retrofits.
- Petrochemical corridor maintenance cycles:Refinery turnaround schedules along the Texas and Louisiana Gulf Coast sustain replacement demand for chloroprene and nitrile variants.
Market Restraints
- Raw material volatility:Natural rubber and synthetic elastomer feedstock prices fluctuate with crude oil indices, compressing margin predictability for molded joint fabricators.
- REACH compliance costs:European manufacturers face elevated testing and documentation burdens for chemical substance registration, disadvantaging smaller fabricators against integrated polymer producers.
- Fluoroelastomer substitution timelines:Evolving PFAS restrictions in the United States and European Union create uncertainty around high-performance sealant alternatives and certification continuity.
Strategic Opportunities
- India water infrastructure buildout:Central government Jal Jeevan Mission allocations are expanding municipal pipeline networks requiring potable water-certified expansion joints.
- Digital specification platforms:Engineering-procurement-construction firms are migrating joint selection to cloud-based piping specification tools, creating channel access for certified suppliers.
- Green hydrogen transport systems:Emerging hydrogen pipeline networks in Germany and the Netherlands require specialized elastomer compounds resistant to hydrogen embrittlement and permeation.
Industry Challenges
- Compound formulation expertise scarcity:Specialized knowledge of textile cord reinforcement patterns and molded rubber cure chemistry is concentrating among retiring technical workforces.
- Multi-certification coordination:Suppliers must simultaneously maintain FDA food contact, EPA potable water, and EU REACH compliance across overlapping but non-harmonized testing protocols.
- Legacy system integration:Custom-fabricated large-diameter joints must interface with decades-old cast iron and carbon steel piping infrastructure with non-standard flange dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angular Rubber Expansion Joints Market |
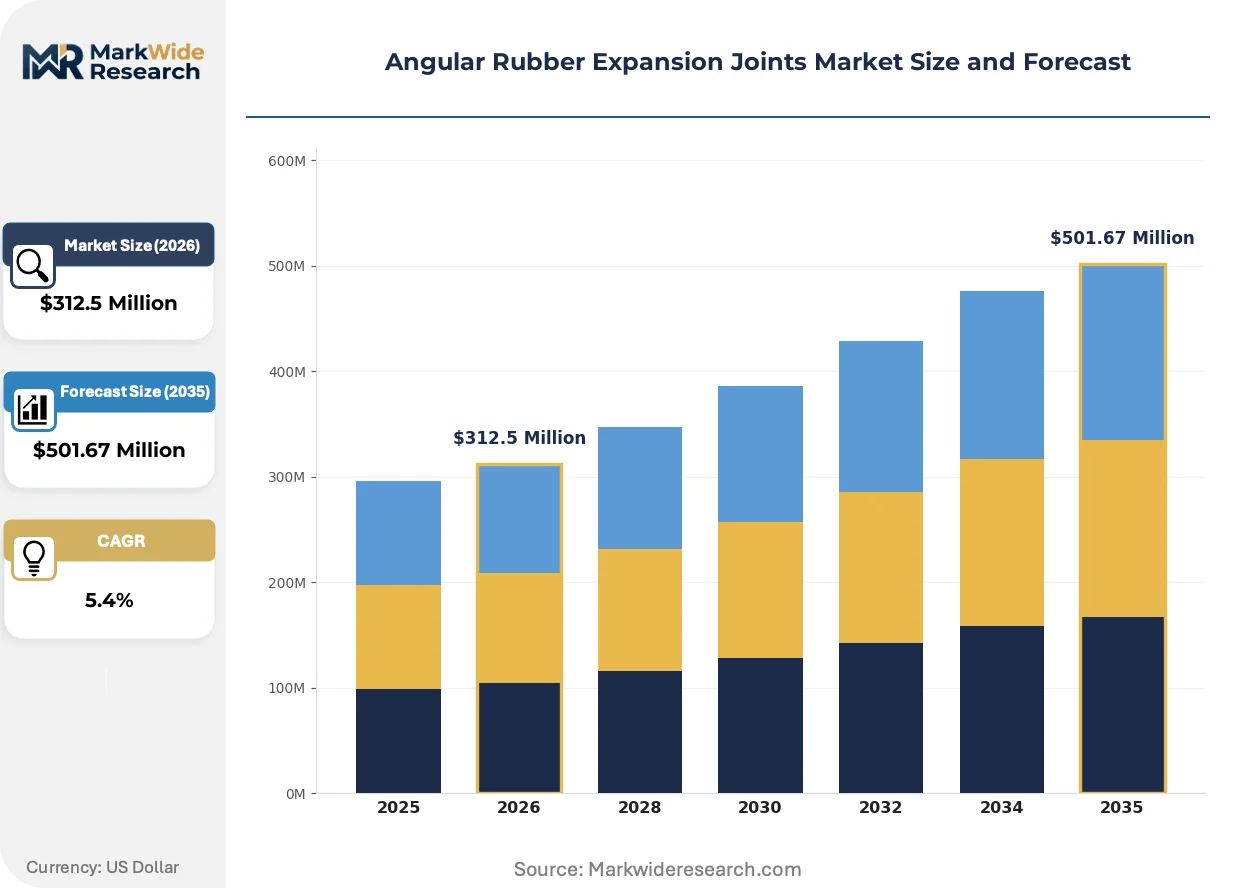
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Neoprene, EPDM, Nitrile, Silicone, Butyl, Chloroprene End Use Industry: Water Treatment, Petrochemical Plants, Power Generation, Shipbuilding, Food Processing, Chemical Manufacturing Application: Piping Systems, HVAC Systems, Pressure Relief, Vibration Absorption, Shock Resistance, Pipeline Protection Size: Small Diameter, Medium Diameter, Large Diameter, Custom Fabricated |
| Companies Covered | Elaflex, HKS Group, ContiTech AG, Politeknik, Kadant, Flexicraft Industries, Garlock Sealing Technologies, HOLZ Rubber Company, Belman A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angular Rubber Expansion Joints Market Trends and Innovations
Specification workflows are digitizing while material science advances and regulatory pressure on fluorinated compounds are forcing compound innovation. These shifts are compressing product development cycles and redrawing competitive boundaries.
Multi-layer EPDM-chloroprene hybrid compounds are modularizing to address simultaneous chemical resistance and ozone durability requirements in coastal industrial environments. Water treatment utilities in Florida and chemical processors in Rotterdam are specifying these configurations for 20-year service life guarantees. The technology is modularizing procurement decisions by allowing standardized body designs with interchangeable liner materials.
EU REACH SVHC candidate list expansion is accelerating substitution research for conventional plasticizers and cure accelerators in molded rubber bodies. German manufacturers face mandatory supply chain disclosure requirements for substances of very high concern. Food processing installations across France and dairy operations in the Netherlands are prioritizing suppliers with pre-validated REACH-compliant compound portfolios.
Engineering-procurement-construction firms are consolidating vendor pools through framework agreements that bundle angular joints with adjacent piping components. This behavior concentrates specification authority with integrated MRO distributors and away from specialized rubber fabricators. The shift is most visible in United States municipal water infrastructure projects where design-build contracts dominate procurement methodology.
Angular Rubber Expansion Joints Market Segmentation
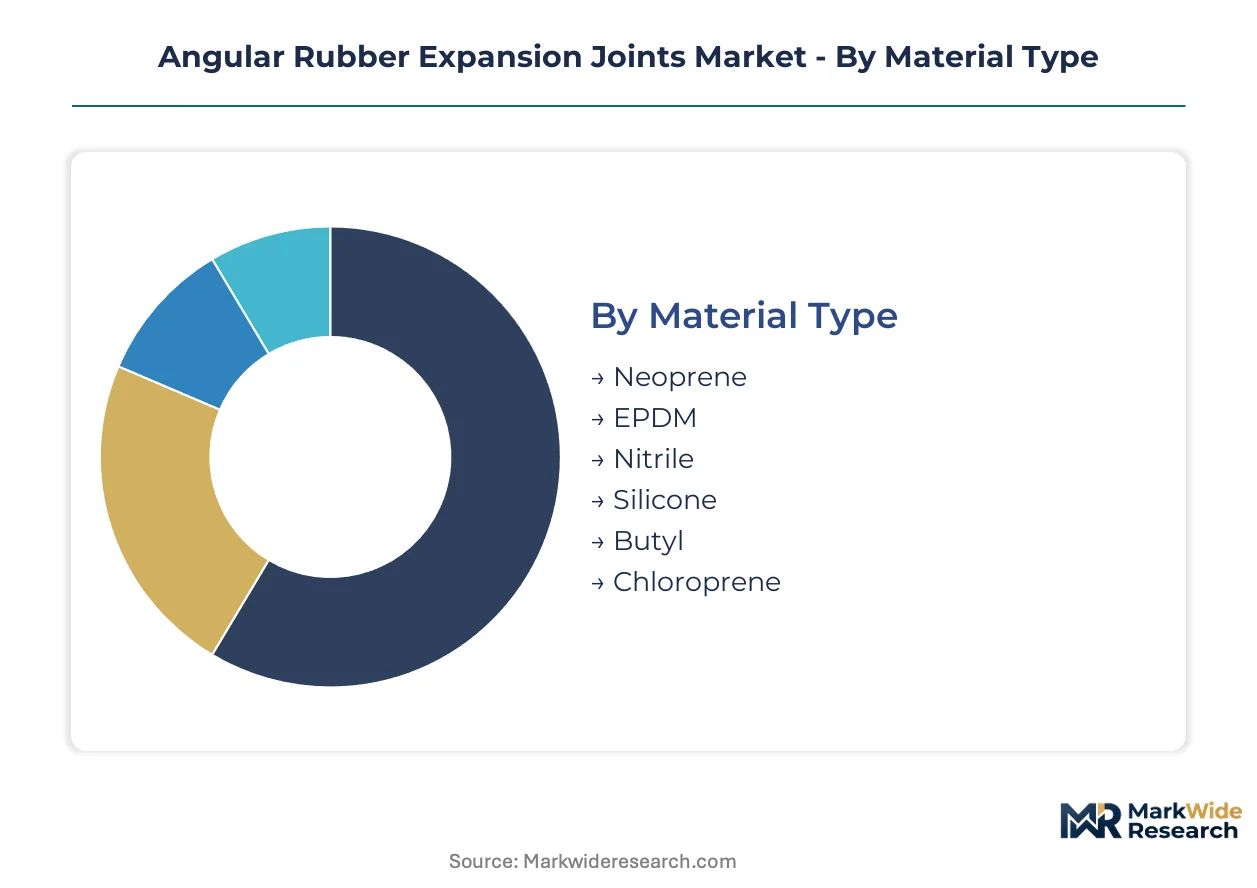
Segmentation in angular rubber expansion joints reveals how specification authority fragments across material science, end-use certification requirements, and dimensional engineering complexity. Buyers prioritize different performance vectors—ozone resistance for municipal water infrastructure, hydrocarbon tolerance for petrochemical corridors, or thermal stability for power generation—creating distinct procurement channels and margin profiles.
Material Type:
Cost tier differentiation separates commodity elastomer buyers from premium compound specifiers, with certification requirements and service life guarantees driving material selection.
- EPDM:Ethylene-propylene-diene monomer compounds dominate potable water and HVAC specifications due to superior ozone resistance and NSF/ANSI 61 certification compatibility. Municipal utilities in Germany and the United States are expanding procurement of EPDM-based angular joints to comply with tightened EPA and EU drinking water infrastructure standards.
- Nitrile:Acrylonitrile-butadiene rubber delivers exceptional hydrocarbon resistance for refinery and chemical processing environments. Demand concentrates along the Gulf Coast petrochemical corridor where pipeline integrity mandates sustain replacement volumes for nitrile variants in turnaround cycles.
- Neoprene:Chloroprene-based compounds balance weather resistance with moderate chemical tolerance for general industrial applications.
- Silicone:High-temperature stability suits power generation and food processing installations requiring FDA-compliant flexibility.
- Butyl:Isobutylene-isoprene rubber provides superior gas impermeability for vacuum and low-pressure containment systems.
- Chloroprene:Alternative designation for neoprene variants, specified interchangeably in legacy procurement documentation and European technical standards.
EPDM leads volumes today; nitrile is gaining share fastest in hydrocarbon-exposed industrial corridors.
End Use Industry:
Application maturity varies sharply, with water treatment representing established replacement demand and hydrogen transport infrastructure emerging as a greenfield specification channel.
- Water Treatment:Municipal and industrial water infrastructure drives standardized, high-volume procurement of certified EPDM joints. EPA Lead and Copper Rule revisions are accelerating specification of potable water-certified angular joints across United States municipal utilities.
- Petrochemical Plants:Refinery turnaround schedules and pipeline integrity mandates sustain replacement demand for chloroprene and nitrile variants. The Gulf Coast corridor from Texas to Louisiana anchors this segment with concentrated maintenance expenditure cycles.
- Power Generation:High-temperature steam and cooling water systems require specialized compounds resistant to thermal cycling and pressure fluctuations.
- Shipbuilding:Marine applications demand saltwater corrosion resistance and vibration damping for propulsion and auxiliary systems.
- Food Processing:FDA food contact compliance and clean-in-place compatibility drive specification of silicone and specialized EPDM formulations.
- Chemical Manufacturing:Aggressive media exposure necessitates custom-compounded solutions with site-specific resistance profiles.
Water treatment commands the largest installed base; petrochemical applications are expanding most quickly through maintenance cycle intensification.
Application:
Functional specification priority determines buyer sophistication, with vibration absorption and pressure relief demanding engineered solutions versus commodity piping connections.
- Piping Systems:General pressurized fluid transport represents the foundational application, with specification driven by pressure rating and flange compatibility standards.
- HVAC Systems:Refrigerant piping and thermal expansion management in heating, ventilation, and air conditioning installations. EU F-Gas Regulation pressures are expanding specification opportunities for vibration-absorbing joints in refrigerant piping retrofits across Germany and France.
- Pressure Relief:Surge protection and thermal expansion accommodation in high-pressure industrial pipelines.
- Vibration Absorption:Mechanical isolation of rotating equipment and pump stations from connected piping infrastructure.
- Shock Resistance:Water hammer and transient pressure event mitigation in municipal distribution networks.
- Pipeline Protection:Seismic accommodation and ground movement compensation for buried and elevated transmission lines.
Piping systems anchor current procurement volumes; HVAC applications are climbing the fastest on regulatory retrofit mandates.
Size:
Engineering intensity and price transparency inversely correlate with diameter, concentrating margin pools in non-standard fabrications.
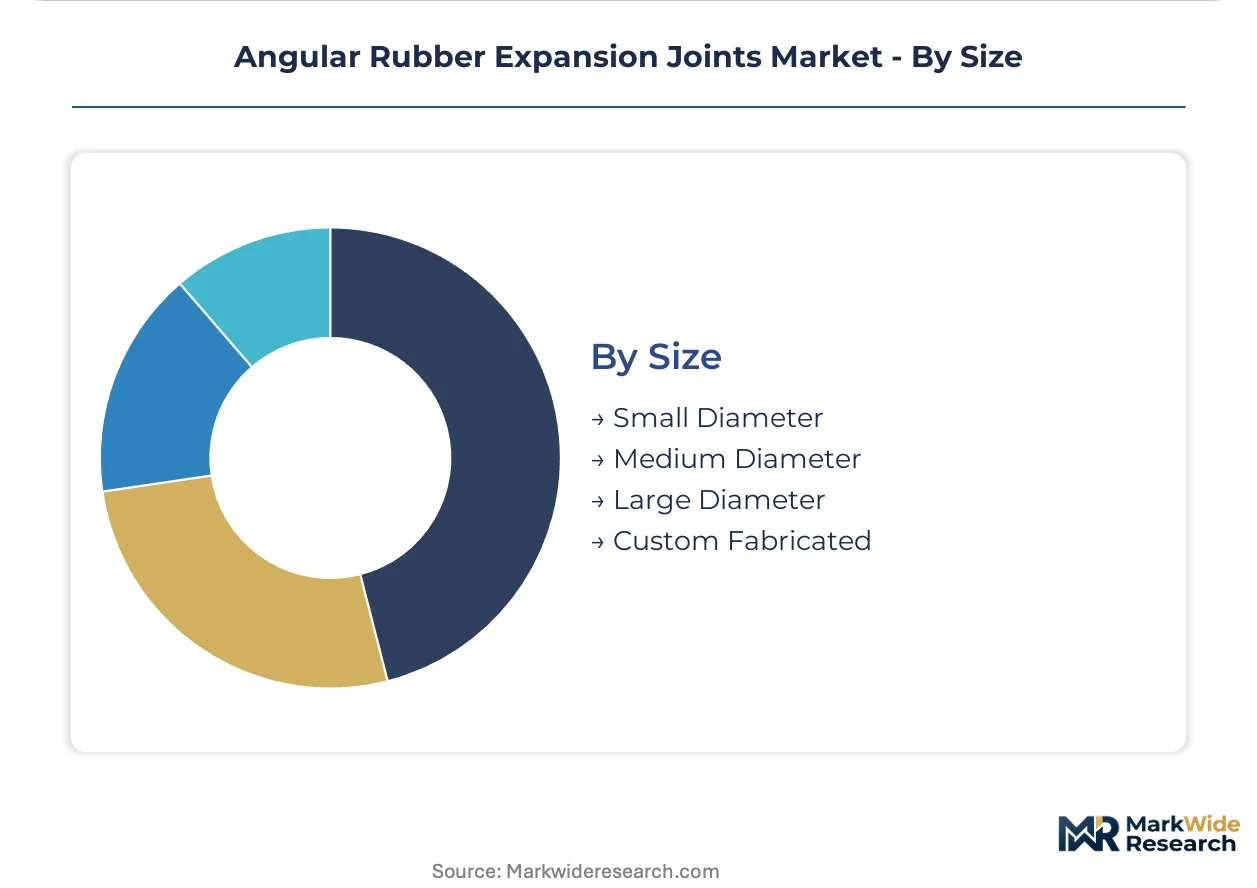
- Large Diameter:Engineered solutions above 24 inches require custom textile reinforcement patterns and specialized molding equipment. The segment captures disproportionate margin pools given engineering-intensive specification work and lower price transparency in project-based procurement.
- Custom Fabricated:Non-standard dimensions and legacy flange interface requirements demand hand-built construction with extended lead times. Custom-fabricated large-diameter joints must interface with decades-old cast iron and carbon steel piping infrastructure with non-standard flange dimensions.
- Small Diameter:Standardized molded products for residential and light commercial plumbing applications.
- Medium Diameter:Industrial process piping and municipal distribution branch connections in the 4- to 24-inch range.
Medium diameter leads volumes today; custom fabricated solutions are gaining share fastest on aging infrastructure replacement complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angular rubber expansion joint manufacturing originated in German industrial centers during the early twentieth century, with textile-reinforced molded rubber technology scaling through post-war chemical infrastructure investments across Western Europe and North America.
United States
Gulf Coast petrochemical complexes drive replacement cycles for nitrile and chloroprene variants, while municipal water utilities accelerate EPDM procurement under EPA Lead and Copper Rule revisions. The Texas-Louisiana corridor concentrates maintenance expenditure for refinery turnaround schedules.
Germany
Industrial machinery heritage sustains precision molding capabilities for large-diameter custom fabrications. EU F-Gas Regulation pressures expand specification opportunities in HVAC refrigerant piping retrofits across the Rhine-Ruhr industrial region.
China
Central government infrastructure allocations expand municipal water pipeline networks requiring certified expansion joints. Yangtze River Delta manufacturing clusters scale molded rubber production for domestic and export markets.
India
Jal Jeevan Mission allocations accelerate municipal pipeline construction requiring potable water-certified EPDM joints. Gujarat and Maharashtra industrial corridors concentrate procurement for chemical processing and water treatment installations.
Netherlands
Rotterdam port petrochemical infrastructure sustains demand for hydrocarbon-resistant compounds. Emerging hydrogen pipeline networks in the North Sea region require specialized elastomer formulations resistant to hydrogen embrittlement.
Angular Rubber Expansion Joints Market Competitive Landscape
The competitive structure tilts toward integrated polymer producers with captive compounding capabilities and specialized fabricators with deep specification relationships. Tiered positioning separates multinational elastomer suppliers from regional molding specialists and project-engineering contractors. Dominant competitive moves include backward integration into compound formulation and framework agreements bundling angular joints with adjacent piping components.
Within the integrated polymer producer tier, ContiTech AG exemplifies deep research integration, while Elaflex leverages European manufacturing footprints for export competitiveness. Among specialized sealing technology providers, Garlock Sealing Technologies occupies a position in high-temperature compound applications. These three anchors represent distinct strategic archetypes: polymer science-driven vertical integration, geographic arbitrage through manufacturing footprint optimization, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Elaflex |
| HKS Group |
| ContiTech AG |
| Politeknik |
| Kadant |
| Flexicraft Industries |
| Garlock Sealing Technologies |
| HOLZ Rubber Company |
| Belman A/S |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between NSF/ANSI 61-certified EPDM joints and uncertified commodity alternatives manifests in both pricing power and supply chain configurations. Buyers in German municipal water utilities and United States Gulf Coast refineries pay premiums for documented compliance traceability, while procurement in general industrial segments prioritizes unit cost over qualification depth.
Pricing Analysis
Bundled engineering services versus unbundled product supply splits the pricing landscape. Project-based contracting dominates large-diameter custom fabrications where specification authority rests with engineering-procurement-construction firms, while transactional spot purchasing governs small-diameter molded products. Price differentiation rests on certification tier—EPA potable water approval commands 15-30% premiums over baseline EPDM—and volume scale, with municipal framework agreements securing favorable unit economics. Pricing pressure stems from raw material volatility in synthetic elastomer feedstocks, compressing margins for non-integrated fabricators. General industrial buyers exhibit highest price sensitivity, while power generation and food processing clients prioritize thermal stability and FDA compliance over unit cost.
Supply Chain Analysis
Certification and qualification gating concentrates supply among compounders with in-house testing laboratories and documented REACH compliance. Manufacturing clusters in Germany, the United States, and China anchor production, with German facilities specializing in large-diameter engineered solutions and Chinese plants scaling standardized molded volumes. Raw material dependencies center on EPDM polymer, textile cord reinforcement, and cure accelerators subject to ECHA SVHC scrutiny. Single-source vulnerability runs through specialized textile weavers supplying aramid reinforcement for high-pressure ratings. Distribution runs through integrated MRO distributors consolidating vendor pools, though direct specification relationships persist for custom fabrications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where infrastructure replacement cycles and regulatory tightening are shifting procurement toward premium-certified specifications. Municipal water utilities in Germany and the United States now mandate documented compliance traceability that commodity suppliers cannot fulfill.
For Market Incumbents: Anticipate margin compression from raw material volatility by securing captive compounding capabilities or long-term elastomer offtake agreements. Defensive positioning requires deepening specification relationships with engineering-procurement-construction firms before framework agreements consolidate vendor pools. Threats from integrated polymer producers with research-backed compound portfolios necessitate certification investment in emerging PFAS-free formulations.
For New Entrants and Emerging Players: EPA Lead and Copper Rule revisions in the United States open a window for potable water-certified EPDM specialists without legacy compliance burdens. White-space targets include India's Jal Jeevan Mission pipeline buildout and hydrogen transport infrastructure in Germany and the Netherlands. The most penetrable segment is custom-fabricated large-diameter solutions where engineering intensity deters commodity competitors. Go-to-market positioning should emphasize digital specification platform integration to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where compound formulation expertise concentrates among aging technical workforces without succession pipelines. Long-term viability favors targets with validated REACH-compliant portfolios and established relationships with municipal procurement authorities. Acquisition archetypes include regional fabricators with EPA certification depth and specialized large-diameter engineering capabilities. The signal to watch is framework agreement announcements by major engineering-procurement-construction firms, which will foretell vendor pool consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Formulation | Captive EPDM compounding secures margin control against synthetic rubber feedstock volatility. |
| REACH-Compliant Portfolio Expansion | Pre-validated SVHC-free formulations accelerate specification approval with Dutch and German food processors. |
| Digital Specification Platform Partnership | Cloud-based piping design tools create channel access bypassing traditional MRO distributor gatekeepers. |
| Hydrogen-Resistant Compound Development | Specialized elastomer formulations for German and Dutch hydrogen pipeline networks address emerging greenfield demand. |
| Framework Agreement Negotiation | Bundled supply contracts with United States municipal design-build contractors lock out fragmented competitors. |
Research Methodology
Direct dialogue with plant engineers, municipal procurement officers, aftermarket service directors, and technical R&D leads at elastomer compounders grounded qualitative findings. Secondary validation drew from EPA enforcement actions, ECHA SVHC candidate list updates, SEC filings of integrated polymer producers, and customs trade data for rubber expansion joint classifications. Bottom-up and top-down triangulation cross-checked volume estimates against refinery turnaround schedules and municipal infrastructure expenditure reports.
Bottom-up modeling anchored projections, with top-down macro checks for plausibility. Segmentation dimensions included material type, end-use industry, application function, and dimensional category across the projection horizon. CAGRs derived from trend extrapolation of replacement cycle intensification and regulatory compliance acceleration. Industry-specific inputs incorporated pipeline integrity mandate timelines and REACH SVHC list expansion trajectories.
Revisions become necessary when PFAS restriction timelines accelerate, hydrogen infrastructure deployment stalls, or framework agreement consolidation alters channel economics. Forecasts reflect assumptions about elastomer feedstock price stability and certification continuity. A model refresh is warranted upon material change in EPA enforcement priorities or EU F-Gas Regulation implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Sanitary Ware Market