
 Die Casting Market | 2026-2036
Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Die Casting Market Intelligence
Tool-and-die engineering talent scarcity is reorganizing foundry investment patterns across North America and Western Europe. Nemak leverages captive aluminum smelting partnerships to secure ingot supply for structural battery tray programs. Rheinmetall AG anchors defense-sector demand through armor-grade magnesium casting specialization. GF Casting Solutions competes on vacuum-assisted process control for thin-wall electric motor housings.
Die casting forces molten non-ferrous metal into reusable steel molds under pressures exceeding 1,000 bar, achieving dimensional tolerances of ±0.1 mm for complex net-shape components. The process serves primarily to reduce machining steps and consolidate multi-part assemblies into single castings for mass production. Aluminum alloys dominate automotive structural applications where strength-to-weight ratios determine vehicle range and payload. High-pressure die casting captures the largest volume share but faces margin pressure from capital-intensive cell retrofitting for larger part formats. Vacuum die casting commands premium positioning in EV battery enclosure segments where porosity thresholds below 1% prevent electrolyte leakage.
EPA Corporate Average Fuel Economy standards and EU F-Gas Regulation constrain foundry energy profiles and refrigerant choices in die lubrication systems. China's MIIT enforces GB standards on recycled aluminum content in automotive castings, reshaping raw material procurement. NHTSA crashworthiness protocols and ECE R94 homologation rules dictate wall-thickness minima that directly influence alloy selection and gating design. Stakeholders must monitor evolving OEM platform consolidation timelines and secondary alloy price spreads to time capacity commitments.
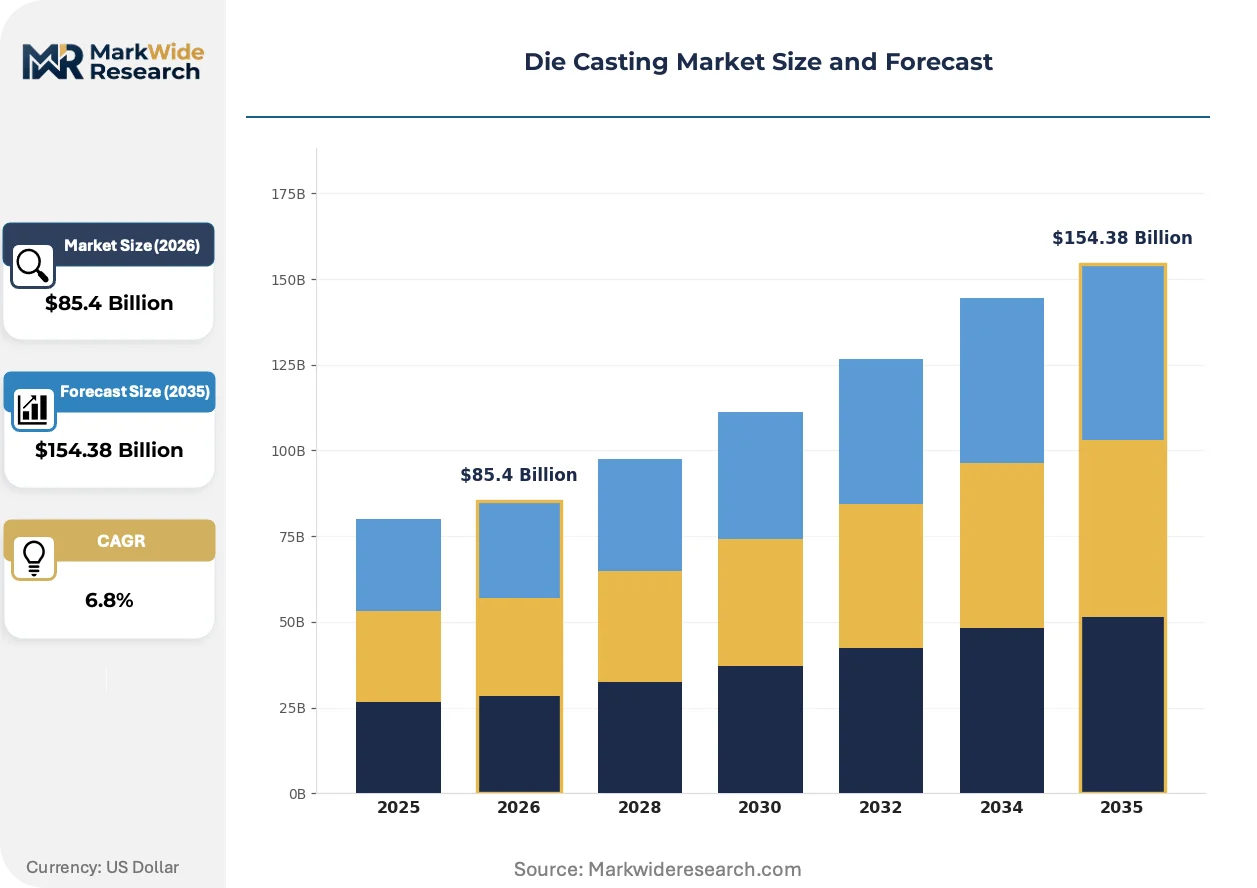
Market Dynamics
Platform consolidation across automotive OEMs is compressing die casting contract timelines while simultaneously expanding part complexity requirements for integrated battery-electric architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Mandate fleet-wide efficiency gains that force material substitution from steel to aluminum castings in powertrain housings.
- Structural battery tray demand:Electric vehicle architectures require large-format aluminum castings that consolidate dozens of stamped components into single net-shape parts.
- China's MIIT GB standards:Recycled aluminum content mandates reshape raw material procurement patterns across automotive supply chains.
Market Restraints
- Primary aluminum price volatility:LME price swings and energy cost spikes in smelting regions compress foundry margins unpredictably.
- Tool-and-die engineering scarcity:North American and Western European talent pipelines cannot replenish retiring mold designers at required rates.
- High-pressure die casting porosity limits:Conventional HPDC cannot reliably achieve sub-1% porosity thresholds required for EV battery enclosures without vacuum assist retrofits.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic OEM localization programs create demand for aluminum casting capacity near Chennai and Pune assembly clusters.
- Magnesium alloy convergence:Hybrid aluminum-magnesium casting processes enable thinner wall sections for seat frames and steering columns.
- Secondary alloy closed-loop channels:Direct foundry-to-OEM scrap return agreements bypass merchant scrap markets and stabilize ingot input costs.
Industry Challenges
- Multi-cavity mold qualification timelines:ECE R94 homologation and NHTSA crashworthiness protocols extend validation cycles for structural castings.
- Legacy equipment retrofit complexity:Existing HPDC cells require substantial capital outlays for vacuum systems and real-time porosity monitoring.
- Cross-platform tooling amortization:OEM consolidation onto fewer vehicle architectures concentrates volume risk on single mold investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Casting Market |
| Market Size in 2026 | $85.4 Billion |
| Market Size in 2035 | $154.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alloys, Zinc Alloys, Magnesium Alloys, Copper Alloys Application: Automotive Components, Electronics, Industrial Equipment, Consumer Goods Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Vacuum Die Casting, Die Casting with Inserts End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fabricators |
| Companies Covered | Nemak, Rheinmetall AG, Linamar Corporation, Alcoa Corporation, Ryobi Die Casting, Bühler AG, UBE Machinery Corporation Ltd., Dynacast International Inc., GF Casting Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Casting Market Strategic Shifts & Innovations
Process control digitization and alloy formulation advances are compressing the gap between prototype casting validation and mass production ramp rates across automotive supply chains.
Large-scale integrated die casting is decomposing traditional multi-part assembly sequences into single-shot structural components. Tesla and Volvo Car Group have adopted 6,000-ton-plus HPDC cells for rear underbody castings that replace stamped steel assemblies. This technology is decomposing tiered supplier hierarchies by bringing formerly outsourced fabrication steps in-house.
The EU F-Gas Regulation constrains refrigerant choices in die lubrication spray systems, forcing foundries to retrofit atomization equipment for water-based alternatives. Industrial consequence includes elevated cycle times and modified thermal management protocols. German and Austrian foundries serving premium OEMs are responding fastest due to domestic regulatory enforcement density.
Consolidated procurement contracts now bundle casting, machining, and surface treatment under single-supplier responsibility. Tier-1 suppliers are displacing fragmented multi-vendor arrangements that separated foundry output from finishing operations. This pattern is most visible in Mexico's Bajío region where OEMs co-located with dedicated casting-machining campuses.
Die Casting Market Segmentation
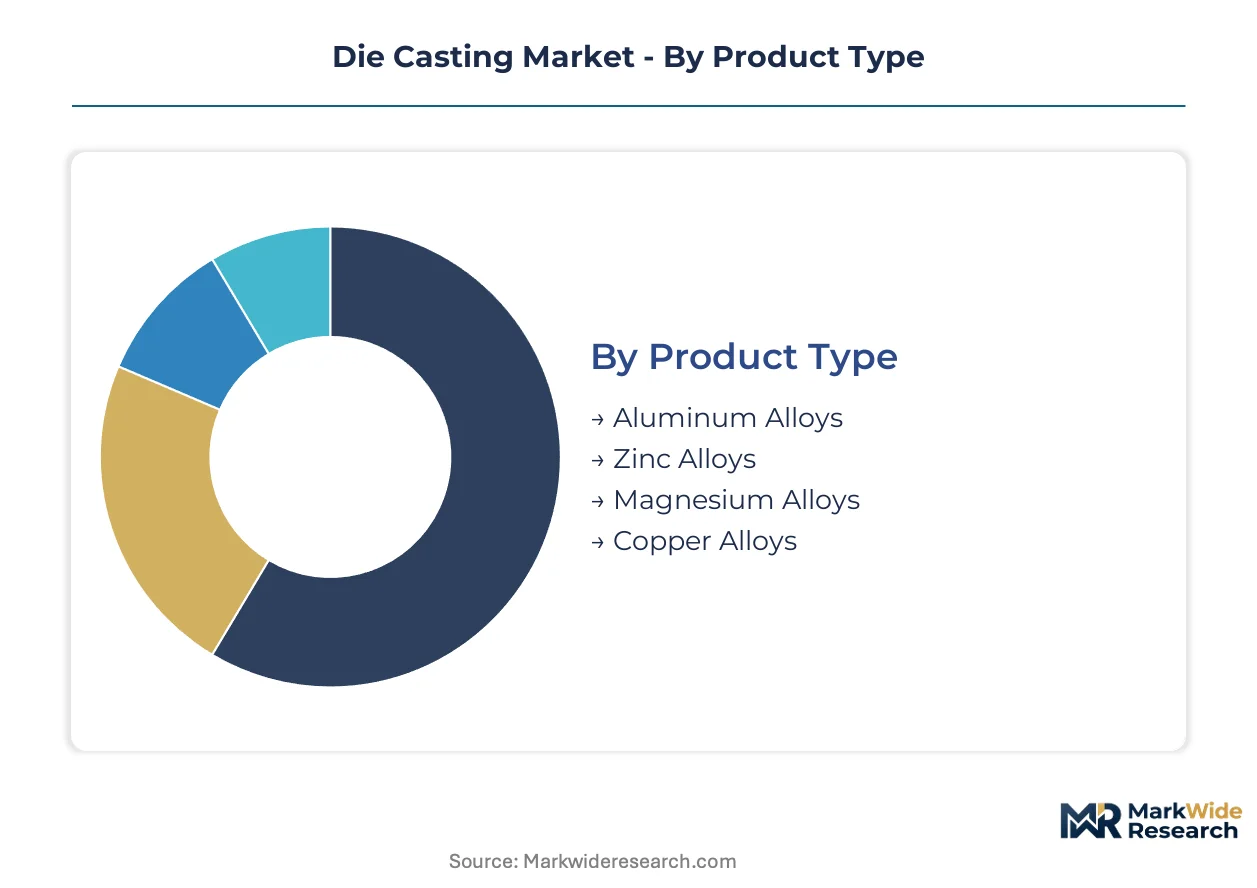
Die casting market segmentation reveals how alloy chemistry, process physics, and supply chain position determine margin capture across automotive electrification and industrial automation cycles. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape foundry investment decisions.
Product Type:
EPA Corporate Average Fuel Economy standards and EU CO2 fleet mandates create divergent compliance burdens across alloy categories, with density and recyclability thresholds directly influencing automotive platform eligibility.
- Aluminum Alloys:A356 and Silafont-36 grades deliver strength-to-weight ratios of 150-200 MPa yield strength at 2.7 g/cm³ density, satisfying NHTSA crashworthiness protocols for structural battery trays. China's MIIT GB standards on recycled content concentrate procurement around secondary A380 ingot for powertrain housings in Shanghai and Guangzhou assembly corridors.
- Magnesium Alloys:AZ91D and AM60B formulations achieve 1.8 g/cm³ density with 60-80% mass reduction versus aluminum equivalents, though ECE R94 homologation complexity restricts deployment to non-structural interior components. Rheinmetall AG anchors defense-sector demand through armor-grade WE43 casting specialization in Germany.
- Zinc Alloys:Zamak 3 and Zamak 5 variants enable thin-wall precision below 0.5 mm for electronics connectors and lock mechanisms, with die temperatures below 450°C reducing thermal fatigue on tooling.
- Copper Alloys:C87800 silicon brass and C83600 leaded red brass serve electrical busbar and plumbing fitting applications where conductivity and corrosion resistance outweigh density penalties.
Aluminum alloys handle the majority of throughput; magnesium alloys are expanding most quickly on electrification-driven lightweighting mandates.
Application:
Customer procurement scale separates this dimension, with billion-unit annual volumes in automotive contrasting project-based industrial equipment cycles.
- Automotive Components:Powertrain housings, structural battery enclosures, and motor end-caps consolidate multi-part stampings into single net-shape castings. Tesla and Volvo Car Group have adopted 6,000-ton-plus HPDC cells for rear underbody castings that replace 70+ welded steel components.
- Electronics:Heat sinks, shielding enclosures, and connector housings demand tight dimensional tolerances for EMI compliance and thermal dissipation in 5G infrastructure and data center equipment.
- Industrial Equipment:Pump housings, valve bodies, and compressor components serve oilfield and HVAC OEMs with batch production economics that favor gravity and low-pressure processes over high-pressure automation.
- Consumer Goods:Power tool housings, appliance hardware, and sporting equipment components prioritize surface finish and color consistency over mechanical performance.
Automotive components dominate absolute volume; electronics applications show the steepest expansion trajectory on thermal management demands from AI compute infrastructure.
Technology:
Capital deployment intensity and porosity control thresholds differentiate process selection, with vacuum retrofits commanding 40-60% equipment premiums over conventional HPDC cells.
- High-Pressure Die Casting:Conventional HPDC operates at 1,000-1,500 bar injection pressure with cycle times below 60 seconds for mass production of transmission cases and engine blocks. Porosity levels of 2-5% limit structural battery tray qualification without vacuum assist modifications.
- Vacuum Die Casting:Chamber evacuation to 50-100 mbar before metal injection achieves sub-1% porosity thresholds mandatory for EV battery enclosures where electrolyte leakage prevention is critical. GF Casting Solutions competes on real-time vacuum process control for thin-wall electric motor housings.
- Low-Pressure Die Casting:0.3-0.8 bar metalostatic pressure fills molds from below, eliminating turbulence and oxide entrainment for wheel and suspension components requiring x-ray clarity.
- Die Casting with Inserts:Pre-placed steel or copper components become metallurgically bonded during metal injection, creating threaded bosses, bearing surfaces, and electrical terminals without secondary machining.
High-pressure die casting maintains the installed base majority; vacuum die casting is gaining share fastest on EV battery enclosure qualification requirements.
End User:
Supply chain position determines technical specification authority and inventory risk allocation across captive foundries and merchant suppliers.
- OEMs:Volkswagen, BMW, and Ford Motor Company operate captive casting capacity for powertrain components where design iteration speed outweighs merchant foundry cost advantages. Platform consolidation onto fewer architectures concentrates volume risk on single mold investments.
- Tier-1 Suppliers:Nemak, Ryobi, and Georg Fischer serve multiple OEM programs through dedicated casting-machining campuses in Mexico's Bajío region and China's Yangtze River Delta. Consolidated procurement contracts now bundle casting, machining, and surface treatment under single-supplier responsibility.
- Aftermarket Providers:Independent distributors and remanufacturers source replacement transmission cases and engine components from secondary alloy streams, with BIS certification requirements governing Indian import eligibility.
- Fabricators:Job shops and custom casting houses serve industrial and consumer goods markets with short-run production and rapid prototyping capabilities.
Tier-1 suppliers manage the largest contract flow; OEM captive operations are climbing fastest on platform consolidation and giga-casting technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes aluminum die castings predominantly for structural battery trays and powertrain consolidation, while Germany and Mexico concentrate on precision-machined transmission housings and export-oriented supply chains serving regional vehicle assembly clusters.
China
MIIT GB standards on recycled aluminum content reshape procurement patterns for automotive castings serving BYD and NIO battery-electric platforms. The Yangtze River Delta and Pearl River Delta host dedicated casting clusters feeding Shanghai and Guangzhou assembly plants with high-pressure die cast powertrain components.
Germany
EU F-Gas Regulation constrains die lubrication refrigerant choices, forcing foundries serving BMW and Volkswagen to retrofit atomization equipment for water-based alternatives. Bavaria and Baden-Württemberg concentrate vacuum die casting capacity for thin-wall electric motor housings requiring sub-1% porosity thresholds.
Mexico
Bajío region OEM co-location drives demand for integrated casting-machining campuses supplying Ford and General Motors powertrain programs. NHTSA crashworthiness protocols and USMCA rules of origin requirements dictate wall-thickness minima that influence alloy selection for cross-border automotive trade.
United States
EPA Corporate Average Fuel Economy standards mandate fleet-wide efficiency gains that accelerate material substitution from steel to aluminum castings in Detroit Three powertrain architectures. Michigan and Ohio foundry clusters serve legacy internal combustion programs while retooling for EV structural components.
India
PLI scheme automotive localization programs create demand for aluminum casting capacity near Chennai and Pune assembly corridors. BIS certification requirements govern import eligibility for secondary alloy streams used in replacement transmission cases and engine components.
Die Casting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operations at Volkswagen and Ford competing against merchant suppliers for multi-OEM programs. The market structure rewards backward integration into aluminum smelting partnerships and real-time process control capabilities. Strategic archetypes include vacuum-assist technology specialists, large-format giga-casting adopters, and defense-grade magnesium alloy fabricators. Dominant competitive moves involve captive ingot supply agreements and consolidated procurement contracts bundling casting, machining, and surface treatment.
Among North American and European fabricators, Nemak, Rheinmetall AG, and GF Casting Solutions occupy positions reflecting distinct specialization vectors. Nemak represents the integrated supply chain archetype through captive aluminum sourcing arrangements. Rheinmetall AG exemplifies defense-sector casting specialization with armor-grade magnesium capabilities. GF Casting Solutions sits within the precision process control tier, anchoring vacuum-assisted die casting positioning for automotive electrification applications.
| Leading Market Players |
|---|
| Nemak |
| Rheinmetall AG |
| Linamar Corporation |
| Alcoa Corporation |
| Ryobi Die Casting |
| Bühler AG |
| UBE Machinery Corporation Ltd. |
| Dynacast International Inc. |
| GF Casting Solutions |
| Others |
Cost & Logistics Intelligence
Thousand-ton giga-casting cell utilization rates above 85 percent concentrate pricing power among foundries with vacuum-assist retrofit completion, compressing margin recovery for legacy high-pressure die casting operators serving commodity powertrain programs. China's Yangtze River Delta ingot premiums and Mexico's Bajío labor arbitrage create divergent cost floors that OEM procurement teams exploit through consolidated casting-machining campus contracts.
Pricing Analysis
Long-term offtake agreements between Volkswagen and Nemak anchor aluminum structural battery tray pricing, while spot secondary alloy purchases expose smaller foundries to LME volatility. Price differentiation rests on vacuum-assist certification status and ECE R94 homologation completion, with crash-qualified suppliers commanding 15-20 point spreads over commodity powertrain casters. Cost compression in standard-grade A380 powertrain housings intensifies as Chinese foundries add 6,000-ton capacity. Aftermarket remanufacturers exhibit highest price sensitivity due to merchant scrap input dependency, whereas captive OEM operations absorb alloy swings through backward smelting partnerships.
Supply Chain Analysis
Strategic aluminum ingot stockpiling dominates foundry inventory strategy, with 45-60 day cover ratios insulating against Shanghai Futures Exchange volatility that just-in-timers cannot match. Primary supply concentrates in China, Germany, and the United Arab Emirates, with secondary flows from Mexico and India gaining share on USMCA and PLI scheme localization. Raw material procurement draws from bauxite refining, post-consumer scrap sorting, and alloying element additives including silicon and magnesium. Single-source vulnerability permeates vacuum pump and real-time porosity sensor equipment, where German and Japanese suppliers control aftermarket service networks. Distribution runs through Tier-1 supplier casting-machining campuses co-located with OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die casting incumbents face substitution pressure from carbon fiber reinforced polymer battery enclosures and stamped aluminum megacasting alternatives that eliminate welding joints through adhesive bonding. Defense of structural casting share requires process capability investments that polymer processes cannot replicate at automotive volume scale.
For Market Incumbents: Consolidate vacuum-assist retrofit completion across installed HPDC cells before Tesla and Volvo Car Group finalize giga-casting supplier qualification timelines. Lock captive aluminum smelting partnerships in China's Guangdong and Mexico's Nuevo León to isolate margin exposure from LME volatility. Secondary alloy closed-loop agreements with OEMs displace merchant scrap market dependency.
For New Entrants and Emerging Players: Aftermarket remanufacturer certification gaps in India's BIS-compliant secondary alloy streams offer white-space entry with lower capital intensity than OEM structural tray qualification. Target electronics heat sink applications for 5G infrastructure where thermal conductivity requirements exclude polymer substitutes. Lead with rapid prototyping services for industrial equipment batch production that gravity casting specialists cannot match on speed.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers with consolidated casting-machining-surface treatment contracts spanning multiple OEM platforms. Long-term viability favors vacuum-assist technology specialists over commodity powertrain foundries facing platform consolidation volume risk. Monitor Tesla and Rivian giga-casting in-sourcing announcements as inflection indicators for merchant supplier displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Assist Retrofit Completion | Sub-1% porosity qualification unlocks EV battery enclosure contracts from BMW and Ford. |
| Captive Aluminum Smelting Partnership | Nemak's ingot supply integration insulates margin from Shanghai Futures Exchange volatility. |
| Secondary Alloy Closed-Loop Channel | Direct OEM scrap return agreements bypass merchant markets and stabilize input costs. |
| Giga-Casting Cell Capacity Addition | 6,000-ton HPDC deployment captures rear underbody programs displacing 70-part stampings. |
| ECE R94 Homologation Investment | Crashworthiness certification extends addressable market into structural automotive applications. |
Research Approach
A spread of perspectives from foundry operations managers, OEM platform engineers, Tier-1 supplier procurement leads, and aluminum smelting commercial directors converged on the working assumptions shaping this analysis. Primary fieldwork combined plant-level interviews across China's Yangtze River Delta, Germany's Baden-Württemberg, and Mexico's Bajío region with secondary validation from MIIT GB standard filings, EPA Corporate Average Fuel Economy regulatory dockets, LME warehouse stock reports, and vehicle production databases. Bottom-up capacity utilization assessments and top-down alloy demand modeling were triangulated against OEM platform consolidation timelines.
Segmentation dimensions modeled include alloy chemistry tier, process technology category, automotive application content per vehicle, and regional production cluster concentration. CAGRs were derived from production volume forecasts cross-referenced with alloy price elasticity assumptions and platform lifecycle phasing. Industry-specific inputs incorporated EPA fleet efficiency mandate compliance curves, EU F-Gas Regulation retrofit deadlines, and China's recycled content enforcement trajectories across the projection horizon.
Forecasts assume regulatory continuity in EPA fuel-economy standards, EU CO2 fleet mandates, and China's MIIT GB recycled content regimes; material policy shifts would require re-modeling alloy substitution rates and foundry investment payback periods. Revision becomes warranted when primary aluminum price volatility exceeds historical bands or when OEM giga-casting in-sourcing announcements accelerate beyond current platform consolidation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Global Large Conveyor Chain Market