
 Industrial Elevator Market | 2026-2036
Industrial Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Elevator Market Analysis
Aftermarket service revenue is narrowing the margin gap between new equipment sales and long-term maintenance contracts. Otis Elevator Company leverages its global service network to capture recurring revenue streams. KONE Corporation anchors its position through predictive maintenance platforms. Schindler Group differentiates via modular modernization kits that extend equipment lifecycles.
An industrial elevator is a vertically guided transport machine engineered to move materials, goods, or personnel between fixed levels in industrial environments, typically rated for loads exceeding standard commercial capacities and built with reinforced steel car frames and traction or hydraulic drive systems. Its primary purpose centers on optimizing throughput in facilities where vertical logistics constrain operational efficiency. Freight elevator configurations dominate warehouse and distribution center deployments due to their higher load ratings and wider platform dimensions. Electric traction technology leads new installations for buildings above six stories, while hydraulic systems retain cost advantages in low-rise manufacturing plants. Scissor lift demand accelerates in construction site applications where temporary vertical access requires mobility rather than fixed shaft infrastructure.
OSHA mandates govern worker safety in US industrial elevator installations, requiring regular inspections and load-testing protocols that sustain replacement demand for aging equipment. The EU Machinery Directive and CE marking requirements shape product design standards for equipment sold across European member states, forcing manufacturers to harmonize control systems and emergency braking specifications. China's GB standards and MEE environmental compliance rules add certification layers for foreign suppliers targeting domestic infrastructure projects. Stakeholders must weigh regulatory compliance costs against the service revenue potential of installed base expansion as they allocate capital across geographic markets.
Market Dynamics
The shift from reactive maintenance to predictive uptime models is restructuring competitive advantage around data infrastructure rather than manufacturing scale alone.
Growth Catalysts
- ISO 19443 nuclear quality standards:Australian mining operators are replacing legacy hoists with certified industrial elevators to meet radiation monitoring requirements in uranium extraction facilities.
- Automotive battery gigafactories:Multi-level electrode coating lines in China's Jiangsu and Sichuan provinces require high-speed freight elevators with cleanroom-rated car enclosures.
- Hydraulic-to-traction retrofits:European chemical plants are modernizing aging lift systems to eliminate mineral oil contamination risks under REACH substance restrictions.
Market Restraints
- Specialized steel supply concentration:High-tensile car frame production depends on Japanese and South Korean specialty steel mills with limited spot market availability.
- Permanent magnet cost volatility:Gearless traction machines rely on rare-earth magnet assemblies whose pricing fluctuates with Chinese export quota adjustments.
- CE-GB standard divergence:European manufacturers face redundant testing protocols when certifying identical equipment for EU Machinery Directive and China's GB 7588 safety codes.
Strategic Opportunities
- Indonesian nickel processing corridor:Sulawesi and Halmahera smelter construction is generating first-time demand for heavy-duty material hoists in previously unserved territories.
- IoT-enabled condition monitoring:Vibration sensor networks and edge computing platforms are converging to enable remote diagnostics for offshore oil platform elevators.
- US Inflation Reduction Act domestic content credits:Green manufacturing facility construction is accelerating demand for US-assembled vertical transport equipment qualifying for federal tax incentives.
Industry Challenges
- Certified elevator technician shortages:OSHA-qualified installation and inspection personnel are concentrated in legacy manufacturing regions, creating bottlenecks for new project commissioning.
- Legacy control system integration:Analog-era relay logic in 1980s-era plants resists seamless interfacing with modern PLC-based safety architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Elevator Market |
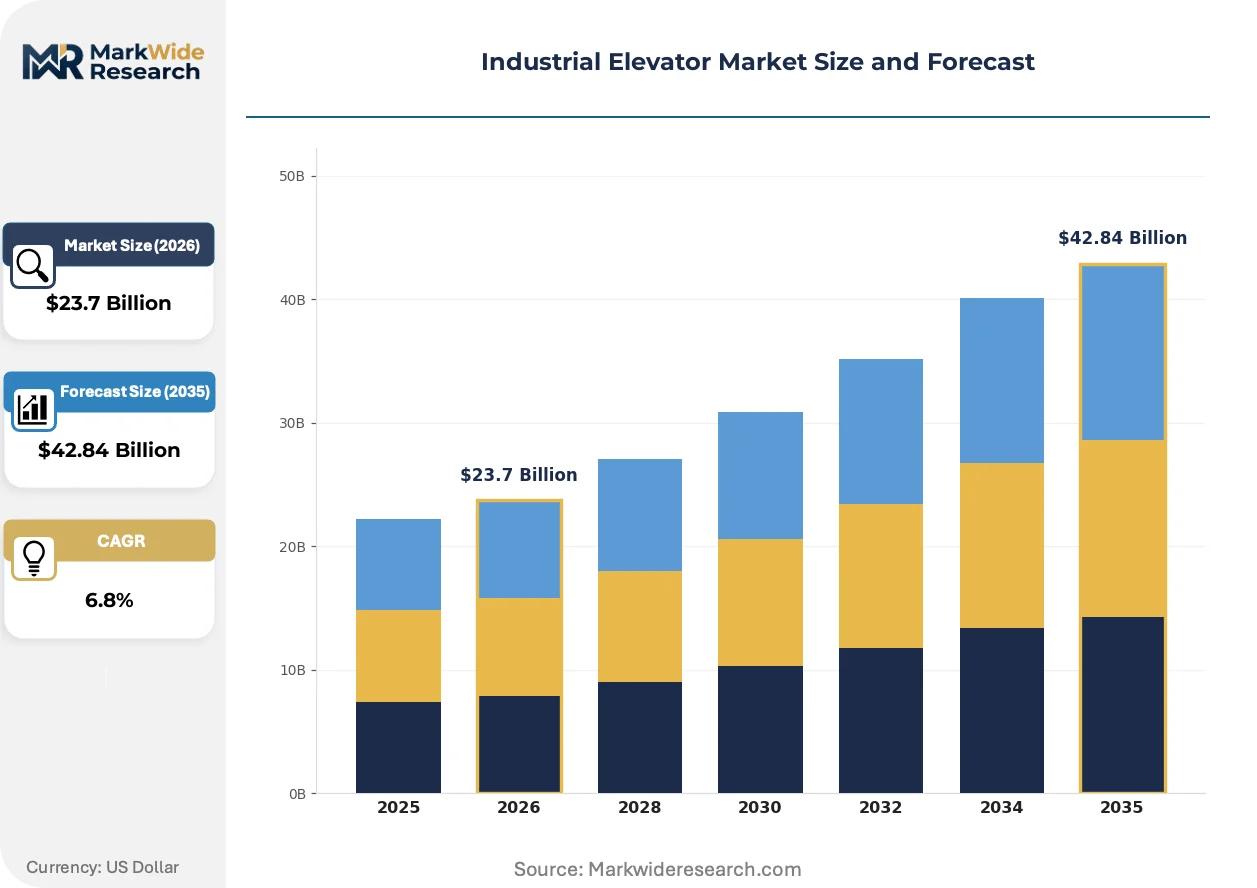
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freight Elevator, Passenger Elevator, Scissor Lift, Stackers Technology: Hydraulic, Electric, Pneumatic, Vacuum Application: Warehouse, Manufacturing Plant, Distribution Center, Construction Site End User: Logistics, Retail, Construction, Mining |
| Companies Covered | Otis Elevator Company, KONE Corporation, Schindler Group, TK Elevator, Mitsubishi Electric Corporation, Hitachi Ltd., Fujitec Co., Ltd., Hyundai Elevator Co., Ltd., Toshiba Elevator and Building Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Elevator Market Emerging Trajectories
Equipment intelligence and regulatory stringency are converging to elevate service contracts above hardware transactions as the primary value capture mechanism.
Machine learning algorithms applied to motor current signature analysis are digitizing failure prediction for traction machine bearings and brake systems. Warehouse operators in Germany's Ruhr industrial cluster are deploying these platforms at scale, compressing unplanned downtime intervals from weeks to hours and shifting supplier relationships toward guaranteed availability contracts.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based hydraulic fluids is forcing refrigerant substitution in elevator machinery across member states. Manufacturers are reformulating biodegradable synthetic alternatives, with Nordic pulp and paper mills—where cold-weather viscosity requirements are most severe—serving as the proving ground for next-generation fluid performance validation.
Buyer organizations are consolidating vertical transport procurement under integrated facilities management contracts rather than discrete capital expenditure approvals. This restructuring disintermediates traditional distributor networks in favor of direct OEM service relationships, with pharmaceutical manufacturing campuses in India's Hyderabad–Bangalore corridor most visibly advancing this consolidated sourcing model.
Industrial Elevator Market Segmentation
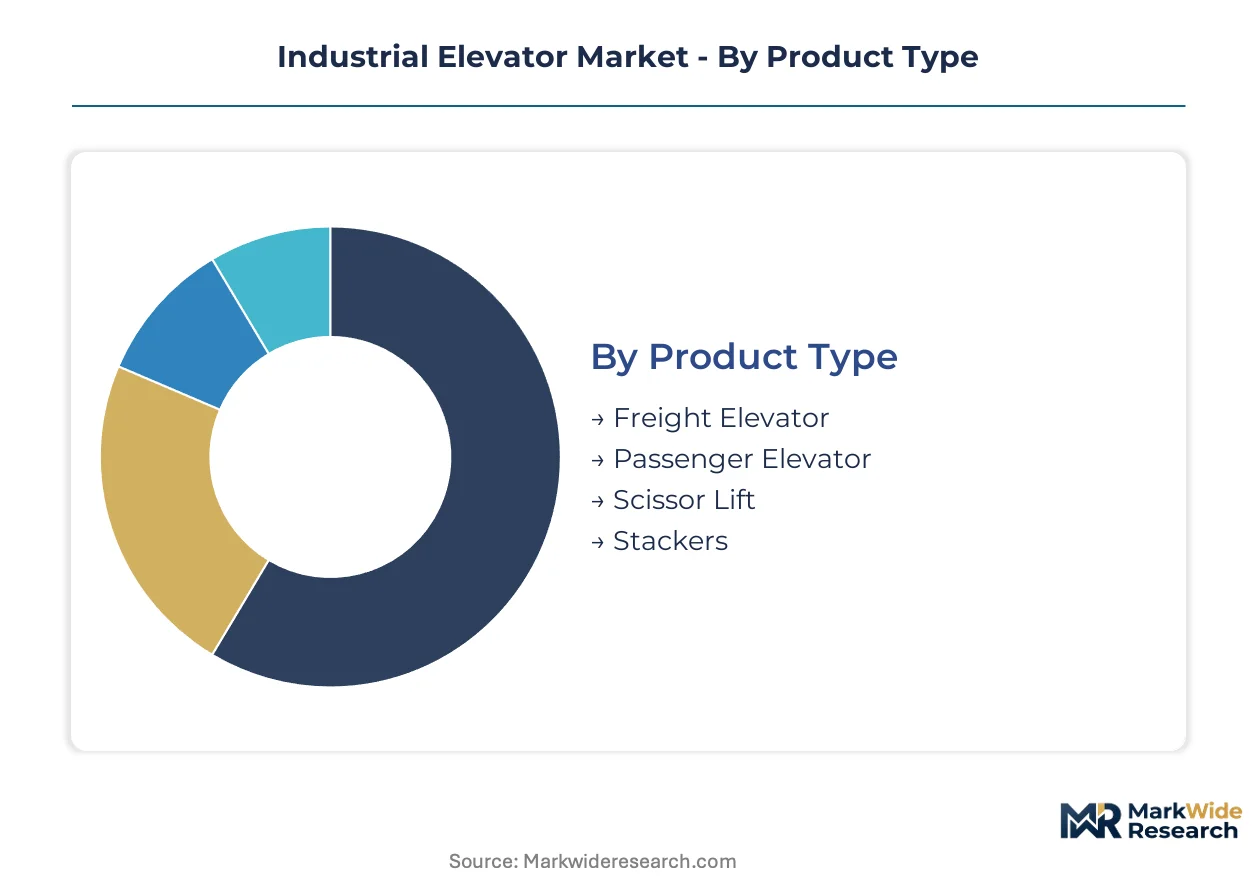
Segmentation in industrial elevators reveals how service contract economics vary dramatically across equipment types and duty cycles. Predictive maintenance platforms generate recurring revenue streams that differ by technology maturity and installation base density.
Product Type:
After-sales-service intensity correlates directly with car frame stress cycles and door operation frequency across product categories.
- Freight Elevator:Reinforced steel car frames rated for loads exceeding standard commercial capacities serve multi-level warehouse operations. Demand concentrates in China's coastal manufacturing zones where MEE environmental standards reshape equipment procurement toward higher-duty specifications.
- Passenger Elevator:Personnel-rated transport systems built with emergency braking and interlock protocols serve industrial campuses with vertical workforce movement. Australian mining operators are replacing legacy hoists with certified units to meet ISO 19443 radiation monitoring requirements in uranium extraction facilities.
- Scissor Lift:Mobile vertical platforms with hydraulic or electric drive systems enable temporary access at construction sites.
- Stackers:Self-propelled or pedestrian-operated units combine lifting with horizontal transport for palletized goods.
Freight elevators hold the largest share; momentum sits with scissor lifts in temporary infrastructure deployments.
Technology:
Cost tier differentiation separates premium gearless traction systems from economy hydraulic installations.
- Hydraulic:Fluid-powered drive systems using mineral oil or biodegradable synthetic fluids retain cost advantages in low-rise manufacturing plants. European chemical plants are modernizing aging lift systems to eliminate contamination risks under REACH substance restrictions.
- Electric:Traction machines with permanent magnet motors and variable frequency drives dominate new installations above six stories. Gearless configurations rely on rare-earth magnet assemblies whose pricing fluctuates with Chinese export quota adjustments.
- Pneumatic:Air-pressure-driven systems eliminate hydraulic fluid maintenance in cleanroom-sensitive environments.
- Vacuum:Atmospheric pressure differential drives enable compact shaft designs for specialized material handling.
Electric systems command the premium tier; hydraulic retrofits are expanding most quickly amid regulatory fluid substitution mandates.
Application:
Volume concentration follows e-commerce fulfillment network expansion and battery manufacturing facility construction.
- Warehouse:High-bay storage facilities require freight elevators with extended travel distances and automated dispatch integration. Germany's Ruhr industrial cluster deploys machine learning platforms for motor current signature analysis at scale.
- Manufacturing Plant:Production line integration demands synchronized vertical transport with cleanroom-rated car enclosures. Multi-level electrode coating lines in China's Jiangsu and Sichuan provinces drive high-speed freight elevator specifications.
- Distribution Center:Cross-dock operations prioritize throughput velocity over load capacity in elevator selection.
- Construction Site:Temporary vertical access requirements favor mobile scissor lifts over fixed shaft infrastructure.
Warehouse applications represent the dominant volume base; manufacturing plant installations are climbing the fastest with gigafactory construction.
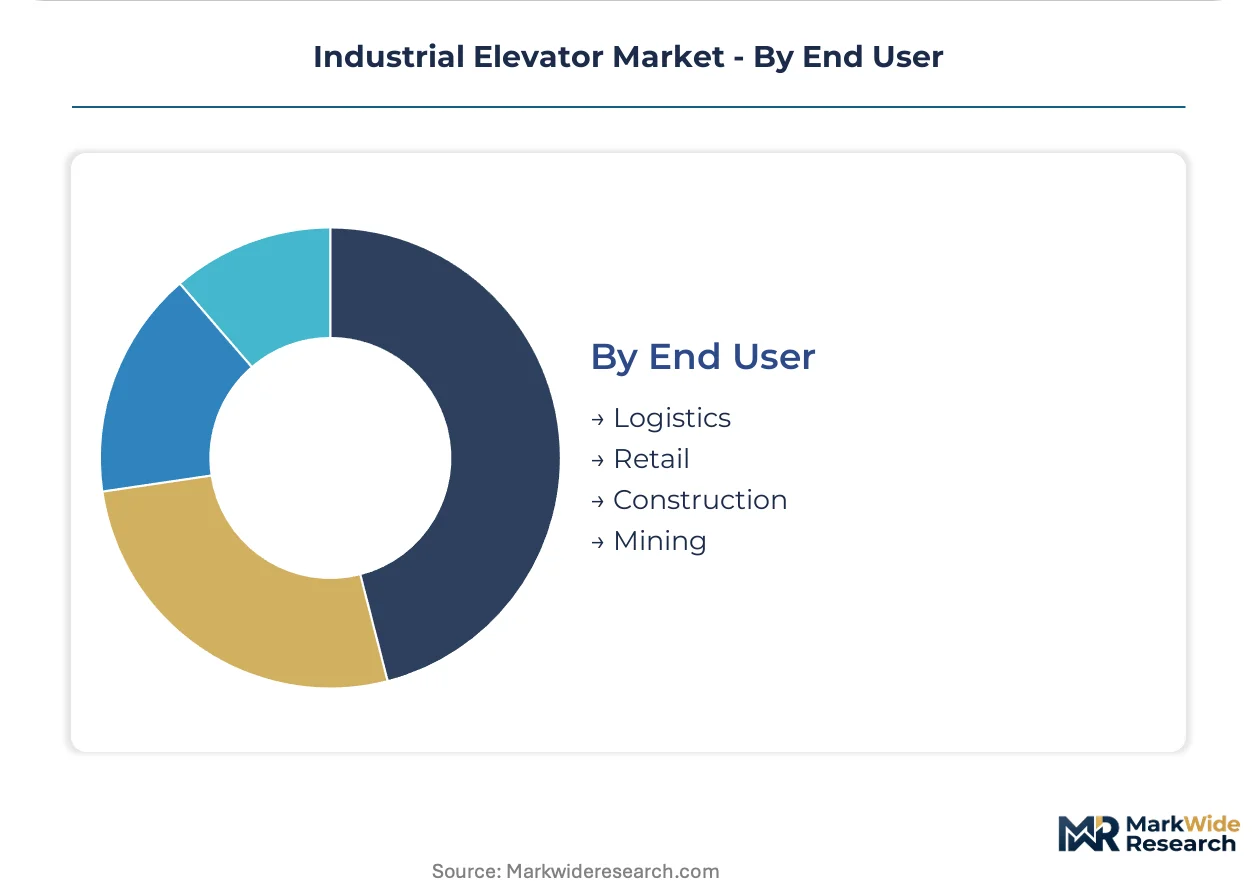
End User:
Customer type determines procurement consolidation patterns and service contract structuring.
- Logistics:Third-party fulfillment operators integrate vertical transport under integrated facilities management contracts rather than discrete capital expenditure approvals. Pharmaceutical manufacturing campuses in India's Hyderabad–Bangalore corridor advance consolidated sourcing models most visibly.
- Retail:Omnichannel distribution networks drive demand for automated material handling with elevator integration.
- Construction:Project-based procurement favors rental and lease structures over permanent installation ownership.
- Mining:Underground and surface extraction operations require heavy-duty hoists with radiation monitoring capabilities for uranium facilities.
Logistics end users anchor contract value; mining sector demand is gaining share fastest with stricter ISO safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys industrial elevators for high-throughput manufacturing logistics while Australia prioritizes radiation-certified hoists for uranium extraction. Germany emphasizes predictive maintenance platforms in warehouse clusters. The United States channels demand through domestic content incentives for green manufacturing facilities.
China
Jiangsu and Sichuan provinces drive demand through multi-level electrode coating lines in battery gigafactories. MEE environmental standards reshape procurement toward higher-duty freight elevator specifications. The Yangtze River Delta manufacturing corridor concentrates cleanroom-rated car enclosure installations.
Germany
Ruhr industrial cluster warehouse operators deploy machine learning platforms for motor current signature analysis at scale. The EU F-Gas Regulation mandates refrigerant substitution in hydraulic elevator machinery across member states. Chemical plants in North Rhine-Westphalia modernize lift systems to eliminate mineral oil contamination risks under REACH substance restrictions.
United States
OSHA mandates sustain replacement demand for aging equipment through regular inspections and load-testing protocols. The Inflation Reduction Act domestic content credits accelerate demand for US-assembled vertical transport equipment in green manufacturing facilities. Southeast construction markets favor rental scissor lifts over permanent shaft infrastructure.
Australia
Mining operations in Western Australia and South Australia replace legacy hoists with ISO 19443 certified industrial elevators for uranium extraction facilities. Stricter radiation monitoring requirements govern equipment selection in extraction zones. Surface and underground operations require heavy-duty material hoists with specialized safety architectures.
Indonesia
Sulawesi and Halmahera nickel processing smelter construction generates first-time demand for heavy-duty material hoists in previously unserved territories. The country's national industrial safety regulator imposes certification requirements on imported vertical transport equipment. Eastern archipelago mining corridors lack established service infrastructure for predictive maintenance platforms.
Industrial Elevator Market Vendor Landscape
Capability concentration sits with predictive maintenance platform developers; scale advantage sits with established service network operators. The market structures around three tiers: full-service OEMs with captive installation bases, technology specialists monetizing data infrastructure, and regional fabricators competing on delivery speed. Strategic moves center on predictive uptime model adoption and direct service relationship cultivation with consolidated procurement buyers.
Within the full-service OEM tier, Otis Elevator Company and KONE Corporation exemplify divergent approaches to recurring revenue capture. Otis leverages its global service network density to anchor long-term maintenance contracts. KONE occupies a position emphasizing predictive maintenance platform deployment. Schindler Group represents the modernization specialist archetype, with modular kit offerings extending equipment lifecycles.
| Leading Market Players |
|---|
| Otis Elevator Company |
| KONE Corporation |
| Schindler Group |
| TK Elevator |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Fujitec Co., Ltd. |
| Hyundai Elevator Co., Ltd. |
| Toshiba Elevator and Building Systems Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing corridor's freight elevator procurement costs reflect concentrated specialty steel supply from Japanese and South Korean mills, with downstream price differentiation separating ISO 19443-certified nuclear-grade installations from standard warehouse configurations.
Pricing Analysis
Long-term service contracts dominate pricing structures, with three-tier pricing stratification across premium predictive maintenance bundles, standard inspection agreements, and economy break-fix arrangements. Price differentiation hinges on certification tier and geographic service network density. Pricing pressure stems from rare-earth magnet cost volatility tied to Chinese export quota adjustments. Mining operators in Australia demonstrate lowest price sensitivity due to ISO safety mandate compliance requirements, while Southeast Asian construction rental markets exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
High-tensile car frame production draws from Japanese and South Korean specialty steel mills, with permanent magnet assemblies for gearless traction machines sourced primarily from Chinese rare-earth processors. Supply chain risk concentrates in single-source vulnerability for neodymium magnet feedstocks subject to export license restrictions. Distribution runs through OEM-direct service relationships for predictive maintenance platforms, with traditional distributor networks retaining project-based installation and commissioning flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are displacing hardware transactions as the primary value capture mechanism, with predictive uptime models and IoT-enabled condition monitoring creating winner-take-most dynamics around data infrastructure and service contract consolidation.
For Market Incumbents: Build predictive maintenance platform moats through edge computing deployment and vibration sensor network density. Anchor position by expanding certified technician training pipelines to address OSHA-qualified personnel shortages. Capture recurring revenue through guaranteed availability contracts that disintermediate traditional distributors in favor of direct OEM relationships with consolidated procurement buyers. For New Entrants and Emerging Players: Indonesian nickel processing corridors in Sulawesi and Halmahera represent the most penetrable entry point for heavy-duty material hoist deployments in previously unserved territories. Target modular modernization kit offerings for European chemical plants facing REACH substance restriction compliance deadlines. Pursue joint venture structures with established service network operators to bypass captive installation base disadvantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors predictive maintenance platform developers with proven machine learning algorithm deployment for motor current signature analysis. Long-term viability over the coming decade rests on data infrastructure ownership rather than manufacturing scale alone. Monitor Indonesian national industrial safety regulator certification requirement implementation as inflection indicator for regional market formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Machine learning algorithms for motor current signature analysis compress unplanned downtime from weeks to hours in Germany's Ruhr cluster. |
| Biodegradable Hydraulic Fluid Reformulation | EU F-Gas Regulation compliance enables continued market access across member states with Nordic pulp mills validating cold-weather performance. |
| Certified Technician Pipeline Expansion | OSHA-qualified installation personnel concentration in legacy regions creates bottlenecks for new project commissioning acceleration. |
| Modular Modernization Kit Development | REACH substance restriction compliance drives European chemical plant hydraulic-to-traction retrofit demand for lifecycle extension. |
| Direct OEM Service Relationship Cultivation | Integrated facilities management contract consolidation in India's Hyderabad-Bangalore pharmaceutical corridor disintermediates distributor networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and industry association reports covering elevator manufacturing and vertical transport equipment. Primary interviews engaged maintenance directors at warehouse and distribution center operators, plant engineers at battery gigafactory facilities, OEM procurement teams at industrial elevator manufacturers, and aftermarket service heads at established service network operators. Bottom-up triangulation across installation base counts and service contract values validates top-down market sizing derived from equipment shipment tracking and regulatory certification databases.
Forecast inputs span product type segmentation across freight, passenger, and scissor lift configurations; technology differentiation between hydraulic, electric, pneumatic, and vacuum drive systems; application clustering in warehouse, manufacturing plant, distribution center, and construction site deployments; and end-user categorization across logistics, retail, construction, and mining sectors. CAGRs were derived through regression analysis of historical equipment shipment patterns against industrial construction spending and manufacturing capacity expansion indicators. Industry-specific inputs include MEE environmental standard implementation timelines and ISO 19443 nuclear quality certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, specialty steel pricing, or rare-earth export quota enforcement would shift the trajectory across the projection horizon. Cross-checking against equipment manufacturer order backlog disclosures and national elevator safety regulator certification statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Electric Stacker Market