
 Drive-In Pallet Racking Market | 2026-2036
Drive-In Pallet Racking Market Size, Share, and Industry Trends Forecast 2026-2036
Drive-In Pallet Racking Market Foresight
ISO 9001 quality management certification is rotating as a baseline gate for supplier qualification in drive-in pallet racking procurement. Mecalux leverages its integrated manufacturing footprint across Europe to sustain large-format project delivery. Daifuku anchors its position through automated storage integration capabilities that extend beyond static racking systems. Hannibal Industries competes on domestic steel sourcing, controlling raw material cost volatility for North American clients.
Drive-in pallet racking consists of continuous lane storage structures where forklifts enter the rack structure to deposit or retrieve pallets, typically engineered from cold-formed steel with load capacities ranging from 1,500 to 3,000 kilograms per pallet position and depths extending 5 to 10 pallet positions deep to maximize cubic warehouse utilization. Steel dominates the material segment due to its fatigue resistance under cyclic loading, though aluminum gains traction in corrosion-sensitive environments such as pharmaceutical cold storage. Standard Drive-In configurations occupy the largest installed base, while Drive-Thru Racking captures growth in high-throughput distribution centers requiring dual-access inventory rotation.
FEM 10.2.02 European racking design standards and OSHA 1910.176 material handling regulations shape product engineering requirements and installation compliance across major markets. The EU Machinery Directive and CE marking obligations further constrain market access for non-certified manufacturers. Stakeholders must monitor evolving seismic design codes and automated guided vehicle compatibility specifications as warehouse automation deepens.
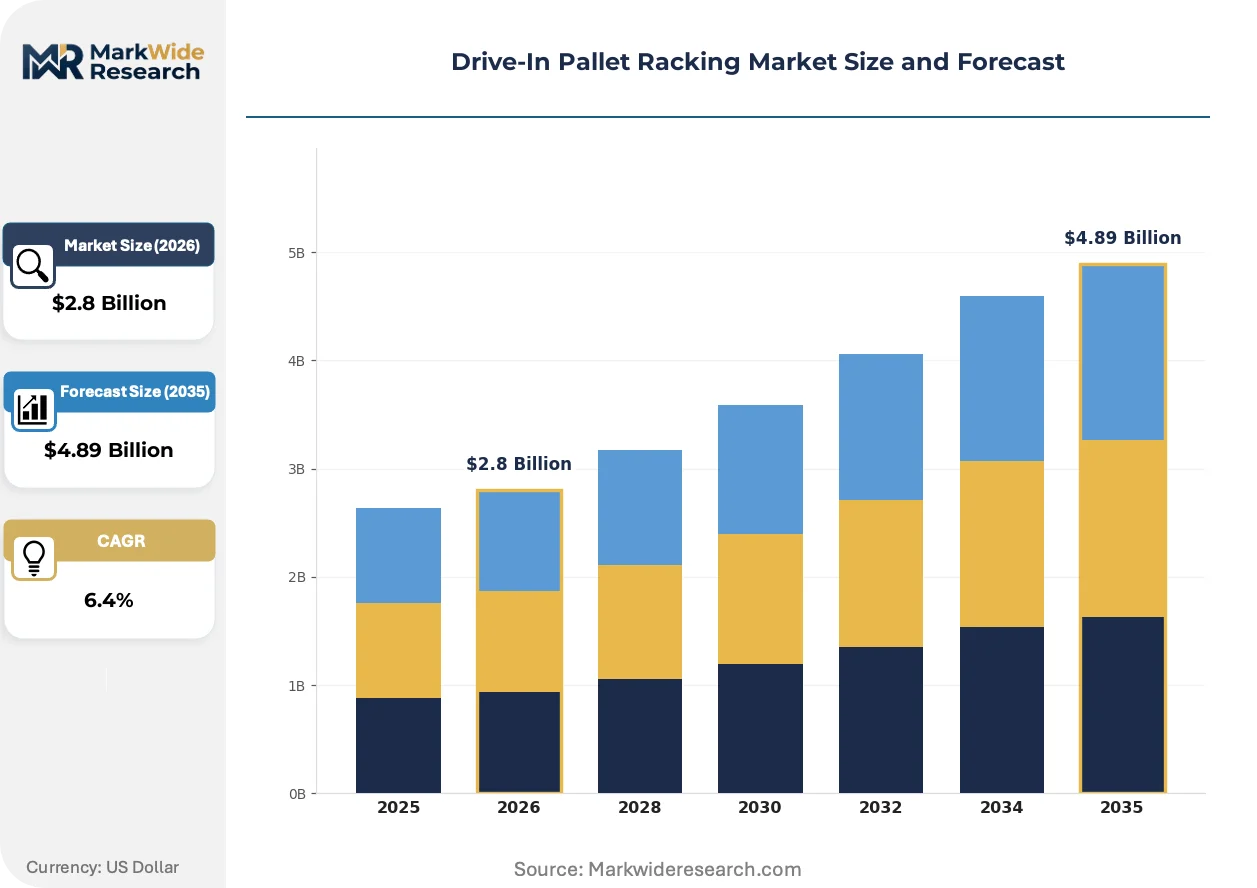
Market Dynamics
Cold-chain logistics operators are forcing warehouse density recalculations across the installed base, compressing aisle widths and accelerating lane-depth specifications beyond historical 5-pallet norms. FEM 10.2.02 and OSHA 1910.176 compliance cycles are tightening simultaneously, creating dual certification burdens for cross-border suppliers.
Growth Catalysts
- FEM 10.2.02 recertification mandates:European warehouse operators face shortened load-bearing inspection cycles, driving replacement demand for older racking installations.
- Automated guided vehicle compatibility:Distribution centers in Germany and the US Midwest are retrofitting lane clearances and floor flatness specifications to accommodate AGV navigation.
- Aluminum corrosion resistance:Pharmaceutical cold storage facilities specify aluminum uprights and beams to withstand chloride exposure in sub-zero environments.
Market Restraints
- Steel price volatility:Hot-rolled coil fluctuations compress margin predictability for North American fabricators dependent on domestic mill supply.
- Seismic zone engineering concentration:California and Japan require site-specific structural calculations that fragment design standardization.
- Drive-thru racking substitution:High-throughput distribution centers favor dual-access configurations that reduce drive-in density advantages.
Strategic Opportunities
- India cold-chain infrastructure:PLI scheme incentives for food processing and pharmaceuticals are creating first-mover warehouse densification projects.
- CE marking automation:EU Machinery Directive documentation requirements favor suppliers with integrated design-to-certification workflows.
- AGV-lane convergence:Rack manufacturers combining static storage with automated shuttle integration capture upgrade cycles in automated facilities.
Industry Challenges
- Seismic certification timelines:Site-specific structural engineering reviews extend project delivery windows in earthquake-prone zones.
- Welding inspector scarcity:Cold-formed steel rack fabrication faces qualified welder shortages in Midwest manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive-In Pallet Racking Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drive-In, Drive-Thru Racking, Mobile Drive-In, Selective Racking Material: Steel, Aluminum, Composite, Plastic End User: Retail, Wholesale, Manufacturing, Pharmaceuticals Installation Type: Permanent, Temporary, Modular, Customizable |
| Companies Covered | Mecalux, Dexion, AR Racking, Daifuku, SSI Schaefer, Hannibal Industries, Interlake Mecalux, Konstant, Unarco Material Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive-In Pallet Racking Market Shifts & Advancements
Automation compatibility is rewriting rack engineering specifications, forcing structural designers to anticipate vehicle clearances and sensor mounting before ground breaks. The convergence of static storage with mobile robotics is collapsing traditional boundaries between racking infrastructure and material handling equipment.
Modular aluminum upright systems with integrated cable management channels are supplanting welded steel configurations in pharmaceutical and food-grade cold storage. Facility operators in Switzerland and the Netherlands specify these systems for rapid reconfiguration and corrosion immunity. The shift is compressing traditional steel fabricator dominance in premium cold-chain segments.
OSHA 1910.176 enforcement emphasis on load capacity labeling and aisle width maintenance is tightening installation documentation requirements. Inspectors in Texas and Ohio manufacturing belts now demand stamped engineering drawings for modifications exceeding single-bay replacements. Third-party rack inspection services are proliferating to bridge compliance gaps.
Buyer consolidation among third-party logistics operators is compressing supplier negotiation cycles and unbundling after-sales service contracts. Large 3PLs in Germany and the US Midwest now separate rack procurement from installation and inspection services, pressuring integrated manufacturers to defend margin on hardware alone. Regional installation specialists are capturing service revenue that previously flowed to original equipment suppliers.
Drive-In Pallet Racking Market Segmentation
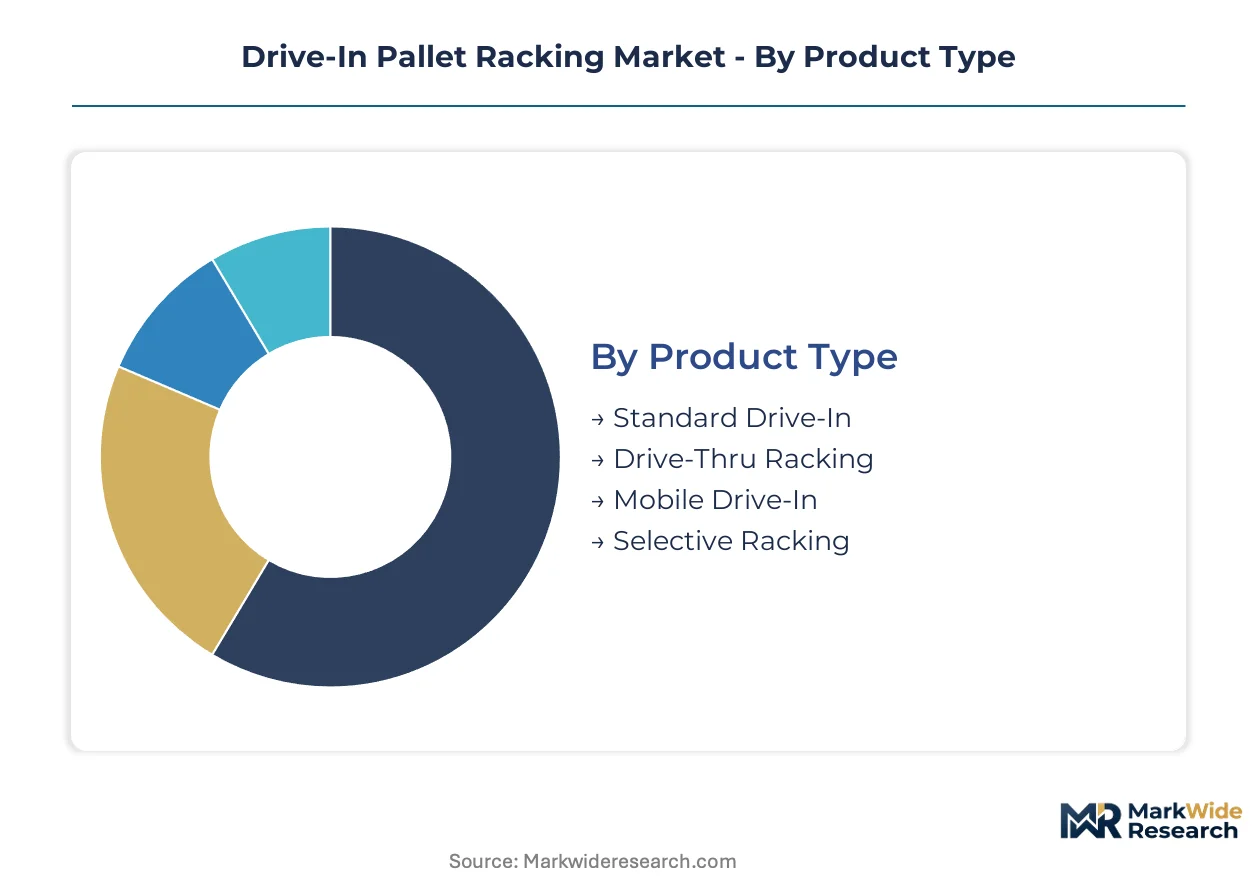
Segmentation in drive-in pallet racking determines specification pathways for warehouse density targets and compliance burdens. Procurement teams weight material fatigue resistance against automation compatibility when selecting configurations for cold-chain or high-throughput environments.
Product Type:
Substitution pressure runs strongest against single-access configurations as distribution centers prioritize throughput velocity over cubic utilization.
- Standard Drive-In:Continuous lane structures with single-entry access points maximize pallet positions per cubic meter in low-rotation inventory environments. Cold-chain operators in Germany and the US Midwest specify depths exceeding historical norms as FEM 10.2.02 recertification compresses replacement cycles.
- Drive-Thru Racking:Dual-access configurations enable first-in-first-out rotation through opposing aisle entry points. High-throughput distribution centers in the US Midwest favor this format despite density trade-offs, accelerating lane-clearance retrofits for AGV compatibility.
- Mobile Drive-In:Motorized base frames relocate entire rack arrays to open access aisles on demand.
- Selective Racking:Single-deep pallet positions with 100% selectivity compete directly against drive-in density advantages.
Standard Drive-In anchors the volume base while Drive-Thru Racking gains share at the steepest rate.
Material:
Cost tier stratification separates commodity structural grades from corrosion-resistant premium specifications in pharmaceutical and food-grade deployments.
- Steel:Cold-formed carbon steel profiles deliver fatigue resistance under cyclic forklift loading across 1,500-3,000 kilogram capacity ranges. North American fabricators in the Midwest manufacturing belt face margin compression from hot-rolled coil price volatility.
- Aluminum:Extruded upright and beam assemblies withstand chloride exposure in sub-zero pharmaceutical cold storage without protective coating maintenance. Swiss and Dutch facility operators specify aluminum for rapid reconfiguration and corrosion immunity.
- Composite:Fiber-reinforced polymer hybrids reduce weight for manual assembly in temporary installations.
- Plastic:Injection-molded structural components serve light-duty applications with minimal load requirements.
Steel commands the installed base while aluminum expands most quickly in premium cold-chain segments.
End User:
Application-specific engineering requirements fragment standardization as sectoral compliance regimes diverge on load-bearing documentation and inspection cycles.
- Retail:Seasonal inventory surges drive modular configuration demand with rapid reconfiguration capabilities. Big-box operators in Germany prioritize FEM 10.2.02 certified installations with shortened inspection intervals.
- Wholesale:High-velocity SKU rotation favors selective accessibility over maximum density in distribution center networks.
- Manufacturing:Just-in-line raw material storage integrates racking directly with production floor layouts. US Midwest automotive suppliers specify permanent installations with OSHA 1910.176 stamped engineering drawings for modification protocols.
- Pharmaceuticals:Cold-chain validation requirements mandate corrosion-resistant materials and continuous temperature monitoring integration.
Manufacturing anchors the volume base while Pharmaceuticals climbs the fastest on cold-chain infrastructure expansion.
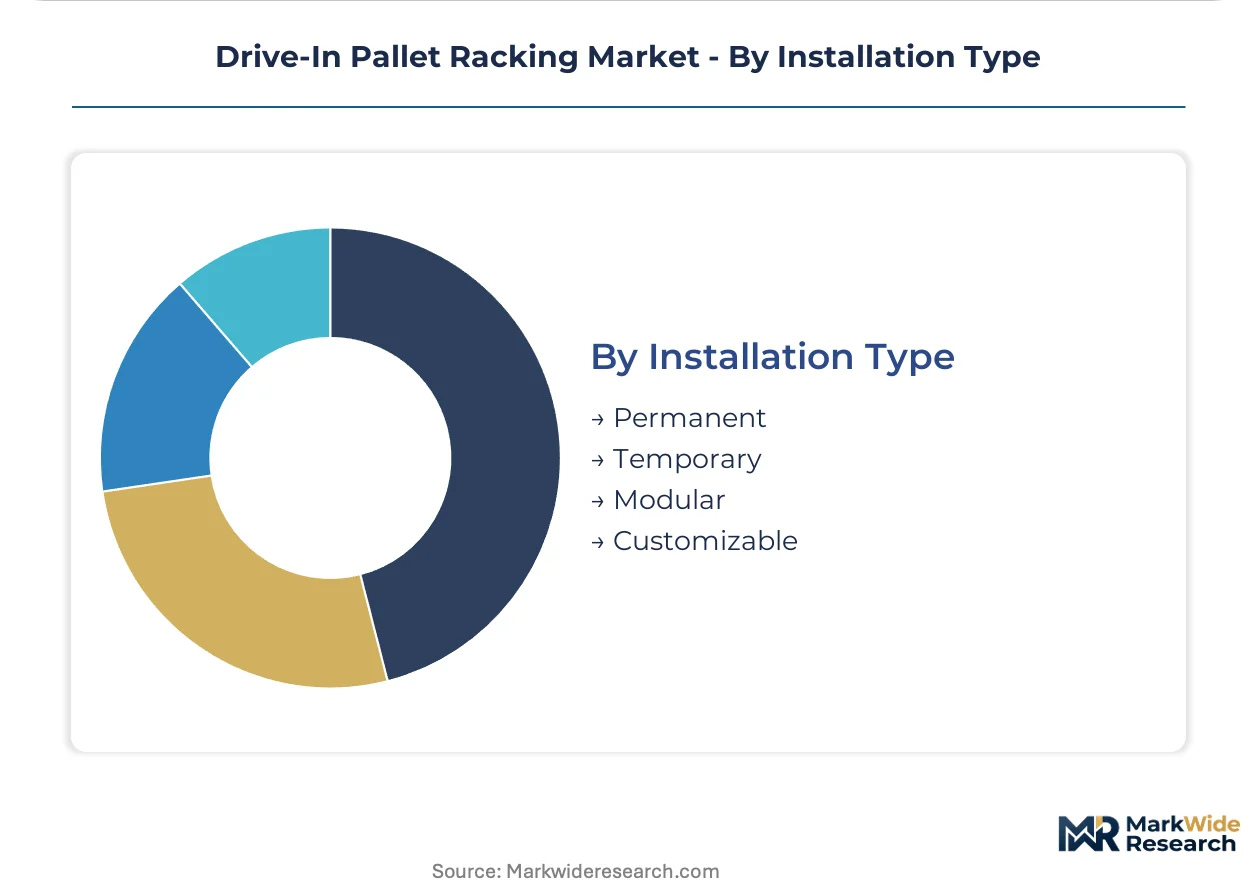
Installation Type:
Customer procurement patterns increasingly unbundle hardware from installation services, compressing margin capture for integrated suppliers.
- Permanent:Anchored structural connections with welded or bolted column bases serve long-lease industrial facilities. Seismic zone engineering in California and Japan requires site-specific calculations that fragment design standardization.
- Temporary:Freestanding or lightly anchored systems support seasonal capacity surges and project-based warehousing.
- Modular:Bolt-together components enable field reconfiguration without hot-work permits. Third-party logistics operators in Germany separate rack procurement from installation contracts, pressuring original equipment suppliers on hardware margins alone.
- Customizable:Engineered-to-order specifications accommodate non-standard pallet dimensions or automated vehicle clearances.
Permanent installations anchor the volume base while Modular configurations gain share at the steepest rate on unbundled procurement trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives for food processing and pharmaceuticals are accelerating warehouse densification projects across India. Germany's FEM 10.2.02 recertification mandates are compressing replacement cycles for aging installations. OSHA 1910.176 enforcement in the US Midwest is tightening documentation requirements for load-bearing modifications.
United States
Cold-chain logistics operators in the US Midwest are expanding lane depths beyond historical 5-pallet norms to maximize cubic utilization. OSHA 1910.176 regulations now demand stamped engineering drawings for rack modifications exceeding single-bay replacements. Automotive suppliers in Michigan and Ohio specify permanent installations with documented compliance protocols for just-in-line raw material storage.
Germany
FEM 10.2.02 European racking design standards are shortening inspection cycles for load-bearing certification, driving systematic replacement demand. The EU Machinery Directive and CE marking obligations constrain market access for non-certified manufacturers. Distribution centers in Bavaria and North Rhine-Westphalia are retrofitting lane clearances for automated guided vehicle compatibility.
India
PLI scheme incentives for food processing and pharmaceutical cold-chain infrastructure are creating first-mover warehouse densification projects. BIS standards and CDSCO cold-chain validation requirements mandate corrosion-resistant materials for sub-zero pharmaceutical storage. Processing clusters in Maharashtra and Gujarat are specifying aluminum upright systems for rapid reconfiguration capabilities.
China
GB standards and MIIT industrial upgrading programs are accelerating automation-compatible rack specifications in high-throughput distribution centers. SAMR quality certification requirements are filtering supplier qualification toward integrated design-to-manufacturing workflows. Yangtze River Delta logistics hubs are converging static storage with automated shuttle integration for e-commerce fulfillment density.
Switzerland
Swissmedic pharmaceutical cold storage regulations mandate continuous temperature monitoring integration with corrosion-resistant structural materials. Swiss building codes favor modular aluminum upright systems with integrated cable management for rapid field reconfiguration. Pharmaceutical distribution facilities in Basel and Zurich are specifying these systems to withstand chloride exposure without protective coating maintenance.
Drive-In Pallet Racking Market Competitive Landscape
Player mix skews toward integrated European fabricators with captive steel processing and automated storage integration capabilities. The vendor base separates into three strategic tiers: full-system integrators combining static racking with mobile robotics, regional steel fabricators competing on domestic raw material sourcing, and modular aluminum specialists capturing premium cold-chain segments. Dominant competitive moves include geographic footprint expansion through manufacturing co-location and technology licensing for AGV-compatible lane engineering.
Among European-integrated specialists, Mecalux anchors the full-system tier with manufacturing footprint spanning multiple countries for large-format project delivery. Daifuku occupies a position exemplifying the convergence archetype, representing suppliers whose capabilities extend beyond static racking into automated storage integration. Hannibal Industries sits within the regional fabrication tier, competing on domestic steel sourcing to control raw material cost volatility for North American clients.
| Leading Market Players |
|---|
| Mecalux |
| Dexion |
| AR Racking |
| Daifuku |
| SSI Schaefer |
| Hannibal Industries |
| Interlake Mecalux |
| Konstant |
| Unarco Material Handling |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between North American fabricators and domestic steel mills lock in raw material cost visibility while constraining margin flexibility for rack manufacturers serving the US Midwest automotive belt. These arrangements tie pricing power to mill capacity allocation rather than spot market dynamics, forcing fabricators to absorb hot-rolled coil volatility through contract renegotiation cycles.
Pricing Analysis
Certification level creates the primary spread between premium and standard rack specifications, with FEM 10.2.02 and CE-marked installations commanding hardware premiums over uncertified alternatives. Project-based pricing dominates large-format warehouse deployments, while modular aluminum systems in Swiss pharmaceutical cold storage fetch material premiums for corrosion immunity. Cost compression runs through steel-tier installations as buyer consolidation among German third-party logistics operators unbundles after-sales service contracts. Wholesale distribution centers exhibit highest price sensitivity, prioritizing throughput velocity over density-maximizing configurations.
Supply Chain Analysis
Inventory buffers for cold-formed steel coil have compressed to six-week horizons across Midwest manufacturing clusters, exposing fabricators to mill delivery volatility. Supply concentrates in Germany, the United States, and China, with European integrated manufacturers leveraging captive steel processing for margin control. Raw material dependencies center on hot-rolled carbon steel, extruded aluminum billet, and zinc coating chemistries for corrosion protection. Single-source vulnerability persists in specialized rack inspection services, where qualified welding inspectors are scarce in Ohio and Michigan industrial corridors. Distribution runs through regional installation specialists who have captured service revenue previously flowing to original equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party rack inspection and recertification services are expanding faster than hardware sales as FEM 10.2.02 and OSHA 1910.176 compliance cycles tighten across European and North American installed bases. This service-attach layer offers recurring revenue visibility that pure equipment transactions cannot match.
For Market Incumbents: Consolidate regional installation capabilities to recapture service revenue flowing to independent specialists in Germany and the US Midwest. Backward integration into captive steel processing insulates margin from hot-rolled coil volatility while securing mill allocation priority during supply constraints. Certification investment in AGV-compatible lane engineering defends positioning against automated storage integrators converging on static racking. For New Entrants and Emerging Players: Differentiate on aluminum modular systems for pharmaceutical cold-chain deployments in India and Switzerland, where BIS standards and Swissmedic regulations mandate corrosion-resistant materials. Target Maharashtra and Gujarat processing clusters for first-mover warehouse densification projects under PLI scheme incentives. Pursue design-to-certification workflow automation as a go-to-market angle, collapsing EU Machinery Directive documentation timelines that constrain non-integrated competitors. For Investors and Strategic Acquirers: Regional aluminum fabrication specialists with pharmaceutical cold-chain credentials represent the most defensible acquisition profile. These targets combine material differentiation with regulatory moats in sub-zero storage validation. Long-term viability hinges on automation convergence, where rack manufacturers with AGV lane engineering capabilities capture upgrade cycles in automated facilities. Watch for inflection when distribution center AGV penetration thresholds trigger systematic lane-clearance retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| AGV Lane Engineering Investment | Captures retrofit cycles as German distribution centers automate material handling workflows. |
| Aluminum Upright Manufacturing Scale-Up | Addresses Swiss and Indian pharmaceutical cold-chain demand for corrosion-resistant structural materials. |
| Third-Party Inspection Service Acquisition | Recaptures recurring revenue streams unbundled by consolidated 3PL procurement teams. |
| Design-to-Certification Workflow Automation | Accelerates CE marking documentation for EU Machinery Directive compliance. |
| Domestic Steel Mill Partnership | Secures hot-rolled coil allocation priority and cost visibility for North American fabricators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse operations directors, rack system procurement managers, cold-chain logistics executives, and third-party installation contractors. Secondary validation drew from FEM 10.2.02 technical documentation, OSHA 1910.176 enforcement records, EU Machinery Directive guidance, customs trade data for steel and aluminum inputs, and SEC filings of publicly listed material handling equipment manufacturers. Bottom-up project pipeline assessment was triangulated against top-down macroeconomic indicators for warehouse construction and automation investment.
Across the analysis window, volume and value outputs were modeled through segmentation by product configuration, material grade, end-use sector, and installation type. CAGRs were derived from fitted growth curves anchored to replacement cycle dynamics and cold-chain infrastructure expansion trajectories. Industry-specific forecast inputs included lane-depth specification trends, AGV compatibility retrofit rates, and regulatory recertification mandate timelines.
Material uncertainties — steel price volatility, seismic code revisions, and automated vehicle standardization — sit outside the modeled envelope and could accelerate or compress replacement demand. Forecasts reflect documented assumptions about regulatory enforcement intensity and buyer procurement pattern stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Weighbridge Market