
 Global Lifting Columns Market | 2026-2036
Global Lifting Columns Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lifting Columns Market Outlook
Skilled electromechanical engineering talent is reorganizing competitive dynamics across the Global Lifting Columns Market as automation integrators and medical OEMs compete for specialized workforce pools. LINAK AS anchors Scandinavian design leadership through captive R&D in linear actuator architectures, while TiMOTION Technology Co. Ltd. dominates manufacturing scale across Asia-Pacific production corridors. Thomson Industries Inc. differentiates through precision-ground ball screw integration within multi-stage column assemblies.
Lifting columns are telescopic linear actuation devices, typically fabricated from cold-drawn steel or aluminum extrusions with acme or ball screw drive mechanisms, engineered to provide vertical displacement loads from 500 N to 10,000 N for height-adjustable equipment platforms. Electric columns command the largest product type share due to silent operation and programmable positioning, while microprocessor-controlled technology segments are expanding fastest as IoT-enabled synchronization and collision detection become standard in premium medical and industrial installations. Hydraulic columns retain entrenched positions in heavy-construction applications where load ratings exceed electromechanical limits.
The EU Machinery Directive and CE marking requirements enforce mandatory risk assessments and emergency-stop functionality for powered lifting equipment deployed across European industrial and healthcare settings. The FDA's 510(k) clearance pathway for powered medical devices shapes product development cycles for hospital-grade lifting columns in the United States. China's GB standards and MIIT equipment safety protocols govern domestic manufacturing certification and cross-border export compliance. Stakeholders must monitor evolving interoperability standards between building management systems and networked lifting infrastructure as smart facility integration deepens.
Market Dynamics
Electromechanical automation is compressing design cycles across medical and industrial equipment sectors, forcing lifting column suppliers to synchronize firmware development with hardware platforms while managing multi-certification pipelines for cross-border deployment.
Growth Catalysts
- EU Machinery Directive compliance mandates:European healthcare facilities must retrofit powered beds and patient lifts with emergency-stop functionality and risk-assessed linear actuation, accelerating replacement demand for certified electric columns.
- China's domestic medical device production scaling:Local OEMs are expanding captive assembly of adjustable surgical tables and rehabilitation equipment, driving procurement of precision lifting mechanisms from regional supply bases.
- Ball screw precision integration:Ground-thread ball screw architectures are displacing acme screw drives in premium multi-stage columns, enabling load capacities above 6,000 N with positioning repeatability under 0.1 mm.
Market Restraints
- Cold-drawn steel input volatility:Fluctuations in specialty steel alloy pricing compress margin buffers for mid-tier column fabricators dependent on spot-market raw material sourcing.
- Supply concentration in East Asian motor manufacturing:Brushless DC motor and encoder subassembly production clusters heavily in Taiwan and coastal China, exposing buyers to single-source disruption risk.
- Hydraulic load ceiling advantage:Electromechanical columns face substitution pressure in heavy-construction applications requiring sustained thrust above 10,000 N where hydraulic systems retain performance superiority.
Strategic Opportunities
- India's hospital infrastructure expansion:Government health expenditure targets and private medical facility construction are creating first-time demand for height-adjustable equipment platforms in tier-2 and tier-3 cities.
- IoT-enabled synchronization protocols:Convergence of CANopen bus architecture with wireless mesh networking enables multi-column coordinated lift systems for automated warehouse and cleanroom applications.
- EU Green Deal embodied carbon tracking:Lifecycle assessment requirements for medical equipment procurement are favoring aluminum-extrusion columns with recycled content and regionalized supply chains.
Industry Challenges
- Embedded firmware engineering scarcity:Medical device OEMs and automation integrators compete for limited pools of electromechanical control systems specialists capable of integrating collision detection algorithms with safety-rated PLC architectures.
- FDA 510(k) clearance timeline compression:Powered patient handling devices face extended premarket review cycles when incorporating novel sensor feedback loops, delaying revenue recognition for column suppliers serving US healthcare markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lifting Columns Market |
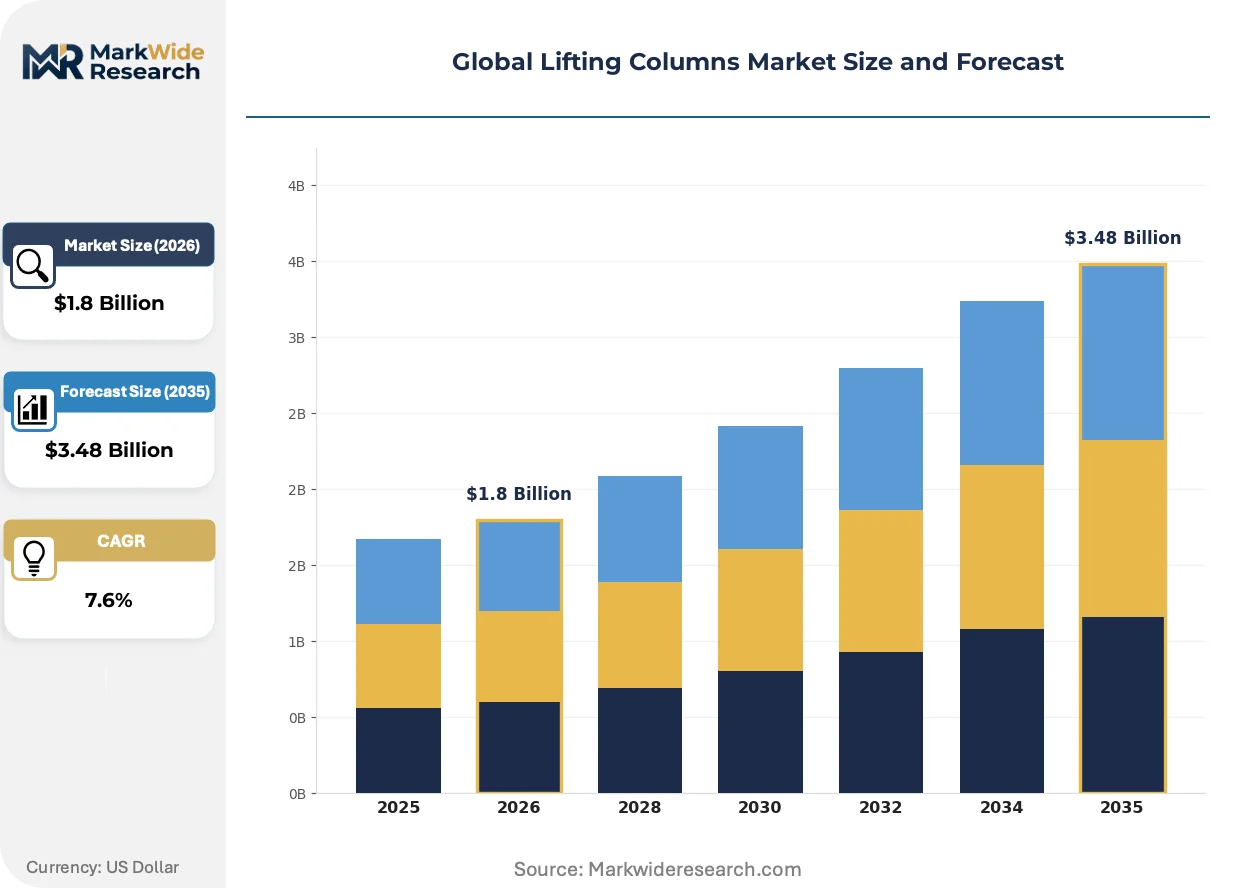
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Columns, Hydraulic Columns, Pneumatic Columns, Manual Columns Application: Industrial Automation, Medical Equipment, Furniture Industry, Construction End User: Manufacturers, Hospitals, Retailers, Contractors Technology: Electromechanical, Hydraulic Systems, Pneumatic Systems, Microprocessor-Controlled |
| Companies Covered | LINAK AS, TiMOTION Technology Co. Ltd., Thomson Industries Inc., Phoenix Mecano Inc., SUSPA GmbH, Hettich Holding GmbH and Co. oHG, B. Ketterer Sohne GmbH & Co. KG, HOERBIGER Holding AG, DIHAO Electric Zhejiang Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lifting Columns Market Strategic Shifts
Intelligent actuation architectures are redefining value capture in lifting column supply chains, as firmware-enabled positioning and predictive maintenance capabilities separate premium tier suppliers from commodity hardware fabricators.
Microprocessor-controlled drive electronics is fragmenting competitive tiers across the installed base. Hospital-grade adjustable beds and surgical tables now require programmable soft-start algorithms and position memory functions as baseline specifications. Industrial automation buyers in Germany and Japan are specifying EtherCAT-compatible column controllers for synchronized multi-axis platforms, compressing margins for suppliers lacking fieldbus integration expertise.
China's GB standards evolution and MIIT equipment safety protocols are tightening electromagnetic compatibility testing requirements for powered medical devices. Domestic manufacturers must now certify conducted emissions and immunity profiles for column-integrated motor controllers before hospital procurement eligibility. Export-oriented suppliers are redirecting R&D resources toward dual-compliant architectures satisfying both Chinese national standards and EU CE marking pathways.
Equipment-as-a-service contracting is altering capital deployment patterns in North American healthcare systems. Hospital networks in Texas and California are bundling adjustable bed fleets with maintenance-inclusive lease structures, transferring ownership risk to integrated equipment vendors. This procurement model demands lifting column suppliers provide remote diagnostic telemetry and predictive failure alerting, compressing traditional component-only sales channels.
Global Lifting Columns Market Segmentation
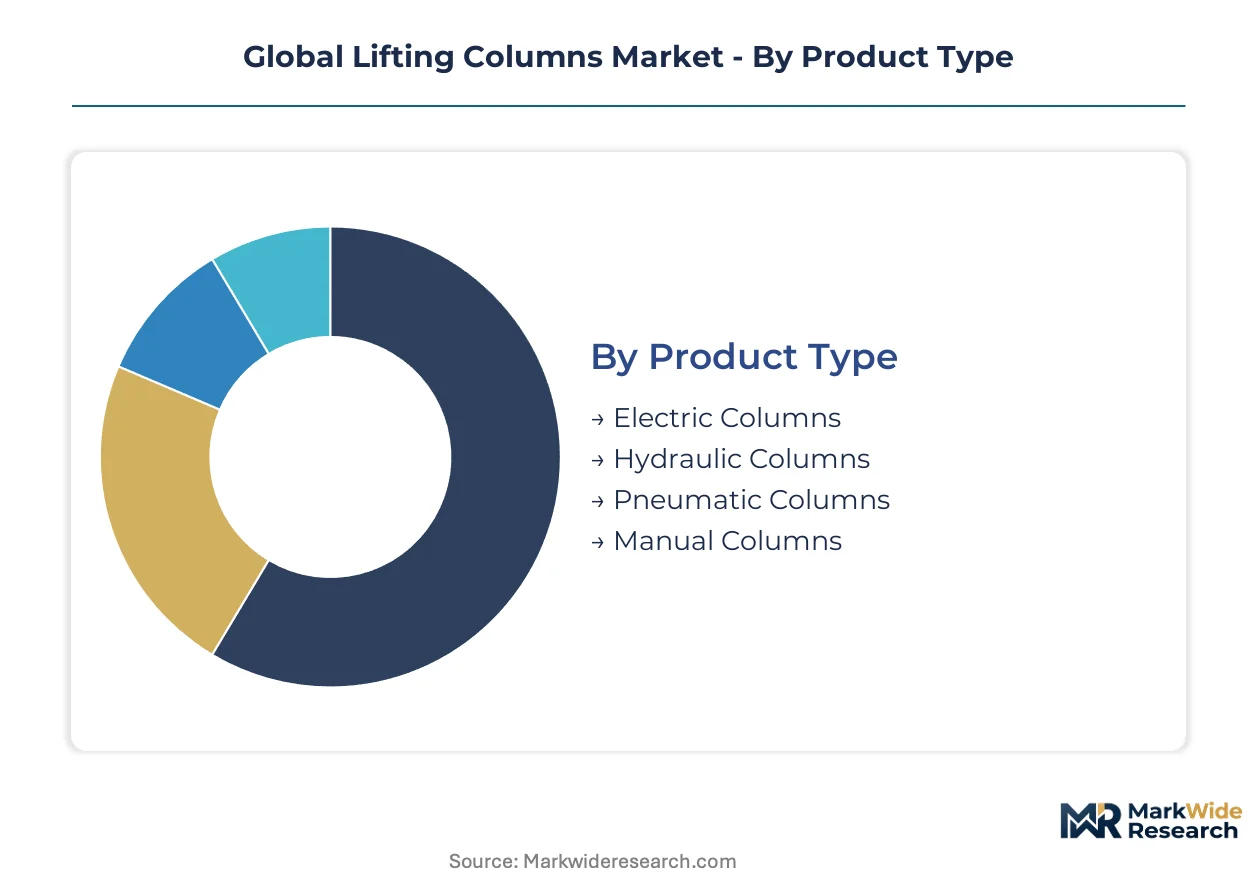
Segmentation in the Global Lifting Columns Market reveals divergent sourcing strategies across medical, industrial, and furniture end-uses. Electric and microprocessor-controlled variants concentrate in EU and US procurement pipelines, while hydraulic and pneumatic systems dominate domestic construction markets in China and India.
Product Type:
Domestic consumption clusters around electric columns in Germany, Denmark, and Sweden, where medical OEMs source precision actuators from regional supply bases. Export-led demand for hydraulic and pneumatic variants flows from Chinese fabricators serving Southeast Asian construction equipment builders.
- Electric Columns:Brushless DC motor drives with ball screw or belt transmission mechanisms deliver silent operation below 45 dB and programmable positioning repeatability within 0.1 mm. Hospital bed manufacturers in Denmark and surgical table OEMs in Germany specify these for EU Machinery Directive compliance, driving captive procurement from Scandinavian and Central European supply corridors.
- Hydraulic Columns:Pressurized fluid power systems using piston-cylinder architectures sustain continuous thrust loads exceeding 10,000 N. Chinese construction equipment fabricators and Indian infrastructure contractors specify these for heavy-lift platforms where electromechanical alternatives face thermal derating constraints.
- Pneumatic Columns:Compressed air actuation systems with diaphragm or piston drives suit explosive-environment applications in chemical processing and mining operations.
- Manual Columns:Mechanical screw or crank mechanisms without powered actuation serve cost-sensitive furniture markets and backup safety systems.
Electric columns command the established base. The steepest expansion runs through microprocessor-controlled variants.
Application:
Cost tier differentiation separates premium medical installations from volume industrial automation. Medical equipment applications absorb the highest per-unit pricing, while furniture industry procurement drives scale economies for standardized column architectures.
- Industrial Automation:Multi-axis synchronized lifting platforms for automated storage and retrieval systems, cleanroom material handling, and precision assembly lines. German automotive suppliers and Japanese electronics manufacturers specify EtherCAT-compatible columns for sub-millimeter positioning accuracy in battery cell assembly and semiconductor wafer handling.
- Medical Equipment:Adjustable hospital beds, surgical tables, patient lifts, and rehabilitation devices requiring IEC 60601-1 electrical safety certification and emergency-stop functionality. US hospital networks and EU healthcare procurement frameworks mandate these specifications, filtering supplier eligibility to firms with FDA 510(k) and CE marking pathways.
- Furniture Industry:Height-adjustable desks, tables, and workstations for commercial office and home office markets.
- Construction:Temporary lifting platforms, scaffolding elevation systems, and material hoists for building sites.
Medical equipment absorbs the premium tier. Furniture industry procurement is climbing the fastest as hybrid workplace normalization sustains demand.
End User:
Volume concentration among manufacturers versus fragmented procurement by contractors and retailers reshapes sales channel economics. Direct OEM relationships dominate medical and industrial segments, while distributor networks serve scattered construction and retail demand.
- Manufacturers:Industrial automation integrators, medical device OEMs, and furniture producers sourcing columns as subassemblies for finished equipment. German automotive suppliers and Chinese domestic automation builders maintain the largest procurement volumes, negotiating multi-year supply agreements with firmware customization clauses.
- Hospitals:Direct procurement by healthcare networks for replacement bed fleets and facility renovation projects. Texas and California hospital systems are bundling adjustable equipment into equipment-as-a-service contracts, shifting supplier relationships toward maintenance-inclusive partnerships.
- Retailers:Office furniture dealers and e-commerce platforms selling height-adjustable desks and tables to commercial and consumer end-users.
- Contractors:Construction firms renting or purchasing temporary lifting equipment for specific project phases.
Manufacturers anchor procurement volumes. Hospital direct purchasing is expanding most quickly as US healthcare networks consolidate supplier relationships.
Technology:
Supply concentration in East Asian motor and controller manufacturing shapes technology adoption curves. Electromechanical and microprocessor-controlled systems depend on Taiwan and coastal China for brushless DC motors, encoders, and drive electronics.
- Microprocessor-Controlled:Embedded firmware architectures enabling position memory, soft-start algorithms, collision detection, and IoT telemetry integration. Premium medical bed producers in Sweden and industrial automation specialists in Japan specify these for predictive maintenance capabilities and synchronized multi-column operation.
- Electromechanical:AC or DC motor drives with mechanical transmission elements including ball screws, belt drives, or rack-and-pinion systems. Standard configurations serve cost-optimized industrial and furniture applications where programmable positioning is secondary to reliability and first-cost minimization.
- Hydraulic Systems:Fluid power transmission using pumps, valves, and cylinders for high-force applications.
- Pneumatic Systems:Compressed air power transmission for hazardous environment deployment.
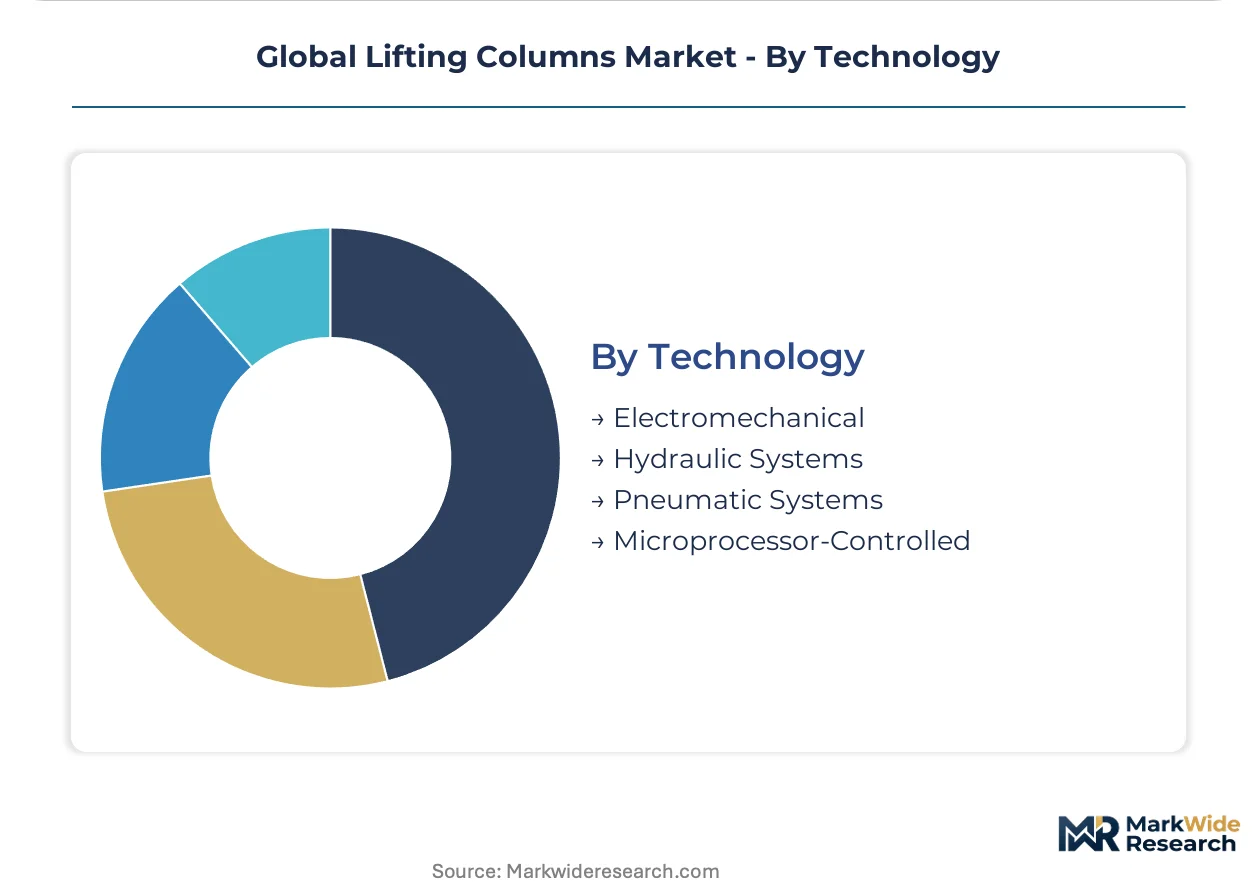
Electromechanical systems retain the installed base. Microprocessor-controlled architectures are gaining share fastest as firmware-enabled differentiation separates premium suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT equipment safety protocols and GB standards are tightening electromagnetic compatibility requirements for powered medical devices, reshaping certification pathways for lifting column suppliers serving domestic hospital procurement.
United States
Texas and California hospital networks are consolidating supplier relationships through equipment-as-a-service contracts for adjustable bed fleets. FDA 510(k) clearance pathways for powered patient handling devices extend premarket review cycles when novel sensor feedback loops are incorporated. Medical device OEMs in the Minneapolis-St. Paul corridor are scaling firmware customization partnerships with column suppliers.
Germany
EU Machinery Directive compliance mandates are accelerating replacement demand for certified electric columns across Bavarian and North Rhine-Westphalian healthcare facilities. The country's automotive suppliers in Stuttgart and Wolfsburg are specifying EtherCAT-compatible columns for battery cell assembly lines. CE marking requirements enforce mandatory risk assessments for powered lifting equipment deployed in industrial settings.
China
Domestic automation equipment builders in the Yangtze River Delta are scaling local sourcing of precision lifting mechanisms for adjustable surgical tables. MIIT equipment safety protocols now require conducted emissions certification for column-integrated motor controllers before hospital procurement eligibility. Shenzhen and Suzhou production corridors host concentrated brushless DC motor and encoder subassembly manufacturing.
Japan
Electronics manufacturers in the Nagoya and Osaka industrial zones are demanding sub-millimeter positioning accuracy for semiconductor wafer handling applications. METI industrial automation incentives are supporting synchronized multi-axis platform development. Precision assembly specialists in the Chubu region are integrating predictive maintenance telemetry into cleanroom material handling systems.
India
Government health expenditure targets and private medical facility construction in Maharashtra and Karnataka are creating first-time demand for height-adjustable equipment platforms. CDSCO medical device regulations are harmonizing with international standards for powered patient handling equipment. Tier-2 and tier-3 cities across Gujarat and Tamil Nadu are expanding hospital infrastructure with adjustable bed procurement.
Global Lifting Columns Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Scandinavian and German firms commanding premium positioning through captive R&D in linear actuator architectures while Asian manufacturers compete on production scale. The market structure separates firmware-enabled positioning specialists from commodity hardware fabricators, with medical certification pathways acting as tier gates. Two strategic archetypes dominate: vertically integrated electromechanical system builders and modular component suppliers serving automation integrators. Competitive moves center on multi-certification pipeline management for cross-border deployment and strategic partnerships with hospital network procurement consortia.
Within the integrated European tier, LINAK AS and SUSPA GmbH represent design-led archetypes with Scandinavian and German engineering heritage respectively. TiMOTION Technology Co. Ltd. anchors the Asia-Pacific manufacturing scale vector. These three occupy positions spanning premium medical specification through volume industrial automation supply.
| Leading Market Players |
|---|
| LINAK AS |
| TiMOTION Technology Co. Ltd. |
| Thomson Industries Inc. |
| Phoenix Mecano Inc. |
| SUSPA GmbH |
| Hettich Holding GmbH and Co. oHG |
| B. Ketterer Sohne GmbH & Co. KG |
| HOERBIGER Holding AG |
| DIHAO Electric Zhejiang Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Taiwanese brushless DC motor fabs shapes margin structures across electric lifting column tiers, concentrating cost-competitive supply in East Asian production corridors while European medical OEMs absorb premium pricing for CE-marked, firmware-enabled architectures.
Pricing Analysis
Geographic price spreads separate Scandinavian and German premium suppliers from Chinese volume fabricators by 40-60% at equivalent load ratings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—FDA 510(k) and CE-marked columns command substantial premiums over GB-standard domestic Chinese units. Pricing pressure stems from cold-drawn steel alloy volatility compressing mid-tier fabricator margins. Hospital networks exhibit lowest price sensitivity due to equipment-as-a-service contracting, while furniture industry procurement drives aggressive cost negotiation.
Supply Chain Analysis
Taiwan Strait logistics chokepoints expose global column supply to semiconductor and encoder shipment disruptions. Manufacturing concentrates in China, Taiwan, and Germany—Shenzhen and Suzhou host motor controller subassembly, while Stuttgart anchors precision ball screw grinding. Raw material dependencies include cold-drawn steel tubing, aluminum extrusions with recycled content, and rare-earth permanent magnets for brushless DC motors. Single-source vulnerability runs through East Asian encoder manufacturing. Distribution runs through direct OEM partnerships for medical and industrial segments, with distributor networks serving fragmented construction and retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lifting Columns Market sits in early-cycle expansion as hospital infrastructure buildouts in India and Southeast Asia drive first-time penetration of height-adjustable medical equipment platforms.
For Market Incumbents: Secure firmware engineering talent pools through captive hiring in Stuttgart and Minneapolis-St. Paul corridors, where electromechanical control systems specialists face poaching from automation integrators. Lock in multi-year aluminum extrusion supply agreements with recycled content certification to preempt EU Green Deal embodied carbon tracking requirements. Defend against Chinese domestic automation builders by accelerating FDA 510(k) clearance pipelines for sensor-integrated column architectures.
For New Entrants and Emerging Players: Predictive maintenance telemetry bundling represents an under-served service layer where incumbent hardware suppliers lack software monetization capabilities. Target India's tier-2 and tier-3 hospital construction markets through CDSCO-compliant column architectures priced below European premium tiers. Pursue equipment-as-a-service partnership structures with Texas and California hospital networks seeking maintenance-inclusive supplier relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-enabled positioning specialists serving medical OEMs with multi-year service contracts. Long-term viability favors suppliers with dual-certification capabilities spanning FDA 510(k) and CE marking pathways. Monitor MIIT equipment safety protocol evolution as signal for Chinese domestic market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Customization Partnership | Enables collision detection algorithms for FDA 510(k) clearance in powered patient handling devices. |
| Dual-Certification Architecture Investment | Positions suppliers for simultaneous EU CE marking and China GB standards compliance. |
| Recycled Aluminum Supply Agreement | Supports EU Green Deal embodied carbon tracking for hospital procurement eligibility. |
| Predictive Maintenance Platform Launch | Captures equipment-as-a-service revenue streams from Texas and California hospital networks. |
| EtherCAT Fieldbus Integration | Meets German automotive supplier specifications for battery cell assembly line synchronization. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with electromechanical engineering directors, hospital procurement managers, biomedical equipment planners, and automation integration specialists; and secondary validation against FDA 510(k) filings, EU Machinery Directive compliance databases, MIIT equipment safety protocol updates, and customs trade data for linear actuator components. Bottom-up triangulation of column shipment volumes by application and top-down reconciliation against medical equipment production statistics anchored market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation, technology tier adoption curves, end-user procurement patterns, and regional regulatory cluster penetration. CAGRs were derived from installed base replacement cycles and greenfield hospital infrastructure buildout trajectories. Industry-specific inputs included EU Machinery Directive retrofit mandates, China's domestic medical device production scaling targets, and IoT-enabled synchronization protocol adoption rates in automated warehouse applications.
Forecasts assume regulatory continuity in FDA 510(k) review timelines, EU Machinery Directive enforcement, and China MIIT electromagnetic compatibility testing requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as hospital capital expenditure cycles and cold-drawn steel input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Industrial Lift Ladder Market