
 Dock Levelers Market | 2026-2036
Dock Levelers Market Size, Share, and Industry Trends Forecast 2026-2036
Dock Levelers Market Analysis
A capital-intensity divergence between integrated manufacturers and assembly-focused competitors is redrawing competitive boundaries in the dock levelers market. Hörmann leverages in-house steel fabrication and door-system integration to sustain margin control across European distribution networks. Rite-Hite anchors its position through North American service density and aftermarket parts logistics. SEPPES competes aggressively on cost-engineered mechanical units for Asia-Pacific warehouse developers.
Dock levelers are height-adjustable bridge platforms, typically fabricated from structural steel with load capacities ranging from 30,000 to 80,000 pounds, designed to create a safe transition between a loading dock and a vehicle bed. The primary purpose is to eliminate gaps and height differentials that cause forklift damage, product loss, and worker injury during material transfer operations. Hydraulic type units command the premium tier due to push-button operation and automatic return functionality, while mechanical segments retain volume leadership in cost-sensitive developing markets. Steel material construction dominates installed base economics, though aluminum variants are gaining specification share in corrosive environments and weight-restricted floor applications.
OSHA regulations in the United States mandate fall protection and load-rated specifications for dock equipment, while the EU Machinery Directive requires CE conformity assessment for powered levelers sold across member states. China's SAMR enforces GB standards for industrial lifting platforms that affect import eligibility and domestic manufacturer certification paths. Buyers must weigh total cost of ownership against regional compliance burdens when specifying equipment for multi-national facility rollouts.
Market Dynamics
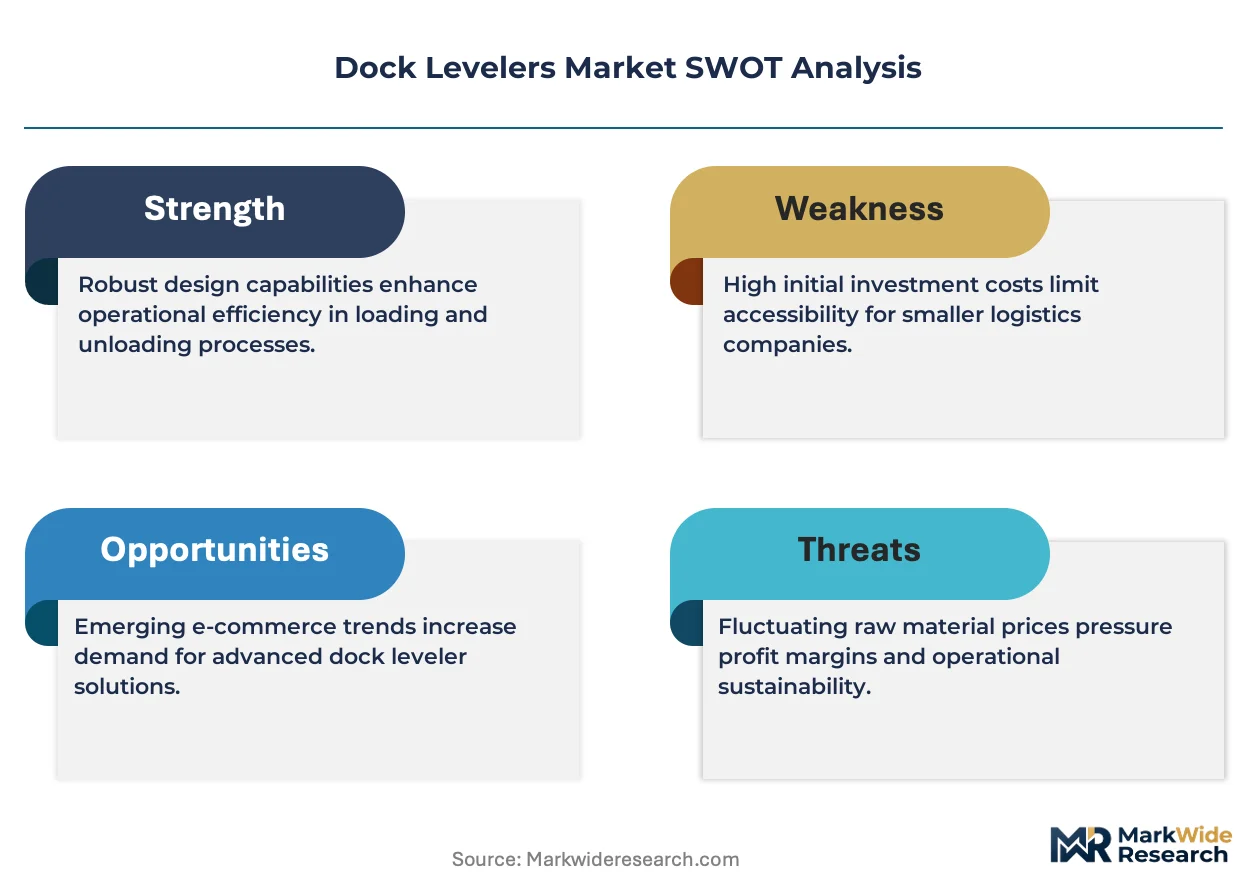
OSHA workplace safety mandates and the EU Machinery Directive are tightening certification requirements for powered dock levelers, forcing manufacturers to re-engineer product lines and absorb compliance costs while buyers delay replacement cycles to await certified inventory.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics operators in the United States and Germany are installing hydraulic units with automatic return functionality to accelerate trailer turnaround times during peak seasonal volume.
- OSHA fall protection mandates:The U.S. regulator's updated loading dock safety standards are compelling facility managers to replace outdated mechanical levelers with load-rated, gap-sealed platforms certified for forklift operations.
- Steel fabrication integration:Manufacturers with captive steel processing capabilities are compressing lead times and insulating margins against raw material volatility in European distribution networks.
Market Restraints
- Structural steel price volatility:Fluctuations in hot-rolled steel coil costs directly compress margins for assembly-focused competitors lacking backward integration into metal fabrication.
- CE conformity assessment timelines:The EU Machinery Directive's extended certification paths for powered levelers delay product launches and tie up working capital in testing documentation.
- Aluminum substitution in corrosive environments:Food processing and chemical handling facilities in coastal China are specifying lightweight aluminum platforms that displace traditional steel units in niche applications.
Strategic Opportunities
- India warehouse modernization:The country's PLI scheme for logistics infrastructure is attracting foreign capital into automated distribution centers requiring specification-grade dock equipment.
- IoT-enabled predictive maintenance:Sensor-integrated levelers transmitting load-cycle data to cloud platforms are creating recurring revenue streams through aftermarket service contracts.
- SAMR GB standard harmonization:China's alignment of industrial lifting platform regulations with international norms is reducing import friction for European and North American manufacturers.
Industry Challenges
- Certified technician scarcity:Hydraulic system diagnostics and repair require specialized training that outpaces vocational program output in Midwestern U.S. manufacturing corridors.
- Legacy dock retrofit complexity:Aging concrete pits and non-standard door heights in older industrial facilities complicate installation of modern leveler specifications without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dock Levelers Market |
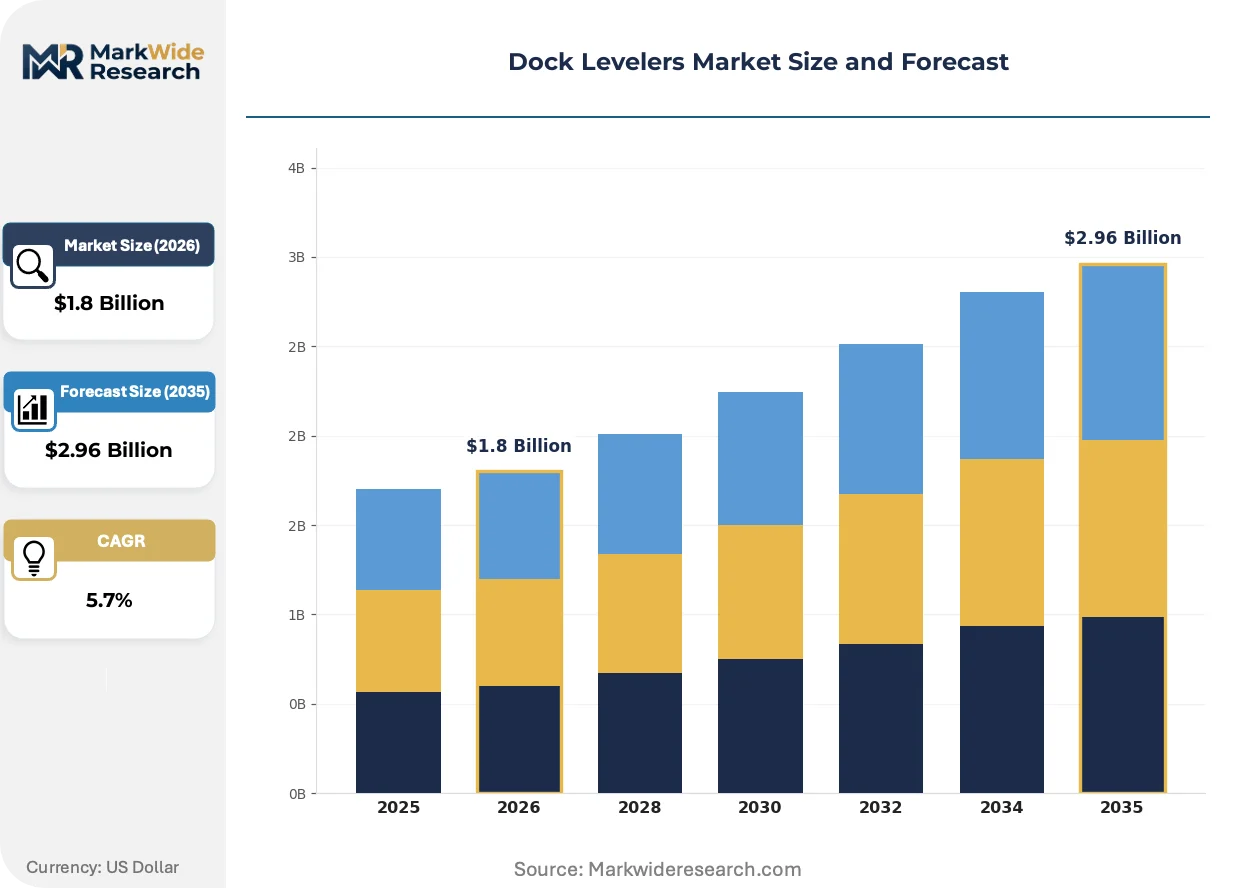
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydraulic, Mechanical, Air-Powered, Manual Material: Steel, Aluminum, Composite, Plastic Application: Warehousing, Manufacturing, Distribution Centers, Retail Installation: Inground, Surface-Mounted, Portable, Fixed |
| Companies Covered | Hörmann, Kelley, Rite-Hite, Nordock, Pentalift, Blue Giant, McGuire, SEPPES, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dock Levelers Market Emerging Trajectories
Automation and connectivity are redefining dock leveler specifications as buyers prioritize operational data visibility and remote diagnostics over purely mechanical reliability. Equipment suppliers are repositioning around software-enabled service models.
Embedded load sensors and edge computing modules are fragmenting the traditional equipment-only procurement model. Cold storage operators in Germany are specifying these units to track pallet weight distribution and prevent forklift tip-overs in temperature-controlled environments. The technology is compressing differentiation between premium hydraulic and mid-tier mechanical segments as data capabilities become table stakes.
The EU Machinery Directive's 2023 updates to CE marking requirements for powered industrial platforms are extending third-party assessment timelines. Manufacturers serving cross-border European distribution networks are consolidating certification documentation and pre-qualifying testing laboratories to reduce launch delays. German engineering firms with established Notified Body relationships are capturing specification share from competitors facing backlog bottlenecks.
Third-party logistics providers are unbundling equipment procurement from installation and maintenance contracts. Large warehouse developers in the United States are engaging directly with regional installers while sourcing levelers through competitive bidding platforms, compressing traditional distributor margins. This pattern concentrates purchasing power among national facility operators and fragments local dealer networks.
Dock Levelers Market Segmentation
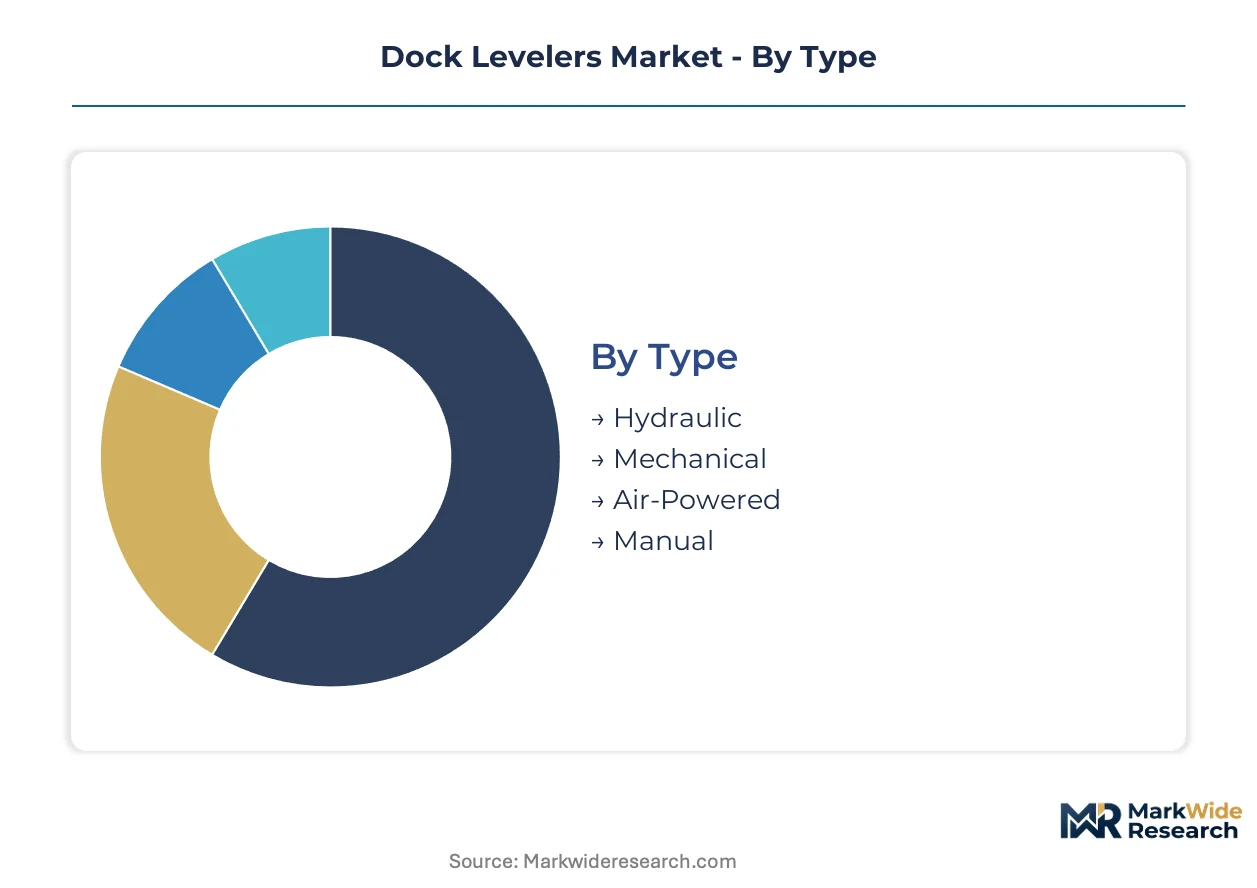
Dock leveler procurement decisions hinge on regulatory compliance burdens, operational intensity, and facility infrastructure constraints. Buyers segment specifications across power systems, structural materials, end-use environments, and mounting configurations to align capital deployment with duty cycles and safety mandates.
Type:
OSHA and the EU Machinery Directive impose divergent certification timelines on powered versus non-powered systems, reshaping manufacturer product roadmaps and buyer replacement schedules.
- Hydraulic:Push-button actuation with automatic return functionality eliminates manual positioning hazards. Third-party logistics operators in Germany and the United States specify these units to compress trailer turnaround times during peak seasonal volume surges.
- Mechanical:Spring-counterbalanced platforms require manual deployment via pull-chain operation. Cost-sensitive warehouse developers in India and Southeast Asia favor this segment for greenfield distribution centers where labor costs offset speed requirements.
- Air-Powered:Pneumatic actuation using facility compressed air supplies offers intermediate automation without hydraulic fluid maintenance. Food processing facilities specify these units where contamination risks prohibit petroleum-based systems.
- Manual:Basic hinged plates with no powered assist serve low-throughput loading bays and temporary installations. Small-scale retail receiving docks in secondary cities deploy these for occasional freight deliveries.
Established volume favors Mechanical; emerging adoption favors Hydraulic.
Material:
Raw material cost trajectories and environmental exposure conditions drive specification splits between structural metals and engineered alternatives.
- Steel:Hot-rolled structural steel dominates installed base economics with load capacities from 30,000 to 80,000 pounds. Integrated manufacturers with captive fabrication capabilities in Germany compress lead times and insulate margins against coil price volatility.
- Aluminum:Lightweight extruded platforms resist corrosion in coastal chemical handling environments. China's food processing facilities along eastern seaboards are displacing traditional steel units where weight-restricted floors and salt-air exposure converge.
- Composite:Fiber-reinforced polymer constructions eliminate rust maintenance in pharmaceutical cleanrooms. Biotech manufacturing clusters specify these for washdown compatibility.
- Plastic:Molded polymer decks serve light-duty retail and temporary event logistics. Exhibition centers and seasonal distribution pop-ups favor these for rapid deployment without structural pit modifications.
Steel retains procurement dominance; Aluminum gains specification share fastest in corrosive applications.
Application:
End-use intensity varies dramatically across facility types, with throughput velocity and safety incident exposure dictating specification tier.
- Warehousing:High-cycle e-commerce fulfillment networks demand load-rated platforms with fall protection integration. Automated distribution centers in the United States specify hydraulic units with embedded sensor diagnostics.
- Manufacturing:Just-in-time production lines require synchronized dock equipment with building automation systems. Automotive suppliers in Germany specify CE-certified powered levelers with programmable logic controller interfaces.
- Distribution Centers:Cross-dock operations prioritize rapid trailer exchange over deep storage functionality. Regional parcel hubs favor mechanical units with minimal maintenance intervals.
- Retail:Back-of-store receiving bays handle intermittent freight volumes with limited dock door counts. Big-box chains standardize on surface-mounted units to avoid concrete pit construction costs.
Warehousing commands specification premiums; Retail concentrates volume at economy tiers.
Installation:
Existing facility constraints and capital deployment flexibility determine mounting configuration selection across new construction and retrofit contexts.
- Inground:Recessed pit installations preserve interior floor space and enable flush dock approaches. Modern logistics parks in China specify these for seamless forklift transition from warehouse to trailer bed.
- Surface-Mounted:Above-grade platforms eliminate concrete cutting in legacy industrial buildings. Aging Midwestern U.S. manufacturing corridors favor these where original dock infrastructure predates current safety standards.
- Portable:Mobile units with integrated ramps serve temporary loading needs and emergency capacity expansion. Construction sites and disaster relief distribution points deploy these for rapid operational standup.
- Fixed:Permanent structural integrations anchor high-throughput dedicated facilities. Dedicated automotive assembly plant docks specify these for 24/7 operational reliability.
Inground dominates new construction specifications; Surface-Mounted captures retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering firms command specification premiums through established Notified Body relationships, while Chinese manufacturers compete aggressively on cost-engineered mechanical units for Asia-Pacific warehouse developers. This pricing-power asymmetry shapes procurement patterns across multinational facility rollouts.
United States
Third-party logistics operators are installing hydraulic units with automatic return functionality to accelerate trailer turnaround times during peak seasonal volume surges. OSHA's updated loading dock safety standards compel facility managers to replace outdated mechanical levelers with load-rated, gap-sealed platforms. The Midwest manufacturing corridor faces certified technician scarcity for hydraulic system diagnostics and repair.
Germany
Automotive suppliers specify CE-certified powered levelers with programmable logic controller interfaces for just-in-time production lines. The EU Machinery Directive's extended certification paths for powered levelers delay product launches and tie up working capital in testing documentation. Cold storage operators in Bavaria are specifying sensor-integrated units to track pallet weight distribution and prevent forklift tip-overs.
China
Food processing facilities along the eastern seaboard are specifying lightweight aluminum platforms where weight-restricted floors and salt-air exposure converge. SAMR enforces GB standards for industrial lifting platforms that affect import eligibility and domestic manufacturer certification paths. Modern logistics parks in the Yangtze River Delta specify inground installations for seamless forklift transition from warehouse to trailer bed.
India
Cost-sensitive warehouse developers favor mechanical units for greenfield distribution centers where labor costs offset speed requirements. The country's PLI scheme for logistics infrastructure is attracting foreign capital into automated distribution centers requiring specification-grade dock equipment. Regional parcel hubs in Maharashtra concentrate volume at economy-tier mechanical specifications with minimal maintenance intervals.
Japan
Biotech manufacturing clusters specify fiber-reinforced polymer constructions for washdown compatibility in pharmaceutical cleanrooms. METI's industrial equipment efficiency guidelines influence procurement specifications for automated distribution networks. The Kanto region around Tokyo drives premium-tier hydraulic adoption for high-cycle e-commerce fulfillment operations.
Dock Levelers Market Vendor Landscape
Concentration sits with integrated manufacturers possessing captive steel fabrication capabilities and established service networks. The vendor base stratifies across three tiers: premium engineering specialists with full-system integration, mid-scale fabricators competing on regional installation density, and cost-focused assemblers sourcing standardized components. Dominant competitive moves include backward integration into metal processing to compress lead times and insulate margins against raw material volatility, plus geographic expansion through distributor acquisition to capture aftermarket parts logistics.
Among European engineering specialists, Hörmann leverages in-house steel fabrication and door-system integration to sustain margin control. Rite-Hite anchors its position through North American service density. SEPPES occupies a position within the cost-engineered tier for Asia-Pacific warehouse developers. These three exemplify the strategic archetypes reshaping procurement relationships as third-party logistics providers unbundle equipment procurement from installation contracts.
| Leading Market Players |
|---|
| Hörmann |
| Kelley |
| Rite-Hite |
| Nordock |
| Pentalift |
| Blue Giant |
| McGuire |
| SEPPES |
| ASSA ABLOY |
| Others |
Supply Flow & Price Mechanics
Captive steel fabrication capacity in Germany compresses lead times and insulates margin floors against hot-rolled coil volatility, concentrating pricing power among integrated manufacturers while assembly-focused competitors absorb margin compression from raw material swings.
Pricing Analysis
Configured-to-order hydraulic units with embedded sensor diagnostics command premium spreads over standard mechanical specifications, with price differentiation anchored in CE certification grade and after-sales service bundling. Pricing stratifies across premium, standard, and economy tiers, with cost compression in the mechanical segment intensifying as Chinese assemblers compete on bare-bone specifications. Third-party logistics operators show least price sensitivity due to throughput velocity requirements, while retail warehouse developers in secondary Indian markets concentrate volume at economy tiers.
Supply Chain Analysis
Inventory buffers and extended lead times for CE conformity documentation are tying up working capital as manufacturers pre-qualify Notified Body testing relationships. Supply concentrates in Germany, China, and the United States, with structural steel coil, hydraulic actuators, and edge computing modules as critical inputs. Single-source vulnerability sits with European Notified Body capacity bottlenecks for powered leveler certification. Distribution runs through national facility operators unbundling procurement from regional installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as e-commerce fulfillment networks unbundle equipment procurement from installation contracts, creating niche entry points for specialized service providers and component innovators.
For Market Incumbents: Fortify backward integration into captive steel processing to compress lead times against coil price volatility, while deepening Notified Body relationships to capture specification share from competitors facing CE certification backlogs. Prioritize aftermarket parts logistics density as third-party logistics providers fragment traditional distributor margins.
For New Entrants and Emerging Players: Anchor in India's PLI-driven warehouse modernization wave, targeting cost-engineered mechanical specifications for greenfield distribution centers in Maharashtra and Gujarat. Penetrate through direct engagement with regional facility developers bypassing incumbent distributor networks, leveraging labor-cost arbitrage to offset speed disadvantages.
For Investors and Strategic Acquirers: Sensor-integrated platform specialists with established cloud analytics capabilities represent the most compelling acquisition archetype as IoT-enabled predictive maintenance creates recurring revenue streams. Long-term viability hinges on software-enabled service model transition rather than equipment-only margins. Monitor CE conformity assessment timeline normalization as inflection signal for European market re-entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Insulates margins against hot-rolled coil volatility for German and North American manufacturers. |
| IoT Sensor Platform Development | Enables predictive maintenance contracts with cold storage operators in Bavaria and Tokyo. |
| Notified Body Relationship Consolidation | Reduces CE certification delays for powered levelers across European distribution networks. |
| Regional Installer Network Acquisition | Captures aftermarket parts logistics density as procurement unbundling fragments distributor margins. |
| Aluminum Platform Specification Push | Displaces steel units in coastal Chinese food processing facilities with weight-restricted floors. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with facility maintenance directors, plant engineers at automotive suppliers, OEM procurement teams, and aftermarket service heads; and secondary validation through customs/trade data, SEC filings, OSHA regulatory documentation, and EU Machinery Directive implementation records. Bottom-up installation tracking across logistics parks and manufacturing corridors triangulated against top-down steel consumption and hydraulic component shipment patterns.
Across the analysis window, the forecasting framework modeled power system type, structural material grade, end-use facility intensity, and mounting configuration complexity. CAGRs derived from segment-level demand elasticity and replacement cycle dynamics, with inputs including e-commerce fulfillment network expansion trajectories, regulatory compliance timeline shifts, and raw material cost trajectory assumptions.
Material uncertainties — steel price volatility, CE certification backlog duration, and technician training program output — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Global Lifting Columns Market