
 Crushing Screening Equipment Market | 2026-2036
Crushing Screening Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Crushing Screening Equipment Market Insights
The capital-intensity divergence between integrated manufacturers and component assemblers is unwinding competitive stability in the crushing screening equipment sector. Sandvik AB leverages its captive metallurgy and tooling supply chains to sustain margin control across jaw and cone crusher lines. Terex Corporation anchors its position through specialized mobile screening plants for quarrying contractors in North American and European markets. McCloskey International competes aggressively on modular plant configurations that reduce site installation timelines for demolition contractors.
Crushing screening equipment encompasses machinery that reduces mineral and construction material feedstock to specified particle gradations through compressive, impact, or attrition forces, with throughput ratings typically spanning 100 to 1,200 tonnes per hour depending on rotor diameter, chamber geometry, and drive configuration. These systems serve mining extraction and construction aggregates producers by enabling downstream processing efficiency, transportation economy, and product specification compliance. Jaw crushers occupy the mature volume core of the product type spectrum, while VSI crushers capture expanding margin pools in manufactured sand applications where particle shape control commands price premiums. Electromechanical technology is displacing hydraulic actuation in urban recycling operations where noise ordinances and energy recovery requirements reshape procurement criteria for demolition contractors.
EPA enforcement of National Ambient Air Quality Standards and MEE particulate emission limits in China are tightening crusher enclosure and dust suppression mandates, forcing design revisions to intake hoods and fabric filter systems. The EU Green Deal's embedded carbon reporting for construction machinery is redirecting R&D investment toward electrified drivetrains and regenerative braking in European-sold units. Stakeholders must monitor how converging emissions accounting rules across EPA, MEE, and EU frameworks reshape total cost of ownership calculations and fleet replacement timing for mining firms and materials suppliers.
Market Dynamics
The capital-intensity gap between integrated metallurgy producers and component assemblers is forcing structural repositioning across the crushing screening equipment sector. Fleet operators in mining and quarrying now prioritize total cost of ownership over upfront equipment pricing as emissions compliance costs compound through operational lifecycles.
Growth Catalysts
- EPA particulate enforcement:Mining operators in the United States are accelerating crusher enclosure retrofits and dust suppression upgrades to meet National Ambient Air Quality Standards, triggering replacement demand for legacy cone and jaw installations.
- Iron ore belt concentration:Brazil's Carajás and Quadrilátero Ferrífero regions are seeing capital deployment from major producers aligned with ANVISA occupational dust limits, driving demand for high-throughput screening systems.
- Electromechanical drivetrains:European quarrying contractors are specifying regenerative braking and electrified crushing systems to satisfy EU Green Deal embedded carbon reporting requirements for construction machinery.
Market Restraints
- Specialized alloy supply concentration:Manganese steel and chromium carbide overlay plate production clusters in select metallurgical centers, exposing crusher liner and wear part manufacturers to input volatility and logistics bottlenecks.
- Hydraulic system legacy lock-in:Established mining fleets face technical friction retrofitting electromechanical actuation into existing mobile crusher chassis, slowing technology transition timelines.
- MEE enforcement variance:Inconsistent provincial implementation of China's particulate emission standards creates compliance uncertainty for multinational equipment suppliers operating across multiple prefectures.
Strategic Opportunities
- Urban demolition electrification:European contractors operating under municipal noise ordinances in cities like Berlin and Amsterdam represent underserved demand for battery-powered mobile crushing units with sub-75 dB operating profiles.
- Manufactured sand specification premiums:VSI crusher technology capturing particle shape control requirements in concrete aggregate markets commands pricing power as natural sand extraction faces regulatory restriction.
- Modular plant rapid deployment:Demolition contractors in North American metropolitan markets are specifying containerized crushing modules that reduce site installation from weeks to days, creating channel preference for flexible configuration suppliers.
Industry Challenges
- Field service technician scarcity:Specialized hydraulic and electromechanical maintenance expertise for high-tonnage crushing systems remains concentrated among aging workforce cohorts, constraining aftermarket service expansion.
- Multi-jurisdiction certification timelines:Equipment suppliers must sequence CE marking, EPA verification, and MEE compliance testing in parallel, extending product launch cycles for globally distributed crusher lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crushing Screening Equipment Market |
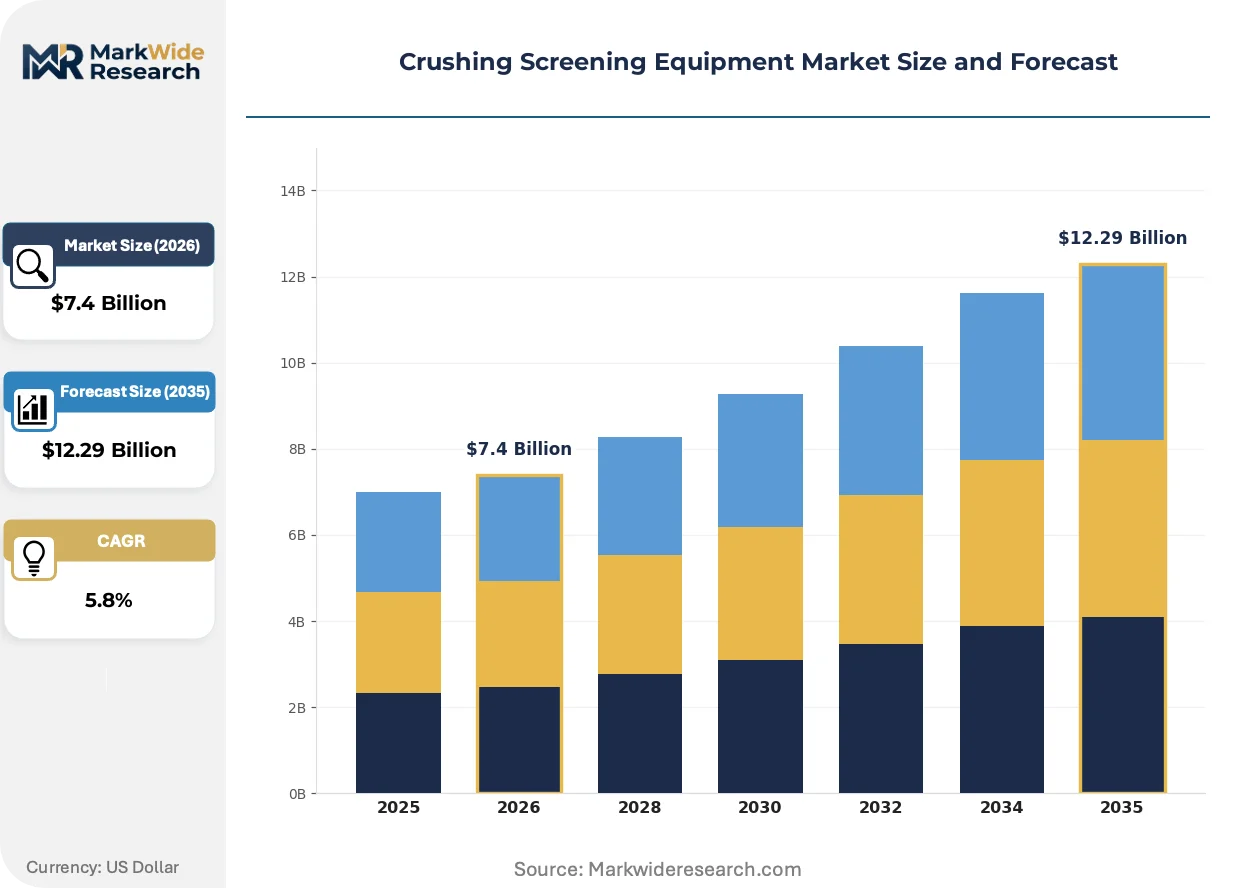
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jaw Crushers, Cone Crushers, Impact Crushers, VSI Crushers Technology: Hydraulic, Mechanical, Pneumatic, Electromechanical Application: Construction Aggregates, Mining Extraction, Recycling Operations, Quarrying End User Industry: Mining Firms, Construction Companies, Demolition Contractors, Materials Suppliers |
| Companies Covered | Astec Industries, Inc., Kleemann GmbH, Terex Corporation, thyssenkrupp Industrial Solutions AG, Komatsu Ltd., Sandvik AB, McCloskey International, Caterpillar Inc., Metso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crushing Screening Equipment Market Trends and Innovations
Active transformation in crushing screening equipment centers on drivetrain electrification, emissions accountability frameworks, and procurement model restructuring. These forces are compressing technology refresh cycles and reshaping supplier-customer relationships across mining and construction verticals.
Electromechanical crushing systems with regenerative braking and energy recovery circuits are supplanting traditional hydraulic actuation in urban recycling and quarrying applications. Demolition contractors in noise-sensitive European and North American municipalities are specifying these configurations to meet municipal decibel limits while reducing fuel consumption. The shift is compressing demand for hydraulic component suppliers and elevating margin capture toward integrated electromechanical system providers.
The EU Green Deal's embedded carbon reporting mandate for construction machinery is redirecting R&D investment toward lifecycle emissions documentation and electrified powertrains. Equipment sold into European markets must now certify upstream supply chain carbon intensity, forcing design revisions to steel sourcing and manufacturing location decisions. Mining firms operating across EU jurisdictions are prioritizing suppliers with verified carbon accounting, creating procurement preference differentiation.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete performance-based modules. Large mining operators in Australia and Canada are separating wear parts supply from technical service, sourcing liners and mantles through independent distributors while retaining OEM field support for major overhauls. This bifurcation is most visible in iron ore and copper extraction operations with mature fleet management capabilities and centralized procurement functions.
Crushing Screening Equipment Market Segmentation
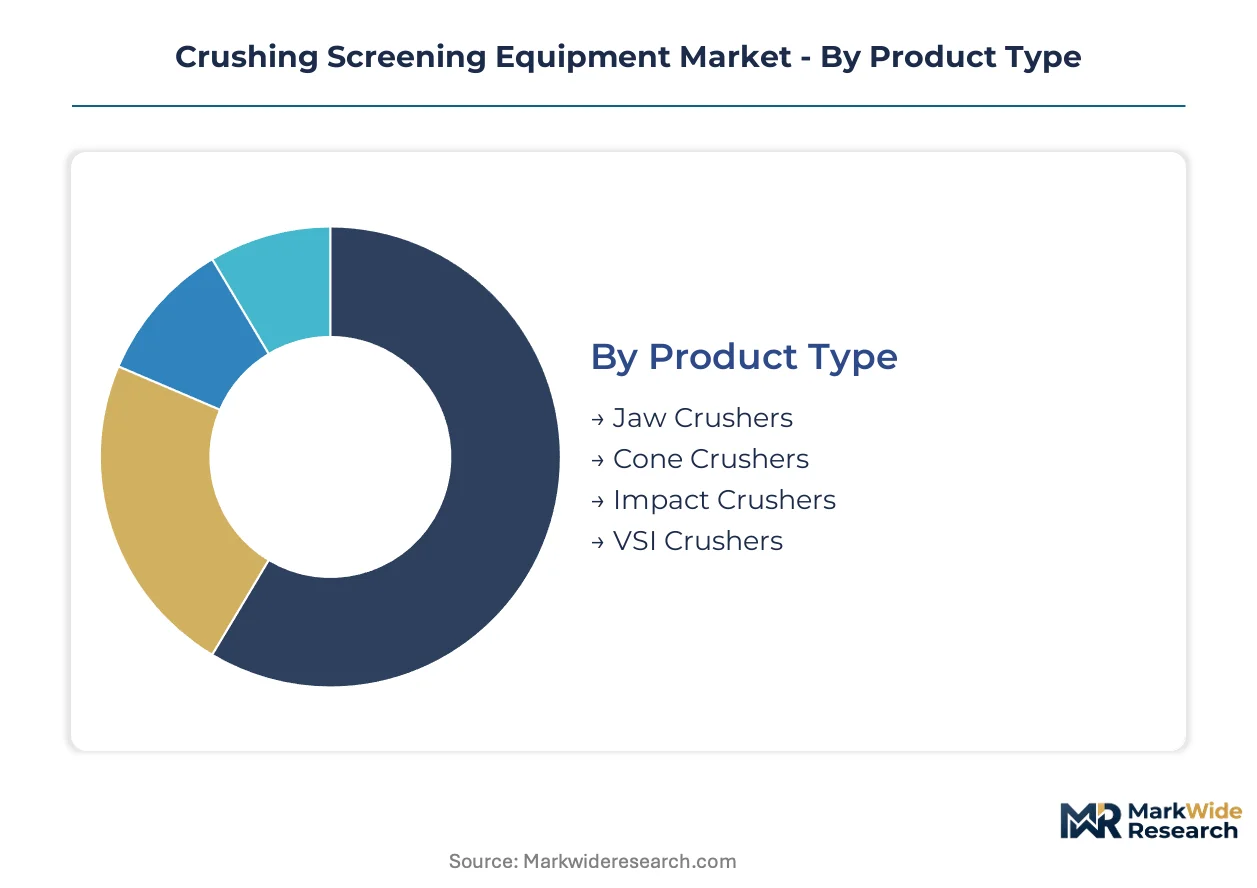
Segmentation in crushing screening equipment reveals how procurement patterns split between high-volume mining deployments and specialized urban recycling configurations. Equipment specifications diverge sharply across geographies, with EPA enforcement in the United States, EU Green Deal carbon accounting in Europe, and ANVISA dust limits in Brazil each driving distinct technology preferences.
Product Type:
Jaw crushers dominate domestic replacement cycles in mature mining markets, while VSI technology captures export demand from manufactured sand specifications tightening worldwide.
- Jaw Crushers:Fixed and mobile configurations with toggle plate mechanisms process hard rock feedstocks up to 1,500mm inlet dimensions. Fleet operators in Australia's Pilbara and Canada's oil sands prioritize these units for iron ore and bitumen processing, where EPA and provincial emissions rules mandate enclosure retrofits on aging installations.
- VSI Crushers:Vertical shaft impactors with autogenous and semi-autogenous rotor designs control particle angularity for concrete aggregate specifications. Demand concentrates in Brazil's Quadrilátero Ferrífero, where Vale's capital programs and ANVISA-aligned occupational limits accelerate replacement of legacy cone installations with high-throughput VSI systems for pellet feed production.
- Cone Crushers:Compression crushing with eccentric bushing drives serves secondary and tertiary reduction stages in hard rock quarries.
- Impact Crushers:Horizontal shaft designs with adjustable curtain settings target softer feedstocks in limestone and recycling applications.
Jaw crushers hold the largest share; momentum sits with VSI technology as natural sand extraction faces regulatory restriction.
Technology:
Cost tiers separate established hydraulic fleets from premium electromechanical systems commanding price premiums in noise-sensitive European municipalities.
- Electromechanical:Servo-driven actuation with regenerative braking circuits reduces energy consumption and decibel output below 75 dB. Demolition contractors in Berlin and Amsterdam specify these configurations to satisfy municipal noise ordinances while meeting EU Green Deal embedded carbon reporting requirements for construction machinery procurement.
- Hydraulic:Traditional fluid power systems with piston accumulators dominate installed base in North American mining operations. Established fleets in the United States face technical friction retrofitting electromechanical actuation into existing mobile chassis, slowing transition timelines despite EPA particulate enforcement accelerating enclosure upgrades.
- Mechanical:Direct drive linkages and cam mechanisms persist in entry-level stationary plants for developing market quarrying.
- Pneumatic:Compressed air actuation occupies niche applications in explosive atmosphere environments and underground mining.
Hydraulic technology retains the largest installed base; electromechanical configurations are climbing the fastest as carbon accounting tightens.
Application:
Volume concentrates in mining extraction, while margin expansion tracks recycling operations where regulatory complexity creates specification premiums.
- Mining Extraction:High-tonnage primary crushing and screening trains process run-of-mine ore for downstream concentration. Brazil's Carajás iron ore belt and Australia's Pilbara region drive demand for 1,000+ tonne per hour systems, with fleet renewal programs tied to EPA-style emissions enforcement and MEE particulate limits in supplier export markets.
- Recycling Operations:Mobile and semi-mobile configurations process construction and demolition waste for secondary aggregate markets. Contractors in North American metropolitan areas specify containerized modules that reduce site installation timelines from weeks to days, creating preference for flexible configuration suppliers serving LEED certification and landfill diversion mandates.
- Construction Aggregates:Stationary and portable plants produce specified gradations for infrastructure concrete and asphalt.
- Quarrying:Hard rock dimension stone and crushed stone operations utilize tracked mobile units for face extraction.
Mining extraction holds the largest share; recycling operations gain share fastest as landfill restrictions tighten.
End User Industry:
Customer sophistication separates integrated mining firms with centralized procurement from fragmented demolition contractors purchasing through rental channels.
- Mining Firms:Large operators in Australia and Canada unbundle service contracts into discrete performance modules, sourcing wear parts through independent distributors while retaining OEM field support for major overhauls. These firms prioritize total cost of ownership calculations as emissions compliance costs compound through operational lifecycles.
- Demolition Contractors:Urban recycling specialists in European and North American cities specify battery-powered mobile units with rapid deployment configurations. Procurement concentrates through equipment rental channels for project-based work, with municipal noise ordinances in cities like Amsterdam and Berlin filtering technology selection toward electromechanical systems.
- Construction Companies:General contractors and aggregate producers purchase stationary plants for long-term quarry operations.
- Materials Suppliers:Independent aggregate and ready-mix concrete operators specify mid-range throughput systems for regional market supply.
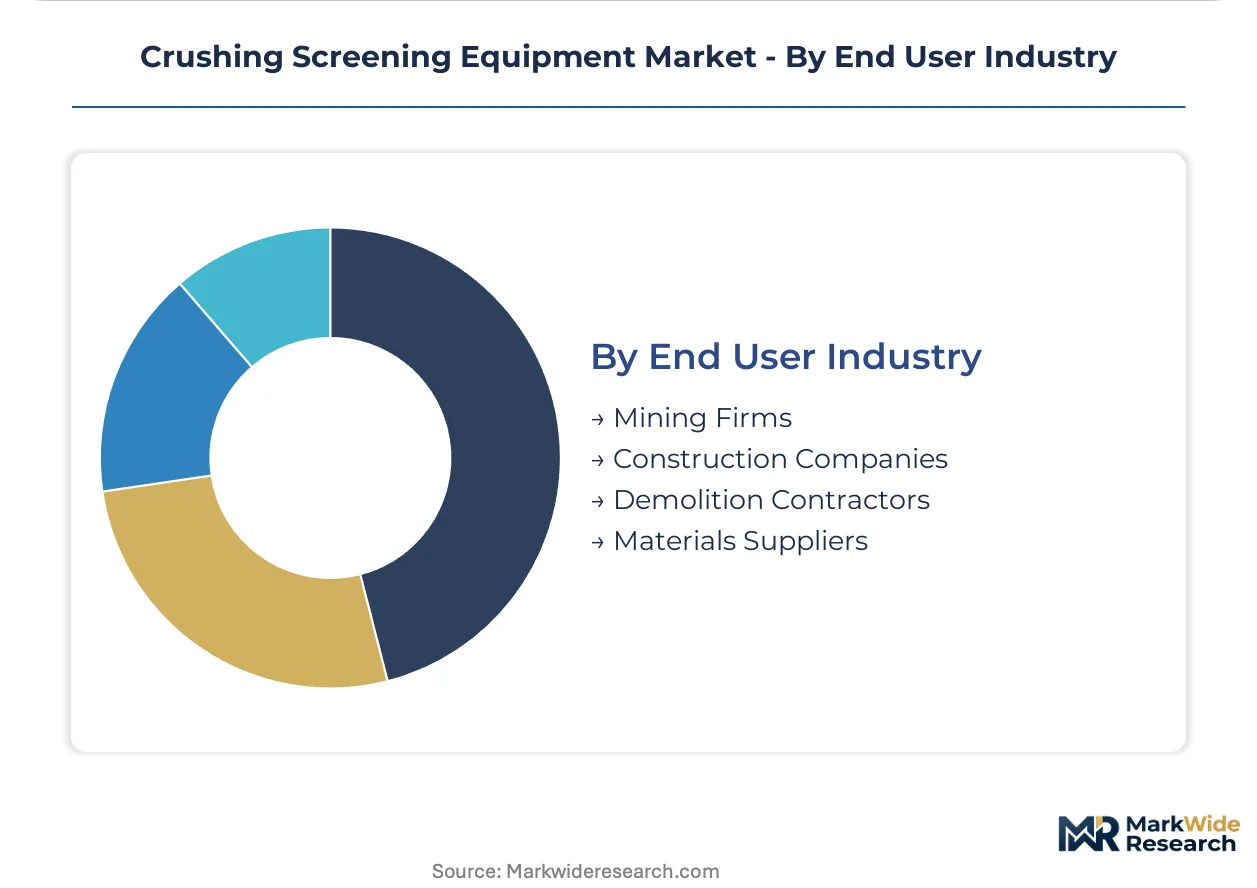
Mining firms hold the largest share; demolition contractors represent the steepest expansion trajectory as urban recycling infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers command pricing premiums in Australia's Pilbara iron ore belt that exceed Brazilian margins by 15-20 percent, reflecting divergent regulatory enforcement intensity and fleet sophistication levels. This asymmetry shapes capital deployment patterns across mining jurisdictions.
United States
EPA enforcement of National Ambient Air Quality Standards drives crusher enclosure retrofits and dust suppression upgrades across Appalachian coal operations and Southwest copper districts. Mining operators in Arizona and Nevada accelerate replacement cycles for legacy cone installations to meet particulate limits. Fleet renewal concentrates in the Mountain West where copper-molybdenum extraction faces tightening regional haze regulations.
Brazil
ANVISA-aligned occupational dust limits and Vale's capital spending accelerate high-throughput screening system deployment in the Carajás and Quadrilátero Ferrífero iron ore belts. State-level environmental licensing in Minas Gerais province enforces stricter particulate controls than federal baselines. Equipment demand clusters around Belo Horizonte engineering procurement hubs serving pellet feed production expansion.
Australia
Western Australia's Pilbara region sustains premium equipment pricing through integrated mining firm procurement centralization and total cost of ownership calculations. State environmental protection authorities enforce dust management plans that exceed federal baselines, favoring enclosed crushing trains. Fleet renewal programs concentrate in the Port Hedland-Karratha corridor tied to iron ore export capacity expansion.
Germany
EU Green Deal embedded carbon reporting redirects quarrying contractor procurement toward electromechanical systems with regenerative braking in the North Rhine-Westphalia limestone belt. Municipal noise ordinances in Berlin and Hamburg filter mobile crusher selection toward sub-75 dB configurations. Equipment specification concentrates in the Bavarian aggregates sector where CSRD-aligned sustainability disclosure affects supplier qualification.
China
MEE particulate emission enforcement variance across provinces creates compliance complexity for equipment suppliers serving the Shanxi coal belt and Sichuan copper districts. National dual carbon goals accelerate electromechanical system trials in Yangtze River Delta urban recycling operations. Demand clusters in the Pearl River Delta where Guangdong provincial standards exceed national baselines for construction waste processing.
Crushing Screening Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the crushing screening equipment sector. Integrated metallurgy producers with captive tooling supply chains sustain margin control through backward integration into manganese steel and chromium carbide overlay production. Component assemblers compete on modular plant configurations and rapid site deployment timelines. Strategic moves center on portfolio diversification into electromechanical drivetrains and geographic expansion through regional service hub establishment.
Among European-integrated industrial groups, thyssenkrupp Industrial Solutions AG and Sandvik AB exemplify the metallurgy-captive archetype controlling upstream wear part supply chains. Terex Corporation anchors the North American mobile equipment specialist position. Kleemann GmbH represents the premium-tier German fabrication tradition serving quarrying contractors with high-specification configurations. These three occupy distinct competitive vectors without direct head-to-head confrontation across identical customer segments.
| Leading Market Players |
|---|
| Astec Industries, Inc. |
| Kleemann GmbH |
| Terex Corporation |
| thyssenkrupp Industrial Solutions AG |
| Komatsu Ltd. |
| Sandvik AB |
| McCloskey International |
| Caterpillar Inc. |
| Metso Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Australian iron ore operators and integrated metallurgy suppliers lock in manganese steel access while stabilizing liner replacement costs against spot market volatility. These contracts embed EPA compliance cost-sharing clauses that transfer enclosure retrofit risk from mining firms to equipment vendors, compressing margin visibility for component assemblers competing on standardized jaw crusher configurations.
Pricing Analysis
Configured-to-order pricing for electromechanical crushing systems commands 20-35 percent premiums over standard hydraulic units in European quarrying markets. Three-tier pricing structure across premium, standard, and economy levels separates regenerative-braking configurations from conventional diesel-hydraulic fleets and entry-level mechanical drives. Cost compression in mid-tier hydraulic segments intensifies as Brazilian iron ore producers consolidate procurement through Vale-engineering hubs. Demolition contractors in Amsterdam and Berlin exhibit lowest price sensitivity, prioritizing sub-75 dB noise compliance over capital expenditure minimization.
Supply Chain Analysis
Strait of Malacca transit routes for manganese ore concentrates from South African mines to Chinese smelters expose crusher liner manufacturers to logistics bottlenecks and bunker fuel cost volatility. Production clusters in Sweden, Germany, and Japan supply chromium carbide overlay plate and specialized servo-drive actuators. Raw material dependencies center on high-carbon ferromanganese, rare-earth permanent magnets, and synthetic hydraulic fluids. Single-source vulnerability concentrates in Swedish specialty steel mills serving Sandvik AB and thyssenkrupp Industrial Solutions AG. Distribution runs through OEM direct sales for mining fleets and rental channel partners for demolition contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical drivetrain displacement of hydraulic systems constitutes a high-growth disruption, with EU Green Deal embedded carbon reporting forcing technology refresh cycles that compress incumbent replacement revenue windows.
For Market Incumbents: Compound metallurgy-captive advantages through backward integration into manganese steel recycling streams serving Australian Pilbara operators. Deepen field service technician training pipelines to counter workforce scarcity constraining aftermarket expansion. Defensive positioning requires rapid CE marking acquisition for electromechanical configurations before MEE enforcement variance resolves toward stricter national baselines. For New Entrants and Emerging Players: Lead with battery-powered mobile crushing units targeting Berlin and Amsterdam municipal noise ordinances where established OEMs lack sub-75 dB portfolios. Urban demolition electrification represents the most penetrable white-space, with containerized rapid-deployment configurations offering channel differentiation against hydraulic legacy fleets. Go-to-market execution should prioritize equipment rental partnerships over direct mining fleet sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated metallurgy producers with captive wear part supply chains serving Australian and Canadian iron ore operators. Five-to-ten year viability favors suppliers with verified carbon accounting documentation qualifying for EU procurement preference. Acquisition target archetype: electromechanical system specialists with MEE compliance testing capabilities. Signal to watch: provincial implementation convergence toward stricter particulate limits in Shanxi and Sichuan provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Drivetrain Transition | Regenerative braking configurations satisfy EU Green Deal carbon reporting for Berlin quarrying contractors. |
| Backward Integration into Manganese Recycling | Captive secondary metallurgy supply secures liner cost stability against South African ore volatility. |
| MEE Compliance Certification Investment | Parallel EPA verification and CE marking accelerates product launch cycles for Chinese export markets. |
| Urban Demolition Rental Channel Expansion | Equipment rental partnerships capture project-based procurement from Amsterdam demolition specialists. |
| Field Service Technician Training Pipeline | Specialized electromechanical expertise counters aging workforce constraints in Australian aftermarket operations. |
Research Methodology
Cross-validation between maintenance director interviews at Australian iron ore operators and SEC 10-K filings from integrated equipment manufacturers anchors the qualitative findings. Primary fieldwork encompassed plant engineers at Brazilian pellet feed facilities, aftermarket service heads at North American demolition contractors, and OEM procurement teams in Germany's North Rhine-Westphalia limestone belt. Secondary validation drew from EPA enforcement action databases, EU ETS carbon accounting disclosures, and ANVISA occupational exposure guidelines. Bottom-up unit shipment modeling triangulates against top-down mining capital expenditure tracking.
Sensitivity analysis around electromechanical adoption rates and manganese steel price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology actuation method, application intensity, and end-user procurement sophistication. CAGRs derive from equipment replacement cycle analysis tied to emissions compliance cost accumulation. Industry-specific forecast inputs incorporate Vale capital program disclosures and MEE provincial enforcement variance indices.
The analysis sits within stated boundaries; outcomes outside sustained EPA particulate enforcement and EU Green Deal carbon reporting adoption would require recalibration. Forecasts reflect documented assumptions regarding fleet renewal timing and technology transition friction. Practitioners should keep alternative scenarios live as MEE provincial implementation patterns and ANVISA occupational limit revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Motorized Decoiler Machine Market