
 Froth Flotation Equipment Market | 2026-2036
Froth Flotation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Froth Flotation Equipment Market Analysis
Junior mining ventures and battery-material developers are bifurcating demand once dominated by large base-metal conglomerates. Metso Outotec leverages its integrated technology portfolio to anchor premium mechanical flotation contracts across Nordic copper belts. FLSmidth competes through dense aftermarket service networks that sustain recurring revenue in African gold circuits. Eriez Flotation differentiates via specialized column flotation systems designed for coarse particle recovery.
Froth flotation equipment encompasses vessels, impellers, air sparging systems, and reagent dosing skids engineered to separate hydrophobic mineral particles from aqueous slurry through selective bubble attachment, typically operating at pulp densities between 25% and 40% solids by weight. Mechanical flotation cells retain the largest installed base due to proven scale-up reliability in sulfide concentrators, though column flotation is gaining share in molybdenum and coal cleaning where wash-water circuits improve grade. Hybrid flotation technology is expanding fastest among lithium spodumene processors seeking finer grind size compatibility without secondary classification stages.
EPA tailings standards in the United States and Chile's SMA environmental enforcement are forcing operators to validate flotation circuit water recovery rates and reagent containment before permit renewal. China's MEE discharge limits for mineral processing effluent are accelerating domestic procurement of closed-loop flotation plants with integrated thickener returns. Stakeholders must monitor how jurisdictional carbon border adjustments and scope-three emissions accounting reshape capital allocation between newbuild concentrators and retrofit upgrades.
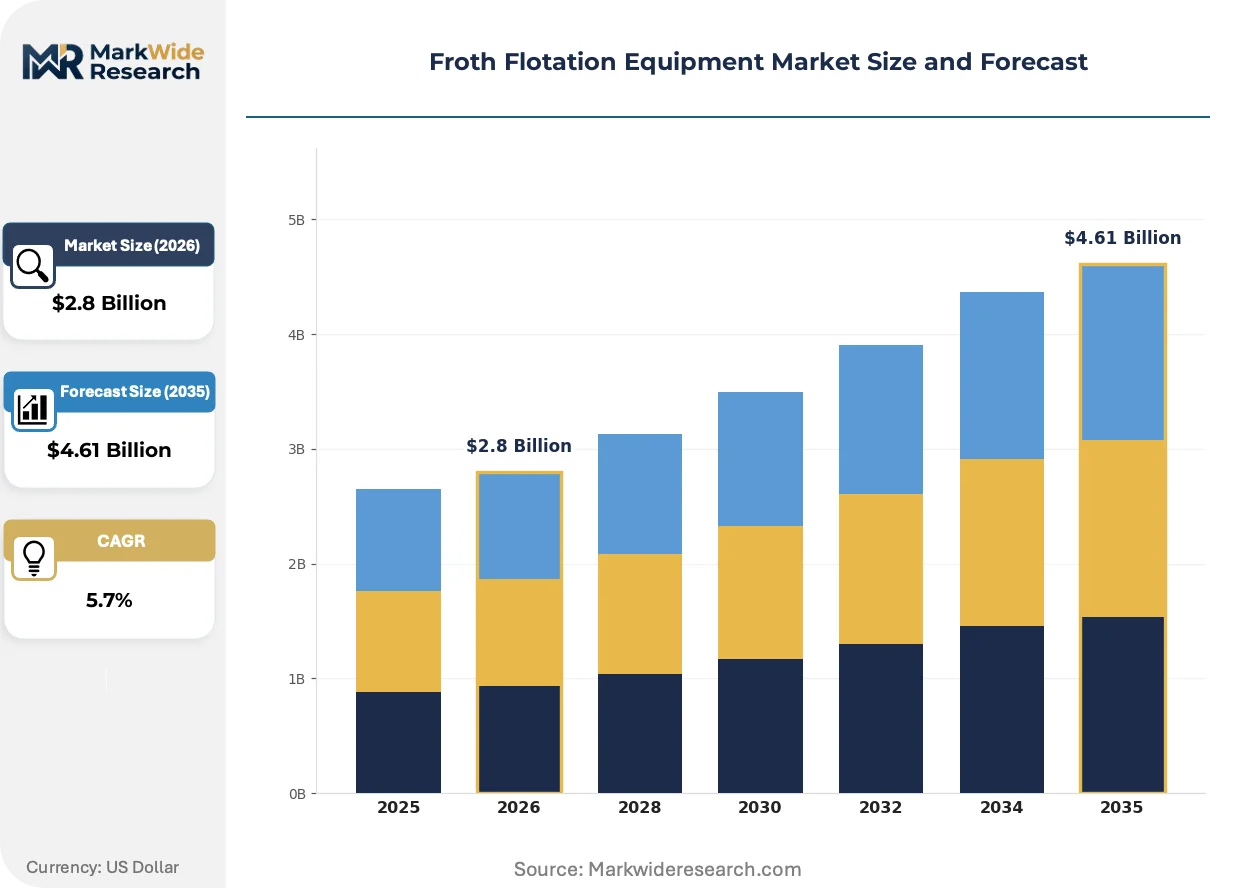
Market Dynamics
Declining head grades across Chilean and Australian copper deposits are forcing concentrator operators to deploy higher-capacity flotation cells with advanced froth control systems to maintain metal recovery economics.
Growth Catalysts
- Chile's SMA tailings enforcement:Stringent environmental compliance deadlines are compelling processors to retrofit legacy circuits with closed-loop water recovery systems, creating replacement demand for modern flotation infrastructure.
- Lithium spodumene expansion:Battery-material developers in China's Jiangxi province are commissioning fine-grind flotation trains to extract lithium from hard-rock deposits previously considered subeconomic.
- Hybrid cell technology:Combined mechanical-column flotation circuits are capturing market traction among molybdenum producers seeking simultaneous rougher-scavenger efficiency without secondary classification.
Market Restraints
- Steel and alloy input volatility:Flotation cell fabrication depends on specialized stainless grades and high-chrome white iron for impellers, exposing manufacturers to commodity price swings that compress project margins.
- Specialized engineering talent scarcity:The shallow pool of metallurgists capable of optimizing complex polymetallic flotation circuits constrains deployment velocity for greenfield concentrators.
- Thickener and filtration bottlenecks:Water recovery infrastructure upstream of tailings storage often lacks capacity to match expanded flotation throughput, limiting circuit utilization rates.
Strategic Opportunities
- Indonesian nickel laterite processing:Emerging hydrometallurgical flowsheets incorporating flotation preconcentration present equipment vendors with entry points into the expanding battery supply chain.
- EU Critical Raw Materials Act:Domestic rare earth and lithium extraction mandates across Finland and Portugal are accelerating permitting for concentrator projects requiring column flotation systems.
- Digital twin integration:Real-time froth imaging and machine learning-based reagent optimization are converging with traditional mechanical cells to enable autonomous circuit control.
Industry Challenges
- Commissioning timeline compression:EPC contractors face penalties for delayed concentrator handover, forcing equipment suppliers to accelerate factory acceptance testing and site installation sequences.
- Legacy DCS integration complexity:Modern flotation cells with variable-speed drives and advanced instrumentation must interface with aging distributed control systems prevalent in African and Central Asian gold circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Froth Flotation Equipment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Flotation, Column Flotation, Agitation Flotation, Flotation Cells Technology: Batch Flotation, Continuous Flotation, Hybrid Flotation, Ultra-Fine Flotation End User: Mining, Chemical Processing, Wastewater Treatment, Recycling Application: Mineral Processing, Water Treatment, Paper Industry, Oil Recovery |
| Companies Covered | Metso Outotec, FLSmidth, Eriez Flotation, Yantai Jingpeng Mining Technology, JXSC Mine Machinery, Sandvik, Shandong Xinhai Mining Technology & Equipment, Tenova, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Froth Flotation Equipment Market Emerging Trajectories
Electrochemical flotation monitoring and coarse particle recovery systems are restructuring how concentrators balance capital intensity against metal recovery targets.
Jameson cell technology is displacing conventional mechanical flotation in coal and base metal cleaning duties where rapid kinetics and small footprint reduce civil works costs. Australian coal washeries have adopted these high-intensity systems for ultrafine fraction recovery. The shift is compressing demand for large-volume tank cells in applications where retention time requirements have shortened.
EPA effluent limitation guidelines for mineral processing are mandating zero liquid discharge validation before permit issuance for new concentrators in the United States. Operators must demonstrate closed-loop water balances with third-party verification of tailings containment integrity. Copper-molybdenum projects in Arizona and New Mexico are redesigning flotation circuits to incorporate integrated thickener underflow recirculation.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts across African gold circuits. Junior miners are procuring spare parts through independent distributors and engaging regional mechanical contractors for cell refurbishment rather than returning equipment to original manufacturers. This pattern is most pronounced in Ghana and Burkina Faso, where logistics costs and currency volatility make bundled service premiums unsustainable.
Froth Flotation Equipment Market Segmentation
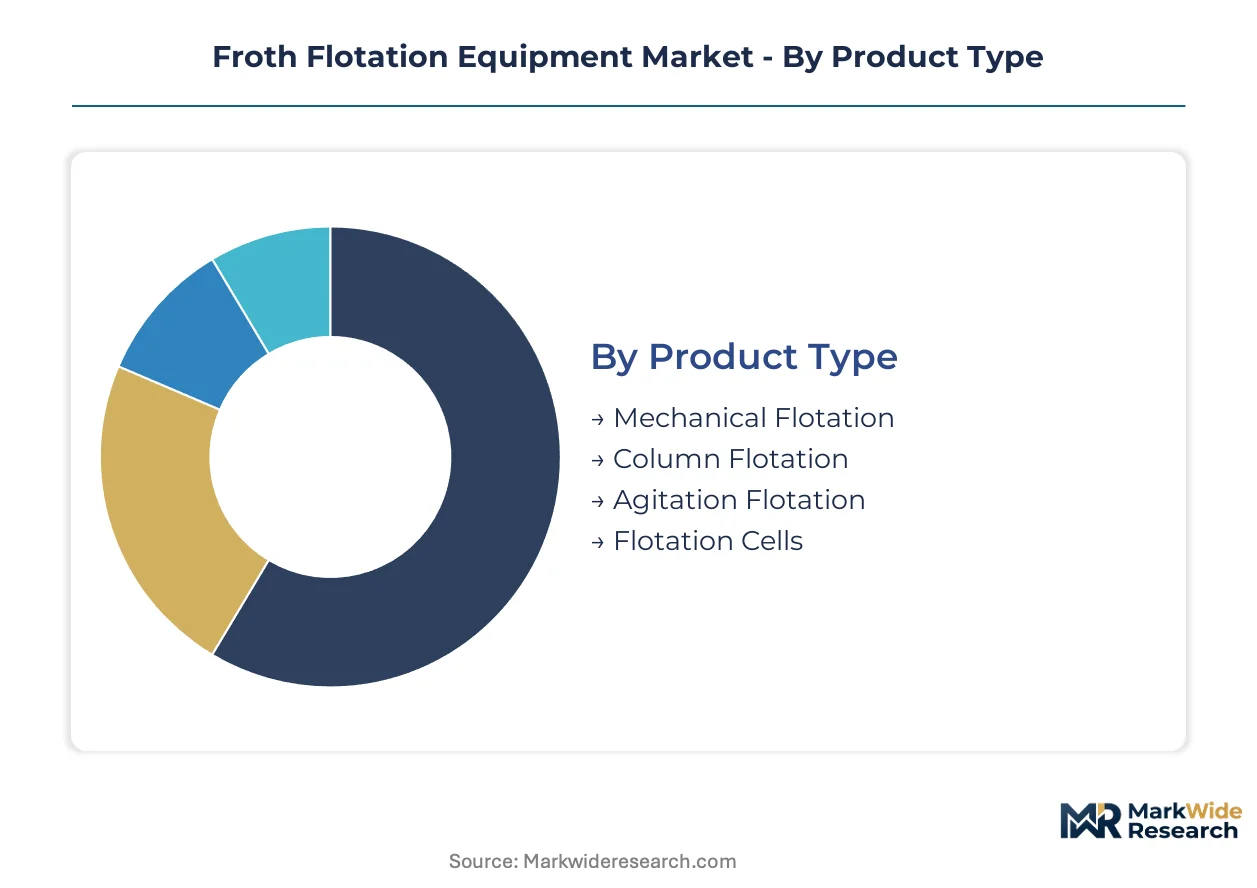
Equipment segmentation in froth flotation reflects divergent regulatory compliance burdens across jurisdictions. Chile's SMA tailings enforcement and China's MEE discharge limits create distinct procurement patterns that reshape category prioritization.
Product Type:
EPA effluent guidelines and Chilean water recovery mandates differentiate equipment selection by closed-loop capability and containment integrity.
- Mechanical Flotation:Impeller-driven cells with variable-speed drives and advanced froth control systems dominate sulfide concentrator installations. Chilean copper operators in the Atacama Desert deploy these for high-throughput rougher-scavenger duty where water recirculation compliance is mandatory.
- Column Flotation:Tall vessels with wash-water circuits and air sparging systems enable finer bubble size distribution for molybdenum cleaning stages. China's Jiangxi province lithium developers commission column systems for spodumene fine-grind circuits that meet MEE effluent concentration limits.
- Agitation Flotation:High-shear mixing vessels suit coarse particle conditioning in African gold circuits.
- Flotation Cells:Standardized tank designs serve retrofit projects in Australian base-metal concentrators.
Mechanical flotation handles the majority of throughput; column flotation is gaining share fastest on water recovery compliance.
Technology:
Capital intensity and metallurgical recovery targets stratify technology adoption across battery-material and base-metal flowsheets.
- Batch Flotation:Laboratory-scale and pilot-plant systems enable metallurgical testwork for greenfield concentrator design. Australian feasibility studies for rare earth projects in Western Australia rely on batch protocols to validate reagent schemes before continuous circuit commitment.
- Continuous Flotation:Steady-state operation with real-time froth imaging supports autonomous control in large-scale copper-molybdenum operations. Arizona concentrators integrate continuous trains with thickener underflow recirculation to satisfy EPA zero liquid discharge validation.
- Hybrid Flotation:Combined mechanical-column circuits eliminate secondary classification stages for lithium processors.
- Ultra-Fine Flotation:Specialized cells target sub-10-micron recovery in refractory gold circuits.
Continuous technology commands the installed base; hybrid configurations are climbing the fastest on lithium project commissioning.
End User:
Ore grade decline and tailings liability exposure concentrate procurement decisions in extractive sectors with highest water stress.
- Mining:Copper, lithium, and rare earth concentrators drive equipment replacement cycles as declining head grades force capacity expansion. Chilean operators retrofit legacy circuits with closed-loop systems ahead of SMA enforcement deadlines.
- Chemical Processing:Specialty mineral separation for industrial feedstocks employs smaller-scale flotation trains with reagent containment protocols.
- Wastewater Treatment:Municipal and industrial effluent facilities adopt dissolved air flotation for solids removal.
- Recycling:Battery black mass and e-waste processors pilot selective flotation for metal recovery.
Mining end users absorb the dominant equipment volume; recycling applications are expanding most quickly on circular economy policy.
Application:
Process water scarcity and discharge liability differentiate application priorities across arid and temperate jurisdictions.
- Mineral Processing:Base and battery metal concentrators constitute the core demand pool with stringent tailings management requirements. Inner Mongolia rare earth projects integrate flotation with thickener returns to comply with regional water use quotas.
- Water Treatment:Industrial effluent polishing and produced water cleanup employ compact flotation skids for oil and solids separation.
- Paper Industry:De-inking circuits recover fiber from post-consumer waste streams.
- Oil Recovery:Produced water treatment and bitumen extraction utilize induced gas flotation systems.
Mineral processing anchors equipment deployment; water treatment applications are gaining share fastest on tightening discharge standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrators in Chile, lithium developers in China, and gold operators across West Africa concentrate equipment procurement decisions in jurisdictions facing acute water stress and escalating tailings liability.
Chile
Atacama Desert copper operators deploy high-capacity mechanical flotation cells with closed-loop water recovery to maintain throughput against declining ore grades. SMA environmental enforcement deadlines are compelling processors to retrofit legacy circuits ahead of permit renewals. Antofagasta and Calama industrial clusters anchor concentrator expansion as state-owned Codelco accelerates mine life extension projects.
China
Jiangxi province lithium spodumene developers commission fine-grind flotation trains to extract battery-grade material from previously subeconomic hard-rock deposits. MEE discharge limits for mineral processing effluent are accelerating domestic procurement of closed-loop plants with integrated thickener returns. Inner Mongolia rare earth concentrators in Baotou and Bayan Obo are expanding flotation circuit capacity under state-backed critical mineral mandates.
Australia
Western Australian rare earth feasibility studies rely on batch flotation protocols to validate reagent schemes before continuous circuit commitment. EPA tailings standards are forcing operators to demonstrate water recovery rates and reagent containment before permit renewal. Kalgoorlie and Mount Isa base-metal clusters are retrofitting mechanical cells with advanced froth control systems to handle lower head grades.
United States
Arizona and New Mexico copper-molybdenum projects are redesigning flotation circuits to incorporate integrated thickener underflow recirculation for zero liquid discharge validation. EPA effluent limitation guidelines mandate third-party verification of tailings containment integrity before new concentrator permits. Phoenix and Tucson industrial corridors are seeing renewed investment in mechanical cell capacity as dormant projects advance toward construction.
Indonesia
Sulawesi and Halmahera nickel laterite processors are piloting hydrometallurgical flowsheets incorporating flotation preconcentration for battery supply chain entry. The country's mineral processing regulations are tightening discharge standards for new concentrator investments. Morowali Industrial Park is emerging as a cluster where Chinese-backed operators are testing hybrid flotation configurations for laterite upgrade circuits.
Froth Flotation Equipment Market Vendor Landscape
Player mix skews toward integrated technology conglomerates with metallurgical process portfolios and specialized fabricators serving regional mining corridors. Market structure concentrates around Nordic and North American engineering groups with installed base advantages in copper and gold circuits, alongside Chinese equipment builders capturing domestic lithium and rare earth projects. Strategic archetypes divide between full-flowsheet integrators, aftermarket service specialists, and column flotation technology boutiques. Dominant competitive moves include technology licensing partnerships for hybrid cell configurations and geographic expansion through regional fabrication joint ventures.
Within the integrated technology tier, Metso Outotec and FLSmidth occupy positions exemplifying contrasting service models—one anchored in premium mechanical cell contracts across established copper belts, the other sustained by dense aftermarket networks in African gold circuits. Eriez Flotation represents the specialization archetype, with its positioning in column flotation systems for coarse particle and fine cleaning duties. Among China-based fabricators, Yantai Jingpeng Mining Technology and Shandong Xinhai Mining Technology & Equipment exemplify domestic champions capturing state-backed rare earth and lithium concentrator investments. JXSC Mine Machinery anchors the mid-market fabrication segment serving junior miners across Southeast Asian and African jurisdictions.
| Leading Market Players |
|---|
| Metso Outotec |
| FLSmidth |
| Eriez Flotation |
| Yantai Jingpeng Mining Technology |
| JXSC Mine Machinery |
| Sandvik |
| Shandong Xinhai Mining Technology & Equipment |
| Tenova |
| GEA Group |
| Others |
Supply Flow & Price Mechanics
High-volume mechanical cell fabrication in Nordic and Chinese manufacturing clusters generates scale economies that compress unit costs for standard tank designs while elevating price floors for specialized column flotation systems with integrated wash-water circuits. Chilean copper operators and Chinese lithium developers face divergent procurement economics as water recovery compliance mandates reshape total cost of ownership calculations across arid and temperate jurisdictions.
Pricing Analysis
Cost-plus contracts with stainless steel indexation dominate large-scale concentrator procurement, protecting fabricators against nickel and chrome price volatility while exposing buyers to raw material passthrough. Price differentiation rests on impeller alloy grade and froth control automation tier, with premium variable-speed drive configurations commanding substantial premiums over fixed-speed alternatives. Cost compression in standard mechanical cells is intensifying because Chinese fabricators are scaling domestic capacity for state-backed rare earth projects. Junior miners across West Africa exhibit the highest price sensitivity, prioritizing refurbished legacy equipment over newbuild installations.
Supply Chain Analysis
Strategic stockpiling of high-chrome white iron and specialized stainless grades characterizes procurement behavior among Nordic and North American OEMs, contrasting with just-in-time inventory practices at Chinese fabricators serving domestic lithium concentrators. Manufacturing capacity concentrates in Finland, China, and Australia, with component sourcing drawing from South African ferrochrome suppliers and German automation vendors. Single-source vulnerability in specialized impeller castings represents the dominant structural risk. Distribution runs through EPC contractors and regional aftermarket service networks rather than direct OEM sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid flotation technology and digital twin integration are disrupting established competitive positions, creating urgency for incumbents to consolidate control over critical metallurgical intellectual property before autonomous circuit control becomes table stakes.
For Market Incumbents: Secure exclusive licensing arrangements for hybrid mechanical-column configurations to block emerging entrants from replicating combined rougher-scavenger efficiency without secondary classification. Anchor aftermarket service contracts through predictive maintenance platforms that lock in recurring revenue against independent distributor encroachment in African gold circuits. For New Entrants and Emerging Players: Differentiate on coarse particle recovery specialization for molybdenum and coal cleaning applications where Jameson cell displacement creates white-space opportunity. Target Indonesian nickel laterite preconcentration circuits as the most penetrable geography, leveraging hydrometallurgical flowsheet partnerships with Chinese-backed operators in Morowali Industrial Park as the primary go-to-market angle. For Investors and Strategic Acquirers: Column flotation technology boutiques with proprietary air sparging intellectual property represent the most attractive acquisition target archetype given their scarcity value in fine cleaning and water recovery compliance applications. Long-term viability hinges on exposure to battery-material processing rather than cyclical base-metal concentrator replacement. Watch EPA zero liquid discharge enforcement intensity as the signal indicating accelerated replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Hybrid cell configurations enable Nordic OEMs to capture lithium spodumene contracts without greenfield R&D investment. |
| Regional Fabrication Joint Venture | Local assembly in Chile and Indonesia reduces logistics exposure to Atacama Desert and Sulawesi infrastructure constraints. |
| Digital Twin Integration | Real-time froth imaging platforms differentiate service offerings for Arizona copper-molybdenum autonomous circuit deployments. |
| Aftermarket Service Unbundling Response | Predictive maintenance subscriptions counter independent distributor fragmentation in Ghanaian and Burkinabe gold circuits. |
| Closed-Loop Water Recovery Retrofit | Integrated thickener return systems position vendors ahead of Chile SMA and China MEE enforcement deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from concentrator plant managers, metallurgical engineering directors, EPC procurement leads, and aftermarket service heads, then refined through secondary validation against SEC filings from listed mining technology vendors, Chile SMA environmental enforcement records, China MEE discharge compliance databases, and Australian EPA tailings permit documentation. Bottom-up equipment shipment tallies by concentrator project were triangulated against top-down mineral processing capital expenditure estimates across copper, lithium, and rare earth extraction sectors.
Variance decomposition across mechanical, column, and hybrid technology categories, segmented by ore type, process water scarcity tier, and regulatory compliance burden, structured the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles and greenfield concentrator commissioning schedules. Modeled inputs incorporated ore grade decline trajectories in Chilean copper deposits and battery-material demand elasticity for lithium spodumene flotation capacity.
The analysis sits within stated boundaries; outcomes outside sustained battery-material demand growth or accelerated tailings regulation enforcement would require recalibration. Forecasts reflect assumptions regarding water recovery technology adoption rates and metallurgical engineering labor availability. Revision becomes warranted when Chinese state-backed rare earth project subsidies or EPA effluent guideline stringency cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Pipe Wipers Market