
 Lifting Machinery Market | 2026-2036
Lifting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Lifting Machinery Market Analytics
Aftermarket service revenue is fragmenting across original equipment manufacturers and independent service networks. Konecranes sustains premium positioning through captive spare parts distribution and remote diagnostics infrastructure. Liebherr Group anchors its European installed base with regional refurbishment hubs and technician certification programs.
Lifting machinery encompasses mobile and fixed equipment engineered to raise, lower, or horizontally transport loads exceeding one metric ton, with hydraulic systems operating at pressures up to 350 bar and electric hoists typically rated for duty cycles defined by FEM 9.511 classifications. The technology dimension shows electric and hybrid configurations gaining share as battery energy density improves and site emissions rules tighten. In end-user terms, warehousing and construction represent the most contested segments, with telematics-enabled fleet management creating differentiation in equipment utilization contracts.
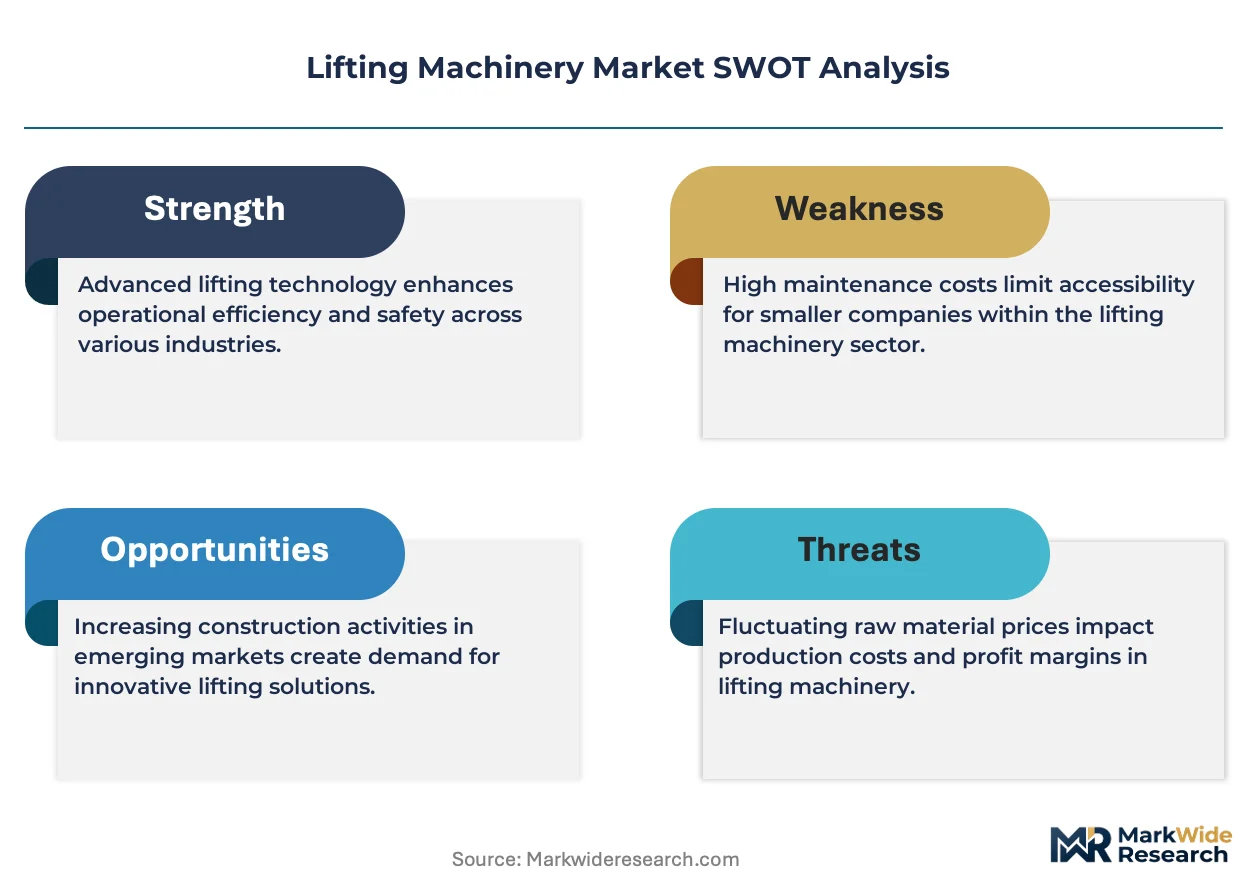
OSHA, the EU Machinery Directive, and ISO 4301-1 collectively govern design safety, inspection intervals, and operator certification requirements across major markets. Compliance with these frameworks determines market access and shapes replacement cycles for aging installed bases. Stakeholders must weigh electrification capital requirements against emerging carbon-border compliance costs in procurement planning.
Market Dynamics
Electrification of port and construction fleets is compressing replacement cycles as battery energy density improvements align with tightening site emissions rules across major industrial economies.
Growth Catalysts
- Warehouse automation surge:E-commerce fulfillment centers are procuring automated guided cranes and stacker systems to accelerate throughput velocity.
- OSHA inspection mandates:US federal requirements for documented crane inspections are accelerating replacement of pre-2010 installed bases.
- China port infrastructure buildout:Coastal terminal expansions are generating concentrated demand for ship-to-shore gantry cranes and rubber-tired gantries.
Market Restraints
- Steel price volatility:Structural steel and high-grade bearing alloys constitute 35-45% of manufacturing input costs, exposing margins to commodity swings.
- European supply concentration:Specialty hydraulic component production clusters in Germany and Italy, creating single-source vulnerability for non-integrated OEMs.
- Lead-acid battery substitution ceiling:Lithium-ion pack costs remain prohibitive for duty cycles below FEM 2m classification, slowing full electrification.
Strategic Opportunities
- Southeast Asian manufacturing zones:Vietnam and Indonesia industrial parks lack mature lifting equipment service networks, opening captive aftermarket entry.
- EU Green Deal machinery retrofit incentives:Member-state subsidy programs for diesel-to-electric crane conversions create financed upgrade pathways.
- Telematics-platform convergence:Integration of load-monitoring sensors with predictive maintenance software enables utilization-based contracting models.
Industry Challenges
- Certified technician scarcity:FEM 9.511 inspector qualifications require 18-month apprenticeship pipelines that lag fleet expansion rates.
- Legacy PLC integration friction:Pre-2015 control architectures lack standardized data protocols, complicating remote diagnostics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifting Machinery Market |
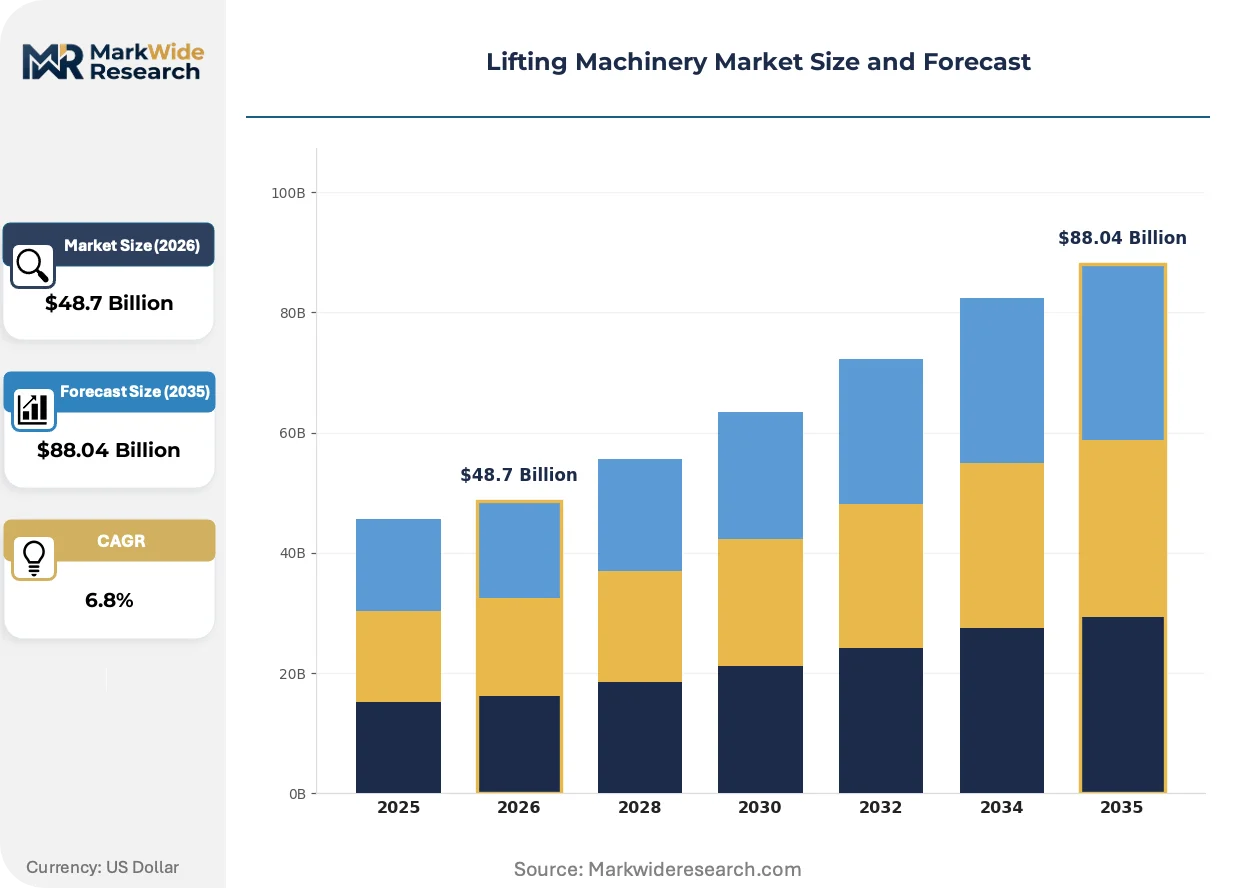
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Cranes, Electric Hoists, Forklifts, Aerial Work Platforms Technology: Telematics, Automation, Electric, Hybrid End User: Construction, Manufacturing, Transportation, Warehousing Capacity: Below 5 Tons, 5-10 Tons, 10-20 Tons, Above 20 Tons |
| Companies Covered | Konecranes, Liebherr Group, Terex Corporation, Tadano Ltd., Manitowoc, Zoomlion Heavy Industry Science & Technology Co., Ltd., Cargotec Corporation, Komatsu Ltd., Columbus McKinnon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifting Machinery Market Evolving Landscape
Digitalization of fleet management and powertrain electrification are converging to redefine equipment lifecycle economics and competitive differentiation across end-use verticals.
Mobile harbor cranes are hybridizing diesel-electric architectures with battery-buffered peak shaving. Port operators in Rotterdam and Singapore are piloting configurations that cut idle fuel consumption by enabling shore-power connection during vessel loading. The technology is hybridizing capital deployment models by allowing terminal operators to defer full grid infrastructure investment while meeting EU port emissions targets.
The EU Machinery Directive 2006/42/EC amendment process is tightening safety integrity level requirements for autonomous lifting systems. OEM engineering departments are reallocating R&D resources to functional safety certification ahead of anticipated 2027 enforcement. Construction sites in Germany and France are most affected, with contractors demanding pre-certified subsystems to compress commissioning timelines.
Equipment-as-a-service contracting is displacing traditional capital purchase in warehousing. Third-party logistics providers in the US and Netherlands are unbundling maintenance and telematics from hardware acquisition, transferring residual value risk to OEM balance sheets. This restructuring concentrates buyer power among multi-site fleet operators capable of standardized performance metrics.
Lifting Machinery Market Segmentation
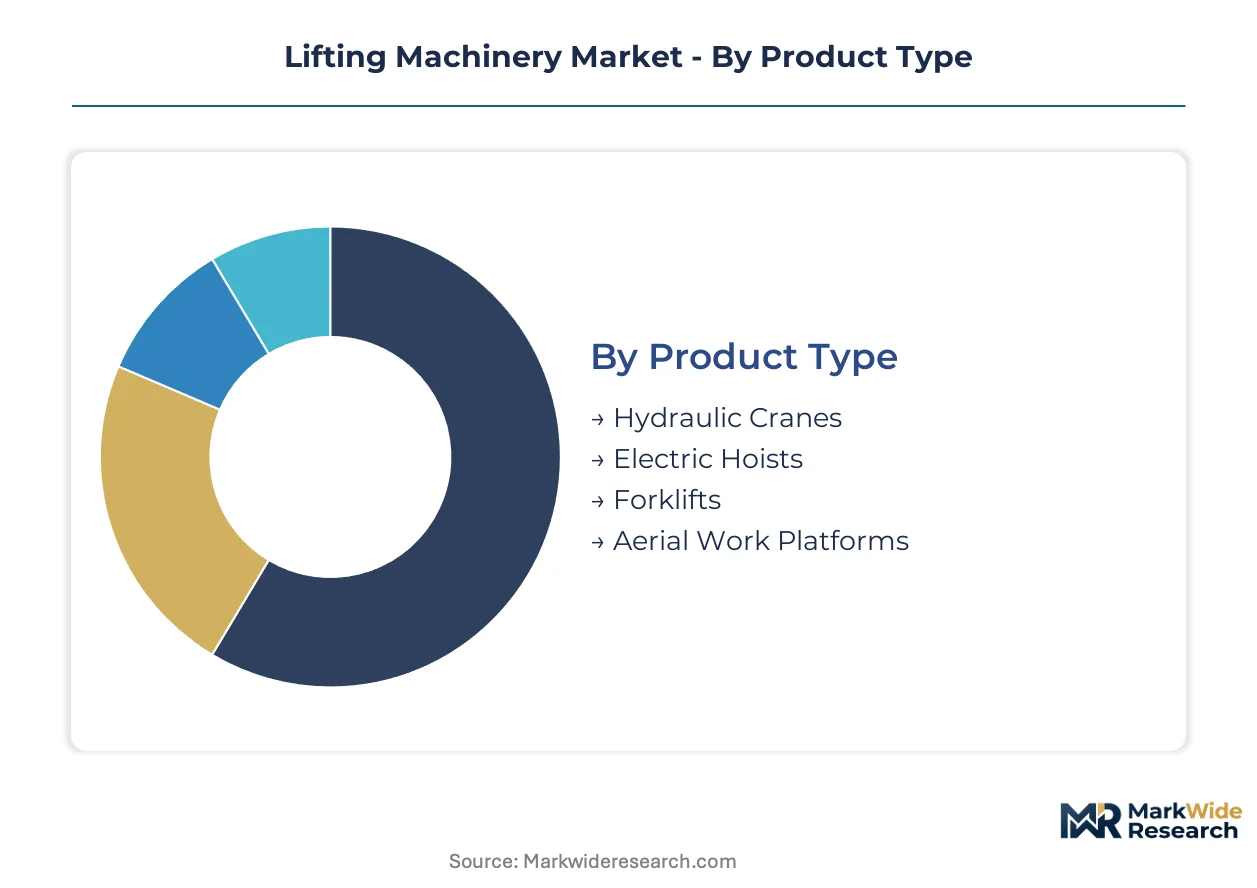
Equipment lifecycle economics vary dramatically across lifting machinery categories, with some segments turning over every 5-7 years while others operate for 15-20 years. Understanding these replacement rhythms shapes procurement strategy and aftermarket revenue timing for suppliers.
Product Type:
Hydraulic cranes and electric hoists turn over fastest due to intensive duty cycles, while aerial work platforms and forklifts exhibit longer replacement intervals tied to safety inspection mandates.
- Hydraulic Cranes:These systems operate at pressures up to 350 bar with telescoping booms rated for continuous FEM 9.511 duty classifications. Port terminals in Rotterdam and Singapore are accelerating replacement of pre-2010 fleets to meet EU port emissions targets and OSHA inspection mandates.
- Electric Hoists:Compact units with chain or wire rope configurations dominate indoor manufacturing environments. German automotive assembly plants and Chinese electronics factories are standardizing on FEM 9.511-certified units to reduce maintenance downtime.
- Forklifts:Counterbalance and reach truck configurations serve warehousing and logistics operations with battery-electric variants displacing internal combustion in indoor applications.
- Aerial Work Platforms:Scissor lifts and boom lifts provide vertical access for maintenance and construction with hybrid-electric models gaining traction in European urban job sites.
Forklifts anchor the volume base while electric hoists gain share at the steepest rate.
Technology:
Cost tiers separate mature mechanical systems from digitally enabled and electrified alternatives, with premium pricing concentrated in integrated automation and telematics packages.
- Telematics:Load-monitoring sensors and GPS tracking enable predictive maintenance and utilization-based contracting. Third-party logistics providers in the Netherlands and US are demanding OEM-integrated platforms to optimize multi-site fleet deployment.
- Automation:Automated guided cranes and robotic stacker systems eliminate operator variability in high-throughput environments. E-commerce fulfillment centers in Germany and Japan are procuring these systems to accelerate order processing velocity.
- Electric:Battery-powered configurations with lithium-ion packs are displacing diesel in indoor and urban applications where emissions rules are tightening fastest.
- Hybrid:Diesel-electric architectures with battery buffering cut idle fuel consumption and enable shore-power connection in port applications.
Electric technology anchors the volume base while automation expands most quickly.
End User:
Application intensity drives margin differentiation, with construction and warehousing exhibiting the most contested procurement dynamics and transportation offering longer contract horizons.
- Construction:Mobile cranes and aerial platforms face seasonal utilization patterns and site-specific safety requirements. German and French contractors are demanding pre-certified subsystems under tightening EU Machinery Directive amendments to compress commissioning timelines.
- Warehousing:Automated stacker cranes and reach trucks operate in climate-controlled environments with 24/7 duty cycles. US and Dutch third-party logistics providers are shifting to equipment-as-a-service contracts that transfer residual value risk to OEMs.
- Manufacturing:Overhead cranes and jib systems integrate with production lines requiring precise load positioning and minimal downtime.
- Transportation:Ship-to-shore gantry cranes and rubber-tired gantries serve port terminals with 20-30 year asset lifecycles and intensive maintenance requirements.
Construction anchors the volume base while warehousing climbs the fastest.
Capacity:
Customer type stratification separates commodity procurement below 5 tons from engineered solutions above 20 tons, with mid-range categories capturing the broadest cross-industry demand.
- Below 5 Tons:Light-duty electric hoists and compact forklifts serve small-scale manufacturing and retail distribution with standardized specifications and price-sensitive procurement.
- 5-10 Tons:Mid-range overhead cranes and counterbalance forklifts dominate general manufacturing and warehousing applications across Southeast Asian industrial parks.
- 10-20 Tons:Heavy-duty mobile cranes and port equipment require custom configuration and certified operator training with longer sales cycles and higher aftermarket attachment.
- Above 20 Tons:Specialized ship-to-shore gantries and crawler cranes serve infrastructure and maritime terminals with project-based procurement and captive service contracts.
5-10 ton capacity anchors the volume base while above 20 ton systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asian manufacturing zones exhibit acute price sensitivity for standardized electric hoists, while port operators in Rotterdam and Singapore absorb premium pricing for emissions-compliant gantry systems with minimal elasticity.
United States
Warehouse automation in e-commerce fulfillment centers drives electric hoist and automated stacker procurement. OSHA crane inspection mandates accelerate replacement of pre-2010 installed bases in construction and port applications. The Gulf Coast petrochemical corridor concentrates demand for heavy-lift mobile cranes serving offshore platform maintenance.
China
Coastal terminal expansions generate concentrated demand for ship-to-shore gantry cranes and rubber-tired gantries. The country's dual carbon goals tighten emissions standards for port equipment, favoring electrified configurations. Yangtze River Delta manufacturing clusters standardize on FEM 9.511-certified overhead cranes to reduce automotive assembly downtime.
Germany
Automotive assembly plants and precision manufacturing facilities anchor demand for high-duty-cycle electric hoists. EU Machinery Directive amendments tighten safety integrity requirements for autonomous lifting systems ahead of 2027 enforcement. Baden-Württemberg engineering clusters pilot telematics-integrated fleet management for multi-site manufacturing operations.
Vietnam
Industrial park buildouts in Bac Ninh and Hai Phong lack mature lifting equipment service networks, opening captive aftermarket entry. The country's national industrial safety framework adopts ISO 4301-1 inspection intervals for imported equipment. Northern manufacturing zones concentrate demand for 5-10 ton capacity overhead cranes serving electronics contract assembly.
Netherlands
Third-party logistics providers shift to equipment-as-a-service contracts that transfer residual value risk to OEMs. EU Green Deal machinery retrofit incentives create financed pathways for diesel-to-electric crane conversions. Rotterdam port terminals pilot hybrid diesel-electric mobile harbor cranes with shore-power connection capability.
Lifting Machinery Market Competitive Landscape
Vertically integrated heavy machinery conglomerates and specialized crane engineering houses split the market between scale-driven port equipment and precision manufacturing solutions. European and East Asian players anchor the premium tier through captive spare parts distribution and remote diagnostics infrastructure. Three archetypes dominate: full-line port equipment suppliers, electric hoist specialists, and mobile crane fabricators. Competitive intensity centers on M&A consolidation of regional service networks and strategic partnerships for battery-electric powertrain development.
Within the premium-tier port equipment segment, Konecranes and Liebherr Group occupy positions defined by aftermarket service density and refurbishment hub networks. Zoomlion Heavy Industry Science & Technology Co., Ltd. exemplifies the scale-driven archetype among Chinese heavy machinery conglomerates. These three companies represent divergent geographic anchors—Finnish-German engineering heritage versus Chinese manufacturing scale—while converging on telematics-enabled fleet management as a competitive differentiator.
| Leading Market Players |
|---|
| Konecranes |
| Liebherr Group |
| Terex Corporation |
| Tadano Ltd. |
| Manitowoc |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Cargotec Corporation |
| Komatsu Ltd. |
| Columbus McKinnon Corporation |
| Others |
Value Network & Pricing Analysis
The Ruhr Valley engineering cluster in Germany anchors specialty hydraulic component production, with its capacity utilization directly transmitting to pricing power for integrated OEMs serving port and heavy-lift segments. Buyers in Southeast Asian manufacturing zones face cost-plus exposure when sourcing from this concentrated base, while European operators absorb premiums through captive aftermarket contracts.
Pricing Analysis
Aftermarket service revenue, encompassing spare parts distribution and remote diagnostics subscriptions, drives lifetime value capture across equipment categories. Three-tier pricing structure across premium, standard, and economy levels separates FEM 9.511-certified systems with telematics integration from basic mechanical configurations. Cost compression in the mid-range tier is intensifying because independent service networks are undercutting OEM maintenance contracts. Warehouse operators in the Netherlands exhibit the highest price sensitivity, while Rotterdam port terminals absorb premium pricing for emissions-compliant gantry systems with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on high-grade bearing alloys and precision hydraulic valves limit technology flows from Germany and Italy to non-integrated assemblers in China and Southeast Asia. Manufacturing draws from specialty steel mills in the Ruhr Valley, precision component shops in northern Italy, and battery pack assembly in South Korea. Single-source vulnerability concentrates in German hydraulic pump production. Distribution runs through OEM-direct channels for port equipment and independent distributors for standardized electric hoists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as warehouse automation in e-commerce fulfillment accelerates equipment procurement velocity beyond replacement rates.
For Market Incumbents: Build captive aftermarket moats through remote diagnostics infrastructure and regional refurbishment hub density. Consolidate independent service networks in Vietnam and Indonesia before emerging Chinese OEMs establish local presence. Defend against battery-electric powertrain specialists by securing lithium-ion supply agreements with South Korean cell producers. For New Entrants and Emerging Players: Mid-market overhead crane installations in Vietnamese industrial parks represent the most penetrable entry point, with local service networks currently underdeveloped. Target 5-10 ton capacity segments in Bac Ninh and Hai Phong where price-sensitive electronics assemblers prioritize rapid delivery over brand heritage. Enter through equipment-as-a-service contracting to transfer residual value risk and compress customer acquisition cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-enabled fleet management providers serving multi-site logistics operators. Long-term viability centers on OEMs with installed base density sufficient to support predictive maintenance platforms. Monitor lithium-ion pack cost curves as the inflection signal for full electrification penetration in duty cycles below FEM 2m classification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Hydraulics | OEMs securing German pump production reduce single-source exposure and compress lead times for port equipment. |
| Telematics Platform Integration | Load-monitoring sensor convergence with predictive software enables utilization-based contracting for Dutch logistics fleets. |
| Regional Refurbishment Hub Expansion | Vietnamese hub density captures aftermarket revenue from pre-2010 installed bases in northern manufacturing zones. |
| Battery-Electric Powertrain Partnership | Collaboration with South Korean cell producers accelerates lithium-ion adoption in FEM 2m duty classifications. |
| EU Green Deal Retrofit Financing | Member-state subsidy programs create financed upgrade pathways for diesel-to-electric crane conversions in Rotterdam terminals. |
Research Methodology
A spread of perspectives from maintenance directors at port terminals, plant engineers in automotive assembly, OEM procurement teams, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed equipment manufacturers, FEM certification registries, and EU Machinery Directive implementation reports. Bottom-up equipment shipment analysis triangulated against top-down industrial capital expenditure tracking.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation modeled by product type, technology tier, end-use vertical, capacity classification, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and penetration rate assumptions for electrified configurations. Forecast inputs incorporated battery energy density improvement curves and port emissions compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, steel commodity prices, or lithium-ion cell supply would shift the trajectory. Material shifts in EU Machinery Directive enforcement timing or OSHA inspection mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Material Handling Monorails Market