
 Drag Chain for Machine Market | 2026-2036
Drag Chain for Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Drag Chain for Machine Market Intelligence
The integration of smart sensors and predictive maintenance capabilities is reshaping the design and function of drag chain systems. These intelligent components allow for real-time monitoring of wear and operational stress, reducing unplanned downtime in industrial equipment. igus GmbH leads in this area with its smart plastics portfolio. Tsubaki Kabelschlepp leverages its extensive experience in steel chains to offer durable solutions for heavy-duty applications, while Murrplastik specializes in integrated systems for the robotics sector.
A drag chain for machines is a protective carrier guiding flexible cables and hoses connected to moving automated equipment. These systems consist of interlocking links, typically made from high-grade plastic or steel, to prevent cable entanglement and wear. Their core function is ensuring reliable power and data transmission in dynamic environments. Plastic-based chains command the market for high-speed robotics, whereas steel variants are specified for heavy-duty CNC machines and material handling systems requiring high strength.
Product specifications are governed by international and regional standards that ensure operational safety and reliability. Compliance with ISO standards for materials, the CE marking requirements in Europe for machinery safety, and OSHA guidelines in the United States for workplace environments directly impacts design and manufacturing. Ultimately, procurement decisions hinge on balancing the cost-effectiveness of standard components against the long-term operational benefits of customized, intelligent chain systems.
Market Dynamics
The market's central dynamic is the divergence between demand for cost-effective, standardized plastic chains for general automation and the pull towards specialized, intelligent systems offering predictive maintenance and higher load capacities for mission-critical industrial applications.
Growth Catalysts
- Factory Automation:Government-backed initiatives, including Germany's Industry 4.0 framework and China's advanced manufacturing goals, are accelerating investment in robotics and automated systems, directly stimulating demand for protective cable carriers.
- Material Science Advances:The development of tribologically optimized polymers and composite materials enables drag chains to operate at higher speeds and handle greater loads, expanding their use in demanding sectors like CNC machining and logistics.
- High-Speed Robotics:Proliferation of multi-axis robots in electronics assembly and automotive manufacturing requires highly flexible, durable, and lightweight drag chains to ensure reliable power and data transmission through complex movements.
Market Restraints
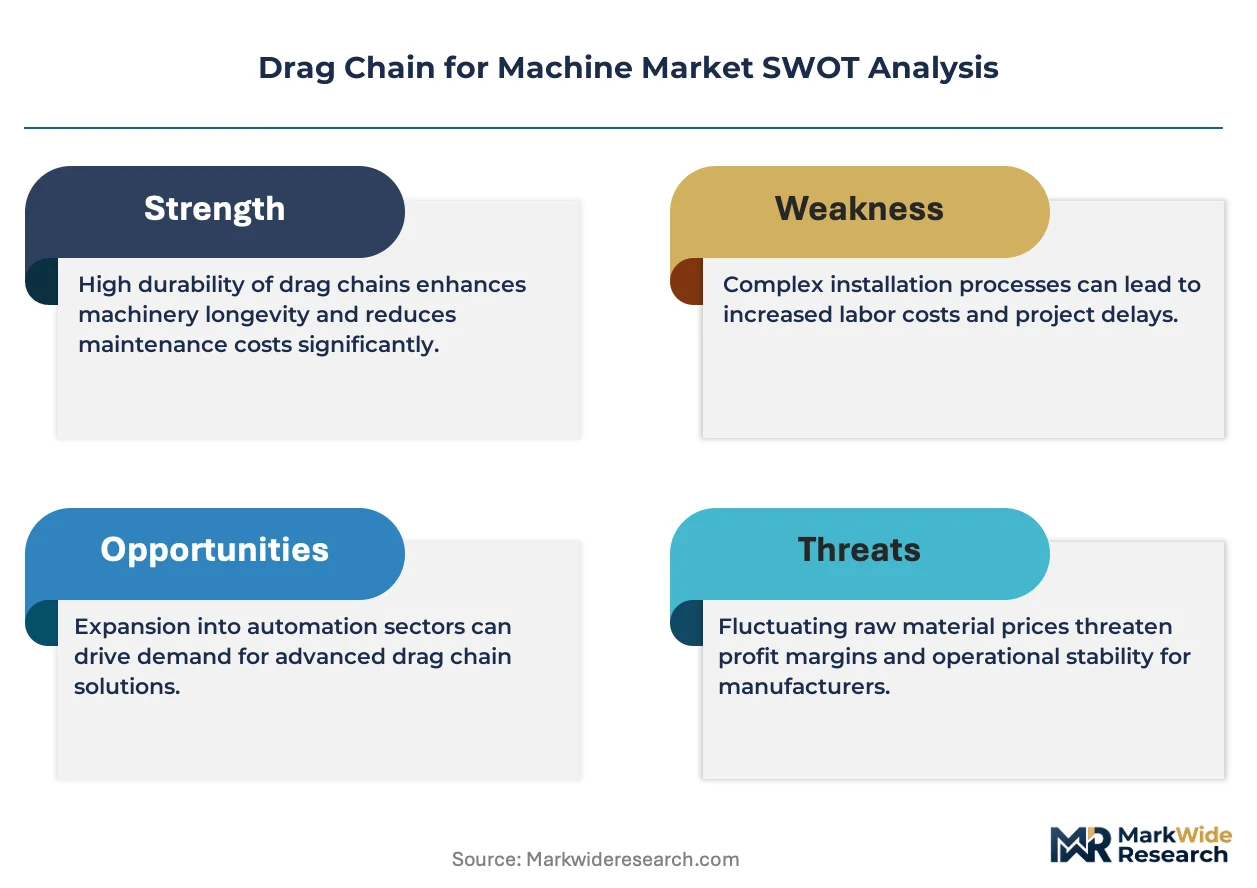
- High Initial Investment:The upfront cost of intelligent drag chains equipped with sensors and monitoring software is substantially higher than standard variants, deterring adoption among cost-sensitive end-users or for less critical applications.
- Substitution from Wireless Technology:In certain low-power or short-range applications, the emergence of reliable wireless power and data transmission technologies presents a long-term substitution threat, potentially bypassing the need for physical cable carriers.
- Integration Complexity:Integrating smart chain sensor data into disparate legacy factory control systems (SCADA, MES) can require significant custom software development and IT expertise, creating a barrier to adoption.
Strategic Opportunities
- Renewable Energy Sector:Wind turbines and solar tracking systems feature large moving components that require durable, weather-resistant cable management, creating an opportunity for specialized drag chain solutions designed for outdoor environments.
- Medical and Laboratory Automation:The growing use of automated diagnostic equipment and robotic sample handling systems provides an opening for cleanroom-certified, low-particle, and low-noise drag chains.
- Predictive Maintenance as a Service:Suppliers can transition from selling components to offering subscription-based services that leverage sensor data from smart chains to predict failures and schedule maintenance, creating recurring revenue streams.
Industry Challenges
- Navigating Global Standards:Manufacturers face complexity in designing products that comply with a patchwork of international and regional regulations, including ISO material standards, the EU's CE marking for machinery safety, and OSHA workplace rules in the US.
- System Interoperability:A lack of standardization in sensor protocols and data formats makes it difficult to ensure plug-and-play compatibility between smart drag chains and the wide variety of industrial controllers and software platforms used by customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drag Chain for Machine Market |
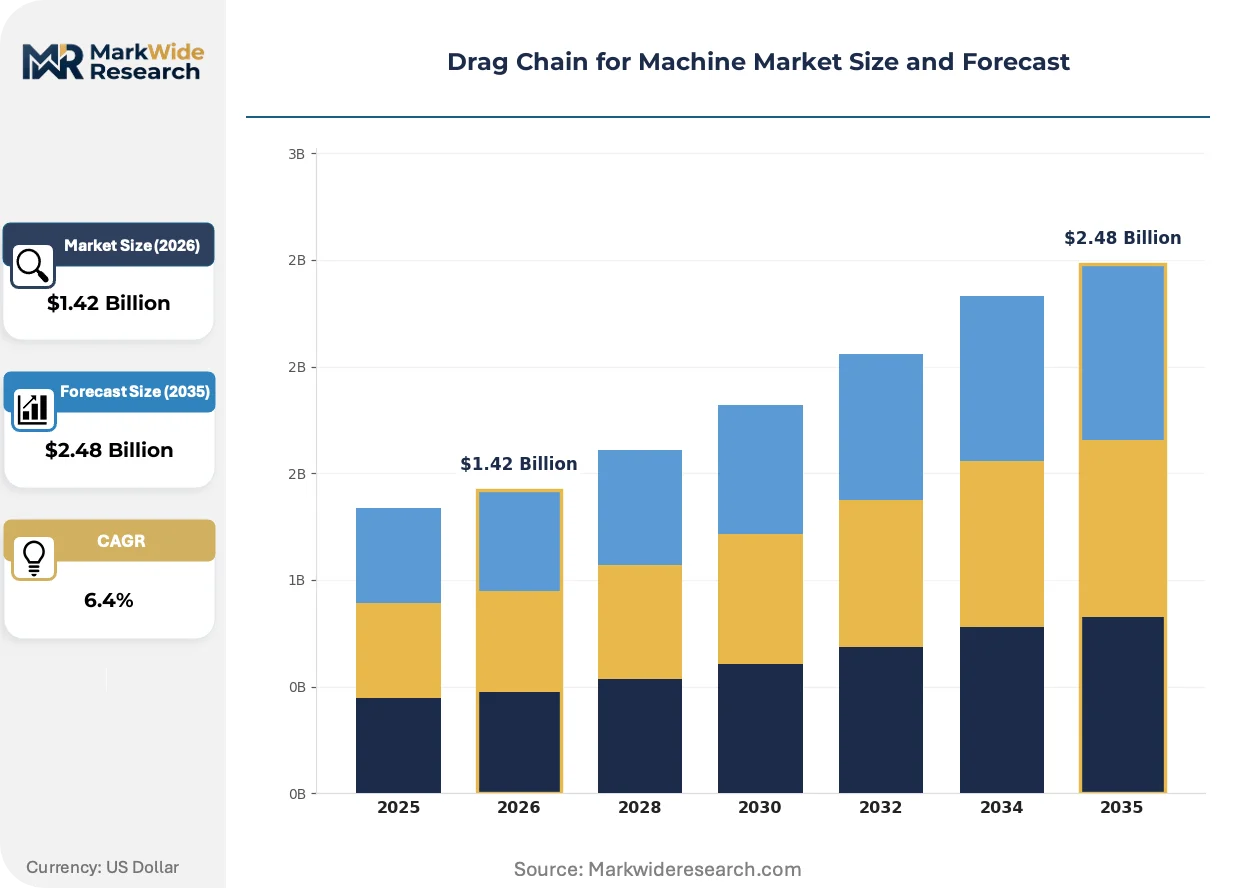
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Plastic, Aluminum, Hybrid Application: Industrial Equipment, Robotics, Material Handling, CNC Machines Size: Small, Medium, Large, Custom End User: Manufacturing, Automotive, Aerospace, Electronics |
| Companies Covered | igus GmbH, Tsubaki Kabelschlepp, Murrplastik, Hennig, Dynatect Manufacturing, Brevetti Stendalto, Lapp Group, Arno Arnold GmbH, HELUKABEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drag Chain for Machine Market Strategic Shifts & Innovations
The evolution of drag chains from passive mechanical protectors to active, data-generating components is the market's defining trend. This shift is driven by the integration of sensor technology, which transforms the chain into a critical node for monitoring equipment health and optimizing operational uptime.
Hybrid drag chains combine plastic links for flexibility with steel or aluminum components for targeted strength. Heavy-duty industries, such as port crane operations and large-format CNC machining, are the primary adopters of these composite systems. This development is hybridizing the market, creating solutions that merge the low-weight benefits of plastic with the high-strength characteristics of metal.
Europe's Machinery Directive, enforced through the mandatory CE marking, requires rigorous safety validation for components on automated equipment. This forces manufacturers to document and guarantee that cable management systems will not fail in a way that creates an industrial hazard. Consequently, demand for chains with certified materials and predictable wear characteristics is particularly strong within the EU's advanced manufacturing sector.
A focus on total cost of ownership (TCO) is altering purchasing criteria for critical industrial components. End-users are increasingly evaluating drag chains based on service life and maintenance-reducing features rather than just initial acquisition cost. This behavioral shift is most visible in high-throughput logistics and automotive production lines, where any unplanned downtime results in significant financial loss.
Drag Chain for Machine Market Segmentation
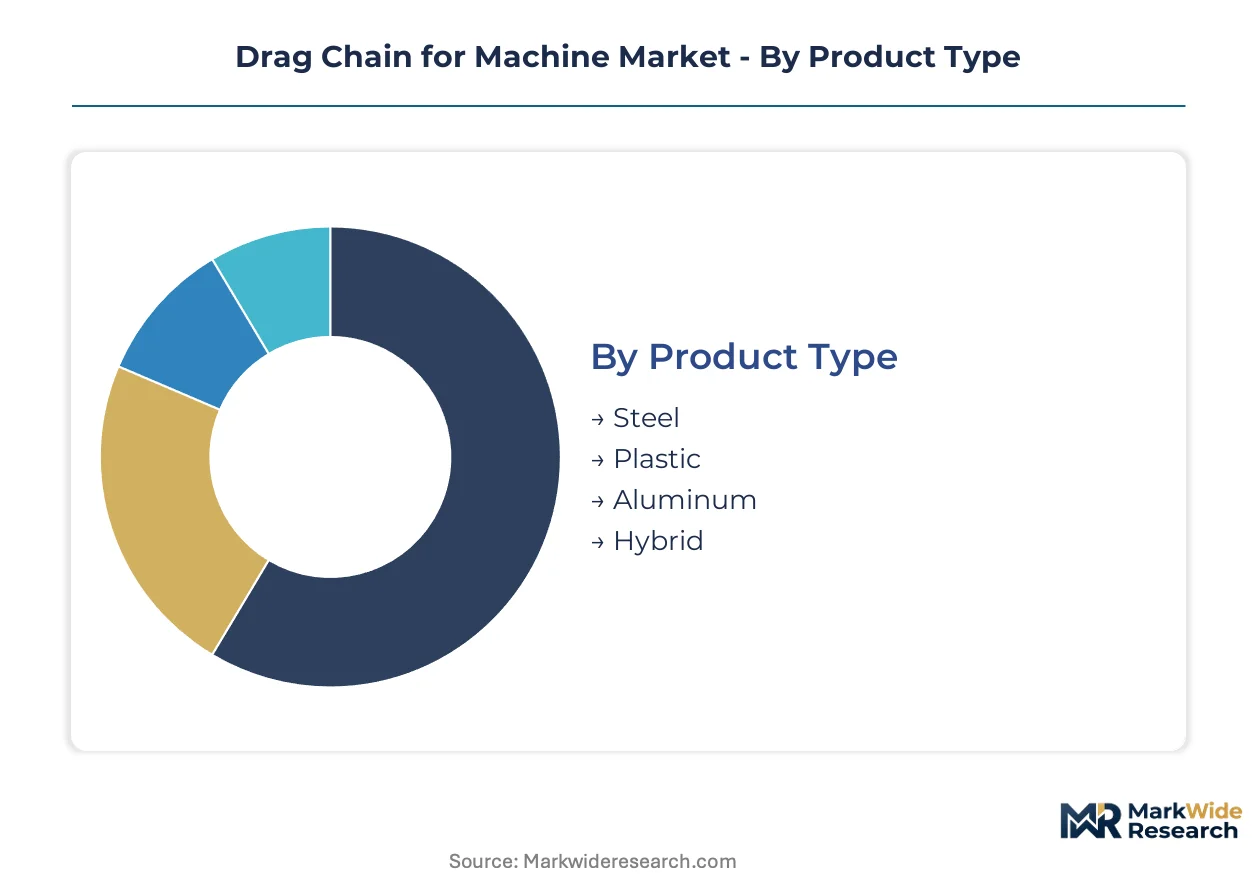
Understanding the varied requirements across industrial applications is critical for dissecting the drag chain market. Segmentation by product type, application, size, and end-user provides a granular view of demand drivers and technological preferences. This detailed analysis helps illuminate where innovation and investment are most concentrated within the industry.
Product Type:
The dimension of product composition fundamentally segments the drag chain market, defining performance characteristics and suitable operational contexts.
- Steel:These robust chains, often constructed from galvanized or stainless steel, offer superior strength and resistance to harsh environments. Demand concentrates in heavy-duty applications like large CNC machines and port crane operations, driven by requirements for high load capacity and extreme durability.
- Plastic:Lightweight and corrosion-resistant, plastic drag chains are typically made from high-performance polymers like nylon or polypropylene. Their adoption is widespread in high-speed robotics and automated assembly lines, where low mass, quiet operation, and flexibility are paramount for reliable power and data transmission.
- Aluminum:Fabricated from lightweight aluminum alloys, these chains provide a balance of strength and reduced weight compared to steel. They find use in applications where moderate loads and dynamic movements are present.
- Hybrid:Combining plastic links with metal components, hybrid chains offer targeted strength where needed while maintaining overall flexibility. Heavy-duty industries, such as large-format CNC machining, increasingly specify these composite systems.
Steel products hold substantial installed capacity. Hybrid variants are rotating up the share rankings.
Application:
Market demand is significantly shaped by the specific operational environments where drag chains are deployed, each presenting unique challenges and technical specifications.
- Robotics:Drag chains for robotics must handle complex multi-axis movements, ensuring reliable power and data transmission to robotic arms and end-effectors. This segment sees significant demand from electronics assembly and automotive manufacturing, where high flexibility and longevity are essential for continuous operation.
- CNC Machines:These applications require drag chains capable of withstanding high speeds, repetitive movements, and often heavy loads in machining environments. Demand is driven by the need for robust cable management in precision manufacturing, preventing entanglement and wear in critical operations.
- Industrial Equipment:This broad category encompasses a wide range of machinery, including packaging lines, textile machines, and printing presses. Drag chains here provide essential cable protection in general automation settings.
- Material Handling:Systems such as conveyors, automated storage and retrieval systems (AS/RS), and gantry cranes rely on drag chains for safe and organized cable guidance. These applications often require durable solutions for continuous, high-volume operations.
Robotics applications exhibit the steepest expansion trajectory. Industrial equipment maintains a foundational demand base.
Size:
The physical scale of automated machinery directly influences the required drag chain dimensions, impacting material choice and design complexity.
- Large:These robust drag chains are designed for heavy-duty applications, accommodating numerous thick cables and hoses over long travel distances. Demand is particularly strong in sectors like port operations and large-scale gantry robotics, where the physical scale of machinery necessitates substantial protective carriers.
- Small:Compact and lightweight, small drag chains are engineered for precision applications requiring minimal space and high flexibility in dynamic environments. This segment is increasingly vital for miniature robotics, intricate electronics assembly lines, and compact automated diagnostic equipment in medical labs.
- Medium:Representing a versatile category, medium-sized drag chains serve a wide array of general industrial automation tasks. They balance load capacity with flexibility for standard machine tools and packaging equipment.
- Custom:Tailored solutions are developed for unique operational requirements, often involving specialized materials or complex geometries. Custom chains address specific performance needs in highly specialized or extreme environments.
Large drag chain systems are critical for heavy industrial processes. Small-scale chains are increasingly vital for precision automation.
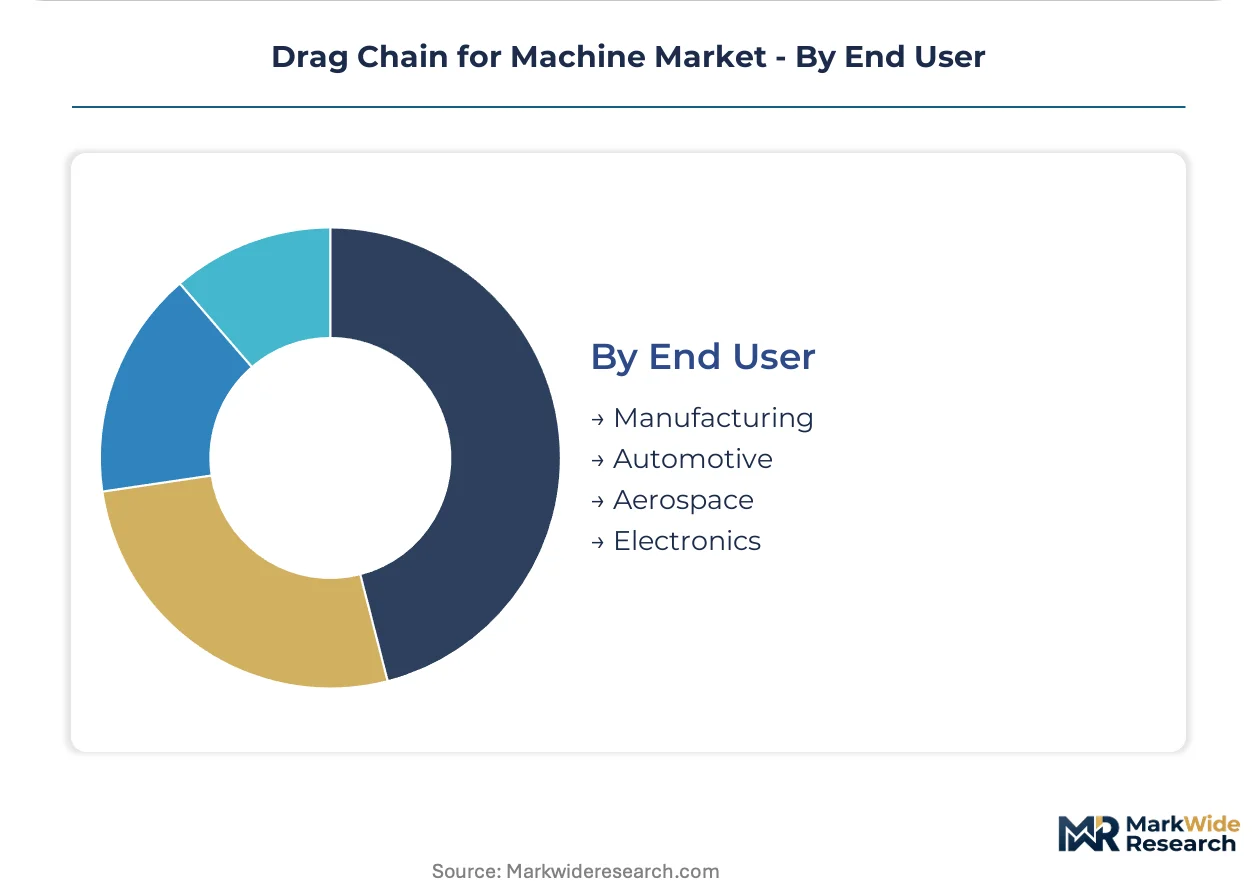
End User:
Customer industry vertical dictates the performance requirements and compliance standards for drag chain systems, influencing procurement decisions and product development.
- Manufacturing:This sector represents a primary consumer, utilizing drag chains across assembly lines, processing plants, and fabrication facilities. Demand is driven by widespread factory automation initiatives and the continuous need for operational efficiency.
- Automotive:The automotive industry heavily relies on drag chains for robotic welding, painting, and assembly operations, ensuring uninterrupted power and data flow to automated systems. Its focus on high-volume production and complex automation drives significant demand.
- Aerospace:This sector requires highly reliable, often lightweight, and cleanroom-certified drag chains for precision manufacturing and assembly of aircraft components. Stringent safety and performance standards characterize aerospace procurement.
- Electronics:Drag chains are essential in electronics manufacturing for handling delicate cables in cleanroom environments and high-speed pick-and-place robotics. The rapid pace of technological advancement in electronics drives demand for precise and compact solutions.
Manufacturing end-users drive the largest volume demand. The aerospace sector demands highly specialized, compliant solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global manufacturing economies balance domestic production with specialized imports for drag chain systems. Demand for high-performance solutions in advanced industrial automation drives cross-border trade. This dynamic ensures a continuous flow of innovative cable management technologies worldwide.
Germany
Germany's robust industrial base drives significant demand for sophisticated drag chain systems, particularly in automotive and machinery manufacturing. Compliance with CE marking requirements ensures high safety and performance standards for all components. The Stuttgart region, a hub for automotive and mechanical engineering, consistently integrates advanced cable management into its production lines.
China
China's rapid expansion in factory automation and high-speed robotics fuels a substantial market for drag chains. Adherence to GB standards for industrial products ensures quality and reliability in domestic manufacturing. The Yangtze River Delta, a key center for electronics and robotics production, actively incorporates precision cable carriers.
United States
United States manufacturing reshoring and increasing investment in logistics automation elevate demand for durable drag chain solutions. OSHA guidelines directly influence the design and installation of safe cable management systems in industrial environments. The Midwest industrial belt, known for heavy machinery and material handling, implements robust drag chain technology.
Japan
Japan's focus on precision robotics and advanced machine tools generates consistent demand for high-performance drag chains. Manufacturers must comply with JIS standards, which specify quality and performance criteria for industrial components. The Tokyo metropolitan area, a global hub for high-tech manufacturing, integrates compact and reliable cable carriers into its sophisticated production systems.
India
India's ongoing infrastructure development and robust automotive sector growth are driving demand for resilient drag chain systems. BIS standards ensure the quality and safety of industrial components used across various manufacturing applications. Maharashtra, a significant automotive and general manufacturing hub, increasingly adopts automated solutions requiring efficient cable management.
Drag Chain for Machine Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing specialized innovators and established industrial players. Several companies focus on niche applications, while others provide broad-line solutions for general automation. Key strategic archetypes include high-performance material specialists, integrated system providers, and regional manufacturers. Market participants engage in portfolio diversification and strategic partnerships to expand their reach and capabilities.
Specialists in advanced cable management solutions exemplify the market's innovation-driven segments. igus GmbH, a German-based company, consistently pushes boundaries with its smart plastics portfolio, integrating sensors for predictive maintenance. Tsubaki Kabelschlepp, leveraging its extensive experience, offers durable steel chain systems for heavy-duty industrial applications. Murrplastik, another German entity, focuses on integrated systems tailored for the robotics sector. These companies collectively demonstrate expertise in complex automation environments and material science.
| Leading Market Players |
|---|
| igus GmbH |
| Tsubaki Kabelschlepp |
| Murrplastik |
| Hennig |
| Dynatect Manufacturing |
| Brevetti Stendalto |
| Lapp Group |
| Arno Arnold GmbH |
| HELUKABEL |
| Others |
Cost & Logistics Intelligence
High-performance plastics manufacturing concentration in Germany and China influences component costs, impacting downstream pricing for specialized drag chain systems. This upstream control shapes margin potential for integrated solution providers.
Pricing Analysis
Industrial OEM buyers anchor a tiered pricing structure, balancing per-unit transactional costs for standard components with value-based pricing for intelligent systems. Price differentiation stems from CE marking compliance for safety and specialized material science innovations. Pricing softness reflects competition from wireless technologies in low-power applications. Mission-critical industrial applications exhibit lower price sensitivity compared to general automation end-users.
Supply Chain Analysis
Export-control regimes for advanced manufacturing technologies limit flows of specialized sensor components, impacting the supply chain. Production concentrates in Germany, China, and Japan, drawing from global suppliers of high-performance polymers and steel alloys. A structural risk involves single-source vulnerability for critical sensor and hybrid material inputs. Distribution runs through direct sales channels for major industrial OEMs and established regional distributor networks for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a robust substitution defense, as incumbents must navigate the emerging threat of wireless power and data transmission technologies. Maintaining relevance demands continuous innovation in physical cable management.
For Market Incumbents:Pre-empt the wireless technology substitution threat by accelerating R&D into intelligent drag chains with integrated sensors and predictive analytics. Standardize communication protocols to ease integration complexities for factory control systems. Deepen material science expertise in hybrid composites to enhance load capacities and service life, reinforcing the value proposition of physical carriers.
For New Entrants and Emerging Players:Pursue niche white-space opportunities in the renewable energy sector, focusing on weather-resistant and durable solutions for wind turbines. Target medical and laboratory automation, offering cleanroom-certified and low-particle drag chains. A focused go-to-market angle involves providing highly specialized, compliant solutions for precision robotics in these emerging fields.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-cap specialists in intelligent drag chain systems, presenting attractive acquisition targets. The market exhibits long-term viability over a 5-10 year window, driven by sustained factory automation investment. Focus on companies with robust intellectual property in smart plastics or hybrid material composites. A critical signal to watch is the increasing adoption rate of subscription-based predictive maintenance services.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Material R&D | New composite materials enable higher load capacities and extended service life for heavy-duty CNC machines. |
| Standardize Sensor Communication Protocols | Improved interoperability eases integration of smart chain data into diverse SCADA and MES systems. |
| Expand Solutions for Renewable Energy | Specialized weather-resistant drag chains are critical for wind turbine and solar tracking system reliability. |
| Acquire Software Integration Specialists | This enhances the capability to integrate smart chain data seamlessly into complex industrial control environments. |
| Obtain Cleanroom Certifications | Compliance enables penetration into the high-growth medical and electronics assembly automation sectors. |
Research Approach
Desk research of industry association reports, patent databases, and company annual filings preceded structured interviews with automation engineers, procurement managers, and material scientists. This combined primary and secondary research approach validated market dynamics and growth catalysts. Bottom-up data collection from component suppliers was triangulated with top-down market sizing estimates.
Assumptions regarding a stable regulatory environment and sustained factory automation investment underpinned the forecast framework across the analysis window. The market was segmented by product type, application, size, end-user, and material composition. Compound annual growth rates were derived from historical data and projected adoption rates. Advanced material costs served as a key forecast input.
Sensitivities concentrate around geopolitical trade policies affecting material supply and rapid advancements in wireless power transmission. Forecasts reflect current market assumptions, but significant supply chain disruptions or shifts in manufacturing investment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Europe Forklift Truck Market