
 Dewatering Screen Market | 2026-2036
Dewatering Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Dewatering Screen Market Analytics
Aftermarket maintenance contracts is pivoting how OEMs monetize dewatering screen deployments, converting one-time equipment sales into recurring revenue streams tied to screen panel replacement and vibration system calibration. Metso leverages its global service network to anchor long-term parts agreements across Scandinavian mining districts. Weir competes through intensive R&D spending on polyurethane screen media formulations that extend wear life in abrasive slurry environments. McLanahan specializes in modular screen architectures that reduce field assembly time for Appalachian coal preparation plants.
A dewatering screen is a vibratory separation device engineered with polyurethane or wire mesh deck surfaces operating at accelerations between 3-5 G to extract free moisture from mineral slurries, tailings, or granular solids. The equipment serves essential dewatering duties in sand production circuits where moisture reduction below 15 percent prevents downstream handling issues and transport weight penalties. Linear screens dominate the product type category due to their mechanical simplicity and lower capital footprint, though high-frequency screens capture the fastest-growing segment as operators pursue finer cut points in silica sand processing. Vacuum screens command premium positioning in chemical processing applications where moisture targets fall below 10 percent, creating concentrated margin pools for specialized panel suppliers.
EPA effluent limitation guidelines under the Clean Water Act shape discharge compliance requirements for US mining and construction sites, directly influencing screen specification and moisture performance guarantees. ECHA's REACH framework restricts certain polyurethane precursor chemistries used in European screen panel manufacturing, compelling reformulation investments by regional suppliers. China's MEE enforces dual carbon goals that tighten water recycling mandates for mineral processing facilities, accelerating adoption of closed-loop dewatering circuits. Stakeholders must monitor how evolving tailings dam safety regulations across multiple jurisdictions redefine acceptable moisture thresholds and drive capital allocation toward higher-performance screening technologies.
Market Dynamics
Aftermarket service contracts are restructuring how OEMs monetize dewatering screen deployments, converting one-time equipment sales into recurring revenue streams tied to screen panel replacement and vibration system calibration. Mining operators now prioritize total cost of ownership over upfront capital expenditure, forcing suppliers to embed predictive maintenance capabilities and remote diagnostics into their commercial models.
Growth Catalysts
- EPA effluent limitation guidelines:The Clean Water Act mandates drive moisture performance guarantees at US mining and construction sites, directly influencing screen specification requirements for tailings discharge compliance.
- Iron ore processing upgrades:Brazil's mineral belt is experiencing concentrated equipment replacement cycles as major producers modernize beneficiation circuits to handle lower-grade ore feeds.
- Polyurethane screen media advances:Formulation improvements extending wear life in abrasive slurry environments reduce unplanned downtime and shift buyer preference toward premium panel suppliers.
Market Restraints
- Steel price volatility:Structural frame fabrication costs fluctuate with commodity cycles, compressing margins for domestic manufacturers and complicating project budgeting for mine operators.
- REACH chemical restrictions:ECHA's framework limits certain polyurethane precursor chemistries used in European screen panel manufacturing, compelling reformulation investments by regional suppliers.
- High-frequency screen complexity:Advanced vibration systems require specialized technical expertise for field commissioning, creating deployment bottlenecks in remote mining districts.
Strategic Opportunities
- Closed-loop water recycling:China's MEE dual carbon goals tighten mandates for mineral processing facilities, accelerating adoption of vacuum-assisted dewatering circuits with sub-10 percent moisture targets.
- Modular field assembly:Reduced installation timelines for Appalachian coal preparation plants create differentiation for suppliers offering pre-engineered screen architectures.
- Sensor-integrated diagnostics:Convergence of vibration monitoring and edge computing enables condition-based maintenance contracts that lock in long-term parts agreements.
Industry Challenges
- Vibration engineer scarcity:Specialized commissioning expertise for high-G acceleration systems remains concentrated among aging technician pools, constraining deployment velocity.
- Legacy control integration:New screen installations must interface with existing SCADA infrastructure at brownfield sites, extending project timelines and inflating integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dewatering Screen Market |
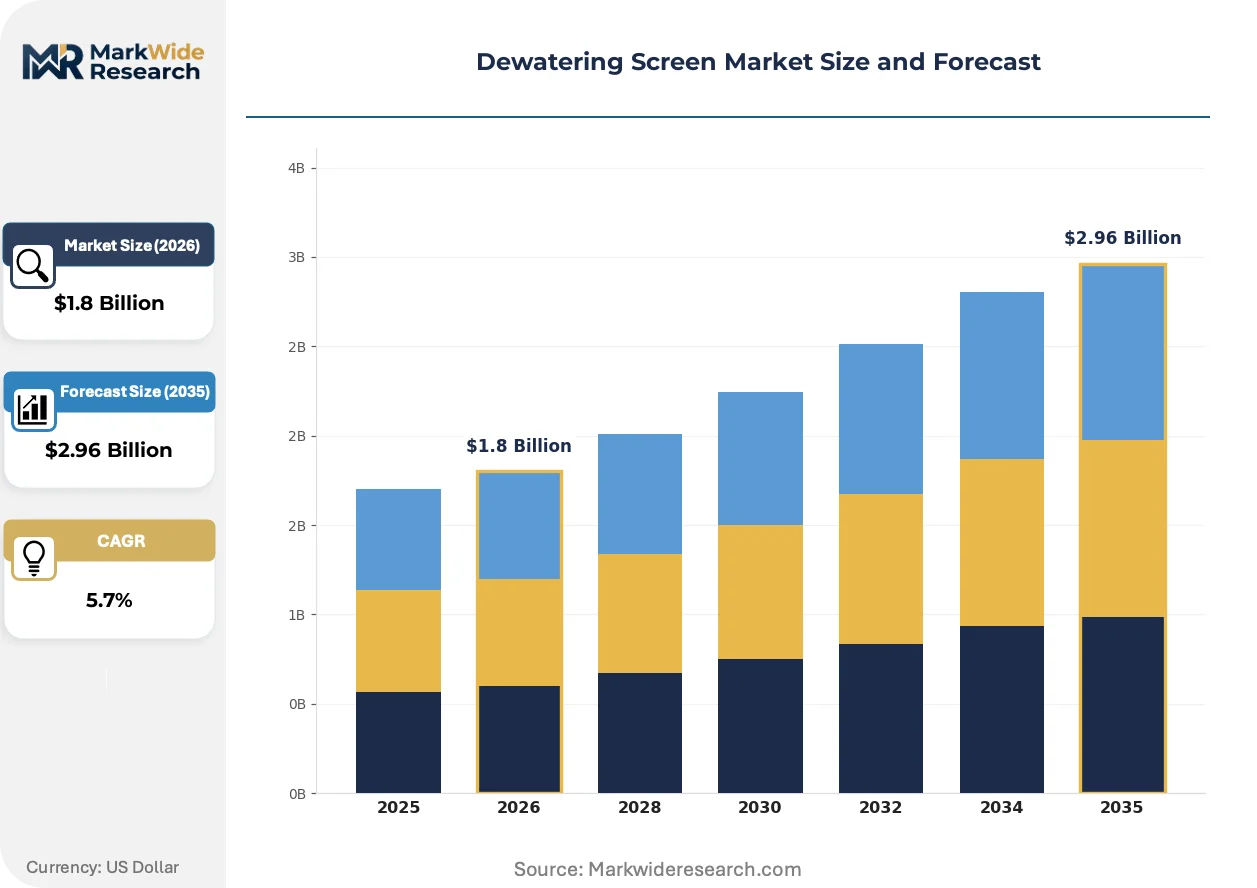
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Screens, Vacuum Screens, High-Frequency Screens, Belt Filters End User: Mining, Construction, Agriculture, Wastewater Treatment Material: Metal, Plastic, Composite, Fiber Application: Sand Production, Coal Processing, Mineral Processing, Chemical Processing |
| Companies Covered | Weir, Multotec, McLanahan, Superior Industries, General Kinematics, Metso, SPALECK, Vibramech, FLSmidth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dewatering Screen Market Evolving Landscape
Digital monitoring systems are penetrating dewatering screen installations at accelerating rates, converting mechanical separation equipment into data-generating assets. This instrumentation shift enables predictive maintenance models that reduce unplanned downtime and reshape supplier-customer relationships.
Machine vision-based wear detection is automating screen panel replacement scheduling by analyzing mesh degradation patterns in real time. Australian iron ore operators are deploying these systems most aggressively, capturing operational data that feeds back into panel design iterations. The technology is automating procurement workflows previously managed through manual inspection cycles.
China's MIIT has tightened GB standards for industrial water recycling, pushing domestic quarries toward vacuum-assisted dewatering systems with enhanced moisture removal capabilities. Mineral processors in Shandong and Hebei provinces face accelerated compliance deadlines, driving specification changes for new screen acquisitions. Chemical processing applications with sub-10 percent moisture targets command premium positioning for specialized panel suppliers.
Maintenance contract unbundling is fragmenting traditional OEM service relationships as mine operators seek specialized third-party providers for vibration system calibration. Procurement teams at mid-tier sand production facilities now separate screen panel sourcing from technical service agreements, compressing supplier margins on bundled offerings. This pattern is most visible in silica sand processing clusters where moisture reduction below 15 percent prevents downstream handling penalties.
Dewatering Screen Market Segmentation
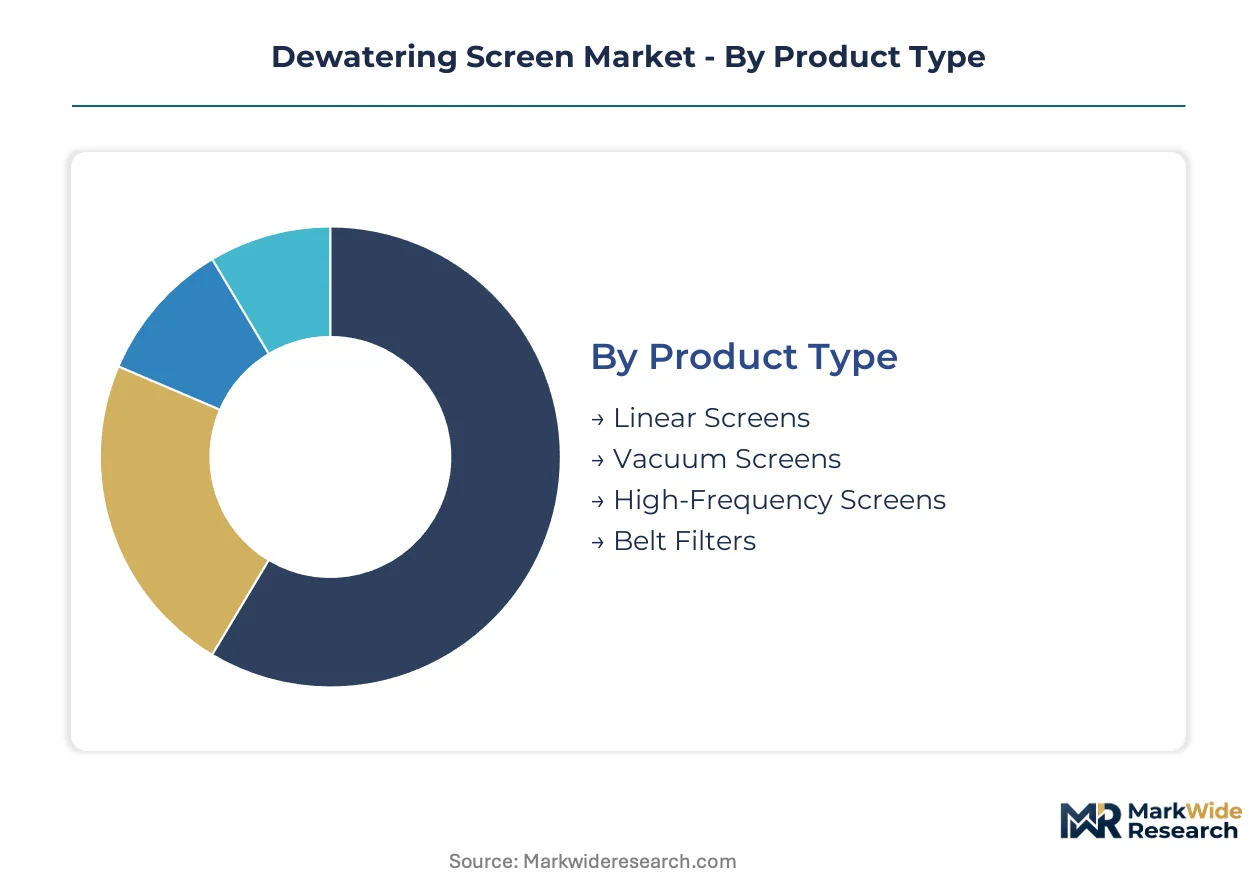
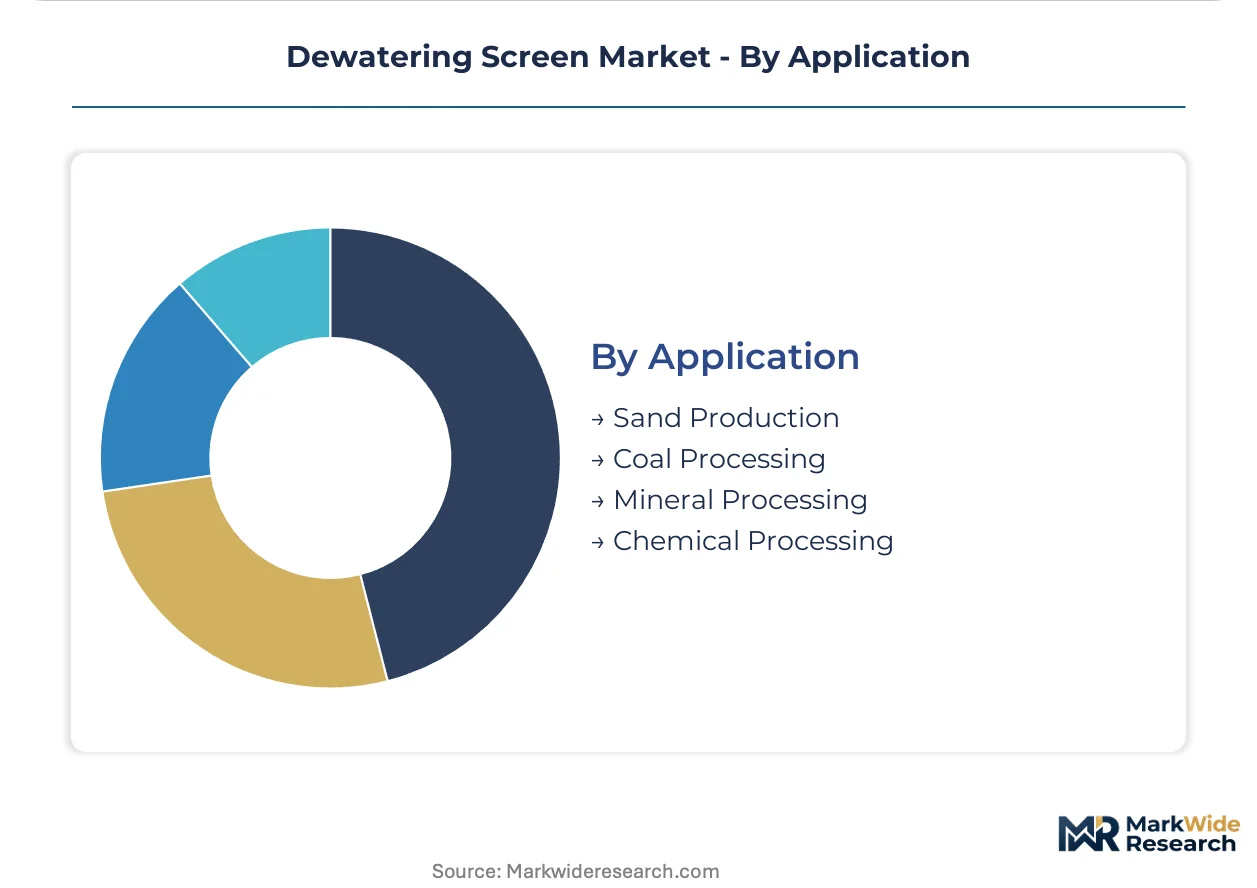
Dewatering screen segmentation reveals how equipment specification varies with integration depth across standalone processing circuits versus embedded beneficiation lines. Buyers select product architectures based on moisture targets, abrasion exposure, and existing plant infrastructure constraints.
Product Type:
Linear screens function as standalone separation units in simple gravity-fed circuits, while vacuum and high-frequency configurations embed into complex closed-loop systems demanding precise moisture control.
- Linear Screens:These units employ dual-motor vibratory drives generating straight-line motion across polyurethane or wire mesh decks. Australian iron ore operators deploy linear screens extensively in tailings circuits ahead of EPA discharge requirements, favoring their mechanical simplicity and lower field maintenance demands. Linear screens lead volumes today; high-frequency screens are gaining share fastest.
- Vacuum Screens:Negative-pressure dewatering achieves sub-10 percent moisture through applied suction beneath the screen deck. China's Shandong province quarries specify vacuum-assisted systems under tightened MIIT water recycling mandates, creating concentrated demand for specialized panel suppliers capable of maintaining seal integrity under high vacuum loads.
- High-Frequency Screens:Operating at accelerations exceeding 4 G, these systems target fine cut points in silica sand processing where moisture reduction below 15 percent prevents transport weight penalties.
- Belt Filters:Continuous belt designs integrate into chemical processing lines requiring consistent cake discharge for downstream thermal drying stages.
Cost tiering separates capital-intensive vacuum systems from standardized linear units, with high-frequency screens commanding mid-tier positioning based on vibration component complexity.
End User:
Mining operations generate the highest equipment wear rates and shortest replacement cycles, while construction and agricultural buyers prioritize portability and rapid field deployment.
- Mining:Hard rock and coal extraction drives specification toward abrasion-resistant polyurethane media and reinforced structural frames. Brazil's iron ore belt replacement cycles concentrate demand for heavy-duty configurations capable of processing lower-grade ore feeds with elevated slurry volumes.
- Construction:Mobile aggregate producers favor modular screen architectures that reduce assembly time at temporary quarry sites. Sand production circuits dominate this segment where moisture targets prevent downstream handling issues at concrete batching plants.
- Agriculture:Grain and seed processing applications require gentle dewatering to preserve product integrity, driving specification toward lower-G linear configurations.
- Wastewater Treatment:Municipal sludge dewatering demands corrosion-resistant materials and automated cleaning cycles to manage biological fouling.
Mining commands the largest installed base; wastewater treatment is expanding most quickly as utilities upgrade aging infrastructure.
Material:
Panel material selection directly determines wear life and replacement frequency, with composite formulations emerging as a hybrid alternative between traditional metal and polymer options.
- Metal:Stainless steel and high-tensile wire mesh panels withstand extreme temperatures and sharp-edged ore particles. Appalachian coal preparation plants specify metal decks for raw coal circuits where tramp material damage risks exceed polyurethane tolerance limits.
- Plastic:Injection-molded polyurethane dominates sand production and fine mineral processing due to abrasion resistance and noise reduction properties.
- Composite:Reinforced polymer-ceramic hybrids target mid-abrasion applications seeking extended wear life without full ceramic cost premiums.
- Fiber:Specialized synthetic fiber screens serve niche chemical processing with extreme pH exposure where metal corrosion and polymer degradation both present risks.
Polyurethane leads procurement volumes; composite materials are climbing the fastest as formulation chemistry advances.
Application:
Moisture specification thresholds vary sharply across applications, with chemical processing demanding the driest outputs and coal processing tolerating higher residual moisture.
- Sand Production:Frac sand and construction aggregate producers target 10-15 percent moisture to avoid transport weight penalties and downstream handling blockages. Silica sand clusters in Wisconsin and Texas specify high-frequency screens to meet API proppant quality standards.
- Coal Processing:Dense medium circuit drain-and-rinse applications prioritize throughput over moisture precision, with linear screens dominating prep plant configurations.
- Mineral Processing:Base metal and iron ore beneficiation circuits integrate dewatering ahead of filtration or thermal drying stages.
- Chemical Processing:Fertilizer and industrial mineral producers require sub-10 percent moisture for pneumatic conveying compatibility, driving vacuum screen specification.
Sand production anchors current equipment deployment; chemical processing offers the steepest expansion trajectory as specialty mineral demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing dewatering screen procurement as compliance-cost differentials widen between jurisdictions with stringent effluent mandates and those with emerging enforcement frameworks.
Australia
Iron ore operators in the Pilbara and Queensland coal basins are accelerating high-frequency screen deployments to meet tightened EPA discharge requirements ahead of 2026 compliance deadlines. The country's national environmental regulator has finalized moisture-content thresholds for tailings dam management that exceed prior voluntary industry standards. Perth-based engineering firms are contracting specialized vibration technicians to support remote site commissioning across Western Australia's mineral processing corridors.
China
Domestic quarries in Shandong and Hebei provinces face accelerated GB standard compliance timelines for industrial water recycling that mandate vacuum-assisted dewatering capabilities. The Ministry of Ecology and Environment has linked dual carbon goal enforcement to mineral processing facility permits, tightening closed-loop circuit requirements. Equipment suppliers are localizing polyurethane panel production near Tangshan steel-processing clusters to reduce lead times for state-owned mining enterprises.
Brazil
Vale's beneficiation circuit modernization across Minas Gerais and Pará states is compressing replacement cycles for heavy-duty screen configurations processing lower-grade iron ore feeds. ANVISA-aligned environmental licensing for tailings facilities now incorporates moisture-performance guarantees that favor premium equipment specifications. Domestic fabricators in Belo Horizonte industrial districts are expanding structural frame welding capacity to capture import substitution opportunities.
Germany
Ruhr Valley coal preparation plants and Bavarian industrial mineral processors are navigating ECHA REACH restrictions on polyurethane precursor chemistries that compel reformulation investments by regional panel suppliers. The country's federal environmental agency has harmonized tailings management standards with EU-wide dam safety directives. Engineering consultancies in Düsseldorf and Munich are specializing in SCADA integration services for brownfield screen retrofits.
United States
Appalachian coal preparation plants and Wisconsin frac sand operations are prioritizing modular screen architectures that reduce field assembly timelines under compressed project schedules. EPA effluent limitation guidelines under the Clean Water Act have tightened moisture-performance guarantees for discharge permits in mining-heavy jurisdictions. Houston-based oilfield services clusters are cross-applying dewatering expertise to silica sand proppant processing for Permian Basin drilling demand.
Dewatering Screen Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mining-heavy applications consolidating around full-service OEMs while construction and aggregate markets sustain a fragmented tier of regional fabricators. The vendor base organizes into three strategic archetypes: integrated multinationals with global service networks, polyurethane-focused material specialists, and modular-system integrators targeting rapid-deployment niches. Dominant competitive moves include backward integration into captive screen panel production and technology licensing agreements that transfer vibration system IP to regional assembly partners.
Among established multinational OEMs, Metso and Weir occupy positions exemplifying the integrated-service archetype, leveraging extensive parts logistics networks to anchor long-term maintenance contracts. McLanahan represents the modular-specialist vector with configurations designed for reduced field assembly complexity. These three companies illustrate how competitive positioning stratifies between scale-driven aftermarket capture and design-led deployment velocity.
| Leading Market Players |
|---|
| Weir |
| Multotec |
| McLanahan |
| Superior Industries |
| General Kinematics |
| Metso |
| SPALECK |
| Vibramech |
| FLSmidth |
| Others |
Value Network & Pricing Analysis
Polyurethane formulation chemistry advances are simultaneously compressing panel replacement costs and consolidating supply among specialized compounders capable of meeting REACH-compliant specifications. This dual shift tightens margins for commodity screen producers while elevating pricing power for certified suppliers serving European mineral processors.
Pricing Analysis
Distributor markups on replacement screen panels run 25-40 percent above direct OEM pricing, creating arbitrage opportunities for mine operators with sufficient procurement scale. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-assisted systems with sub-10 percent moisture guarantees from basic linear configurations. Cost compression in standard-grade polyurethane panels is intensifying because Chinese compounders are expanding Tangshan production capacity. Construction aggregate buyers exhibit highest price sensitivity due to project-based budgeting cycles, while iron ore operators prioritize wear-life guarantees over unit cost.
Supply Chain Analysis
China's MIIT domestic-content mandates for mineral processing equipment are reshaping sourcing patterns for state-owned mining enterprises across Shandong and Hebei provinces. Structural frame fabrication draws from China, Germany, and Brazil, while polyurethane precursor supply rests on Belgium, China, and South Korea. Single-source vulnerability concentrates in specialized high-G vibration motors sourced from Japanese and German suppliers. Distribution runs through regional equipment distributors with captive service technician networks in mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dewatering screen market reads as a late-cycle quality story as EPA effluent guidelines and China's dual carbon goals shift procurement toward premium moisture-performance specifications. Iron ore and frac sand operators now embed total cost-of-ownership models that favor extended-wear panel technologies over upfront capital savings.
For Market Incumbents: Extend predictive maintenance contract coverage to lock in recurring parts revenue against emerging third-party calibration specialists. Anchor long-term polyurethane panel agreements through captive formulation partnerships that exceed REACH compliance thresholds. Brazilian iron ore replacement cycles and Australian EPA deadlines concentrate near-term demand capture opportunities. For New Entrants and Emerging Players: Mid-tier sand production facilities in Wisconsin and Texas represent an underserved buyer archetype seeking modular field-assembly configurations without bundled technical service premiums. White-space exists in sensor-integrated diagnostics for brownfield SCADA retrofits at Appalachian coal preparation plants. A direct-procurement platform targeting unbundled panel sourcing separates price-sensitive construction aggregate buyers from incumbent OEM service bundles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional polyurethane panel compounders with REACH-compliant formulations and untapped aftermarket service capabilities. Five-to-ten year viability hinges on water recycling mandate acceleration across mineral processing jurisdictions. The signal to watch is EPA enforcement variance across US mining districts as a proxy for specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Compounding | REACH-compliant formulation control secures European mining contracts against reformulation-disrupted competitors. |
| Sensor-Integrated Diagnostics Deployment | Vibration monitoring convergence with edge computing enables condition-based maintenance contracts at Pilbara iron ore sites. |
| Modular Field-Assembly Architecture | Pre-engineered screen configurations reduce installation timelines for compressed-schedule Appalachian coal projects. |
| Vacuum-Assisted System Localization | Domestic fabrication near Tangshan steel clusters captures Chinese state-owned mining procurement preferences. |
| Aftermarket Service Contract Unbundling | Separate technical calibration from panel sourcing to penetrate price-sensitive silica sand processing clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Australian iron ore operations, plant engineers at Appalachian coal preparation facilities, OEM procurement teams, aftermarket service heads, and polyurethane compounder technical directors with secondary validation. Trade data from customs filings, SEC equipment manufacturer disclosures, MEE permitting databases, and EPA enforcement records anchored supply-side sizing. Bottom-up installed base counts triangulated against top-down mineral processing capacity estimates.
Segment-weighting across product type, end user, material, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted replacement cycle modeling and regulatory compliance deadline clustering. Iron ore grade decline trajectories in Brazil and frac sand API proppant specification tightening in Texas informed volume outlooks.
Underlying measurement precision varies by segment; vacuum screen and high-frequency configurations carry tighter precision than standardized linear units due to concentrated supplier visibility. Forecasts reflect assumptions around EPA guideline enforcement consistency and MIIT dual carbon goal implementation pacing. A small set of triggers—tailings dam safety regulation revisions, steel price volatility spikes, and vibration engineer labor pool constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Europe Conveyors Market