
 Hybrid System Market | 2026-2036
Hybrid System Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid System Market Intelligence
Demand from fleet operators focused on total cost of ownership is bifurcating the market away from traditional OEM procurement cycles. Siemens Energy leverages its industrial power systems expertise to target marine and grid applications. Continental AG specializes in integrated powertrain components and control units for light-duty vehicles. Meanwhile, Denso sustains its strong position through advanced thermal management and battery management systems for the automotive sector.
A hybrid system integrates an internal combustion engine with an electric propulsion system, comprising an electric motor and energy storage. These systems use a power split device to manage energy flow, aiming to improve fuel efficiency and reduce emissions. While full hybrid systems lead in passenger vehicles, plug-in hybrid technology is expanding in commercial applications. The marine vessels segment offers higher margin potential for specialized diesel-electric configurations.
Emissions mandates from the US EPA and the EU's vehicle CO2 standards directly influence system design and adoption rates. Concurrently, technical requirements like China's GB standards and ISO specifications for battery safety govern market access and component interoperability. Component sourcing strategies, especially for batteries and power electronics, remain a critical decision point for all manufacturers.
Market Dynamics
The convergence of stringent emissions regulations and the commercial imperative for lower total cost of ownership is the central force shaping the hybrid system market, compelling adoption in logistics and public transport fleets across industrial economies.
Growth Catalysts
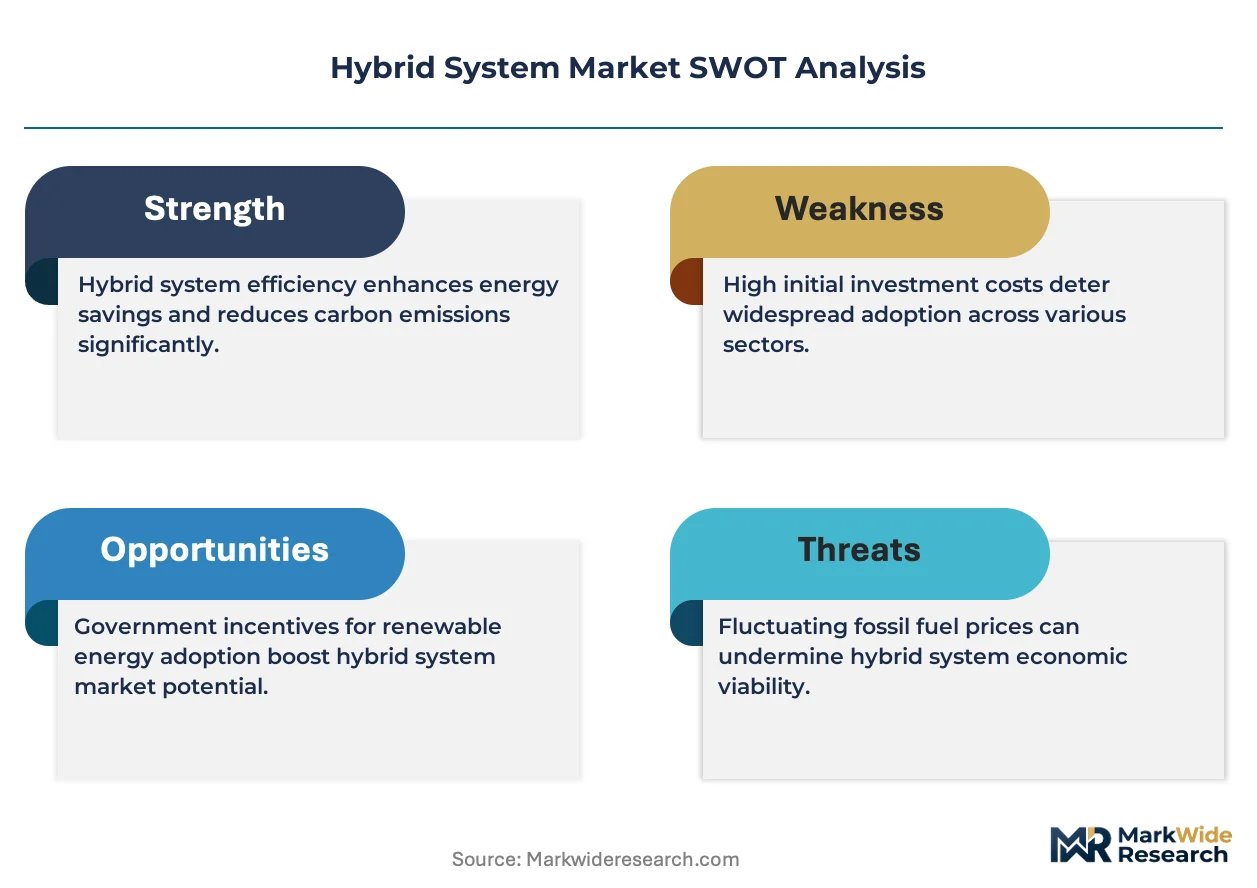
- Regulatory Mandates:Stricter emissions targets, including the EU's vehicle CO2 standards and China's dual carbon goals, create a non-negotiable demand floor for hybrid systems in both passenger and commercial vehicles.
- Commercial Fleet Economics:Fleet operators in logistics and public transport are adopting hybrid vehicles to reduce fuel consumption and operational expenses, driven by a focus on total cost of ownership over initial purchase price.
- Component Technology Advancement:Continuous improvements in battery management systems and power electronics increase the efficiency, reliability, and power density of hybrid powertrains, making them more commercially viable.
Market Restraints
- High Initial Capital Outlay:The upfront cost of hybrid systems, particularly the battery pack and power electronics, remains a significant barrier to adoption compared to conventional internal combustion engine powertrains.
- Raw Material Dependency:The supply chain for critical battery materials, including lithium and cobalt, is highly concentrated geographically, creating price volatility and geopolitical supply risks for manufacturers.
- Infrastructure Gaps:Limited availability of public and private charging infrastructure for plug-in hybrid electric vehicles (PHEVs) constrains their utility and appeal, especially in less developed regions.
Strategic Opportunities
- Specialized Marine Applications:The development of customized diesel-electric hybrid propulsion systems for marine vessels, such as ferries and tugboats, presents a high-margin opportunity due to specific operational and environmental needs.
- Off-Highway Vehicle Electrification:Extending hybrid technology to non-road mobile machinery, including construction and agricultural equipment, opens a new market segment driven by urban air quality rules and worksite noise restrictions.
- Emerging Market Fleet Modernization:Underpenetrated markets in South America and Southeast Asia offer significant growth potential as their commercial fleets begin to modernize and face emerging environmental regulations.
Industry Challenges
- System Integration Complexity:Integrating hybrid powertrains with diverse vehicle platforms and legacy electronic architectures requires substantial engineering expertise and extensive testing, increasing development time and cost.
- Technical Skill Shortages:A deficit of technicians and engineers skilled in high-voltage system diagnostics, repair, and software management hinders after-sales service and long-term maintenance capabilities.
- Navigating Fragmented Standards:Manufacturers face increased compliance costs and design complexity in managing divergent technical and safety regulations, such as China's GB standards versus ISO specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid System Market |
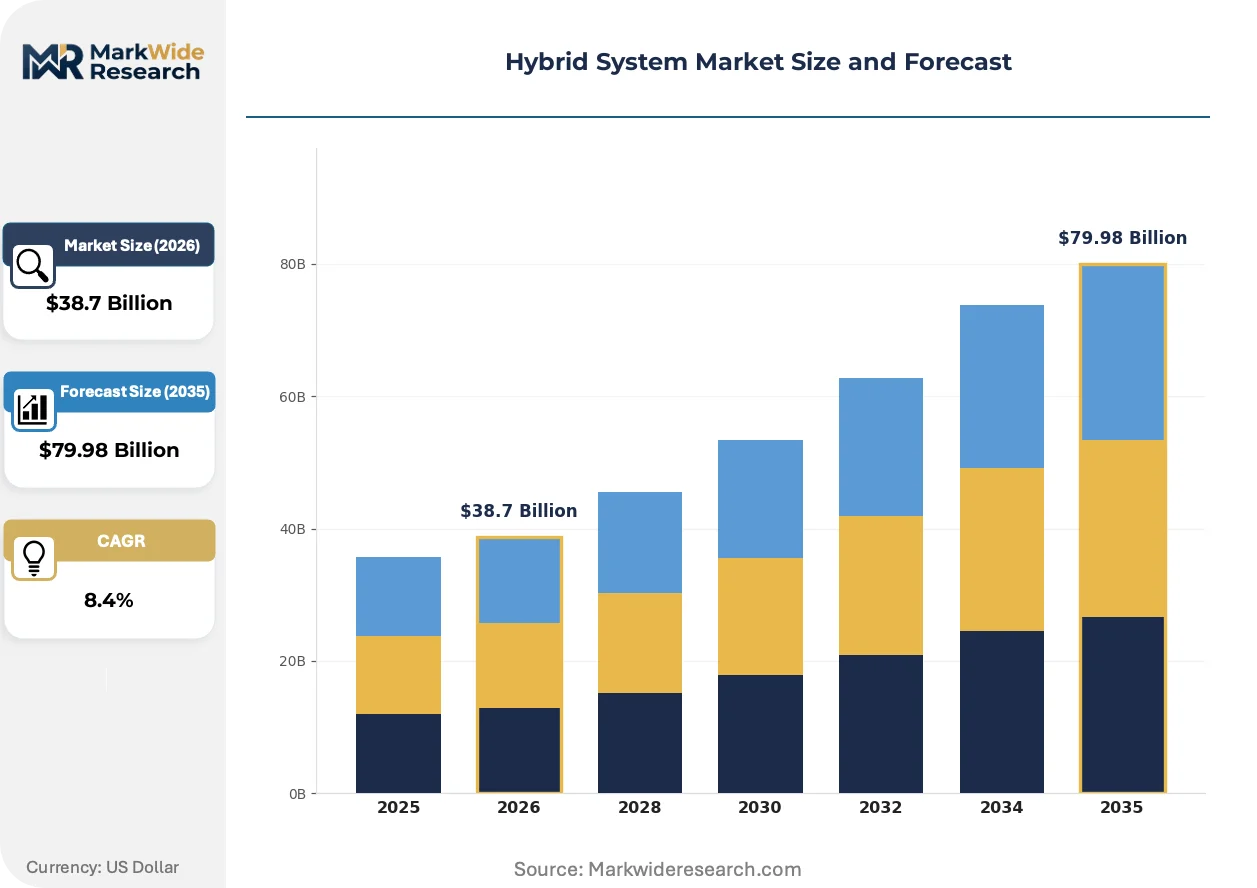
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Diesel-Electric, Gasoline-Electric, Plug-in Hybrid, Full Hybrid, Mild Hybrid Technology: Battery Management System, Regenerative Braking, Electric Motor, Power Split Device, Thermal Management Application: Light-Duty Vehicles, Commercial Vehicles, Agricultural Machinery, Construction Equipment, Marine Vessels End User: OEMs, Fleet Operators, Aftermarket Suppliers, Government Agencies, R&D Institutions |
| Companies Covered | Siemens Energy, General Electric, Bosch, Continental AG, Denso, Johnson Controls, Wärtsilä, ZF Friedrichshafen AG, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid System Market Strategic Shifts & Innovations
Technological advancements in power electronics and energy storage are enabling hybrid systems to penetrate more demanding applications. This evolution is occurring alongside a regulatory push that solidifies the business case for hybridization beyond niche passenger car segments.
Wide-bandgap semiconductors, such as Silicon Carbide (SiC), provide higher thermal conductivity and switching frequency in power inverters. Automotive manufacturers are rapidly adopting this technology for high-performance hybrid and electric vehicle powertrains. The superior efficiency of SiC is supplanting traditional silicon-based components, enabling more compact, lighter, and powerful systems.
Emissions mandates like the US EPA's rules for heavy-duty vehicles and the EU's CO2 standards for trucks directly influence system design. These regulations compel manufacturers to integrate hybrid technologies to meet fleet-wide average emissions targets. The commercial vehicle sector, particularly long-haul trucking and urban delivery segments, is most affected and is accelerating its adoption of diesel-electric hybrid solutions.
Fleet operators are shifting procurement models to prioritize total cost of ownership (TCO) over initial vehicle price. This behavioral change disrupts traditional sales cycles by favoring vehicles that demonstrate superior fuel economy and lower maintenance costs over their operational lifetime. The trend is most visible within large logistics and municipal transport fleets in North America and Europe.
Hybrid System Market Segmentation
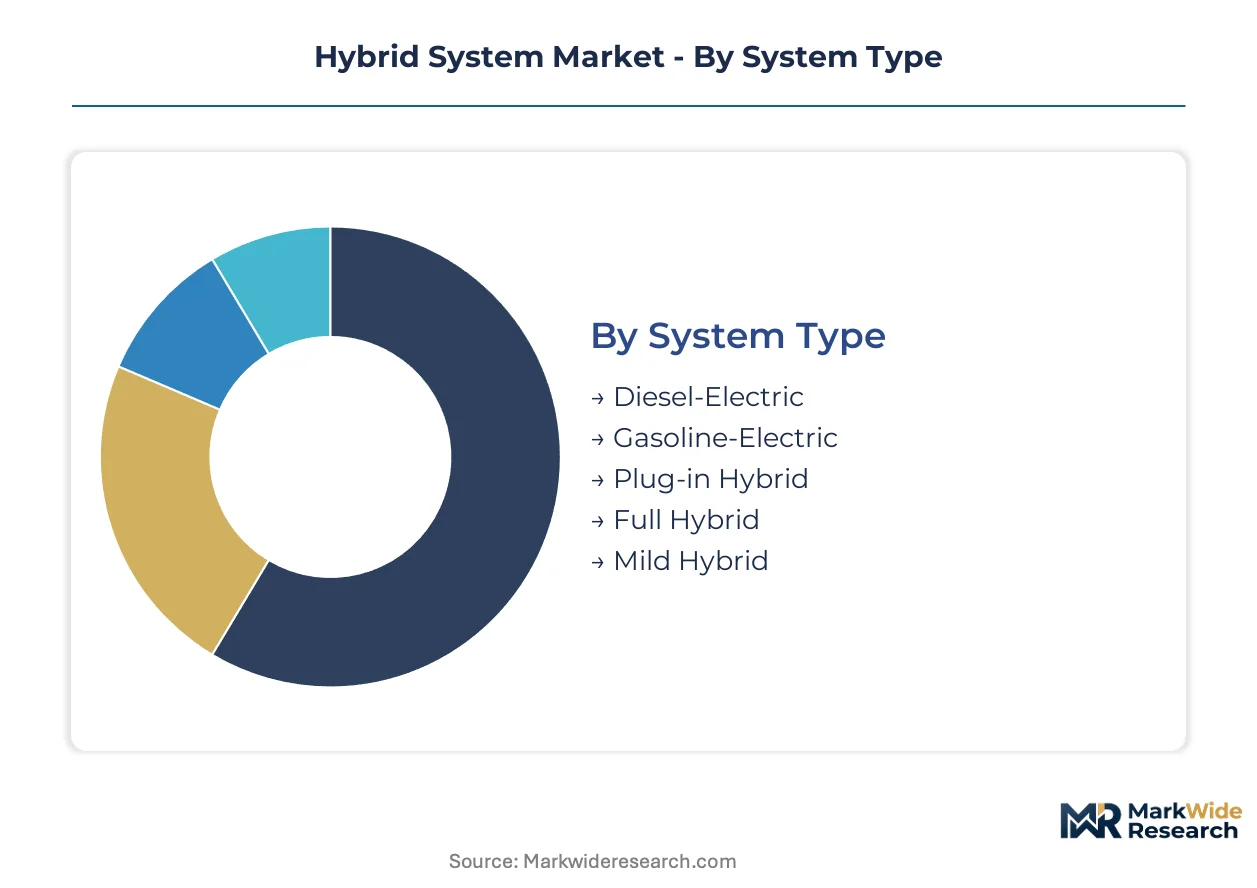
The hybrid system market's structure reflects diverse technological approaches and end-use requirements. Understanding these segments clarifies where innovation is most impactful and where demand drivers are strongest. This granular view reveals critical areas for strategic investment and market penetration.
System Type:
Margin pools within hybrid system types vary significantly, with specialized configurations for heavy-duty applications often commanding higher value.
- Diesel-Electric:This system combines a diesel engine with an electric motor and battery, often in series or parallel configurations. Demand concentrates in marine vessels and heavy commercial vehicles, driven by the need for high torque and efficiency in demanding operational cycles.
- Full Hybrid:Full hybrid systems can operate solely on electric power, internal combustion engine power, or a combination, employing a power split device. Passenger vehicle adoption in Germany and China drives this segment, seeking substantial fuel efficiency gains and lower urban emissions.
- Gasoline-Electric:This common configuration pairs a gasoline engine with an electric motor, primarily for passenger cars and light commercial vehicles.
- Plug-in Hybrid:PHEVs feature larger batteries and external charging capabilities, extending electric-only range for commercial applications.
- Mild Hybrid:Mild hybrids use a smaller electric motor to assist the engine during acceleration and enable advanced start-stop functions.
Full Hybrid technology holds significant installed capacity in passenger cars. Plug-in Hybrid technology is rotating up the share rankings within commercial vehicle fleets.
Technology:
The maturity of hybrid system technologies dictates their integration complexity and performance benefits across diverse applications.
- Battery Management System:BMS monitors and controls battery parameters like voltage, current, and temperature, ensuring safety and optimizing performance and lifespan. Demand concentrates in all hybrid vehicles, driven by the need for reliable energy storage and regulatory compliance with safety standards.
- Thermal Management:Thermal management systems regulate operating temperatures for batteries, electric motors, and power electronics, preventing overheating and ensuring optimal efficiency. Automotive manufacturers, particularly Denso, prioritize advanced thermal solutions for high-performance hybrid powertrains.
- Regenerative Braking:This system converts kinetic energy during braking into electrical energy, recharging the battery and improving overall efficiency.
- Electric Motor:Electric motors provide propulsion assistance or sole propulsion, converting electrical energy into mechanical power for hybrid systems.
- Power Split Device:A power split device mechanically links the engine, electric motor, and drivetrain, managing energy flow in complex hybrid configurations.
Demand for advanced Battery Management Systems is accelerating. Electric Motors remain foundational components across all hybrid architectures.
Application:
The volume and scale of hybrid system deployment vary significantly across different vehicle applications.
- Commercial Vehicles:This segment includes trucks, buses, and vans, where hybrid systems reduce fuel consumption and operational costs for fleet operators. Adoption in logistics and public transport fleets across Germany and China is driven by stringent emissions mandates and total cost of ownership focus.
- Marine Vessels:Hybrid propulsion for marine vessels, such as ferries and tugboats, integrates diesel-electric configurations for improved fuel efficiency and lower emissions in port areas. Specialized technical requirements and higher margin potential characterize this segment for Siemens Energy.
- Light-Duty Vehicles:Light-duty vehicles, including passenger cars and SUVs, represent a large volume segment for gasoline-electric and full hybrid systems.
- Agricultural Machinery:Hybrid systems in agricultural machinery, like tractors and harvesters, offer improved fuel economy and reduced noise for off-highway operations.
- Construction Equipment:Hybrid technology in construction equipment, such as excavators and loaders, aims to lower emissions and fuel consumption at worksites.
Fleet operators are prioritizing commercial vehicle hybridization for cost savings. OEMs continue to optimize light-duty vehicle platforms for hybrid integration.
End User:
Supply concentration for hybrid systems influences the procurement strategies of various end-user categories.
- Fleet Operators:Fleet operators manage large vehicle inventories for logistics, public transport, or other commercial services, prioritizing total cost of ownership. Their procurement models are shifting to favor hybrid vehicles that offer superior fuel economy and lower long-term maintenance expenses.
- OEMs:Original Equipment Manufacturers integrate hybrid systems into new vehicles during the production phase, influencing design and component sourcing decisions. Traditional OEM procurement cycles are being disrupted by fleet operators' demand for specialized, cost-effective hybrid solutions.
- Aftermarket Suppliers:Aftermarket suppliers provide components and services for hybrid system repair, maintenance, and upgrades post-vehicle sale.
- Government Agencies:Government agencies procure hybrid vehicles for public service fleets, driven by environmental mandates and sustainability goals.
- R&D Institutions:R&D institutions conduct research into advanced hybrid technologies, focusing on next-generation components and system optimization.
Regulatory pressures are compelling Government Agencies to adopt hybrid fleet solutions. R&D Institutions are defining future technical requirements for advanced hybrid powertrains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of advanced hybrid system components from East Asian manufacturers to European commercial vehicle assemblers is intensifying. This dynamic reflects both technological leadership and evolving market demand. Regulatory alignment further supports these cross-continental supply chains.
Germany
Demand for full hybrid systems in Germany stems from stringent EU CO2 standards for passenger vehicles. The EU Green Deal mandates further accelerate adoption across commercial fleets. Industrial clusters in Bavaria, including Munich, drive innovation in automotive powertrain integration.
China
China's dual carbon goals necessitate widespread hybrid adoption, particularly in public transport fleets. The Ministry of Ecology and Environment's emissions standards push manufacturers towards cleaner solutions. Major manufacturing hubs like the Yangtze River Delta concentrate production and deployment of hybrid buses.
United States
United States demand for hybrid systems is driven by commercial fleet operators seeking reduced fuel costs. The US EPA's heavy-duty vehicle regulations compel engine efficiency improvements. Automotive R&D centers in Michigan, notably Detroit, focus on optimizing powertrain performance for diverse applications.
Japan
Japanese automotive manufacturers prioritize hybrid system integration for global export markets. METI's fuel efficiency targets encourage continuous technological refinement. Industrial zones in Aichi Prefecture, including Nagoya, remain central to advanced hybrid component production.
Hybrid System Market Key Industry Players
Listed leaders compete with private specialists across the hybrid system value chain, creating a dynamic market environment. The market exhibits a tiered structure, with established automotive suppliers alongside niche technology providers and industrial power system integrators. Strategic archetypes include integrated powertrain developers, specialized component manufacturers, and application-specific solution providers. Companies primarily engage in strategic partnerships for technology co-development and portfolio diversification to expand their market reach into new vehicle segments.
Within the established automotive supplier archetype, Denso and Continental AG exemplify firms specializing in advanced thermal management and integrated powertrain components respectively. Denso sustains its strong position through sophisticated battery management systems for the automotive sector, while Continental AG focuses on control units for light-duty vehicles. Siemens Energy represents a distinct segment, leveraging its industrial power systems expertise for high-power applications like marine and grid systems. These companies collectively anchor innovation across diverse hybrid system configurations, reflecting a blend of specialized component development and broader system integration capabilities crucial for market expansion.
| Leading Market Players |
|---|
| Siemens Energy |
| General Electric |
| Bosch |
| Continental AG |
| Denso |
| Johnson Controls |
| Wärtsilä |
| ZF Friedrichshafen AG |
| Delta Electronics |
Cost & Logistics Intelligence
China's GB standards for battery safety and performance directly gate supply qualification for hybrid components, simultaneously influencing price differentiation for compliant systems across diverse applications.
Pricing Analysis
Current-generation hybrid system components exhibit price stability, while next-generation wide-bandgap semiconductors command a premium due to superior efficiency. The dominant pricing model remains per-unit transactional, though specialized configurations for marine vessels often follow a project-based approach. Price differentiation stems from the level of customization required and stringent certification levels like ISO specifications for battery management systems. Pricing pressure stems from fleet operators' focus on total cost of ownership, compelling suppliers to optimize component expenses. Commercial fleet operators exhibit high price sensitivity, prioritizing long-term operational savings, whereas specialized marine and off-highway applications tolerate higher initial outlays for performance gains.
Supply Chain Analysis
The geographic concentration of critical raw material processing, particularly for lithium and cobalt, introduces a significant chokepoint for the hybrid battery supply chain. Geographic supply concentrates heavily in China for battery cells and power electronics, with Germany and Japan contributing advanced integrated system components. Raw material dependencies include lithium, cobalt, and rare earth elements for electric motors, alongside wide-bandgap semiconductors like Silicon Carbide. Commodity price volatility for these critical materials represents a structural supply chain risk for manufacturers. Distribution runs primarily direct to Original Equipment Manufacturers and specialized system integrators for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid system market presents a defensive-moat story, primarily justified by the regulatory entrenchment driven by global emissions mandates.
For Market Incumbents:Shield core market share by investing heavily in advanced Wide-Bandgap (SiC) power electronics for higher efficiency and power density. Form strategic partnerships with battery raw material suppliers to mitigate geopolitical supply risks and commodity price volatility. This proactive approach counters the threat of emerging EV-only players and strengthens the position against margin pressure. Continuous R&D in thermal management systems and battery management systems provides a critical lever for differentiation and market leadership.
For New Entrants and Emerging Players:A service-layer gap exists in providing modular, scalable hybrid retrofit kits for existing commercial vehicle fleets in underpenetrated markets. Target specialized applications like off-highway vehicle electrification and smaller marine vessels, where specific operational needs outweigh initial cost sensitivity. The most penetrable segment for new players remains the aftermarket for commercial vehicles in emerging economies, offering opportunities for rapid deployment and localized support. A go-to-market angle focusing on rapid integration and proven fuel economy gains can capture early market share.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with private equity-backed component manufacturers specializing in power electronics and battery management systems. The market exhibits long-term viability as hybrid systems bridge the transition to full electrification, particularly in heavy-duty and specialized transport. Target acquisition archetypes include niche technology providers with strong intellectual property in SiC inverter technology or those with established integration capabilities for marine diesel-electric systems. Increased M&A activity for specialized component firms, particularly in advanced power electronics, serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity expansion in wide-bandgap power electronics | Manufacturers reduce reliance on external suppliers and improve cost control for critical components. |
| Battery supply chain diversification | Companies mitigate geopolitical risks and stabilize raw material procurement for energy storage systems. |
| Software-defined hybrid control unit development | OEMs enhance system adaptability and performance across diverse vehicle platforms and operational modes. |
| Partnership for marine diesel-electric systems | Integrators unlock higher-margin opportunities in specialized vessel propulsion for ferries and tugboats. |
| Geographic expansion into emerging commercial fleets | Companies tap into new demand centers driven by modernization and environmental regulations in South America. |
Research Approach
Desk research of regulatory body reports, automotive industry association data, and public company financial filings preceded structured interviews with OEM engineering leads, fleet procurement managers, and component supplier R&D heads. This comprehensive primary and secondary data collection informed both bottom-up market sizing and top-down validation, ensuring robust data triangulation.
Variance decomposition isolated the impact of regulatory mandates, technological advancements, and economic factors on market growth across the analysis window. The analytical framework modeled market dynamics by system type, technology, application, end user, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends, identified market drivers, and expert projections. Key industry-specific forecast inputs included battery cost curves and commercial vehicle fleet turnover rates.
Forecasts assume regulatory continuity in EU, US, and China regimes; material policy shifts would require re-modeling. The analysis reflects assumptions on technology maturation and raw material stability. Practitioners should keep alternative scenarios live as battery chemistry developments and geopolitical events evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Battery Packaging Market
Others
United States Printed Signage Market
Others
Refractometer Market
Others
Basketball Apparel Market
Others
Versatile Video Coding Market
Others
Smart Home Solutions Market
Others
Europe Meditation Market
Others
Smart Doorbell Market
Others
Mobile Computer Cart Market
Others
Managed Testing Services Market
Others
Global Simulation in Healthcare Market
Others
Belt Press Filter Market
Others
Latin America 3D Printing Construction Market
Others
TWS Micro-Battery Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Signal Transformer Market