
 Signal Transformer Market | 2026-2036
Signal Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Signal Transformer Market Outlook
Southeast Asia is reconfiguring signal transformer supply chains as Vietnam and Thailand expand electronics manufacturing zones. Murata Manufacturing Co., Ltd. leverages ceramic core expertise to dominate high-frequency pulse transformer segments. TDK Corporation anchors magnetics R&D in Japan while extending production partnerships across ASEAN. Vishay Intertechnology, Inc. competes through thick-film winding technology that sustains precision in harsh industrial environments.
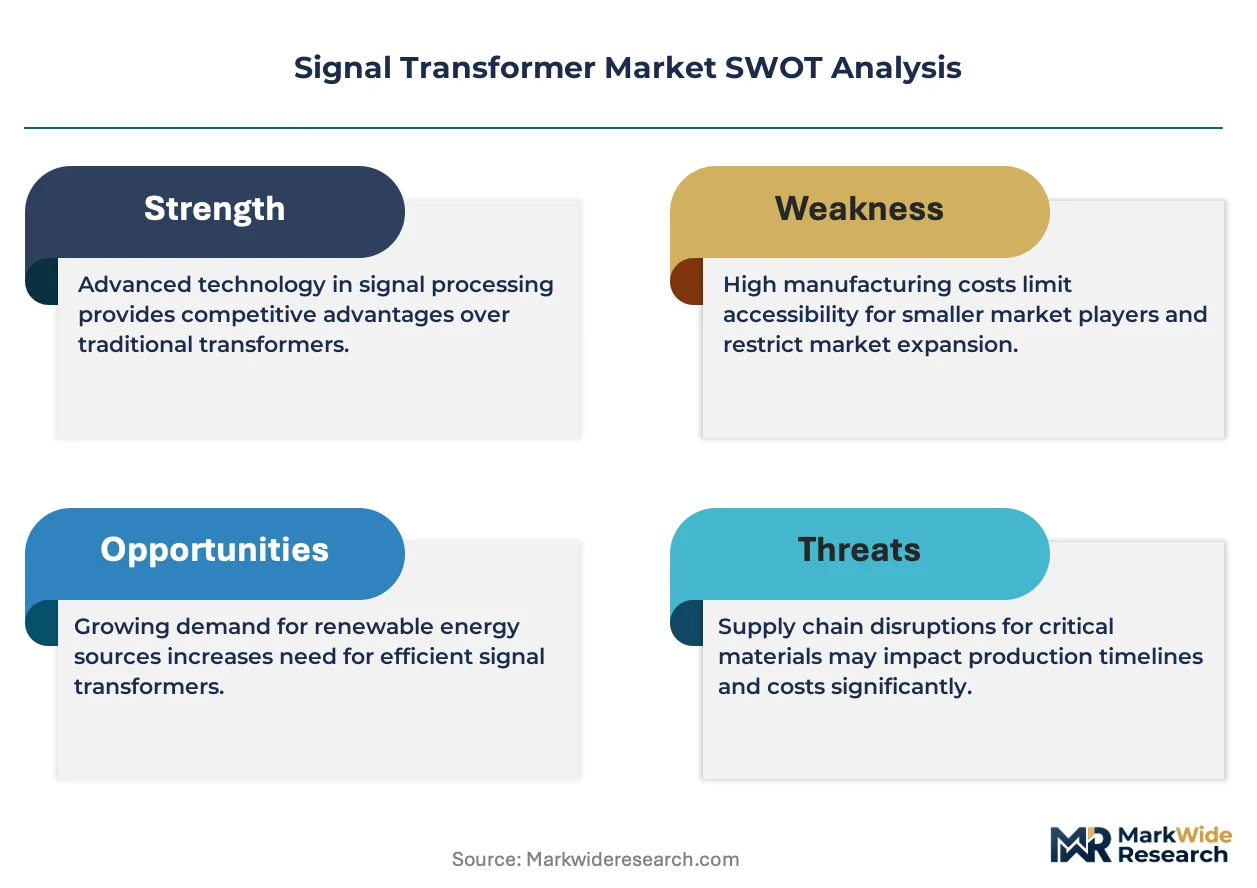
Signal transformers are electromagnetic devices that transfer electrical signals between circuits while maintaining galvanic isolation, typically operating across frequency ranges from audio to RF with core materials including ferrite, iron powder, and nanocrystalline alloys. Their primary purpose centers on impedance matching, noise suppression, and voltage level translation in communication and control systems. Isolation transformers command premium positioning in medical and industrial segments where IEC 60601-1 and UL 508 safety certifications create margin pools. Pulse transformers represent the fastest-growing product category as gate driver applications in power electronics multiply. Hybrid technology bridges analog signal integrity with digital control interfaces, attracting design wins in aerospace and automotive end-use sectors.
FCC Part 15 emissions rules in the United States constrain transformer parasitic capacitance and common-mode noise, while REACH substance restrictions in Europe force ferrite core suppliers to reformulate binders and coatings. China's GB standards for electromagnetic compatibility tighten market access for imported components. Stakeholders must monitor evolving efficiency mandates from DOE and EPA that extend beyond power transformers into signal-grade magnetics.
Market Dynamics
Telecommunications infrastructure buildouts are compressing design cycles for signal transformers as 5G base station deployments and fiber-optic network expansions force manufacturers to reconcile high-frequency performance with IEC 62368-1 safety mandates.
Growth Catalysts
- 5G Base Station Rollouts:Massive MIMO antenna arrays require high-isolation pulse transformers for RF signal conditioning, pulling demand from tower equipment OEMs.
- RoHS Material Mandates:Europe's substance restrictions are forcing ferrite core reformulations that eliminate cadmium and hexavalent chromium binders, creating upgrade cycles across installed industrial equipment.
- China Electronics Manufacturing Scale:Domestic supply chain maturation around Shenzhen and Suzhou is reducing import dependency for precision-wound magnetics in consumer electronics.
Market Restraints
- Raw Material Concentration:Rare-earth oxide processing for high-permeability ferrites concentrates in Chinese smelting corridors, exposing non-domestic transformer manufacturers to export quota volatility.
- Technical Frequency Ceilings:Conventional laminated core architectures face hard limits above 500 MHz, constraining deployment in millimeter-wave 5G backhaul links without costly ceramic substitutions.
- REACH Compliance Friction:ECHA's expanding candidate list of Substances of Very High Concern forces iterative coating reformulations that extend qualification timelines for European medical device approvals.
Strategic Opportunities
- Vietnam Electronics Zones:Northern industrial parks near Hanoi are attracting winding equipment investments as manufacturers diversify beyond China-centric production.
- Gate Driver Integration:Silicon carbide power module adoption in electric vehicle inverters is creating adjacent demand for isolated pulse transformers with nanosecond propagation delay specifications.
- CE Marking Harmonization:Consolidated EU medical device regulations under MDR are enabling single-certification pathways that reduce redundant testing costs for isolation transformer suppliers.
Industry Challenges
- Precision Winding Talent Scarcity:Automated toroidal winding programming requires mechatronics expertise that outpaces vocational training output in ASEAN manufacturing hubs.
- IEC 60601-1 Certification Timelines:Medical-grade isolation transformers face 14-18 month approval cycles that mismatch quarterly product roadmap pressures from imaging equipment OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signal Transformer Market |
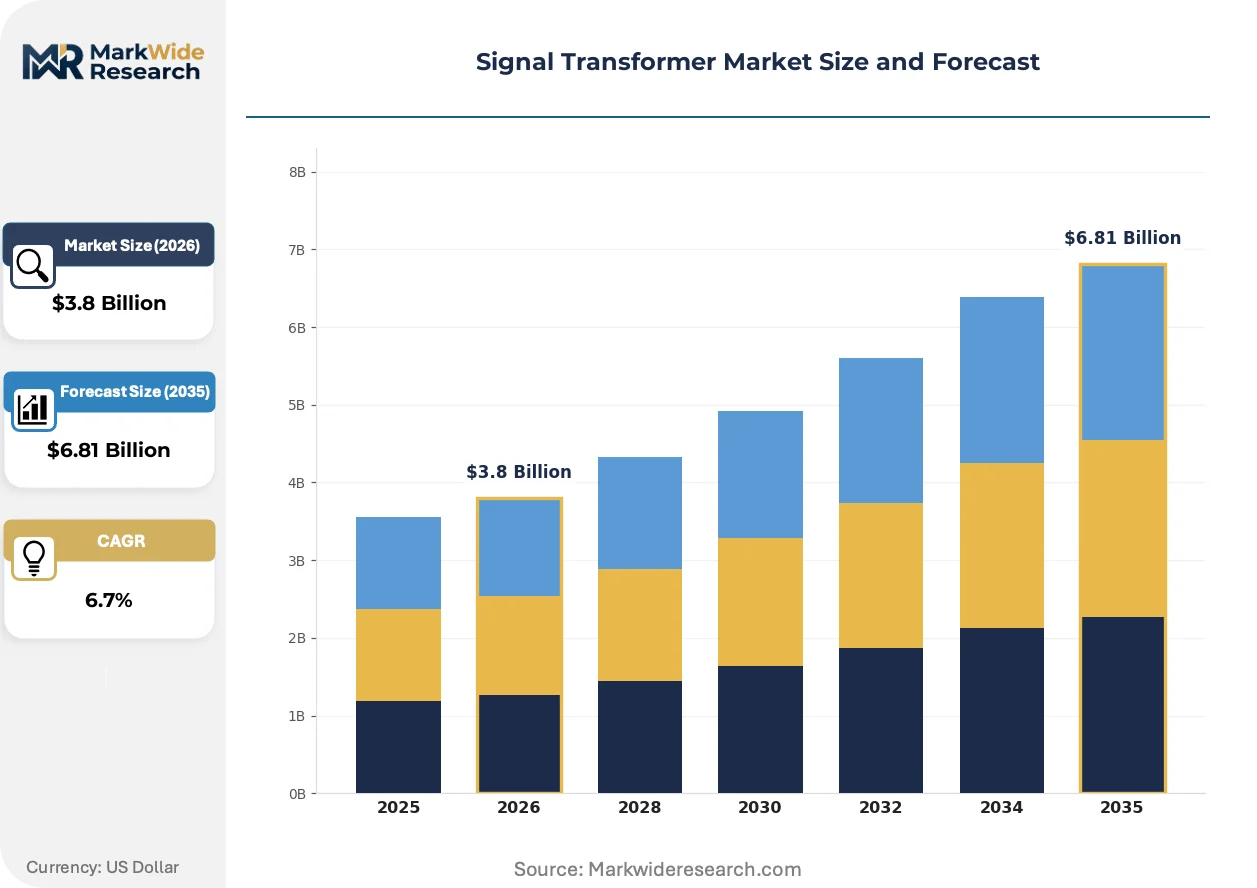
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Transformers, Isolation Transformers, Pulse Transformers, Voltage Transformers Application: Broadcasting, Telecommunications, Power Supplies, Industrial Control End User: Healthcare, Manufacturing, Aerospace, Automotive Technology: Electromechanical, Digital, Analog, Hybrid |
| Companies Covered | Bel Fuse Inc., Murata Manufacturing Co., Ltd., TDK Corporation, Vishay Intertechnology, Inc., Pulse Electronics Corporation, Bourns, Inc., Coilcraft, Inc., Pepperl+Fuchs Group, CUI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signal Transformer Market Strategic Shifts
Transformer architectures are bifurcating between legacy analog signal preservation and digital interface compatibility, forcing manufacturers to engineer hybrid cores that satisfy both domains without performance trade-offs.
Nanocrystalline alloy cores is hybridizing conventional ferrite and amorphous metal properties to achieve sub-milliwatt core losses at switching frequencies above 100 kHz. Aerospace avionics suppliers are qualifying these materials for fly-by-wire control systems where signal integrity must survive 125°C ambient conditions. The convergence is compressing the viable performance gap between commodity ferrite and premium cobalt-based alternatives.
REACH substance restrictions are compelling ferrite manufacturers to eliminate bisphenol-A based epoxy coatings in favor of bio-derived binders that maintain moisture resistance. Industrial automation OEMs in Germany face reformulation costs that add 8-12% to magnetic core bill-of-materials. The regulatory pressure is accelerating qualification of alternative coating chemistries from Japanese specialty chemical suppliers.
Buyers are consolidating transformer procurement under subsystem integrators rather than sourcing discrete magnetics directly. Communication infrastructure OEMs are shifting volume commitments to RF module suppliers who specify transformer parameters internally. The pattern is most pronounced in South Korean 5G equipment supply chains where Samsung and LG Uplus are driving tier-one consolidation.
Signal Transformer Market Segmentation
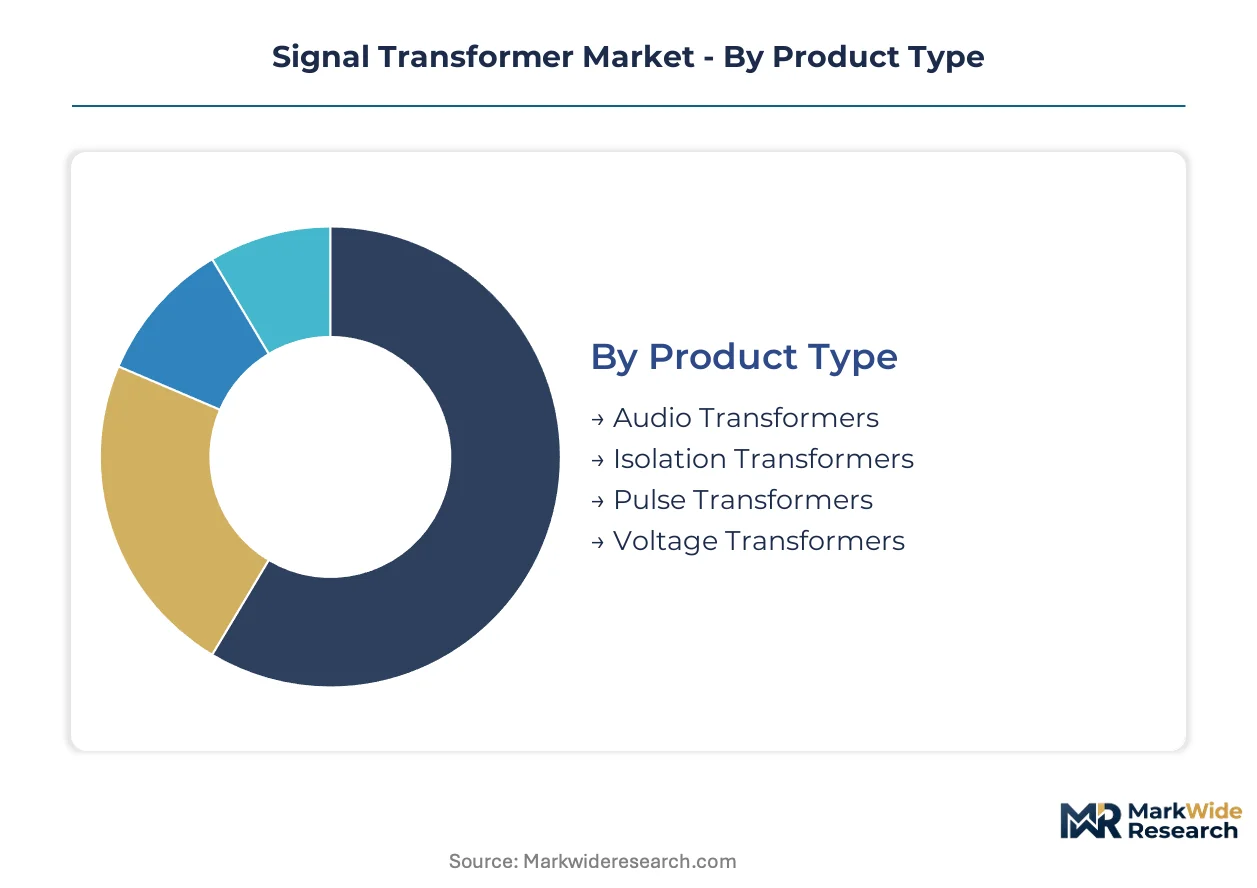
Signal transformer segmentation reveals how electromagnetic isolation requirements diverge across frequency domains, safety certifications, and interface protocols. Each dimension carries distinct margin structures and qualification barriers that reshape competitive positioning.
Product Type:
Mature laminated-core architectures dominate legacy installations while nanocrystalline and ceramic-core variants capture emerging high-frequency applications.
- Audio Transformers:Electromagnetic devices engineered for impedance matching across 20 Hz to 20 kHz ranges, utilizing mu-metal cores to minimize harmonic distortion in professional mixing consoles and broadcast studios. Demand concentrates in Nashville and Los Angeles recording facility upgrades where vintage equipment restoration drives replacement cycles.
- Isolation Transformers:Galvanic separation devices with reinforced insulation systems rated for medical-grade IEC 60601-1 and industrial UL 508 certifications, commanding premium positioning in MRI imaging suites and semiconductor fabrication cleanrooms. Healthcare capital expenditure recovery in Germany and Japan sustains order backlogs for 5 kVA and above ratings.
- Pulse Transformers:High-isolation magnetics optimized for nanosecond rise-time signal integrity in gate driver and data communication circuits. Silicon carbide power module adoption in electric vehicle traction inverters accelerates qualification timelines for 1:1 and 1:1.5 turn-ratio configurations.
- Voltage Transformers:Instrument-grade devices scaling signal levels for measurement and protection relay inputs across medium-voltage switchgear. Grid modernization programs in India and Brazil sustain procurement from utility-tier suppliers.
Isolation transformers retain volume leadership; pulse transformers hold the steepest expansion curve.
Application:
Application segmentation tracks how signal integrity requirements harden across transmission distance, electromagnetic interference exposure, and safety-critical failure modes.
- Telecommunications:5G massive MIMO deployments require high-isolation pulse transformers for RF signal conditioning in tower-mounted active antenna units. FCC Part 15 emissions compliance constrains parasitic capacitance specifications for base station OEMs in the United States.
- Power Supplies:Isolated feedback networks and gate drive circuits in switch-mode converters demand tight coupling coefficients and partial discharge resistance. Server farm expansion in Singapore and Ireland pulls demand for 1 MHz-rated ferrite designs.
- Broadcasting:Audio frequency magnetics for studio and transmission chain signal routing, with particular emphasis on phase linearity in FM and digital radio multiplex equipment.
- Industrial Control:Noise suppression and voltage level translation in programmable logic controller I/O modules and motor drive encoder interfaces. Factory automation upgrades in Vietnam and Thailand sustain mid-volume procurement.
Telecommunications commands the largest revenue pool; power supplies are expanding most quickly.
End User:
End user segmentation isolates how safety certification tiers and operating environment severity stratify transformer specifications and pricing.
- Healthcare:Patient-contact isolation transformers for diagnostic imaging and life support equipment, requiring IEC 60601-1 2MOPP insulation and leakage current below 10 microamperes. EMA and FDA dual-track approvals extend qualification timelines for European and North American hospital system vendors.
- Manufacturing:Industrial-grade isolation for motor drives, robotics, and process control systems operating in 40°C ambient with humidity cycling. Automotive electronics contract manufacturers in Mexico and Eastern Europe consolidate procurement under subsystem integrators.
- Aerospace:Avionics magnetics qualified to DO-160G environmental standards and AS9100 quality systems, with emphasis on 125°C continuous operation and shock resistance. Boeing and Airbus tier-one suppliers in Wichita and Toulouse specify custom toroidal designs.
- Automotive:Onboard charger and DC-DC converter isolation for electric vehicle power electronics, with AEC-Q200 stress testing and PPAP submission requirements. Battery electric vehicle platform launches in South Korea and China accelerate gate driver transformer sampling.
Manufacturing retains volume leadership; automotive holds the steepest expansion curve.
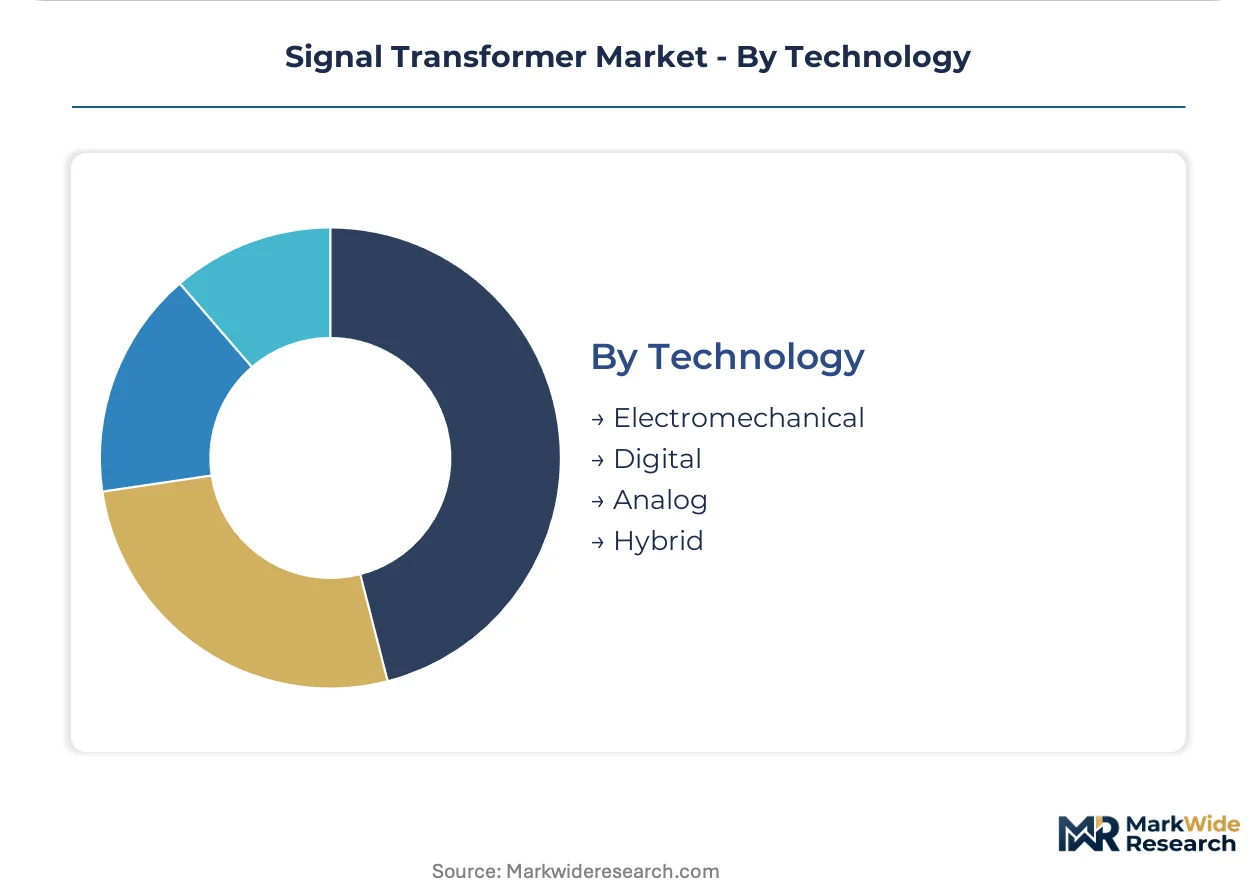
Technology:
Technology segmentation captures the interface between analog signal preservation and digital control integration.
- Hybrid:Architectures combining traditional electromagnetic isolation with digital encoding for simultaneous analog integrity and protocol compatibility. Aerospace fly-by-wire systems in France and the United Kingdom qualify these designs for control surface position feedback.
- Electromechanical:Conventional wound-core transformers utilizing ferrite, iron powder, or nanocrystalline materials without active electronic conditioning. Mature cost structures dominate industrial replacement markets.
- Analog:Precision-wound magnetics optimized for phase coherence and low insertion loss in measurement and audio applications. Professional audio OEMs in Japan specify custom interleaved winding patterns.
- Digital:Transformer-coupled isolation with integrated signal conditioning and protocol translation, typically employing capacitive or magnetic coupling with onboard ADC/DAC stages.
Electromechanical designs retain volume leadership; hybrid architectures hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex underwrites China's dominance in signal transformer procurement, handling ferrite core imports and finished magnetics exports that connect Pearl River Delta factories to global electronics supply chains.
United States
5G massive MIMO tower deployments and data center construction in Ashburn, Virginia drive pulse transformer consumption. FCC Part 15 emissions rules constrain parasitic capacitance specifications for base station OEMs. Dallas-Fort Worth hosts RF module integrators consolidating transformer procurement under subsystem vendors.
China
Domestic electric vehicle inverter production and consumer electronics manufacturing scale demand for gate driver isolation. GB standards for electromagnetic compatibility tighten market access for imported components. Suzhou precision-winding clusters reduce import dependency for high-frequency magnetics.
Germany
Industrial automation upgrades and medical imaging equipment replacement sustain isolation transformer orders. REACH substance restrictions force ferrite core coating reformulations that extend qualification timelines. Munich and Stuttgart host healthcare capital expenditure decision-makers specifying IEC 60601-1 certified units.
Japan
Aerospace fly-by-wire system qualification and automotive power electronics R&D pull nanocrystalline core sampling. METI efficiency mandates extend beyond power transformers into signal-grade magnetics. Nagoya magnetics research anchors TDK's ceramic core development for RF applications.
Vietnam
Northern industrial parks near Hanoi attract winding equipment investments as manufacturers diversify production footprints. The country's national electronics regulator aligns technical standards with ASEAN harmonization frameworks. Bac Ninh and Hai Phong electronics zones concentrate mid-volume transformer assembly for export.
Signal Transformer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying magnetics to RF module and power converter vendors. The vendor base stratifies across three tiers: multinational magnetics conglomerates with ceramic and ferrite core captive supply, mid-scale winding houses serving industrial automation, and niche audio transformer artisans. Two strategic archetypes dominate: technology licensors monetizing core material patents, and capacity expanders securing winding equipment in Vietnam and Thailand. Consolidation pressures intensify as communication infrastructure OEMs reduce qualified supplier lists.
Among Japanese-based manufacturers, TDK Corporation and Murata Manufacturing Co., Ltd. exemplify the materials-integrated archetype, leveraging in-house ferrite and ceramic core production to control cost positions in high-frequency segments. Vishay Intertechnology, Inc. occupies a position among North American component specialists, representing the thick-film precision winding approach that serves harsh-environment industrial applications. These three anchors illustrate how geographic clustering around core material expertise and end-market proximity shapes competitive differentiation.
| Leading Market Players |
|---|
| Bel Fuse Inc. |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Vishay Intertechnology, Inc. |
| Pulse Electronics Corporation |
| Bourns, Inc. |
| Coilcraft, Inc. |
| Pepperl+Fuchs Group |
| CUI Inc. |
| Others |
Value Chain & Pricing Dynamics
Rare-earth oxide export quota volatility from Chinese smelting corridors determines both the spread between premium nanocrystalline and standard ferrite pricing tiers and the geographic shape of transformer manufacturing footprints. Buyers face compressed margins when oxide restrictions tighten, forcing qualification of alternative core suppliers in Japan and Germany.
Pricing Analysis
Volume-discount tiering structures separate medical-grade IEC 60601-1 certified isolation transformers from industrial UL 508 units and economy-grade consumer electronics magnetics. Price differentiation hinges on certification grade and core material performance, with nanocrystalline alloys commanding substantial premiums over commodity ferrite. Cost compression in the standard tier is intensifying because Chinese domestic winding capacity is absorbing mid-volume orders that previously flowed to ASEAN suppliers. Industrial automation OEMs exhibit highest price sensitivity, while healthcare equipment vendors prioritize safety certification over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses are extending payment terms to Vietnamese winding houses, enabling equipment upgrades without immediate capital outlay. Raw material dependencies center on rare-earth oxides from Chinese processing corridors, ferrite powders from TDK's Nagoya facilities, and copper magnet wire from South Korean smelters. Single-source vulnerability concentrates in high-permeability ferrite formulations where Chinese export licenses control global availability. Distribution runs through RF module integrators and power converter OEMs who specify transformer parameters internally rather than sourcing discrete magnetics directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by telecommunications infrastructure capital expenditure normalization following pandemic-era supply chain disruptions. 5G base station deployment schedules and electric vehicle platform launches are restoring order visibility.
For Market Incumbents: Pre-empt margin erosion from Chinese domestic supply chain maturation by securing captive nanocrystalline alloy production or exclusive offtake agreements with Japanese specialty metal suppliers. Accelerate IEC 62368-1 safety certification pipelines to maintain premium positioning against emerging ASEAN winding houses. Channel control through RF module integrators remains the priority lever for volume retention.
For New Entrants and Emerging Players: Northern Vietnam's underpenetrated precision-winding labor pool offers white-space entry below the cost structure of established Shenzhen and Suzhou clusters. Gate driver transformer sampling for silicon carbide power modules represents the most penetrable product segment, with automotive inverter OEMs actively qualifying second-source suppliers. A technical sales approach emphasizing nanosecond propagation delay specifications will differentiate against commodity ferrite competitors.
For Investors and Strategic Acquirers: The market sits at an early-recovery phase that favors materials-integrated specialists with captive core production over pure-play winding houses. Long-term viability over the next decade hinges on exposure to electric vehicle and 5G infrastructure end-markets rather than legacy industrial replacement cycles. The signal to watch is Chinese rare-earth export license issuance patterns, which foreshadow input cost movements and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanocrystalline Alloy Production | Captive supply of high-performance cores insulates margin from Chinese rare-earth quota volatility. |
| IEC 62368-1 Safety Certification Acceleration | Reduced qualification timelines capture 5G base station and medical imaging equipment design wins. |
| Vietnam Manufacturing Footprint Expansion | Bac Ninh and Hai Phong zones offer labor cost arbitrage against Pearl River Delta competitors. |
| Gate Driver Transformer Co-development Partnership | Silicon carbide inverter OEMs require isolated pulse transformers with sub-50 nanosecond propagation delay. |
| REACH-Compliant Coating Chemistry Qualification | Bio-derived epoxy binders from Japanese suppliers satisfy ECHA substance restrictions for European medical device access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF module design engineers, power electronics procurement managers, magnetics manufacturing executives, and healthcare equipment regulatory affairs specialists. Secondary validation drew from IEC certification databases, ECHA REACH candidate list updates, customs trade records for ferrite core imports, and SEC filings from listed component manufacturers. Bottom-up demand modeling across telecommunications, automotive, and healthcare end-markets was triangulated against top-down supply capacity assessments from major production clusters.
Calibration approaches anchored volume and value outputs to disclosed capital expenditure patterns from 5G infrastructure OEMs and electric vehicle platform launches. Segmentation dimensions modeled include product architecture, frequency rating, safety certification tier, core material composition, and regional manufacturing origin. CAGRs were derived from regression analysis of historical procurement data against equipment deployment schedules, with specific weighting applied to silicon carbide adoption curves and medical device replacement cycles.
Practitioners should monitor Chinese rare-earth export license issuance, ECHA SVHC list expansion, and FCC Part 15 rulemaking proceedings for early signals of forecast deviation. Macro-economic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
France Automotive LED Lighting Market
Others
Africa Smart Card Market
Others
5G Smartphone Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Magnetic Stripe Readers Market
Others
Sandbags Market
Others
High Frequency Vibrator Market
Others
Global Emergency Spill Response Market
Others
Global Hydraulics Market
Others
Digital Supply Chain Market
Others
US Legal Services Market
Others
Workbench Tanks Market
Others
Foldable Smartphone Market
Others
Global Electroshock Weapons Market
Others
Fluorapatite Market
Others
France Smart Home Market