
 Smart Home Solutions Market | 2026-2036
Smart Home Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Solutions Market Outlook
The EU Green Deal is decoupling home energy performance from fossil fuel dependence across European residential stock. Samsung Electronics Co., Ltd. leverages its appliance-to-mobile ecosystem to anchor whole-home automation platforms. Schneider Electric specializes in building-to-grid integration, competing for commercial retrofit contracts that demand interoperable energy management systems.
Smart home solutions encompass networked devices, sensors, controllers, and software platforms that automate residential and commercial environments through wireless protocols such as Zigbee, Z-Wave, Wi-Fi, and Bluetooth, primarily serving energy optimization, security surveillance, and occupant comfort objectives. Smart thermostats and smart lighting currently occupy the largest installed base, while health monitoring applications within the application dimension represent the fastest-expanding margin pool as aging-in-place demographics intersect with remote care models. Wi-Fi dominates connectivity volumes for consumer-grade installations, though Zigbee and Z-Wave sustain premium positioning in professionally monitored security and multi-protocol hub architectures.
The EU AI Act and GDPR constrain biometric data processing in smart security cameras, while the F-Gas Regulation pushes refrigerant-linked smart HVAC controls toward lower-global-warming-potential designs. The US FCC governs spectrum allocation for Zigbee and Z-Wave transmissions, shaping device certification timelines and cross-border compatibility. Stakeholders must monitor whether emerging interoperability mandates from the EU and US force protocol consolidation or preserve multi-standard fragmentation.
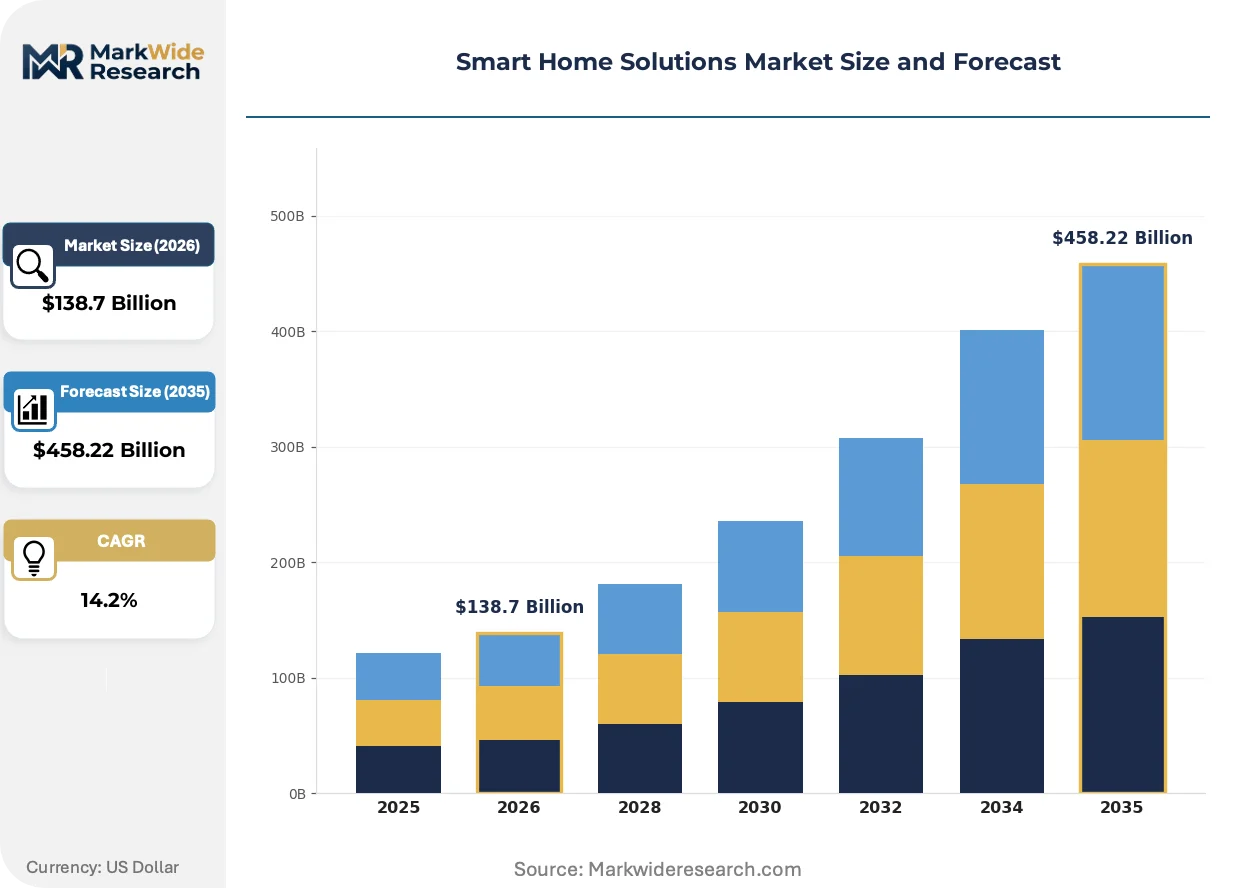
Market Dynamics
The EU Green Deal's building efficiency mandates are compressing payback periods for connected energy management systems, forcing hardware vendors to bundle software subscriptions and utility partnerships into retrofit propositions. This regulatory pressure is restructuring competitive positioning around whole-home automation platforms rather than point solutions.
Growth Catalysts
- F-Gas Regulation:The EU's refrigerant phase-down accelerates replacement cycles for HVAC controls, pulling smart thermostats into mandatory building upgrades across German and French residential stock.
- Zigbee Alliance certification:Unified protocol standards reduce integration friction for multi-vendor installations, expanding addressable market for professional installers in retrofit-heavy markets.
- Utility demand-response programs:European power distributors subsidize connected thermostats and water heaters, converting passive ratepayers into grid-flexibility assets.
Market Restraints
- Silicon supply concentration:Taiwan-based foundry capacity constraints delay Zigbee and Z-Wave chipset deliveries, extending smart device lead times for European OEMs.
- GDPR biometric friction:The EU AI Act's facial recognition restrictions limit feature sets for smart security cameras, compressing margins on premium hardware tiers.
- Copper and rare earth volatility:Magnet and wiring cost swings destabilize smart motor and sensor pricing, complicating multi-year utility contract bidding.
Strategic Opportunities
- Polish and Romanian housing retrofits:EU cohesion funds channel building modernization subsidies into Eastern European markets with sub-15% smart device penetration.
- Matter protocol convergence:Thread and Wi-Fi unification under Matter certification collapses compatibility barriers, enabling cross-platform health monitoring integrations.
- Italy's Superbonus 110%:Tax deductions covering connected energy systems drive contractor certification programs and bulk procurement by property management consortia.
Industry Challenges
- Cybersecurity certification backlog:EN 303645 compliance testing queues extend product launch timelines for startups lacking in-house penetration testing labs.
- Legacy HVAC integration complexity:Hydronic heating systems in Northern European housing stock require proprietary adapter hardware, fragmenting installation training requirements.
- Interoperability patent thickets:Wireless protocol licensing disputes between semiconductor vendors inflate BOM costs for multi-protocol hub manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Solutions Market |
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $458.22 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Smart Speakers, Smart Lighting, Smart Security Cameras Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Rental Properties, Commercial Buildings, Hospitality Application: Home Automation, Energy Management, Security Surveillance, Health Monitoring |
| Companies Covered | Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics Co., Ltd., Schneider Electric, Johnson Controls Inc., Honeywell International Inc., Robert Bosch GmbH, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Solutions Market Strategic Shifts
Matter-certified devices are collapsing the fragmentation that historically locked consumers into single-vendor ecosystems. This protocol convergence is redrawing competitive boundaries around software platform stickiness rather than hardware compatibility moats.
Thread mesh networking is expanding into battery-powered sensor deployments, enabling whole-home coverage without range extenders. German utility-led retrofit programs are adopting Thread for water leak and air quality monitoring in apartment blocks. The technology is expanding into professional installation channels previously dominated by Z-Wave, compressing certification overhead for multi-family housing contractors.
The EU AI Act's risk classification framework imposes conformity assessment requirements on biometric-enabled security cameras. Manufacturers must maintain technical documentation and human oversight protocols for systems deployed in residential common areas. French CNIL guidance on automated decision-making is forcing smart doorbell vendors to localize processing or obtain explicit consent, affecting product architecture for EU-bound SKUs.
Italian and Spanish buyers are consolidating procurement through property management platforms rather than retail channels. These consortia negotiate volume discounts for Superbonus-eligible installations, displacing individual consumer purchases. The shift concentrates bargaining power with certified installation networks, compressing margins for direct-to-consumer hardware brands in Southern European markets.
Smart Home Solutions Market Segmentation
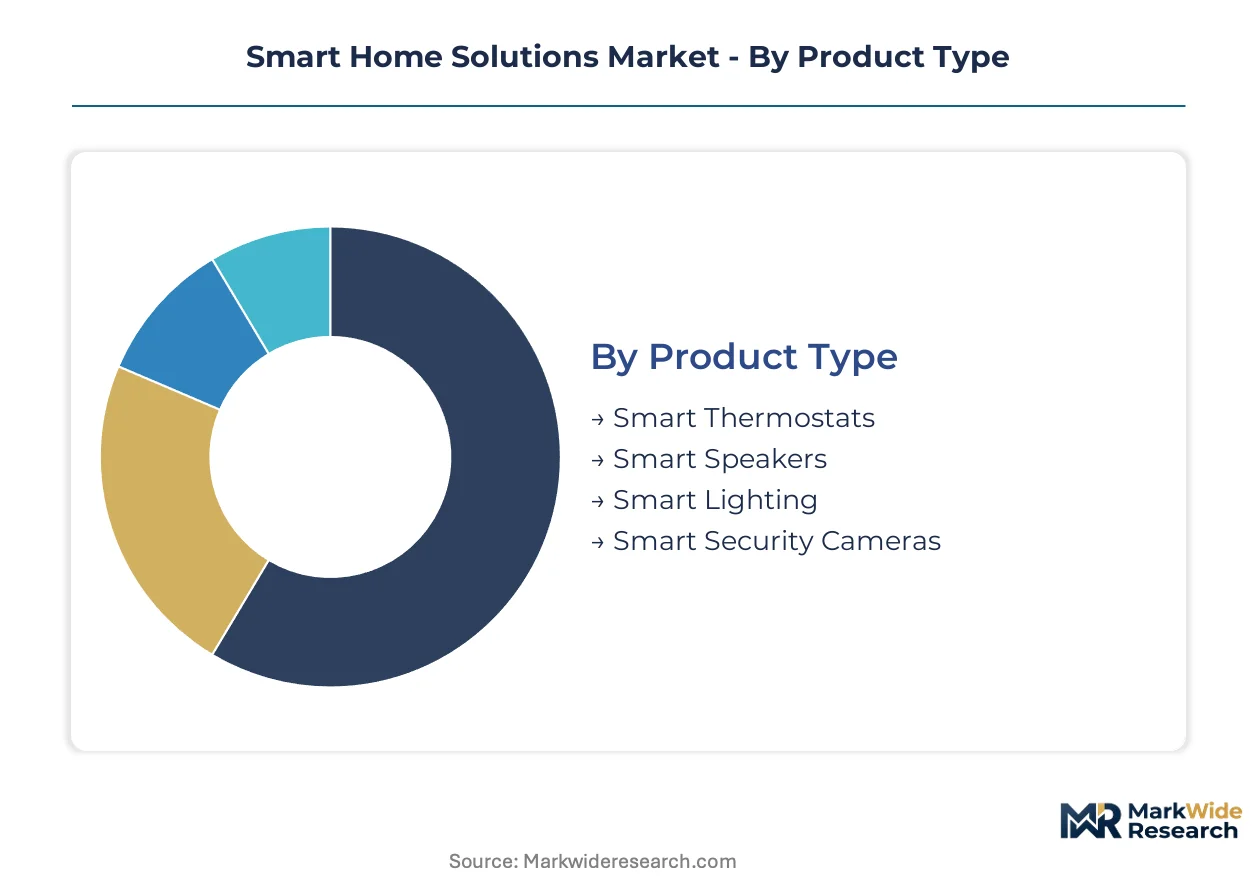
Smart home solutions fragment across protocol standards, installation contexts, and buyer sophistication levels. Device vendors must align hardware specifications with end-user technical capabilities and regulatory compliance requirements.
Product Type:
Standardization dominates thermostat and lighting categories, while security and audio systems retain customization through software feature tiers.
- Smart Thermostats:These devices integrate HVAC control with utility demand-response protocols, enabling automated temperature modulation based on occupancy patterns and grid pricing signals. German utility partnerships and France's F-Gas Regulation compliance requirements concentrate demand in retrofit-heavy single-family housing across these markets.
- Smart Lighting:LED-integrated controllers with dimming, color temperature adjustment, and circadian rhythm programming ship in both retrofit bulb formats and new-construction fixture designs. Italian Superbonus 110% tax deductions and Spanish property management consortia are channeling volume through certified installer networks rather than retail.
- Smart Speakers:Voice-activated hubs with natural language processing for device orchestration and media streaming.
- Smart Security Cameras:Video surveillance endpoints with motion detection and cloud storage, constrained by GDPR biometric processing limits and EU AI Act risk classifications for facial recognition features.
Most installed capacity flows through Smart Lighting. Expansion is steepest in Smart Security Cameras despite regulatory headwinds.
Technology:
Cost tiers separate consumer-grade Wi-Fi deployments from premium professional installations requiring mesh reliability.
- Wi-Fi:Ubiquitous protocol leveraging existing residential internet infrastructure for plug-and-play consumer installations without dedicated hubs. Volume concentrates in North American and Western European retail channels where smartphone-centric setup dominates.
- Zigbee:Low-power mesh networking standard certified through the Zigbee Alliance, enabling multi-vendor interoperability for whole-home automation platforms. German and Austrian utility-led retrofit programs specify Zigbee for water heater and thermostat integration.
- Z-Wave:Sub-GHz mesh protocol with superior wall penetration, historically dominant in professionally monitored security installations.
- Bluetooth:Point-to-point connectivity for initial device provisioning and battery-powered sensor deployments with limited range requirements.
Wi-Fi carries the largest shipment volumes. Zigbee is climbing the fastest as Matter protocol convergence collapses compatibility barriers.
End User:
Customer type determines procurement channel, installation complexity tolerance, and software subscription attach rates.
- Residential:Single-family homeowners purchasing through retail or contractor channels, with highest penetration in German and Dutch markets where building efficiency mandates accelerate adoption.
- Rental Properties:Multi-unit landlords and property management platforms negotiating bulk procurement for tenant-facing amenities, concentrated in Italian and Spanish markets via Superbonus-eligible modernization programs.
- Commercial Buildings:Office and retail facility managers requiring building-to-grid integration and centralized energy management dashboards.
- Hospitality:Hotels and serviced apartments deploying guest room automation for operational efficiency and brand differentiation.
Residential accounts for the dominant share of unit installations. Rental Properties are expanding most quickly as EU cohesion funds channel subsidies into Eastern European housing stock modernization.
Application:
Margin profiles diverge between mature automation categories and emerging health-centric use cases.
- Home Automation:Integrated control of lighting, climate, and entertainment systems through centralized hubs or voice interfaces, representing the foundational use case with established consumer awareness.
- Energy Management:Grid-responsive load modulation and consumption analytics, with demand accelerating under EU Green Deal building efficiency mandates and utility demand-response program expansion.
- Security Surveillance:Intrusion detection, video verification, and remote monitoring services, facing margin compression from GDPR biometric restrictions and EU AI Act compliance costs.
- Health Monitoring:Aging-in-place sensors for fall detection, medication adherence, and emergency response, gaining share fastest as remote care models intersect with demographic shifts in Japan and Western Europe.
Energy Management captures the largest addressable spend. Health Monitoring represents the fastest-growing trajectory as reimbursement frameworks for remote patient monitoring mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart home solutions trace their commercial origins to early automation experiments in the United States during the 1970s, where X10 powerline communication protocols first enabled remote appliance control. European markets later refined these foundations through building efficiency mandates that transformed fragmented gadgetry into integrated energy management platforms.
Germany
Utility-led retrofit partnerships and F-Gas Regulation compliance requirements drive smart thermostat deployment across single-family housing. The KBA coordinates with federal building codes to mandate connected HVAC controls in efficiency renovations. Industrial concentration clusters in Munich and Stuttgart, where appliance manufacturers anchor whole-home automation development.
United States
FCC spectrum governance shapes Zigbee and Z-Wave certification timelines for cross-border device compatibility. The IRA's residential clean energy credits accelerate smart water heater and thermostat adoption through contractor channels. Silicon Valley and Seattle host platform developers competing on voice-interface integration and cloud service attach rates.
China
MIIT's GB standards for wireless home networking compress protocol fragmentation in domestic manufacturing. Dual carbon goals at the national level channel subsidies into connected energy management for new urban residential construction. Shenzhen and Dongguan manufacturing clusters supply Zigbee chipsets and sensor modules to global OEMs.
France
CNIL guidance on automated decision-making forces smart doorbell vendors to localize biometric processing or obtain explicit consent. ANSM collaborates on health monitoring device frameworks as aging-in-place demographics expand. The Lyon-Grenoble corridor concentrates R&D for building-to-grid integration software.
Japan
METI's energy efficiency standards for residential buildings mandate programmable controls in new construction permits. PMDA pathways for wellness device reimbursement accelerate health monitoring sensor deployment. Osaka and Nagoya industrial zones specialize in compact motor and actuator manufacturing for automated home fixtures.
Smart Home Solutions Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the smart home value chain, creating a tiered structure where semiconductor foundries and cloud infrastructure operators extract rents while device assemblers compete on thin hardware margins. The market fragments across three strategic archetypes: ecosystem platform operators bundling software subscriptions, component specialists supplying multi-protocol chipsets, and installation service networks capturing retrofit project value. Dominant competitive moves include strategic partnerships with utilities for demand-response program enrollment and portfolio diversification into adjacent health monitoring applications.
Among ecosystem platform developers, Amazon.com, Inc., Google LLC, and Apple Inc. exemplify the voice-centric hub strategy that locks consumers into recurring service revenue streams rather than one-time hardware transactions. Samsung Electronics Co., Ltd. occupies a distinctive position bridging appliance manufacturing with mobile ecosystem integration. Schneider Electric represents the building-to-grid specialist archetype, competing for commercial retrofit contracts that require interoperable energy management certification.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Schneider Electric |
| Johnson Controls Inc. |
| Honeywell International Inc. |
| Robert Bosch GmbH |
| ABB Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across Northern Europe anchor supply discipline for smart home components, converting generational manufacturing expertise into pricing power that resists commoditization pressure from Asian module assemblers. Their captive control over sensor calibration and protocol certification feeds into three-tier pricing structures that separate utility-grade installations from retail consumer tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified whole-home platforms from Zigbee point solutions and basic Wi-Fi retrofit devices. Price differentiation hinges on EN 303645 cybersecurity certification tier and bundled utility demand-response software subscriptions. Pricing pressure stems from Taiwanese foundry capacity constraints extending smart chipset lead times for European OEMs. Property management consortia in Southern Europe exhibit highest price sensitivity, while German single-family retrofits tolerate premium hardware costs for F-Gas Regulation compliance.
Supply Chain Analysis
Dual-sourcing requirements from major European utilities mandate multi-supplier qualification for Zigbee and Thread chipsets, fragmenting procurement across Taiwan, South Korea, and Chinese manufacturing clusters. Component dependencies center on silicon wafers, rare-earth magnets for smart motor actuators, and copper wiring for sensor networks. Supply chain risk concentrates in single-source vulnerability for sub-GHz RF transceiver modules. Distribution runs through certified installer networks in retrofit-heavy markets and retail electronics channels in North American consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home solutions market functions as a regulatory compounder where EU Green Deal building efficiency mandates generate recurring retrofit demand cycles independent of consumer discretionary spending. F-Gas Regulation phase-down timelines and cohesion fund disbursement schedules create predictable procurement windows for equipment vendors.
For Market Incumbents: Cement platform stickiness through exclusive utility demand-response partnerships that lock competitors out of subsidized retrofit channels. Deepen backward integration into Thread and Zigbee chipset supply through captive semiconductor design teams, insulating against Taiwan foundry allocation volatility. Acquire regional certification labs to compress EN 303645 compliance timelines as cybersecurity testing queues lengthen.
For New Entrants and Emerging Players: Polish and Romanian rental property managers remain underserved by incumbent direct-to-consumer brands, presenting white-space entry through Superbonus-eligible bulk procurement consortia. Target health monitoring sensor deployments for aging-in-place demographics where reimbursement frameworks are maturing fastest. Pursue white-label manufacturing partnerships with established Matter-certified hub vendors to bypass protocol licensing patent thickets.
For Investors and Strategic Acquirers: Valuations sit cheapest among installation service networks with certified technician workforces and utility partnership contracts. Long-term viability over the projection horizon favors building-to-grid software specialists with interoperable energy management certification. Monitor Italian Superbonus 110% tax deduction renewal negotiations as the critical inflection signal for Southern European demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Collapsing compatibility barriers under Matter unification expands addressable market for multi-vendor installations across EU retrofit programs. |
| Utility Demand-Response Partnership | Exclusive grid-flexibility enrollment contracts convert hardware vendors into recurring-revenue platform operators with captive subscriber bases. |
| EN 303645 Compliance Investment | In-house penetration testing capabilities compress product launch timelines as cybersecurity certification queues extend for outsourced testing. |
| Health Monitoring Platform Integration | FDA and PMDA reimbursement pathway navigation positions aging-in-place sensor vendors for fastest-expanding application margin pool. |
| Eastern European Installer Network Expansion | EU cohesion fund channeling into Polish and Romanian housing modernization captures sub-15% penetration markets before incumbent consolidation. |
Study Parameters
Multiple input streams — executive interviews with smart home platform developers, procurement directors at European utilities, and certified installation network operators — were reconciled against secondary validation from EIA building energy data, EU F-Gas Regulation implementation reports, and SEC filings from semiconductor vendors. Primary fieldwork captured demand-response program enrollment patterns and retrofit contractor certification bottlenecks. Bottom-up device shipment modeling and top-down energy efficiency spending allocation were triangulated to anchor volume estimates.
Data-stream reconciliation across the analysis window employed segmentation by protocol standard, installation context, and buyer sophistication level. Modeled dimensions included product type, connectivity technology, end-user category, and application use case. CAGRs were derived from fitted trend extrapolation against regulatory milestone schedules and utility program expansion timelines. Forecast inputs incorporated F-Gas Regulation HVAC replacement cycle assumptions and Matter protocol adoption curve projections from certification body disclosures.
Underlying measurement precision varies by segment; thermostat and lighting categories carry tighter precision than emerging health monitoring applications due to established utility reporting requirements. Forecasts reflect documented assumptions regarding EU cohesion fund disbursement continuity and Taiwan foundry capacity normalization. Deviation in German KBA building code enforcement intensity or Italian Superbonus fiscal renewal would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coriolis Meters Market
Others
Billet Market
Others
Convertible Shipper Display Market
Others
Pickup Truck Market
Others
United States Bean Bags Market
Others
Smart Card Market
Others
Process Instrumentation Equipment Market
Others
Global Mica Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Bimodal Identity Management Solutions Market
Others
Thermoformed Plastics Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
One-Way Degassing Valve Market
Others
Brazil Cane Sugar Market
Others
Magnesite Market
Others
Global Multi-Access Edge Computing Market