
 Europe Battery Packaging Market | 2026-2036
Europe Battery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Battery Packaging Market Analytics
Subscription-based packaging lifecycle management is shifting how European battery logistics contracts are structured. Nefab Group leverages its integrated supply chain services to anchor long-term automotive OEM partnerships. Smurfit Kappa competes through sustainable fiber-based solutions that align with EU circular economy targets. DS Smith specializes in customizable corrugated formats for mid-volume energy storage producers.
Battery packaging encompasses protective enclosures, thermal management layers, and containment systems engineered from flame-retardant polymers, aluminum alloys, or fiber-reinforced composites to prevent thermal runaway propagation during transport and storage. Injection molding dominates rigid plastic housing production for automotive modules due to precision tolerances and cycle efficiency. Composite formats are capturing margin pools in high-performance electric vehicle applications where multi-material barriers outperform single-substrate alternatives. Flexible packaging formats are expanding fastest among consumer electronics and portable power tool segments where weight reduction drives specification.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that ECHA enforces through REACH substance restrictions on hazardous additives. CE marking requirements under the EU Green Deal framework are accelerating redesign cycles for packaging producers serving cross-border supply chains. Stakeholders must monitor how the F-Gas Regulation's phase-down of fluorinated gases reshapes thermal barrier material selection before the next compliance milestone.
Market Dynamics
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are compressing design cycles while ECHA's REACH enforcement on flame-retardant additives forces material substitutions across automotive supply chains.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint declarations and recycled content thresholds create binding compliance demand for redesigned packaging formats across Germany's automotive corridor.
- Nordic battery cell production zones:Sweden and Norway's gigafactory buildouts concentrate procurement of thermal runaway containment systems for cylindrical and prismatic cell formats.
- Fire-resistant polymer innovation:Non-halogenated flame retardants meeting ECHA substance restrictions enable specification wins in premium electric vehicle module housings.
Market Restraints
- Aluminum alloy input volatility:LME price swings for aerospace-grade aluminum alloys compress margin pools in rigid enclosure manufacturing serving mid-volume producers.
- German automotive OEM supply concentration:Volkswagen Group, BMW, and Mercedes-Benz procurement dominance creates pricing pressure and extended payment terms for tier-two packaging suppliers.
- F-Gas Regulation phase-down:Restrictions on fluorinated thermal barrier gases force reformulation of phase-change materials before viable substitutes achieve scale.
Strategic Opportunities
- Poland and Hungary underpenetration:Emerging battery assembly operations in Central Europe lack localized packaging infrastructure, creating first-mover positioning for regional production facilities.
- Second-life battery logistics:Circular economy mandates under the EU Green Deal generate demand for standardized reusable transport containers between automotive dismantlers and recycling processors.
- Digital product passport integration:Battery packaging embedded with RFID and blockchain traceability captures compliance service revenue streams under incoming CSRD disclosure requirements.
Industry Challenges
- Multi-material bonding expertise scarcity:Composite barrier fabrication combining aluminum, mica, and ceramic fiber layers requires specialized technicians absent from conventional packaging labor pools.
- UN 38.3 certification timeline compression:Lithium battery transport testing protocols extend qualification cycles by four to six months, delaying revenue recognition for new format introductions.
- Legacy ERP integration friction:Packaging producers serving dual automotive and energy storage verticals struggle to harmonize inventory systems with diverging OEM and utility procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Battery Packaging Market |
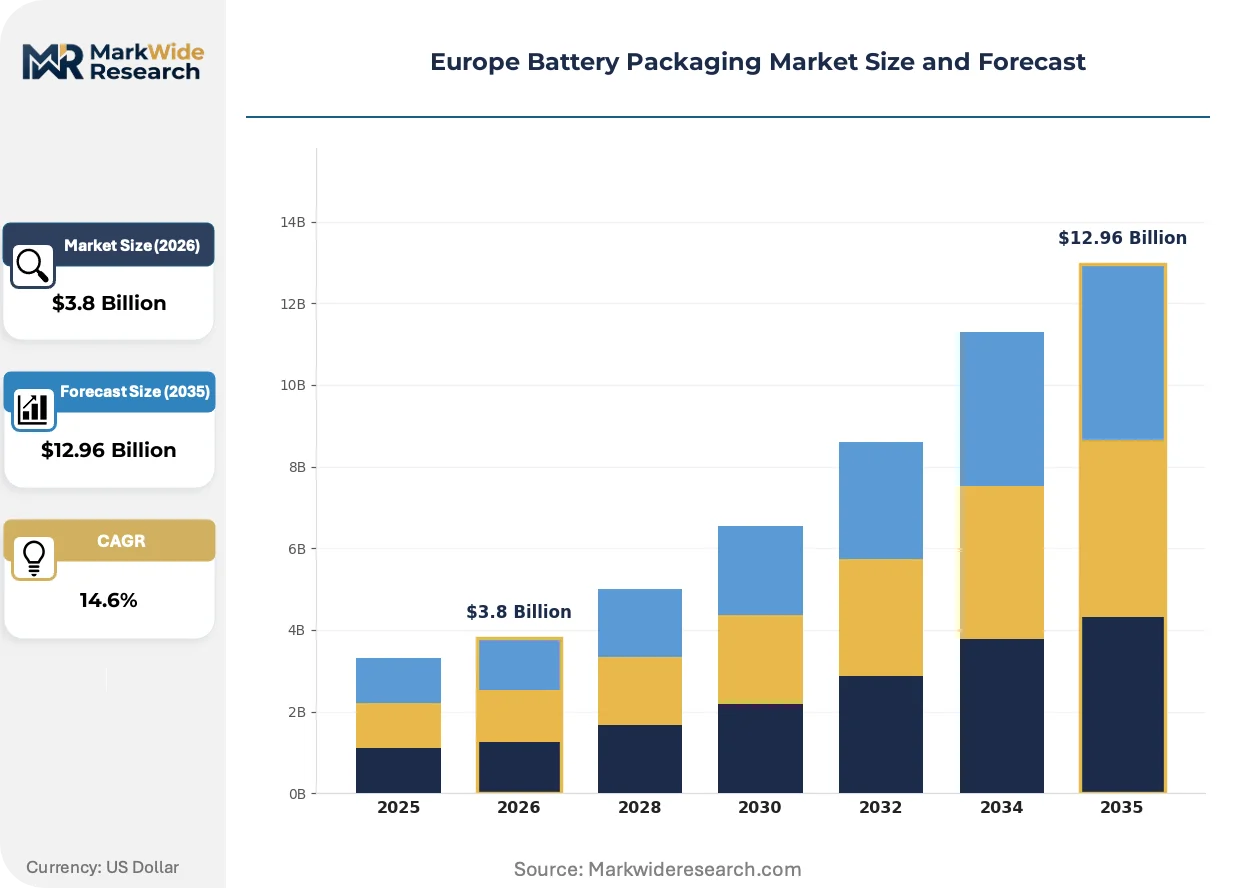
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Paper, Composite End User: Automotive OEMs, Consumer Electronics, Energy Storage Systems, Industrial Equipment Form: Rigid, Flexible, Semi-Rigid, Blister Packaging Technology: Injection Molding, Blow Molding, Thermoforming, Die-Cutting |
| Companies Covered | Nefab Group, Zarges Group, Heitkamp & Thumann Group, Smurfit Kappa, DS Smith, Söhner Kunststofftechnik GmbH, Wellplast AB, GWP Group, Covestro AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Battery Packaging Market Evolving Landscape
Active material substitution and digital compliance integration are compressing traditional packaging procurement cycles while reshaping supplier qualification criteria across European automotive and energy storage verticals.
Aerogel-based thermal barriers are rewriting performance benchmarks for battery module enclosures. German premium electric vehicle manufacturers specify silica aerogel composites for inter-cell spacers, achieving sub-2W/mK thermal conductivity without the weight penalty of conventional ceramic wool. The technology is compressing specification windows for incumbent fiber-based solutions.
REACH substance restrictions on halogenated flame retardants are forcing polymer compounders to validate phosphorus-nitrogen synergist systems. ECHA's 2023-2025 restriction roadmap targets specific brominated additives prevalent in polypropylene battery housings, compelling reformulation investments before the next compliance milestone. Nordic cell producers are accelerating qualification of alternative chemistries to maintain CE marking continuity.
Automotive OEMs are consolidating packaging procurement under lifecycle service contracts that bundle design, logistics, and end-of-life recovery. Long-term agreements spanning eight to twelve years displace spot purchasing for standardized cell formats, concentrating volume with suppliers offering integrated circular economy compliance. This restructuring is most visible in Germany's Baden-Württemberg and Bavaria production clusters.
Europe Battery Packaging Market Segmentation
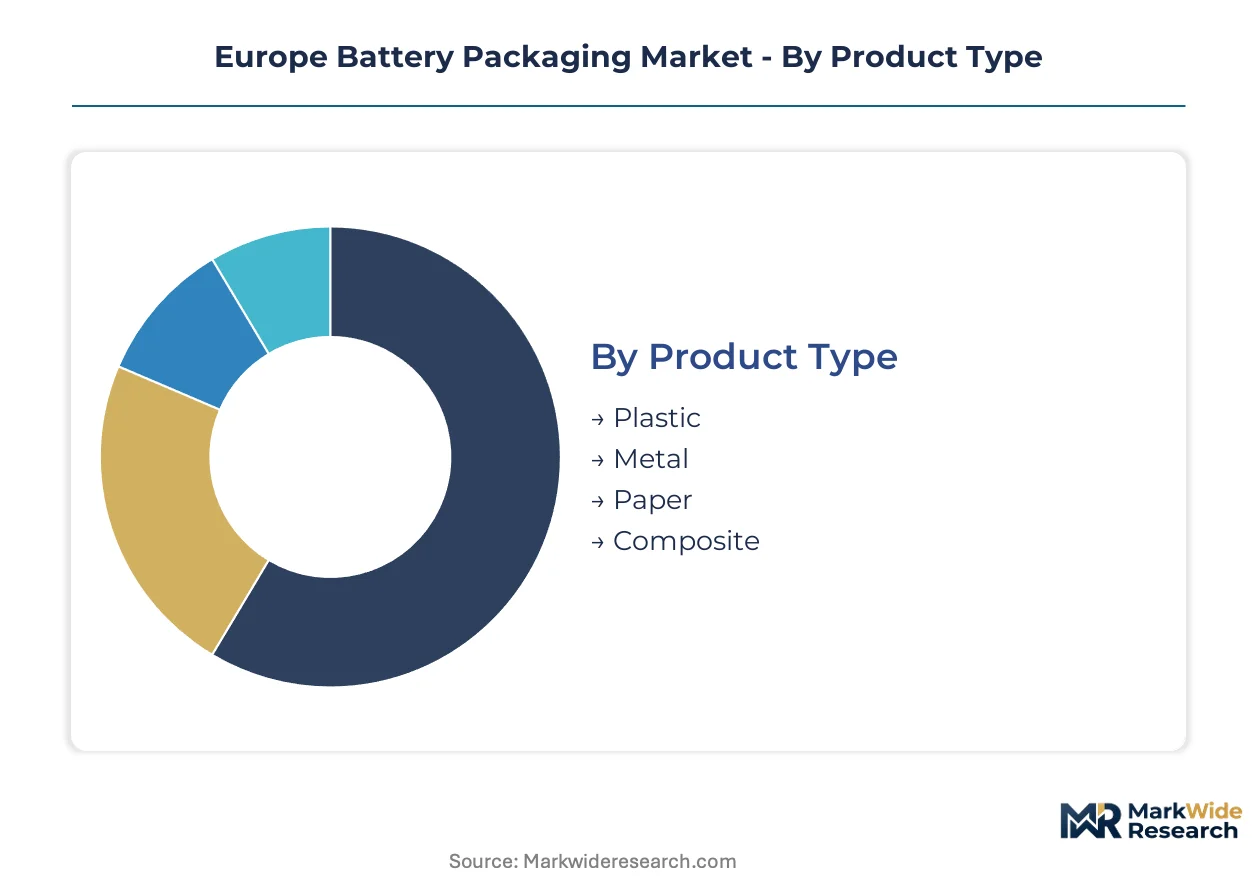
Segmentation in Europe's battery packaging market reveals how material selection and manufacturing technology align with diverging thermal management requirements across automotive and energy storage verticals. Understanding these partitions exposes where procurement power concentrates and where specification windows are widening.
Product Type:
The customization-to-standardization spectrum spans from engineered composites for premium electric vehicle modules to commodity plastics for consumer electronics housings.
- Composite:Multi-material barriers combining aluminum, mica, and ceramic fiber layers achieve sub-2W/mK thermal conductivity for inter-cell spacers in German premium electric vehicle production. Sweden's Northvolt and Norway's Freyr Battery specify these formats for cylindrical cell thermal runaway containment.
- Metal:Aluminum alloy enclosures dominate rigid housing production for prismatic automotive modules, though LME price volatility compresses margins for mid-volume producers serving Poland and Hungary's emerging assembly operations.
- Plastic:Flame-retardant polypropylene and polycarbonate compounds serve cost-sensitive portable power tool and consumer electronics segments where ECHA REACH restrictions on halogenated additives are forcing phosphorus-nitrogen reformulation.
- Paper:Fiber-based corrugated formats from Smurfit Kappa and DS Smith align with EU circular economy mandates for secondary packaging and end-of-life recovery in energy storage system logistics.
Leading the category by volume: Metal. Expanding most quickly: Composite.
End User:
Cost tier stratification separates long-term lifecycle service contracts from spot purchasing arrangements.
- Automotive OEMs:Volkswagen Group, BMW, and Mercedes-Benz procurement dominance in Germany's Baden-Württemberg and Bavaria clusters drives eight-to-twelve-year bundled agreements covering design, logistics, and circular economy compliance.
- Energy Storage Systems:Utility-scale battery deployments require standardized reusable transport containers under EU Green Deal circular economy mandates, generating demand for RFID-embedded packaging between automotive dismantlers and recycling processors.
- Consumer Electronics:Weight reduction specifications favor flexible packaging formats for portable devices, with procurement cycles compressed by rapid product obsolescence.
- Industrial Equipment:Forklift and stationary power applications specify semi-rigid formats balancing durability with cost constraints in mid-volume production runs.
Highest contract value concentration: Automotive OEMs. Steepest specification evolution: Energy Storage Systems.
Form:
Application requirements dictate rigidity trade-offs between protection density and logistics efficiency.
- Rigid:Injection-molded and thermoformed housings protect prismatic and pouch cells in automotive module assembly, with precision tolerances critical for German OEM production lines.
- Flexible:Lightweight formats capture portable electronics and power tool segments where gram-level weight reduction drives specification, expanding fastest among Nordic consumer brands.
- Semi-Rigid:Hybrid constructions balance structural integrity with material efficiency for industrial equipment and secondary logistics applications.
- Blister Packaging:Thermoformed trays organize cylindrical cells for automated assembly in Sweden's gigafactory operations.
Dominant by procurement volume: Rigid. Gaining share fastest: Flexible.
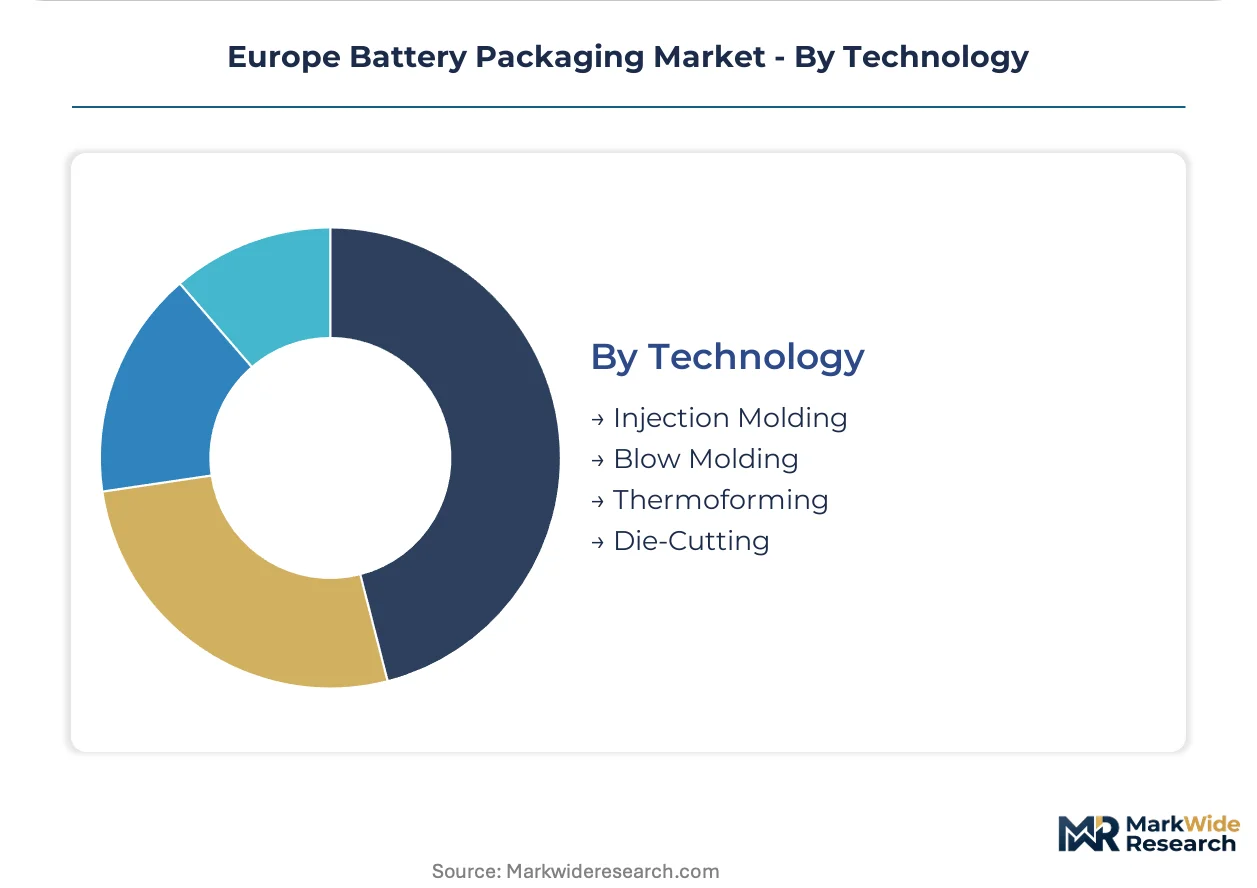
Technology:
Volume scale and margin structure separate high-throughput molding from precision die-cutting operations.
- Injection Molding:Dominates rigid plastic housing production for automotive modules due to cycle efficiency and dimensional repeatability, with German toolmakers supplying precision molds for flame-retardant polymer compounds.
- Thermoforming:Produces blister and tray formats for cell organization and secondary packaging, aligning with mid-volume energy storage producer requirements for customizable corrugated solutions.
- Blow Molding:Hollow container formats serve electrolyte and coolant reservoir integration in thermal management systems.
- Die-Cutting:Precision fiber and composite layer fabrication for aerogel-based thermal barriers and multi-material spacers in premium electric vehicle specifications.
Highest throughput by unit volume: Injection Molding. Climbing the fastest on technology substitution: Thermoforming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's battery packaging production concentrates in Germany and Scandinavia while consumption spreads across automotive and energy storage corridors. Manufacturing gravity pulls toward cell production zones in Sweden and Norway. Regulatory pressure from Brussels reshapes material specifications continent-wide.
Germany
Volkswagen Group, BMW, and Mercedes-Benz procurement dominance in Baden-Württemberg and Bavaria drives specification of fire-resistant polymer enclosures for prismatic automotive modules. ECHA REACH enforcement on halogenated flame retardants forces compound reformulation investments by 2025. Stuttgart and Munich production clusters anchor eight-to-twelve-year bundled lifecycle service contracts covering design, logistics, and circular economy compliance.
Sweden
Northvolt's Skellefteå gigafactory concentrates demand for cylindrical cell thermal runaway containment systems and aerogel-based inter-cell spacers. EU Battery Regulation carbon footprint declarations accelerate qualification of non-halogenated flame retardants in polymer housings. Västerbotten County's cell production zone pulls in composite barrier suppliers from across the Nordic region.
Poland
Emerging battery assembly operations in Lower Silesia and the Warsaw metropolitan area lack localized packaging infrastructure, creating positioning windows for regional production facilities. CE marking requirements under the EU Green Deal compress design cycles for cross-border supply chain integration. Katowice and Wrocław logistics hubs attract secondary packaging investment for energy storage system distribution.
Norway
Freyr Battery's Mo i Rana operations and Morrow Batteries' Arendal facility specify multi-material thermal barriers for prismatic and cylindrical formats. F-Gas Regulation phase-down of fluorinated gases forces reformulation of phase-change materials before substitutes achieve commercial scale. Nordland and Agder counties concentrate Nordic cell production procurement.
United Kingdom
Energy storage system deployments and automotive supply chain participation in the Midlands and Northeast England generate demand for fiber-based corrugated formats aligned with circular economy mandates. DS Smith and Smurfit Kappa operations serve secondary packaging and end-of-life recovery requirements. Birmingham and Sunderland industrial zones anchor mid-volume producer procurement.
Europe Battery Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material technology and integrated service delivery. The vendor base separates between integrated supply chain operators and specialized material compounders. Three archetypes dominate: Nordic logistics-integrated specialists, pan-European fiber-based sustainable packaging providers, and German precision polymer compounders. Competitive moves concentrate on long-term automotive OEM partnerships and geographic expansion into Central European underpenetrated zones.
Within the integrated supply chain tier, Nefab Group exemplifies the lifecycle service model anchoring long-term automotive partnerships. Among fiber-based sustainable packaging providers, Smurfit Kappa and DS Smith occupy positions aligned with EU circular economy mandates and CSRD disclosure requirements. German precision compounders represented by Covestro AG sit within the material technology tier supplying flame-retardant polymer systems.
| Leading Market Players |
|---|
| Nefab Group |
| Zarges Group |
| Heitkamp & Thumann Group |
| Smurfit Kappa |
| DS Smith |
| Söhner Kunststofftechnik GmbH |
| Wellplast AB |
| GWP Group |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Aerogel-based thermal barrier adoption in German premium electric vehicle manufacturing compresses specification windows for incumbent fiber-based solutions while simultaneously concentrating procurement power among compounders capable of multi-material bonding. This technology transition reshapes cost economics across the value chain, rewarding suppliers with in-house die-cutting expertise and penalizing conventional molding operations unable to achieve sub-2W/mK thermal conductivity.
Pricing Analysis
Margin tightening in mid-volume rigid enclosure manufacturing reflects LME price volatility for aerospace-grade aluminum alloys serving Poland and Hungary's emerging battery assembly operations. Three-tier pricing structure across premium composite barriers, standard metal housings, and economy-grade polymer formats separates specification tiers by thermal performance certification and automotive OEM pedigree. Cost-down pressure on fiber-based corrugated solutions accelerates as Smurfit Kappa and DS Smith compete for standardized energy storage system logistics contracts. Energy storage system buyers exhibit highest price sensitivity due to utility procurement standardization, while German automotive OEMs prioritize lifecycle service bundling over unit cost.
Supply Chain Analysis
UN 38.3 lithium battery transport certification requirements extend supplier qualification cycles by four to six months, gating market access for unproven compounders and reinforcing incumbent positioning. Manufacturing concentrates in Germany's precision polymer compounding corridor, Sweden's Northvolt-adjacent composite barrier cluster, and Norway's Freyr Battery supply zone. Raw material dependencies rest on halogenated flame retardant alternatives, silica aerogel precursors, and mica-ceramic fiber laminates. Single-source vulnerability around specialized technicians for multi-material bonding creates bottleneck risk. Distribution runs through automotive OEM direct procurement platforms and Nordic cell producer integrated logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-material bonding expertise scarcity props pricing power for qualified suppliers, constraining capacity expansion and sustaining margin premiums across the European battery packaging value chain.
For Market Incumbents: Lock in eight-to-twelve-year bundled lifecycle service contracts with Volkswagen Group, BMW, and Mercedes-Benz before REACH substance restrictions on halogenated flame retardants force compound reformulation investments by 2025. Deepen backward integration into aerogel precursor supply through captive partnerships with German specialty chemical producers. Prioritize certification investment in phosphorus-nitrogen synergist systems to maintain CE marking continuity under ECHA's 2023-2025 restriction roadmap. For New Entrants and Emerging Players: Aerogel composite die-cutting capabilities offer a technology-first wedge into premium electric vehicle thermal barrier specifications where incumbent fiber solutions face displacement. Target Poland and Hungary's underpenetrated battery assembly corridors where localized packaging infrastructure gaps create first-mover positioning for regional production facilities. Pursue digital product passport integration as a go-to-market angle, embedding RFID and blockchain traceability to capture compliance service revenue under incoming CSRD disclosure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated supply chain operators seeking geographic expansion into Central European growth zones. Five-to-ten year viability hinges on compounders' ability to navigate F-Gas Regulation phase-down timelines and alternative thermal barrier scale-up. Target acquisition archetype: Nordic logistics-integrated specialists with established Northvolt or Freyr Battery relationships and proven multi-material bonding technician pipelines. Watch for inflection when Poland and Hungary gigafactory announcements trigger regional packaging infrastructure investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Bonding Capacity Expansion | Captures margin pools in aerogel-aluminum-ceramic composite barriers for German premium EV specifications. |
| Phosphorus-Nitrogen Flame Retardant Qualification | Ensures CE marking continuity under ECHA REACH restrictions targeting brominated additives in polypropylene housings. |
| Central European Regional Production Footprint | Positions first-mover advantage in Poland and Hungary's emerging battery assembly zones lacking localized infrastructure. |
| Digital Product Passport Integration | Generates compliance service revenue streams under CSRD disclosure requirements for battery packaging traceability. |
| Second-Life Battery Logistics Container Standardization | Aligns with EU Green Deal circular economy mandates for reusable transport between automotive dismantlers and recyclers. |
Research Methodology
Trade association filings, ECHA regulatory submissions, and EU customs data formed the secondary backbone, cross-referenced against primary interviews with Tier 1 automotive packaging procurement managers, Nordic cell producer supply chain directors, ECHA regulatory affairs specialists, and composite barrier fabrication technicians. Bottom-up segmentation modeling triangulated with top-down macroeconomic trend analysis validated volume and value estimates across the analysis window.
Historical trendline analysis established baseline growth patterns across material technology transitions, with projection frameworks incorporating injection molding cycle efficiency improvements, aerogel thermal barrier adoption curves, and REACH substance restriction compliance timelines. Segmentation dimensions modeled include product type, end-user vertical, form factor rigidity, and manufacturing technology. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity constraints, with specific inputs from F-Gas Regulation phase-down schedules and EU Battery Regulation carbon footprint declaration implementation.
Several conditions sit outside the modeled scope, including unforeseen raw material price shocks, accelerated regulatory timeline revisions, and geopolitical disruptions to Nordic cell production expansion. Forecasts reflect documented assumptions about technology substitution rates and buyer procurement consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Personal Care Packaging Market
Others
Spain Automotive LED Lighting Market
Others
Free Space Optics (FSO) Market
Others
Lychee Market
Others
Global Duty-Free Retailing Market
Others
Industrial Wearable Devices Market
Others
Africa Lime Market
Others
North America Cashew Market
Others
Palatants Market
Others
Floor Cleaning and Mopping Machine Market
Others
US Quantum Computing Market
Others
Fluorite Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Drum Motor Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Injectable Nanomedicine Market