
 Mobile Computer Cart Market | 2026-2036
Mobile Computer Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Computer Cart Market Insights
Hospital systems is reorganizing procurement priorities toward powered medication administration carts with integrated barcode scanning and biometric authentication. Ergotron leverages its vertical integration in monitor mounting mechanics to sustain premium positioning across acute care settings. Capsa Healthcare anchors its competitive stance through specialized pharmacy and nursing workstation configurations that dominate North American hospital supply chains.
A mobile computer cart is a wheeled workstation frame designed to transport computing hardware, power systems, and peripheral devices across clinical, educational, or commercial environments, typically constructed from aluminum or steel tubing with casters rated for medical-grade floor surfaces and load capacities exceeding 100 pounds. Its primary purpose is to enable point-of-care data entry, mobile learning delivery, or transactional processing without fixed infrastructure. The workstation segment commands the deepest margin pools where battery management systems and thermal engineering differentiate vendor offerings, while charging solutions represents the fastest-growing category as facilities consolidate fleet power management into centralized infrastructure. Healthcare facilities drives the largest absolute volume, though educational institutions is gaining traction as K-12 districts deploy one-to-one device programs requiring mobile storage and distribution.
FDA medical device regulations and IEC 60601-1 electrical safety standards govern powered cart deployments in clinical settings, with OSHA ergonomic guidelines additionally shaping adjustable-height design requirements to reduce musculoskeletal injury liability. The EU Medical Device Regulation and CE marking directives constrain market access for carts incorporating patient-facing software or diagnostic connectivity. Stakeholders must monitor evolving cybersecurity frameworks for connected healthcare devices as cart-integrated systems expand network attack surfaces.
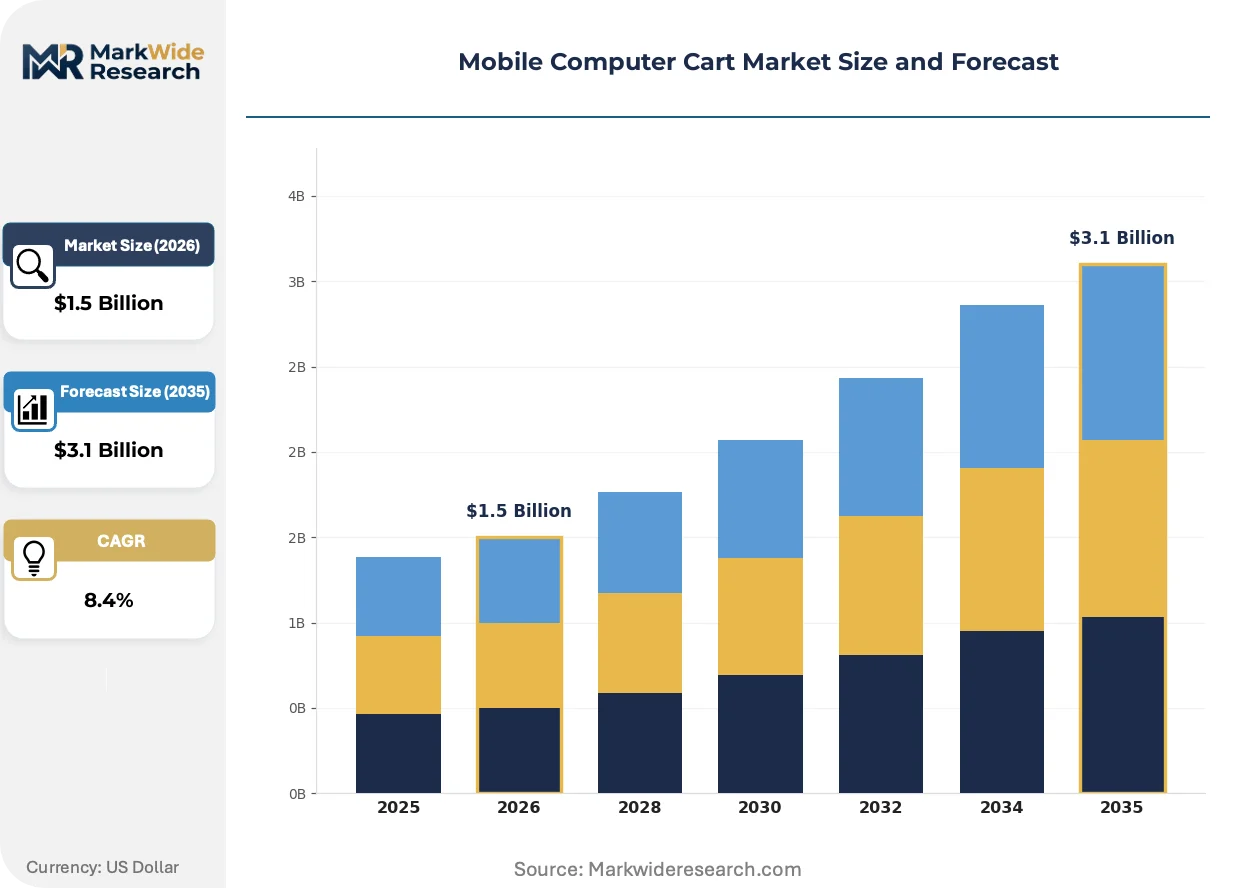
Market Dynamics
Hospital systems are consolidating fleet procurement around powered medication administration carts with integrated biometric authentication, compressing vendor selection cycles and elevating electrical safety certification requirements as non-negotiable gatekeepers.
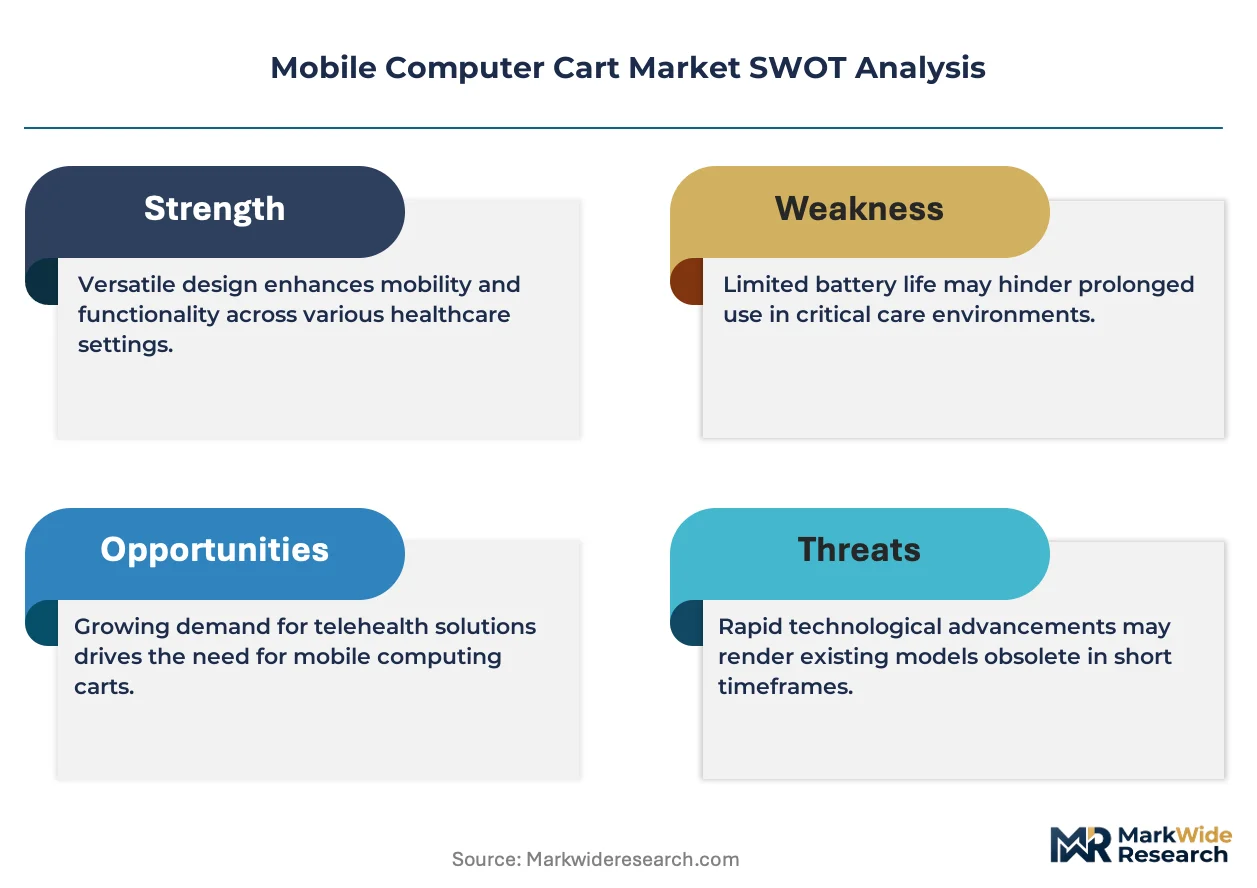
Growth Catalysts
- IEC 60601-1 compliance mandates:FDA device classification rules for powered clinical equipment are forcing replacement of legacy ungrounded cart fleets across acute care networks.
- K-12 one-to-one device programs:Educational institutions are deploying mobile storage and distribution carts to manage tablet and laptop inventories across distributed campuses.
- Barcode scanning integration:Bedside medication administration workflows require cart-mounted scanner hardware, pulling hardware upgrades through clinical safety protocols.
Market Restraints
- Lithium-ion battery supply concentration:Cell production clusters in East Asia create vulnerability for cart manufacturers dependent on just-in-time battery module delivery.
- Aluminum extrusion cost volatility:Primary metal pricing swings directly compress margin on cart frame assemblies, the largest material cost category.
- EU Medical Device Regulation friction:CE marking requirements for patient-facing software connectivity extend certification timelines by 12-18 months for European market entry.
Strategic Opportunities
- Centralized charging infrastructure:Facilities are consolidating fleet power management into wall-mounted charging stations, opening retrofit service contracts for existing cart deployments.
- India healthcare modernization:Government hospital digitization initiatives under Ayushman Bharat are creating first-time demand for powered clinical workstations in tier-2 and tier-3 cities.
- RFID and biometric convergence:Carts integrating both authentication technologies are capturing preference in medication administration workflows requiring dual-factor security.
Industry Challenges
- IEC 60601-1 third edition testing backlog:Certification laboratory capacity constraints are delaying product launches for powered cart variants.
- Legacy fleet interoperability:Hospital IT departments face integration complexity when connecting new cart-mounted systems to existing electronic health record architectures.
- Thermal engineering talent scarcity:Battery management system design expertise sits concentrated within a small pool of specialized engineering consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Computer Cart Market |
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $3.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Accessories, Workstations, Charging Solutions End User: Healthcare Facilities, Educational Institutions, Corporate Offices, Retail Stores Application: Patient Care, Mobile Learning, Point of Sale, Inventory Management Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | Ergotron, Capsa Healthcare, Advantech Co. Ltd., Enovate Medical, Midmark Corporation, Altus, Scott-Clark Medical, ITD GmbH, Jaco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Computer Cart Market Trends and Innovations
Power electronics and authentication hardware are compressing into smaller physical envelopes, enabling cart designs that shed weight without sacrificing runtime or security functionality. Three developments are restructuring competitive positioning.
Solid-state battery technology is miniaturizing energy storage into thinner form factors. Emergency departments and rapid response teams are adopting these configurations to improve maneuverability in crowded clinical spaces. The structural consequence is compressing frame depth requirements and enabling slimmer cart profiles that navigate tighter corridors.
The EU Medical Device Regulation is tightening software validation requirements for carts with patient-facing diagnostic connectivity. Manufacturers must now submit clinical evidence packages for firmware updates, extending product lifecycle management costs. Acute care networks in Germany and France are prioritizing vendors with established notified body relationships to de-risk procurement.
Integrated delivery networks are consolidating vendor contracts into multi-year fleet management agreements that bundle hardware, maintenance, and battery replacement cycles. This displaces transactional purchasing through regional medical distributors. The shift is most visible in United States hospital systems where procurement departments now evaluate total cost of ownership over five-year horizons rather than unit acquisition price.
Mobile Computer Cart Market Segmentation
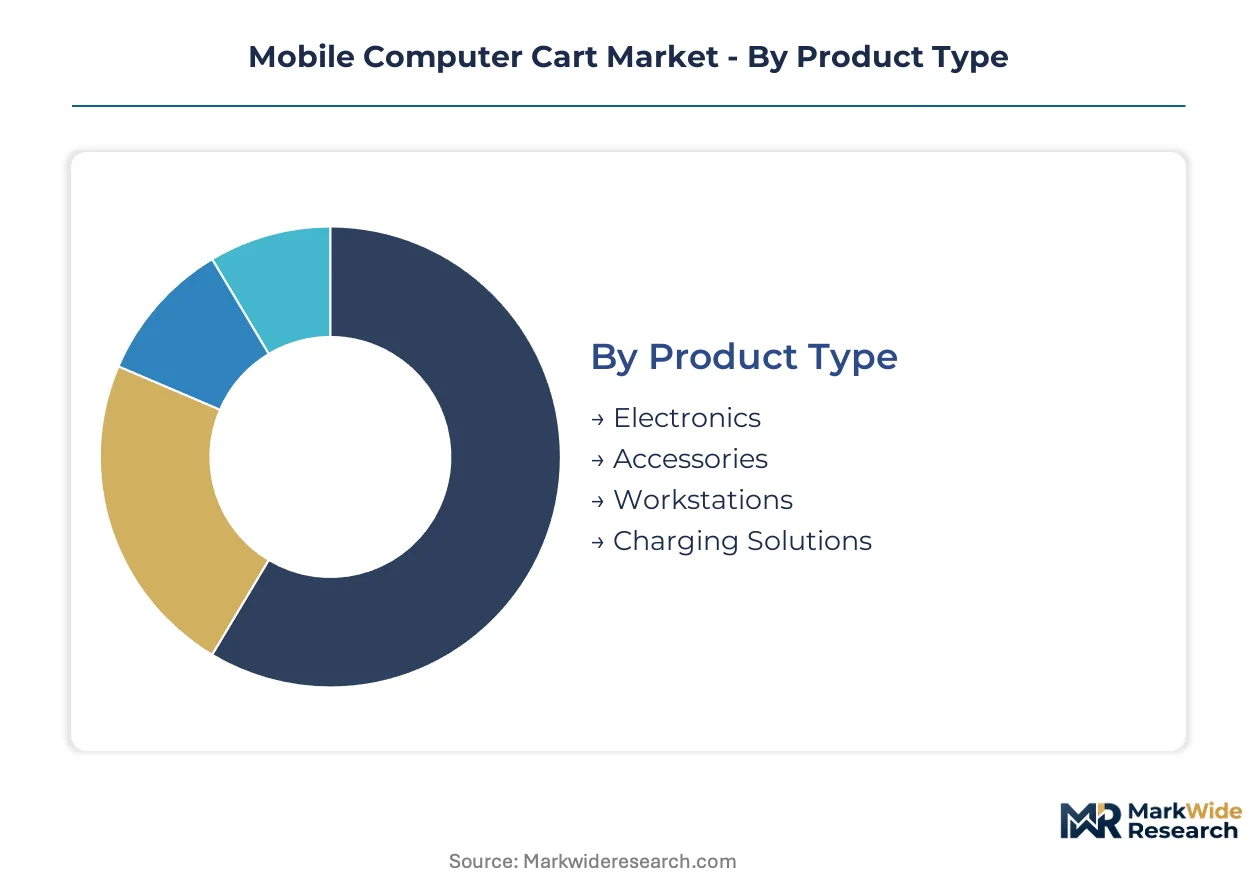
Segmentation reveals how technical specifications and use-case intensity create divergent margin profiles across the mobile computer cart landscape. Product architecture and material selection directly determine IEC 60601-1 compliance pathways, while end-user concentration shapes procurement channel strategies.
Product Type:
Workstations face acute substitution pressure from tablet-based mobile workflows in low-acuity clinical settings, forcing vendors to defend positioning through integrated power and authentication bundles.
- Workstations:These units combine height-adjustable frames, hot-swappable battery systems, and peripheral mounting hardware to support continuous clinical documentation. Demand concentrates in United States acute care networks where bedside medication administration protocols require FDA-compliant powered configurations with biometric authentication integration.
- Charging Solutions:Centralized wall-mounted or rack-based systems consolidate fleet power management for distributed device inventories. K-12 districts in Texas and California are deploying these at scale to support one-to-one laptop programs, with procurement driven by facilities management rather than clinical engineering departments.
- Electronics:Cart-integrated computing modules, battery management systems, and authentication hardware comprise this segment. Hospital IT departments specify these components separately when refreshing legacy fleet compute layers.
- Accessories:Scanner mounts, keyboard trays, and cable management systems attach to base cart platforms. These generate recurring revenue streams through replacement cycles tied to wear patterns in high-traffic corridors.
Workstations anchor the volume base while charging solutions gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade healthcare deployments from price-sensitive education and retail procurement, with certification requirements creating hard boundaries between segments.
- Healthcare Facilities:Hospitals and health systems command premium pricing through IEC 60601-1 electrical safety mandates and FDA device classification requirements. Integrated delivery networks in the United States negotiate multi-year fleet management contracts bundling hardware, preventive maintenance, and battery replacement cycles.
- Educational Institutions:K-12 districts and universities prioritize mobile storage and distribution over powered workstations, with procurement flowing through cooperative purchasing agreements. Districts in Florida and New York are consolidating vendor selection around charging cart configurations that manage one-to-one device inventories across distributed campuses.
- Corporate Offices:Hybrid work arrangements are compressing demand for dedicated mobile workstations, with facilities managers favoring shared hot-desking solutions over permanent cart deployments.
- Retail Stores:Point-of-sale and inventory management applications drive transactional purchasing through regional distributors, with seasonal volume spikes tied to holiday hiring cycles.
Healthcare facilities dominate absolute revenue while educational institutions expand most quickly as device penetration deepens in K-12 systems.
Application:
Application maturity varies sharply, with patient care workflows governed by clinical safety protocols that retail inventory management simply does not face.
- Patient Care:Bedside documentation, medication administration, and clinical decision support require carts with antimicrobial surfaces, seamless EHR integration, and dual-factor authentication. United States hospital systems under Joint Commission oversight mandate these specifications as non-negotiable procurement criteria.
- Mobile Learning:Classroom device distribution and retrieval workflows favor lightweight, non-powered carts with integrated charging. School districts in Georgia and North Carolina are standardizing around 30-40 unit capacity configurations that align with typical class sizes.
- Point of Sale:Retail and hospitality deployments prioritize compact footprints and payment terminal integration, with seasonal demand fluctuations driving rental rather than purchase models.
- Inventory Management:Warehouse and back-of-store applications emphasize durability and scanner integration, with procurement decisions driven by total cost of ownership calculations over extended deployment horizons.
Patient care commands the deepest margin pools while mobile learning climbs the fastest on education digitization tailwinds.
Material:
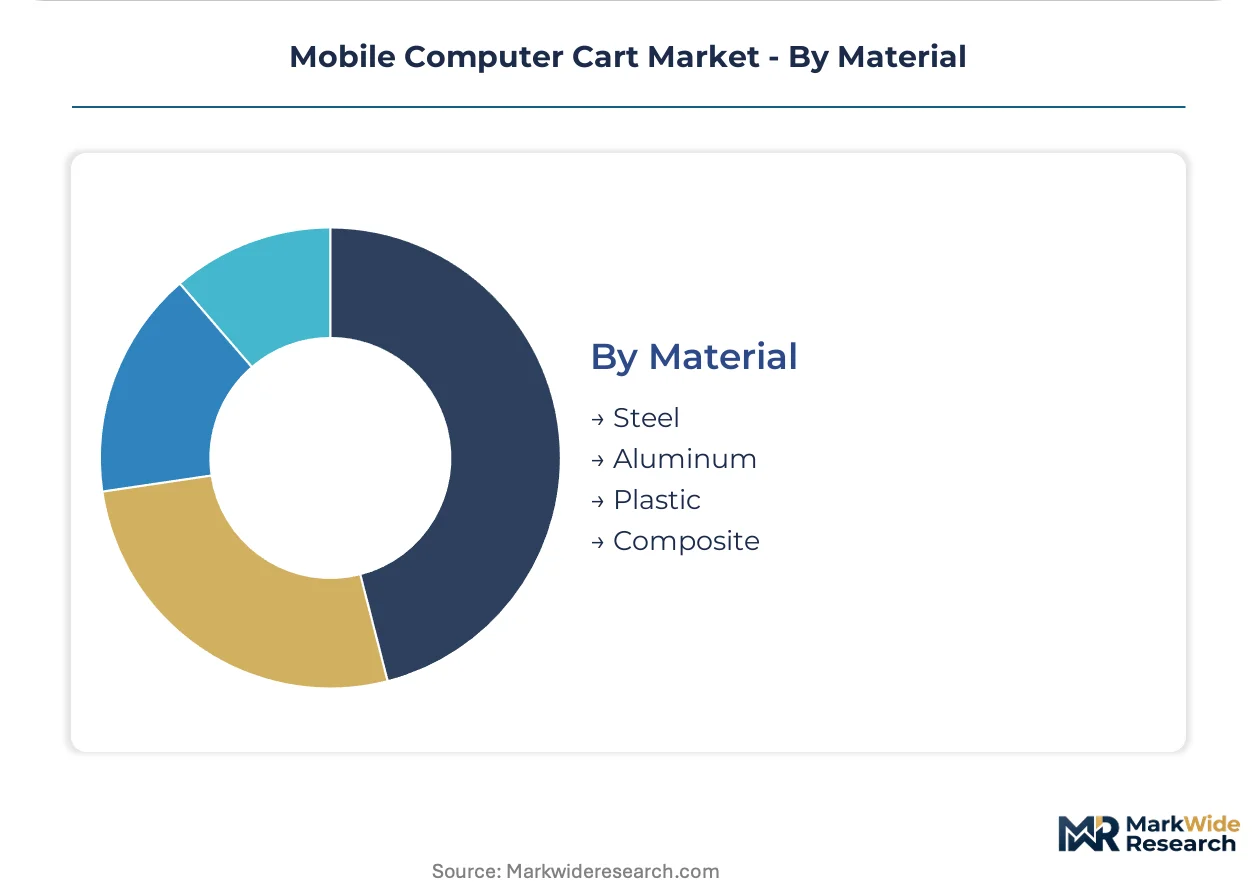
Supply concentration in primary metals creates cost volatility that directly transmits to frame assembly pricing, with composite alternatives gaining traction where weight reduction justifies premium positioning.
- Aluminum:Extruded aluminum tubing dominates mid-to-premium cart construction, offering strength-to-weight ratios that support maneuverability in crowded clinical corridors. LME pricing swings directly compress manufacturer margins on frame assemblies, the largest material cost category.
- Steel:Cold-rolled steel frames anchor economy-tier offerings for education and retail segments where absolute durability outweighs weight considerations. Domestic mill capacity in Ohio and Indiana supports regional supply chain configurations for North American manufacturers.
- Plastic:Injection-molded components reduce unit weight for charging carts and accessory housings, with recycled content specifications emerging in California and Washington state procurement guidelines.
- Composite:Carbon fiber and fiberglass-reinforced materials enable ultra-lightweight configurations for emergency department rapid response teams, with premium positioning justified by maneuverability gains in space-constrained environments.
Steel retains the highest shipment volumes while composite materials capture expanding share in specialized clinical applications demanding weight minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors North American logistics capacity for aluminum extrusion feedstock and battery cell imports that underpin cart manufacturing supply chains.
United States
Integrated delivery networks in Texas and California are consolidating multi-year fleet management contracts bundling hardware, maintenance, and battery replacement cycles. FDA device classification rules and IEC 60601-1 electrical safety mandates govern powered cart deployments in acute care settings. The Dallas-Fort Worth metroplex concentrates procurement decision-making for hospital systems operating across the Southwest.
Germany
Acute care networks in Bavaria and North Rhine-Westphalia prioritize vendors with established notified body relationships under EU Medical Device Regulation requirements. CE marking directives constrain market access for carts incorporating patient-facing software connectivity. The Stuttgart industrial corridor hosts engineering consultancies specializing in battery management system design for clinical equipment.
China
Government hospital digitization initiatives are creating first-time demand for powered clinical workstations in tier-2 and tier-3 cities outside Beijing and Shanghai. GB standards and NMPA regulations shape domestic certification pathways for medical-grade electrical equipment. The Yangtze River Delta manufacturing cluster supplies aluminum extrusion components to global cart assemblers.
India
Ayushman Bharat healthcare modernization is driving procurement of mobile workstations in Maharashtra and Karnataka state hospital systems. CDSCO medical device regulations and BIS electrical safety standards govern import and domestic production requirements. The Pune industrial belt is emerging as an assembly hub for mid-tier cart configurations serving South Asian markets.
Japan
Metropolitan hospital networks in Tokyo and Osaka are adopting solid-state battery configurations to improve maneuverability in space-constrained emergency departments. METI energy efficiency guidelines and PMDA device regulations shape premium-tier procurement specifications. The Nagoya manufacturing corridor concentrates precision metalworking capacity for lightweight frame assemblies.
Mobile Computer Cart Market Competitive Landscape
Concentration sits with vertically integrated specialists controlling in-house production of monitor mounting mechanics and battery management systems. The vendor base stratifies across three tiers: premium-positioned workstation specialists, mid-tier regional fabricators, and economy-grade charging solution providers. Dominant competitive moves include backward integration into aluminum extrusion sourcing and strategic partnerships with EHR platform vendors to secure bedside workflow integration.
Within the premium-tier specialist archetype, Ergotron and Capsa Healthcare occupy positions defined by acute care network relationships and IEC 60601-1 certification depth. Advantech Co. Ltd. represents the Asia-Pacific manufacturing scale vector, anchoring supply chain configurations that serve both domestic Chinese hospital digitization and export markets. These three exemplify how geographic origin and company structure suffixes—Inc., Healthcare, Co. Ltd.—signal divergent strategic postures without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Ergotron |
| Capsa Healthcare |
| Advantech Co. Ltd. |
| Enovate Medical |
| Midmark Corporation |
| Altus |
| Scott-Clark Medical |
| ITD GmbH |
| Jaco Inc. |
| Others |
Pricing and Supply Chain Analysis
Solid-state battery chemistry substitution for lithium-ion packs is redrawing procurement geography toward Japanese and South Korean cell manufacturers while compressing pricing premiums previously commanded by legacy thermal management systems. This chemistry migration simultaneously elevates landed costs for North American assemblers and creates tiered sourcing flexibility that larger hospital systems exploit in multi-year fleet negotiations.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with integrated delivery networks extracting graduated price concessions on fleet orders exceeding five hundred units. Three-tier pricing stratifies across FDA-certified powered configurations, IEC 60601-1 compliant mid-tier offerings, and non-powered economy carts for educational deployment. Cost compression in the aluminum extrusion tier is intensifying because LME pricing volatility transmits directly to frame assembly margins. Educational institutions exhibit the sharpest price sensitivity, while acute care networks prioritize total cost of ownership calculations that amortize battery replacement cycles and preventive maintenance over extended horizons.
Supply Chain Analysis
Inventory buffers and extended lead times for battery management system components have become standard operating posture following pandemic-era disruptions in semiconductor availability. Cell production clusters in China, South Korea, and Japan anchor global supply, with aluminum extrusion feedstock drawing from Yangtze River Delta and domestic Ohio mill capacity. Single-source vulnerability concentrates in specialized battery management ICs sourced from a limited pool of fabless designers. Distribution runs through regional medical distributors for smaller health systems and direct vendor relationships for integrated delivery networks managing enterprise fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement power is concentrating in United States integrated delivery networks, with hospital system consolidation compressing vendor count per metropolitan statistical area and elevating price transparency across competing cart configurations.
For Market Incumbents: Consolidate backward integration into aluminum extrusion sourcing and captive battery module assembly to defend margin position against emerging Asian manufacturers with scale advantages. The priority lever centers on locking multi-year fleet management contracts before procurement departments complete vendor rationalization cycles. IEC 60601-1 third edition certification depth serves as the primary defensive moat against mid-tier regional fabricators lacking notified body relationships.
For New Entrants and Emerging Players: Aftermarket battery replacement and legacy fleet retrofit services represent underserved white space where established vendors prioritize new unit sales over recurring revenue capture. Tier-2 and tier-3 cities in India under Ayushman Bharat digitization programs offer the most penetrable geography, with CDSCO registration pathways less congested than FDA or CE marking queues. A service-first go-to-market angle bundling installation, training, and maintenance contracts can bypass capital procurement committees that gate hardware-only vendor selection.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-tier manufacturers that acquired regional fabricators during consolidation waves but lack R&D depth in solid-state battery integration. Long-term viability hinges on five-to-ten year fleet refresh cycles in United States acute care networks and the pace of K-12 one-to-one device program expansion. The inflection signal to monitor is hospital procurement committee adoption of total cost of ownership scoring that weights battery replacement and maintenance bundling above unit acquisition price.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks Bavaria and North Rhine-Westphalia hospital procurement access. |
| Hospital System Partnership | Integrated delivery network fleet management contracts displace transactional purchasing through regional distributors. |
| Battery Supply Agreement | Long-term cell offtake contracts with South Korean manufacturers hedge lithium-ion supply concentration risk. |
| Software Companion Development | EHR platform integration modules differentiate workstation configurations in Joint Commission-governed facilities. |
| Backward Integration | In-house aluminum extrusion sourcing insulates margin from LME pricing volatility in frame assemblies. |
Research Methodology
A spread of perspectives from hospital procurement directors, biomedical engineering managers, GPO contracts specialists, and battery system design consultants converged on the working assumptions driving this analysis. Primary interview intelligence combined with secondary validation against FDA 510(k) filings, IEC certification registries, hospital procurement databases, and aluminum trade flow data. Bottom-up unit demand estimates triangulated against top-down healthcare capital expenditure trends across the analysis window.
Segmentation dimensions modeled include product architecture tier, end-use intensity grade, material composition category, and regional regulatory cluster throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to fleet penetration rates in acute care networks and K-12 device program adoption patterns. Industry-specific forecast inputs incorporated IEC 60601-1 third edition certification timelines and Ayushman Bharat procurement disbursement schedules.
Underlying assumptions cover aluminum pricing stability, battery cell import continuity, and hospital capital budget allocation norms, with deviation risk concentrated in lithium-ion supply disruption and EU Medical Device Regulation enforcement intensity. Revision becomes warranted when solid-state battery cost curves cross commercial viability thresholds or integrated delivery network consolidation accelerates beyond modeled procurement concentration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Hydraulics Market
Others
Billet Market
Others
Asia-Pacific Road Safety Market
Others
Global Electroshock Weapons Market
Others
Fluid Bed Systems Market
Others
Global Cigarette Packaging Market
Others
Fluid Dispensing Systems Market
Others
Industrial Gauges Market
Others
Bird Food Market
Others
France Smart Home Market
Others
Global Social Networking Market
Others
Turbo Mills Market
Others
Baking Paper Market
Others
Canada 3D Printing Construction Market
Others
UAE Location-Based Services Market
Others
Connected TV Market