
 Versatile Video Coding Market | 2026-2036
Versatile Video Coding Market Size, Share, and Industry Trends Forecast 2026-2036
Versatile Video Coding Market Analytics
Software-defined processing is pivoting hardware-centric codec economics toward cloud-native and edge deployments. MediaKind leverages its broadcast heritage to sustain premium live-event encoding workflows. ByteDance anchors massive-scale short-form video transcoding through its TikTok and Douyin platforms. Qualcomm Technologies dominates mobile-optimized VVC acceleration in smartphone SoCs.
Versatile Video Coding refers to the H.266/MPEG-I Part 3 standard developed by the Joint Video Experts Team of ITU-T and ISO/IEC, employing quadtree plus multi-type tree block partitioning with 128×128 coding tree units to achieve roughly 50% bitrate savings versus HEVC at equivalent perceptual quality for broadcast, streaming, and immersive video distribution. Encoder hardware and software solutions lead current revenue as early commercialization concentrates in professional broadcast and streaming infrastructure, while decoder penetration accelerates fastest through smartphone chipset integration and smart TV firmware updates. Cloud-based deployment captures expanding margin pools as media companies shift capital expenditure to operational expenditure models for elastic transcoding capacity.
The Federal Communications Commission shapes US broadcast transition timelines, while the European Telecommunications Standards Institute influences codec interoperability mandates across EU member states. China's Ministry of Industry and Information Technology accelerates domestic VVC adoption through national ultra-high-definition video industry policy frameworks. Stakeholders must monitor patent pool licensing finalization between Access Advance and MPEG LA, as royalty structures will determine whether VVC achieves mass-market deployment or fragments into competing regional standards.

Market Dynamics
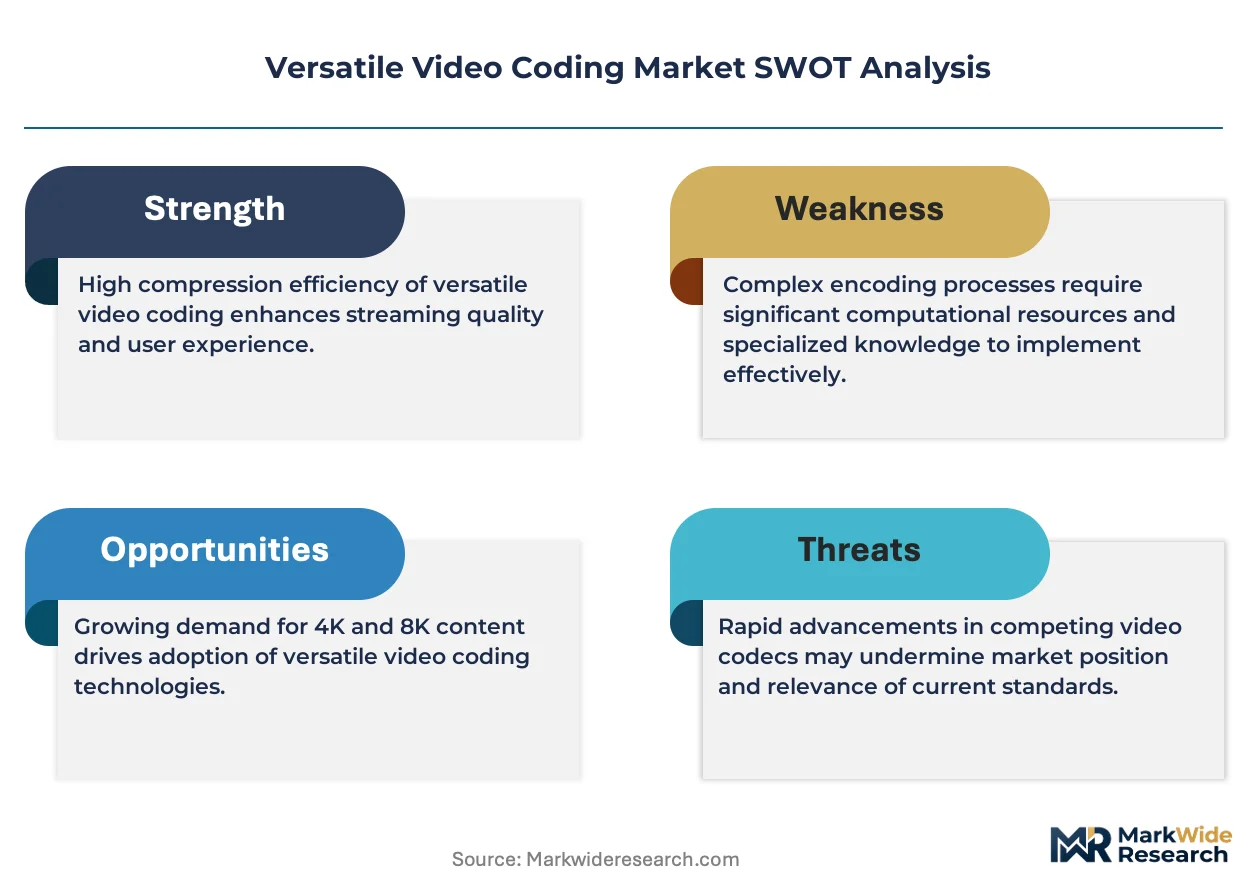
Patent pool licensing fragmentation between Access Advance and MPEG LA is creating structural uncertainty that stalls mass-market VVC deployment despite technical readiness for 4K and 8K streaming infrastructure.
Growth Catalysts
- China's ultra-high-definition video policy:MIIT mandates drive domestic encoder procurement for broadcast infrastructure upgrades.
- Smartphone SoC integration:Mobile chipset vendors embed hardware-accelerated VVC decode blocks into premium tier devices.
- Cloud transcoding elasticity:Media platforms shift from fixed-capacity encoding farms to usage-based operational expenditure models.
Market Restraints
- Uncertain royalty structures:Unfinalized patent pool terms deter consumer electronics manufacturers from committing decoder silicon.
- HEVC installed base inertia:Existing encoding infrastructure and content libraries create switching cost barriers for streaming services.
- AV1 competitive pressure:Royalty-free alternative codecs from the Alliance for Open Media attract budget-conscious platform operators.
Strategic Opportunities
- Edge computing nodes:Low-latency live streaming workflows demand distributed encoding closer to consumption points.
- Immersive video formats:360-degree and volumetric content for virtual reality headsets requires VVC's enhanced compression tools.
- South Korea's 5G content mandates:National policy frameworks prioritize domestic platform adoption of next-generation codecs.
Industry Challenges
- Codec engineering talent scarcity:Deep expertise in block partitioning optimization and entropy coding remains concentrated among legacy MPEG contributors.
- Cross-platform certification complexity:Decoder conformance testing across fragmented smart TV firmware ecosystems delays commercial rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Versatile Video Coding Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Codec, Player, Encoder, Decoder Application: Streaming Services, Broadcast, Video Conferencing, Gaming End User: Media Companies, Enterprises, Educational Institutions, Content Creators Deployment: On-premises, Cloud-based, Hybrid, Edge |
| Companies Covered | MediaKind, ByteDance, Ateme SA, MediaTek Inc., Qualcomm Technologies, Inc., Harmonic Inc., SpinDigital, Google LLC, MainConcept, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Versatile Video Coding Market Evolving Landscape
Software-defined video processing is dissolving the boundary between broadcast-grade encoding and elastic cloud infrastructure, enabling new operational models for live and on-demand content delivery.
Quadtree plus multi-type tree partitioning is expanding into professional broadcast workflows by enabling finer-grained block subdivision for complex scene textures. Sports leagues and live event producers adopt these tools to maintain perceptual quality at half the bitrate of prior standards. The technology is expanding into remote production pipelines where bandwidth constraints previously limited camera count and resolution.
The FCC's broadcast incentive auction repack and subsequent spectrum reallocation decisions influence terrestrial television transition timelines for next-generation transmission standards. These regulatory movements compress deployment windows for encoder hardware upgrades among station groups. US broadcasters respond by phasing VVC readiness into capital planning cycles aligned with ATSC 3.0 infrastructure refreshes.
Content platforms now unbundle encoding services from traditional integrated vendor relationships, treating transcoding as a commodity compute workload procured through hyperscale cloud marketplaces. This procurement pattern disrupts legacy broadcast equipment suppliers who previously captured recurring maintenance revenue. The shift is most pronounced among subscription streaming services operating multi-region content libraries requiring variable bitrate ladders.
Versatile Video Coding Market Segmentation

Versatile Video Coding market segmentation reveals how technical requirements diverge across infrastructure layers and consumption contexts. Understanding these splits enables targeted positioning for codec vendors navigating patent uncertainty and deployment model transitions.
Product Type:
Buyers in this category differentiate primarily by integration depth versus flexibility trade-offs in their video pipelines.
- Encoder:Hardware and software solutions compress raw video into H.266-compliant bitstreams, with broadcast infrastructure operators prioritizing real-time performance for live sports. China's MIIT-mandated UHD upgrades concentrate procurement among domestic station groups upgrading satellite and terrestrial transmission chains.
- Decoder:Silicon blocks and firmware implementations unpack compressed streams for display, with smartphone SoC integration accelerating through Qualcomm's premium tier deployments. South Korean consumer electronics manufacturers embed these for domestic 5G content consumption.
- Codec:Complete encoding and decoding software libraries licensed to platform operators seeking cross-platform compatibility.
- Player:End-user applications rendering VVC content across smart TVs, mobile devices, and desktop environments.
Encoder solutions lead volumes today; decoder silicon is gaining share fastest as consumer device refresh cycles accelerate.
Application:
Application segmentation tracks where bitrate efficiency translates directly into operational cost reduction or quality enablement.
- Streaming Services:Subscription and ad-supported platforms deploy VVC to halve CDN egress costs while maintaining 4K and 8K perceptual quality. ByteDance's TikTok and Douyin infrastructure anchors massive-scale short-form transcoding demand.
- Broadcast:Terrestrial, cable, and satellite operators leverage the standard for spectrum efficiency during ATSC 3.0 transitions. US station groups phase encoder readiness into capital cycles aligned with FCC repack timelines.
- Video Conferencing:Enterprise collaboration platforms adopt the codec for bandwidth-constrained remote participation.
- Gaming:Cloud gaming services utilize enhanced compression to reduce latency in interactive streaming scenarios.
Broadcast infrastructure commands the largest installed base; streaming services show the steepest expansion trajectory.
End User:
End user categories reflect diverging procurement sophistication and volume scale across content economy participants.
- Media Companies:Broadcasters, studios, and streaming platforms operate the highest-volume encoding workloads with dedicated infrastructure teams. These buyers negotiate directly with patent pool administrators for licensing terms.
- Enterprises:Corporate video operations, internal communications, and training departments prioritize cost-efficient cloud transcoding over capital-intensive hardware.
- Content Creators:Individual producers and small studios access VVC through software-as-a-service encoding tools.
- Educational Institutions:Universities and online learning platforms deploy the codec for lecture capture and remote instruction delivery.
Media companies dominate current procurement volumes; enterprises are expanding most quickly as hybrid work persists.
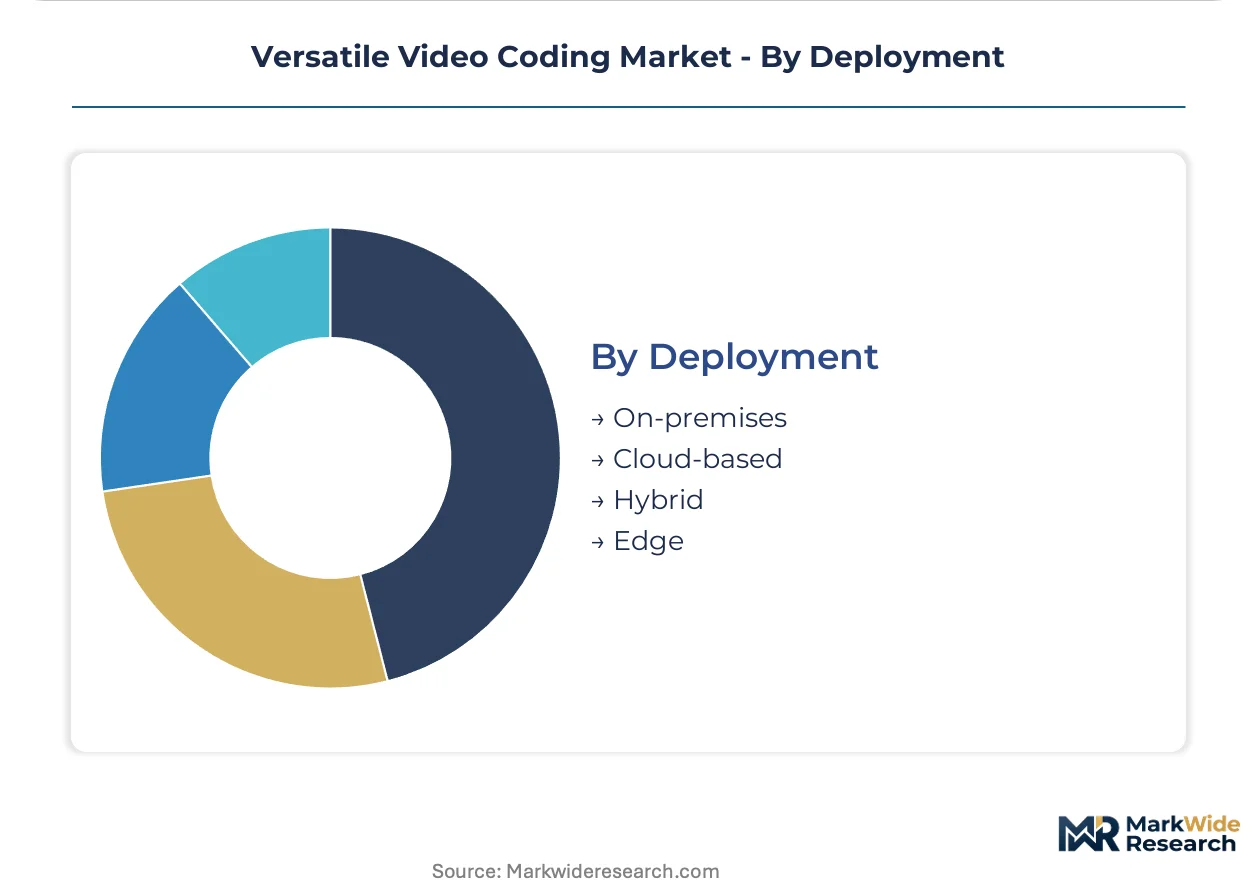
Deployment:
Deployment mode selection separates buyers by capital availability, latency requirements, and workload predictability.
- Cloud-based:Hyperscale transcoding services enable elastic capacity for variable content volumes, with media platforms shifting from fixed encoding farms to usage-based operational expenditure. This model disrupts legacy broadcast equipment suppliers previously capturing recurring maintenance revenue.
- Edge:Distributed encoding nodes position processing closer to consumption points for low-latency live streaming workflows. Sports leagues and live event producers adopt these for remote production pipelines where bandwidth constraints previously limited camera deployment.
- On-premises:Dedicated hardware installations serve broadcasters with predictable schedules and regulatory compliance requirements.
- Hybrid:Mixed deployments combine fixed baseline capacity with cloud burst for peak live events.
Cloud-based deployment leads current adoption; edge infrastructure is climbing the fastest as latency-sensitive use cases multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the most concentrated VVC encoder manufacturing cluster, with domestic component suppliers and firmware developers clustering around Huawei and ZTE supply chains. China's MIIT-mandated ultra-high-definition rollout compresses procurement timelines for broadcast infrastructure operators.
China
MIIT policy directives accelerate domestic encoder procurement for terrestrial and satellite broadcast upgrades. The national ultra-high-definition video industry framework mandates VVC readiness across provincial station groups. Shenzhen and Beijing host the densest concentration of hardware-software integration labs serving state-owned broadcasters.
United States
FCC spectrum repack decisions compress ATSC 3.0 transition windows for station group capital planning. Broadcast incentive auction outcomes shape terrestrial television encoder refresh cycles. Los Angeles and New York media clusters drive early commercial deployment among streaming platform engineering teams.
South Korea
MSIT 5G content mandates prioritize next-generation codec adoption across domestic streaming platforms. National policy frameworks embed VVC decode requirements in smartphone certification protocols. Seoul's Digital Media City anchors R&D collaboration between handset manufacturers and broadcast technology suppliers.
Germany
ARD and ZDF public broadcast procurement specifications influence encoder vendor roadmaps across Central Europe. ETSI interoperability mandates shape decoder conformance testing requirements for consumer electronics. Munich and Berlin concentrate systems integrators serving terrestrial and cable network operators.
Japan
METI broadcasting technology roadmaps coordinate domestic manufacturer alignment with international standardization timelines. NHK 8K satellite transmission trials validate VVC compression performance for next-generation services. Tokyo's Akihabara electronics district remains the primary showcase for decoder chipset commercialization.
Versatile Video Coding Market Competitive Landscape
Patent pool licensing negotiations dominate the current landscape, with Access Advance and MPEG LA positioning divergent royalty structures that stall mass-market silicon commitments. The vendor base segments into three strategic tiers: broadcast heritage equipment suppliers, hyperscale platform operators with captive encoding infrastructure, and mobile chipset architects embedding hardware decode blocks. Two competitive moves define positioning: vertical integration of encoding services into cloud platforms, and cross-licensing alliances to de-risk patent exposure.
Within the broadcast heritage tier, MediaKind and Harmonic occupy positions shaped by live-event encoding workflows and terrestrial transmission infrastructure relationships. Among mobile-optimized silicon architects, Qualcomm Technologies exemplifies premium-tier SoC integration strategies. ByteDance represents the hyperscale platform archetype, anchoring massive-scale transcoding demand through short-form video distribution infrastructure.
| Leading Market Players |
|---|
| MediaKind |
| ByteDance |
| Ateme SA |
| MediaTek Inc. |
| Qualcomm Technologies, Inc. |
| Harmonic Inc. |
| SpinDigital |
| Google LLC |
| MainConcept |
| Others |
Value Network & Pricing Analysis
China's MIIT-mandated UHD broadcast infrastructure upgrades compress procurement timelines for domestic station groups, forcing encoder vendors to absorb component cost volatility or risk losing state-owned contracts to domestic competitors with captive silicon supply.
Pricing Analysis
Input-cost pass-through from advanced node semiconductor fabrication and specialized video processing IP licensing fees structures encoder hardware pricing. Three-tier pricing separates broadcast-grade real-time systems from cloud-elastic transcoding services and entry-level software codecs. Price differentiation hinges on certification level against ETSI conformance suites and volume scale of concurrent encoding channels. Pricing pressure stems from AV1's royalty-free positioning attracting budget-conscious streaming platforms. Enterprise cloud transcoding buyers exhibit highest price sensitivity; premium live-event broadcasters prioritize performance over cost.
Supply Chain Analysis
Advanced video encoder SoC supply rests on Taiwan's foundry capacity, South Korea's memory component ecosystem, and China's domestic assembly and firmware integration clusters. Key inputs include FinFET wafer starts from TSMC and Samsung, high-bandwidth memory stacks from SK Hynix, and specialized entropy coding IP cores. Single-source vulnerability concentrates in leading-edge logic fabrication below 7nm. Distribution runs through direct OEM relationships for broadcast infrastructure and hyperscale cloud marketplaces for elastic transcoding services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Versatile Video Coding operates as a stable compounder anchored by irreversible bandwidth efficiency demands from 4K and 8K streaming proliferation across global content platforms.
For Market Incumbents: Acquire specialized entropy coding engineering teams to consolidate scarce codec optimization talent before patent pool finalization accelerates hiring competition. Incumbents should lock long-term foundry allocation for 5nm and below video processing silicon to secure capacity against fabless entrants. AV1's royalty-free encroachment into mid-tier streaming contracts demands defensive patent portfolio cross-licensing to maintain encoder margin structure. For New Entrants and Emerging Players: South Korea's MSIT 5G content mandates open a window for decoder firmware specialists to penetrate smartphone certification protocols before Qualcomm's premium-tier integration saturates the market. White-space exists in edge computing node deployment for low-latency live sports workflows, where broadcast heritage vendors lack cloud-native software architecture. Target cloud transcoding SaaS tools for mid-market media companies seeking alternatives to hyperscale platform lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with verticalized encoding service providers combining proprietary silicon with captive cloud infrastructure. Long-term viability favors players controlling both patent licensing positions and deployment platform relationships. Patent pool administrator selection between Access Advance and MPEG LA serves as the critical inflection signal for mass-market silicon commitment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Pool Licensing Consolidation | Unified royalty structures unlock consumer electronics decoder commitments from Samsung and Apple. |
| Cloud-Native Encoder Platform Launch | Elastic transcoding capacity captures media company shifts from capital expenditure to operational expenditure models. |
| Edge Computing Node Deployment | Distributed encoding positions processing closer to consumption points for low-latency live streaming workflows. |
| Smartphone SoC Decode Block Integration | Hardware-accelerated VVC penetration accelerates through Qualcomm's premium tier deployments and South Korean certification mandates. |
| Strategic Partnership with Hyperscale Platform | ByteDance's TikTok and Douyin infrastructure anchors massive-scale short-form transcoding demand for codec vendors. |
Research Methodology
Coverage spans China, the United States, South Korea, Germany, and Japan, with primary inputs from each market's broadcast infrastructure operators and semiconductor supply chains. The approach combines primary interviews with codec engineering directors, broadcast technology procurement leads, patent pool licensing administrators, and hyperscale platform infrastructure heads with secondary validation from ITU-T standardization documents, MIIT policy frameworks, FCC spectrum allocation records, and ETSI interoperability specifications. Bottom-up encoder and decoder shipment estimates triangulate against top-down content platform bandwidth expenditure analysis.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon. The analytical framework models segmentation across encoder hardware, decoder silicon, and software codec licensing; deployment modes spanning cloud, edge, on-premises, and hybrid; and end-user categories from media companies through enterprises. CAGRs derive from elasticity modeling of streaming bitrate demand against infrastructure replacement cycles. Forecast inputs incorporate smartphone refresh cycle timing, ATSC 3.0 transition windows, and 5G content mandate compliance deadlines.
Revisions become necessary when patent pool licensing fragmentation resolves unexpectedly, AV1 technical performance achieves parity with VVC for premium content, or major smartphone OEMs delay hardware decode block integration. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hotel Wardrobe Market
Others
Europe Aircraft Lighting Systems Market
Others
Conditional Access System (CAS) Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
France Location-Based Services Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Global Fertility Tracking Apps Market
Others
Duckweed Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Running Apparel Market
Others
Global Magnetic Flow Meters Market
Others
Space Cables Market
Others
Europe Smart Homes Market
Others
Asia-Pacific Intercom Devices Market
Others
Global Application Testing Services Market