
 Managed Testing Services Market | 2026-2036
Managed Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Testing Services Market Foresight
Qualified automation engineering talent is collapsing across North American and European delivery centers, forcing providers to restructure workforce models and accelerate AI-assisted test generation. Capgemini SE sustains competitive advantage through its embedded quality engineering practice within broader transformation contracts. Wipro Ltd anchors its positioning through offshore delivery scale combined with domain specialization in BFSI and telecommunications. Qualitest Ltd differentiates via pure-play testing focus and vertical-specific solution accelerators.
Managed testing services encompass the outsourced planning, execution, and governance of software quality assurance activities performed under recurring contractual arrangements with defined service levels. These engagements typically span functional verification, performance validation, security assessment, and continuous regression cycles across enterprise application portfolios. Functional testing occupies the largest revenue share due to its ubiquity across legacy and modern system landscapes, while security testing registers the fastest expansion as cyber resilience mandates intensify. Cloud-based deployment models are displacing on-premises arrangements as enterprises prioritize elastic infrastructure consumption and distributed team collaboration.
FDA validation requirements for healthcare software, PCI DSS standards governing BFSI payment systems, and FCC network reliability mandates for telecommunications operators collectively elevate compliance-driven testing spend. ISO 27001 and SOC 2 Type II certifications function as gatekeeping credentials that determine provider eligibility for regulated industry contracts. Stakeholders must evaluate whether their testing partners possess demonstrable automation maturity and regulatory domain depth before committing to long-term engagement structures.
Market Dynamics
The migration from waterfall development cycles to continuous integration pipelines is compressing testing timelines and forcing providers to embed automation deeper into delivery architectures. This structural shift rewards partners who can operationalize AI-assisted test generation while maintaining regulatory traceability for healthcare and financial services clients.
Growth Catalysts
- FDA Software Validation Mandates:Healthcare providers face intensified scrutiny of electronic health records and medical device software, driving recurring outsourcing contracts for 21 CFR Part 11 compliance documentation and audit trail verification.
- Cloud-Native Architecture Adoption:Enterprises rebuilding core systems on Kubernetes and serverless platforms require continuous testing pipelines that legacy on-premises tools cannot support, creating replacement demand for elastic, API-first quality engineering services.
- PCI DSS 4.0 Implementation:Payment processors and acquiring banks must demonstrate enhanced authentication testing and encryption validation, expanding security testing budgets across BFSI verticals.
Market Restraints
- Automation Engineer Scarcity:North American and European labor markets face acute shortages of Selenium, Cypress, and Playwright specialists, inflating delivery costs and compressing provider margins.
- Offshore Concentration Risk:India-based delivery centers dominate functional testing execution, exposing clients to geopolitical friction and visa policy volatility that disrupts resource mobility.
- Legacy System Entrenchment:Mainframe and COBOL estates in insurance and banking resist containerization, forcing parallel testing tracks that duplicate effort and extend engagement timelines.
Strategic Opportunities
- EU AI Act Compliance Services:Enterprises deploying machine learning models in European markets require algorithmic bias testing, explainability validation, and conformity assessment documentation that few incumbent providers offer.
- MedTech Embedded Software Testing:Surgical robotics and connected implantable devices create demand for hardware-in-the-loop validation combining functional safety (IEC 62304) with cybersecurity (ISO 27001) certification.
- Outcome-Based Pricing Models:Defect escape rate guarantees and production incident liability shifts are displacing time-and-material contracts, rewarding providers with superior automation maturity and predictive quality analytics.
Industry Challenges
- Test Data Provisioning Complexity:GDPR, HIPAA, and PCI masking requirements restrict production data usage, forcing synthetic data generation investments that slow environment provisioning and inflate infrastructure spend.
- Toolchain Fragmentation:Client-specific preferences for Jira, Azure DevOps, GitLab, or ServiceNow demand costly integration engineering, preventing providers from standardizing delivery templates across accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Testing Services Market |
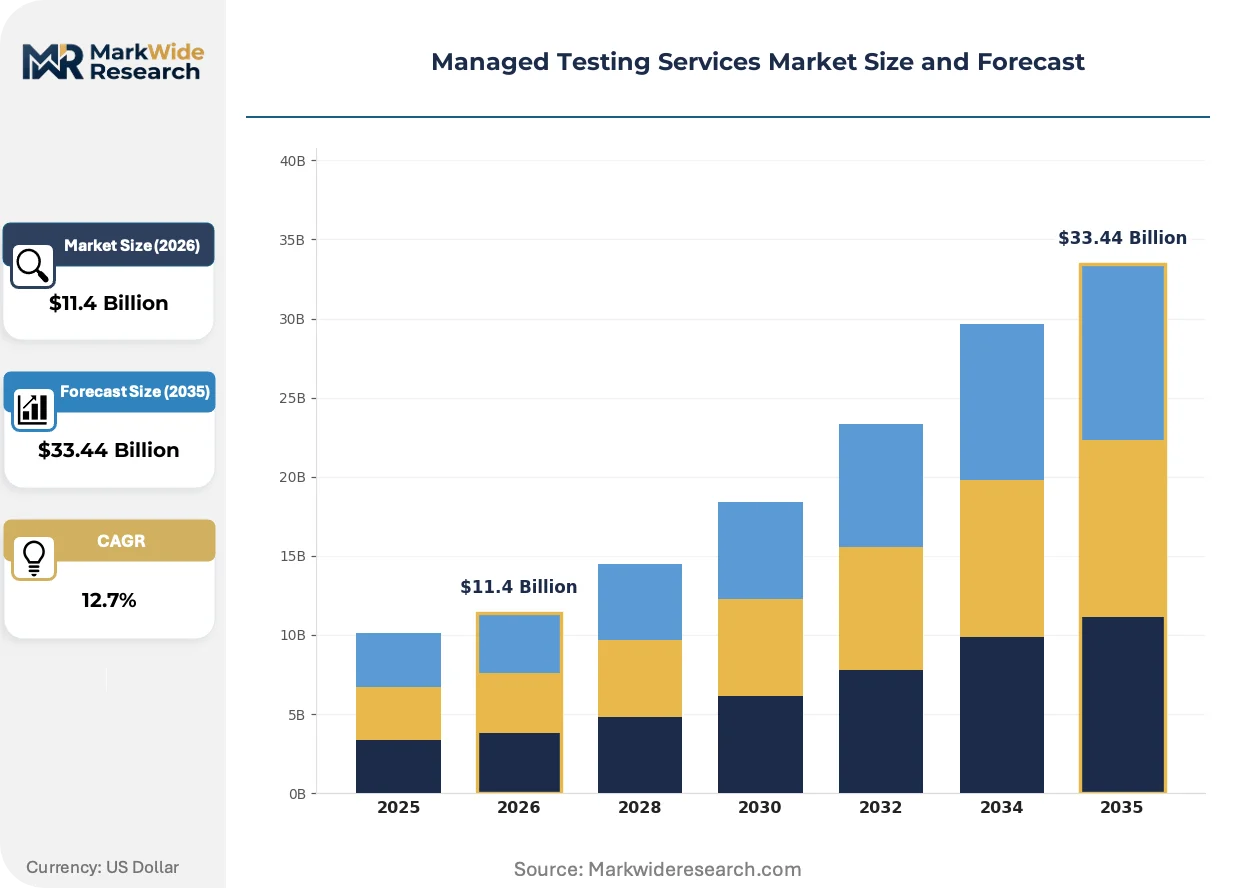
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $33.44 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Functional Testing, Performance Testing, Security Testing, Regression Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote End User: Healthcare, Retail, BFSI, Telecommunications Technology: Automated Testing, Manual Testing, DevOps, Agile |
| Companies Covered | Capgemini SE, Wipro Ltd, Qualitest Ltd, Hexaware Technologies Inc., Testhouse Ltd, Testlio, Microexcel Inc, Codoid, Prolifics Corp Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Testing Services Market Shifts & Advancements
Generative AI is rewriting test asset creation economics while regulatory complexity fragments delivery models across jurisdictions. Providers must simultaneously compress cycle times and harden compliance documentation for regulated verticals.
Self-healing test automation frameworks are displacing script-based Selenium implementations that fracture under frequent UI changes. Retail and e-commerce enterprises with weekly release cadences are adopting machine learning-driven element identification to reduce maintenance overhead. This capability is displacing offshore manual regression teams that previously absorbed change-driven rework.
The EU AI Act's risk classification framework mandates conformity assessments for high-risk automated decision systems, compelling financial services and healthcare enterprises to document testing rigor for algorithmic fairness and robustness. Providers without established AI validation methodologies face exclusion from European public sector and regulated private contracts. German automotive and French healthcare clusters are accelerating procurement of combined functional-AI-security testing bundles.
Enterprise buyers are consolidating vendor relationships from point-tool testing suppliers to integrated quality engineering partners who assume accountability across DevSecOps pipelines. This pattern is displacing discrete project-based engagements in favor of multi-year managed service contracts with outcome-based pricing. United States federal contractors and United Kingdom NHS digital transformation programs exemplify this consolidation trajectory.
Managed Testing Services Market Segmentation
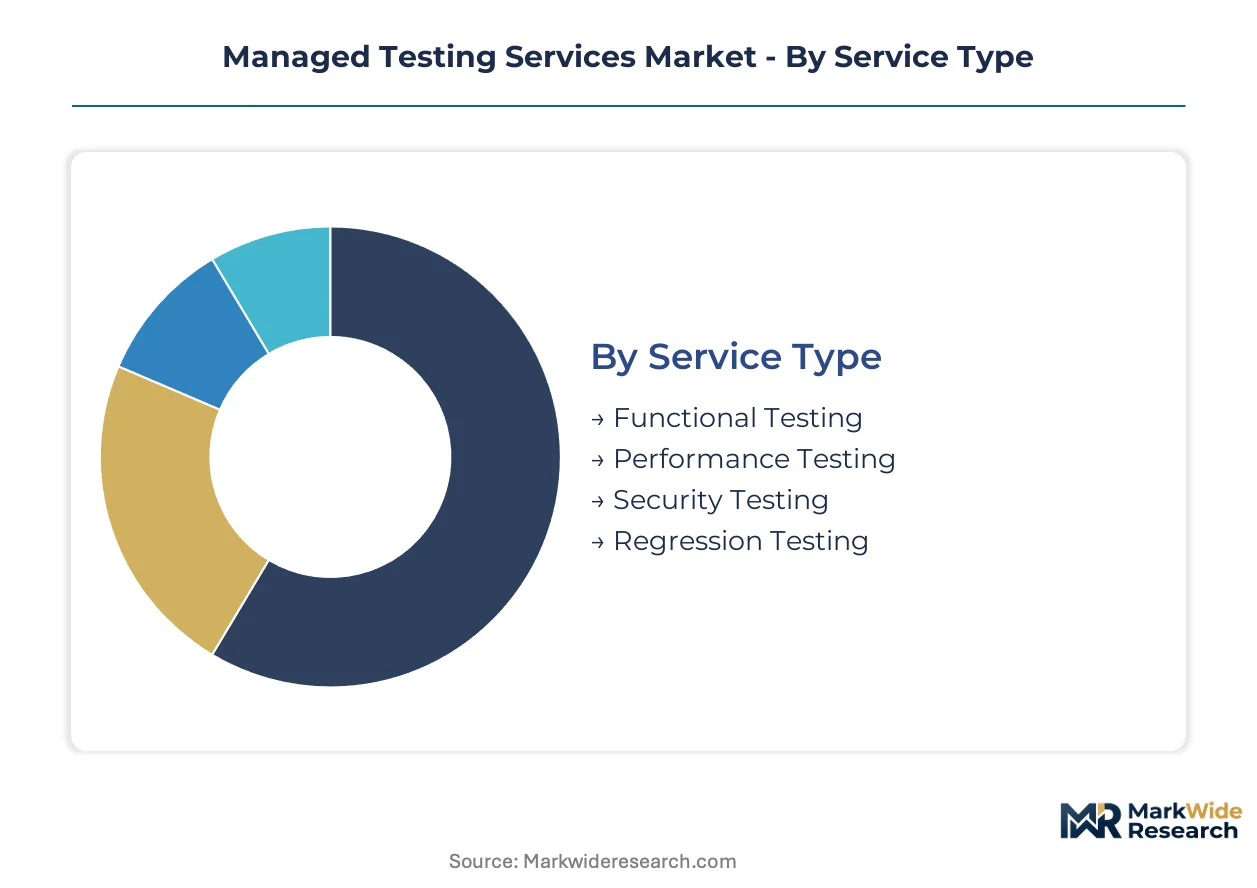
Segmentation in managed testing services reflects divergent compliance burdens and infrastructure modernization timelines across enterprise verticals. Each dimension captures distinct procurement patterns shaped by regulatory stringency, technical debt, and workforce availability.
Service Type:
FDA, PCI DSS, and FCC mandates fragment service demand across validation rigor levels, with healthcare and financial services imposing documentation-heavy requirements that functional testing satisfies while security testing addresses newer cyber resilience rules.
- Functional Testing:Verification of application behavior against specified requirements spans unit, integration, system, and acceptance validation layers. United States healthcare providers concentrate procurement here to satisfy FDA 21 CFR Part 11 audit trail documentation for electronic health records. Mainframe COBOL estates in insurance and banking extend engagement timelines through parallel testing tracks.
- Security Testing:Penetration assessment, vulnerability scanning, and encryption validation address PCI DSS 4.0 authentication mandates. Payment processors and acquiring banks in North America and Europe are expanding budgets for this segment as breach liability frameworks tighten. Synthetic data generation investments slow environment provisioning under GDPR and HIPAA masking rules.
- Performance Testing:Load, stress, and scalability validation for cloud-native architectures on Kubernetes and serverless platforms.
- Regression Testing:Automated re-validation of existing functionality following code changes, critical for weekly retail release cadences.
Functional testing handles the majority of throughput; security testing is expanding most quickly on share.
Deployment Model:
Cost tier differentiation separates elastic consumption from fixed infrastructure commitments, with cloud models capturing DevOps-intensive enterprises while regulated verticals retain on-premises control for audit isolation.
- Cloud-Based:API-first quality engineering services delivered through elastic infrastructure enable distributed team collaboration and continuous integration pipelines. Kubernetes-native testing tools displace legacy on-premises alternatives as enterprises rebuild core systems. Germany automotive clusters and French healthcare procurement favor bundled functional-AI-security testing on cloud platforms.
- Hybrid:Split architectures maintain sensitive data on-premises while leveraging cloud scalability for non-production workloads. Financial services firms in Switzerland and the United Kingdom adopt this model to satisfy FINMA and FCA data residency requirements without sacrificing automation velocity.
- On-Premises:Dedicated infrastructure for regulated environments requiring physical audit trail isolation.
- Remote:Distributed execution models supporting geographically dispersed delivery teams and client personnel.
Cloud-based deployment is gaining share fastest; hybrid models command premium pricing for regulatory flexibility.
End User:
Application complexity and compliance exposure concentrate demand in verticals where software failure carries systemic risk or regulatory penalty.
- Healthcare:Electronic health records, medical device software, and connected diagnostic platforms require IEC 62304 functional safety combined with ISO 27001 cybersecurity certification. Surgical robotics and implantable devices drive hardware-in-the-loop validation demand. FDA validation cycles for 21 CFR Part 11 compliance documentation sustain recurring outsourcing relationships.
- BFSI:Payment systems, core banking platforms, and trading infrastructure face PCI DSS encryption validation and authentication testing mandates. Mainframe estates resist containerization, forcing duplicated testing effort across legacy and modern tracks.
- Retail:E-commerce platforms with weekly release cadences adopt self-healing automation to reduce UI change maintenance overhead.
- Telecommunications:Network reliability mandates from the FCC and equivalent bodies drive continuous monitoring of service availability.
Healthcare captures the steepest expansion trajectory; BFSI maintains the largest installed base of managed testing contracts.
Technology:
Delivery maturity separates script-based legacy implementations from AI-assisted generation, with automation depth determining provider competitiveness and pricing power.
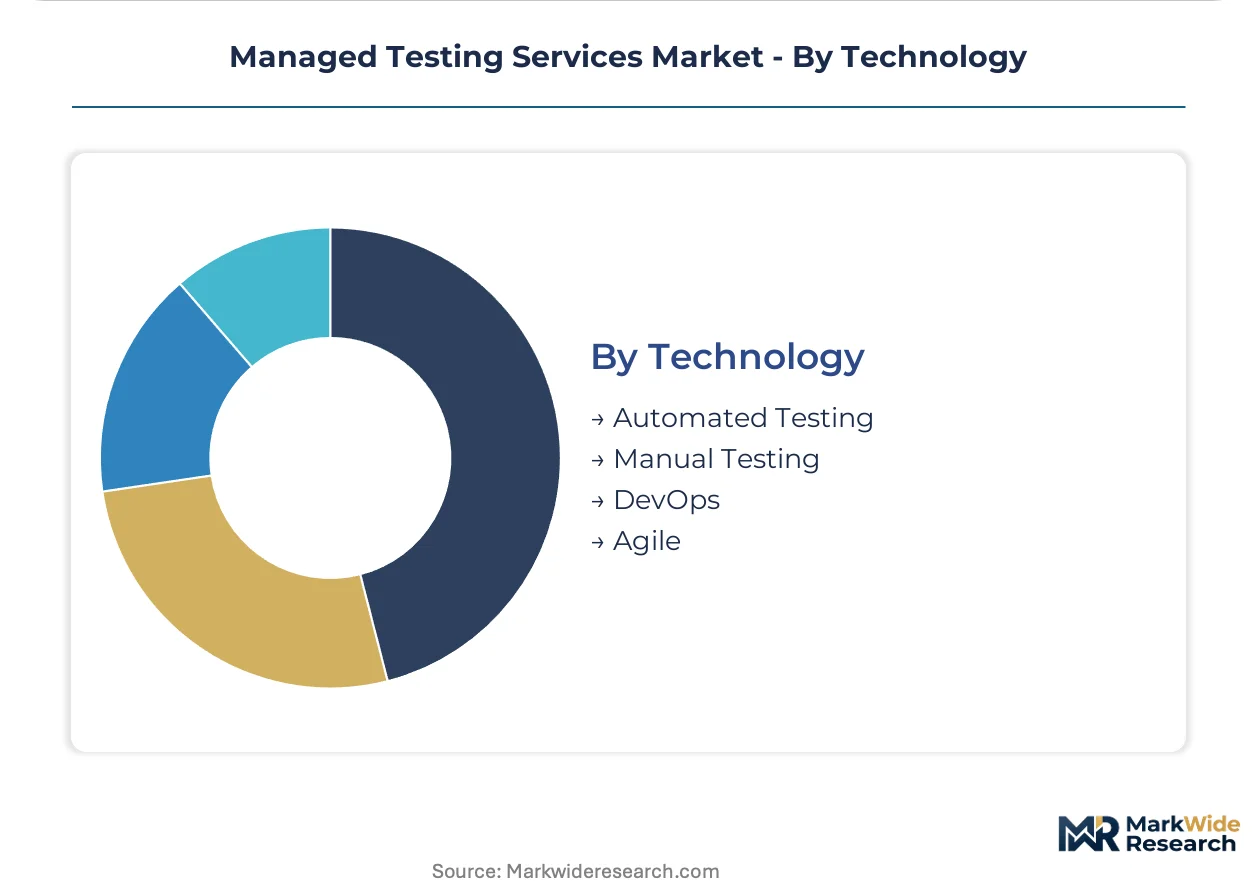
- Automated Testing:Machine learning-driven test generation and self-healing frameworks displace Selenium script maintenance for frequently changing applications. Retail enterprises with compressed release cycles adopt element identification algorithms that reduce offshore manual regression rework. Selenium, Cypress, and Playwright specialist scarcity in North America and Europe inflates delivery costs.
- DevOps:Continuous testing pipeline integration across CI/CD architectures compresses validation timelines from waterfall schedules. This structural shift rewards providers operationalizing AI-assisted generation while maintaining regulatory traceability.
- Agile:Sprint-aligned testing cycles with embedded quality engineering in cross-functional teams.
- Manual Testing:Human-executed validation for exploratory, usability, and edge-case scenarios resisting automation.
Automated testing dominates volume; DevOps integration is climbing the fastest on share as pipeline embedding becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium service consumption in the United States commands pricing multiples exceeding offshore delivery centers in India by significant margins, creating a dual-speed revenue architecture across the managed testing services landscape.
United States
Federal compliance mandates and large-scale digital transformation programs sustain premium demand for outsourced quality assurance. FDA 21 CFR Part 11 validation requirements for electronic health records drive recurring contracts with extensive audit trail documentation obligations. Healthcare technology clusters in Boston and the San Francisco Bay Area concentrate procurement of continuous testing pipelines for cloud-native architectures.
Germany
Automotive and industrial machinery sectors require combined functional-AI-security testing bundles for embedded software systems. EU AI Act conformity assessments for high-risk automated decision systems elevate documentation standards across financial services procurement. Munich and Stuttgart engineering clusters anchor demand for IEC 62304 functional safety certification alongside ISO 27001 cybersecurity validation.
India
Offshore delivery concentration dominates functional testing execution despite geopolitical friction risks. BFSI and telecommunications domain specialization supports cost-competitive service delivery to North American and European clients. Bengaluru and Hyderabad technology corridors house the majority of Selenium and Cypress automation engineering capacity.
United Kingdom
NHS digital transformation programs exemplify vendor consolidation toward integrated quality engineering partnerships. FCA data residency requirements sustain hybrid deployment adoption among financial services firms. London fintech clusters and Manchester health technology hubs drive procurement of DevOps-embedded continuous testing pipelines.
France
Healthcare procurement accelerates adoption of bundled functional-AI-security testing on cloud platforms under EU regulatory pressure. ANSM oversight of medical device software intensifies validation documentation requirements. Paris and Lyon healthcare technology clusters concentrate demand for hardware-in-the-loop validation combining functional safety with cybersecurity certification.
Managed Testing Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the managed testing services market, creating a tiered competitive structure where automation maturity separates premium pricing from commodity execution. The vendor base spans global systems integrators, pure-play testing specialists, and offshore-scale delivery firms with distinct capability profiles. Three strategic archetypes dominate: embedded quality engineering practices within broader transformation contracts, vertical-specific solution accelerators, and offshore delivery scale combined with domain specialization. Competitive positioning hinges on AI-assisted test generation capabilities and regulatory domain depth, with M&A activity targeting automation tooling assets and outcome-based pricing model innovation.
Among the pure-play testing specialists, Qualitest Ltd anchors the vertical-specific accelerator archetype through focused quality engineering positioning. Wipro Ltd represents the offshore-scale delivery model with concentrated presence in BFSI and telecommunications domain expertise. Capgemini SE exemplifies the embedded practice approach, integrating quality engineering within comprehensive transformation engagements. These three firms collectively illustrate the strategic segmentation between automation-led premium positioning and cost-optimized execution scale.
| Leading Market Players |
|---|
| Capgemini SE |
| Wipro Ltd |
| Qualitest Ltd |
| Hexaware Technologies Inc. |
| Testhouse Ltd |
| Testlio |
| Microexcel Inc |
| Codoid |
| Prolifics Corp Ltd |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 compliance documentation gates both supplier qualification and price differentiation simultaneously, separating providers capable of healthcare audit trail verification from commodity testing vendors. ISO 27001 and SOC 2 Type II certifications function as tiering mechanisms that concentrate pricing power among firms with established regulatory domain depth.
Pricing Analysis
Configured-to-order pricing for FDA-validated healthcare engagements commands substantial premiums over standard functional testing packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation maturity and vertical specialization, with AI-assisted test generation capabilities anchoring the top tier. Cost compression in the standard tier is intensifying because Selenium and Cypress specialist scarcity inflates delivery costs across North American and European centers. Healthcare providers demonstrate the lowest price sensitivity due to liability exposure, while retail enterprises with weekly release cadences prioritize cost efficiency over compliance documentation.
Supply Chain Analysis
Just-in-time talent deployment dominates the industry, with providers maintaining bench capacity in India while activating specialized automation engineers on-demand for client-specific toolchains. India, the United States, and Germany anchor supply concentration, with Bengaluru and Hyderabad housing the majority of offshore execution capacity. Delivery architecture draws from proprietary testing frameworks, open-source automation libraries, and synthetic data generation platforms. Single-source vulnerability concentrates in India-based functional testing execution, exposing clients to visa policy volatility. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act conformity assessments for high-risk automated decision systems disrupt established competitive positioning, creating acquisition opportunities for providers with algorithmic bias testing capabilities.
For Market Incumbents: Consolidate automation tooling assets through targeted acquisitions of self-healing framework specialists. Capgemini SE and Wipro Ltd should deepen captive AI-assisted test generation capabilities before emerging pure-play challengers achieve scale. Defensive patent positioning around regulatory traceability technology protects margin structures in healthcare and BFSI verticals.
For New Entrants and Emerging Players: ISO 27001 fast-track certification unlocks European healthcare procurement channels currently dominated by incumbent systems integrators. Algorithmic fairness validation for financial services represents the most penetrable white-space segment, with German automotive clusters and French healthcare providers accelerating bundled functional-AI-security testing procurement. Cloud-native quality engineering partnerships with Kubernetes platform vendors provide credible go-to-market positioning.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward providers with established AI validation methodologies and European regulatory presence. Five-to-ten-year viability favors firms combining automation maturity with vertical-specific solution accelerators. Target acquisition archetypes include pure-play testing specialists with healthcare domain depth and self-healing framework IP. The signal to watch is NHS digital transformation program vendor consolidation patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI-Assisted Test Generation Specialist | Self-healing frameworks displace Selenium maintenance for retail clients with compressed release cycles. |
| EU AI Act Compliance Service Launch | Algorithmic bias testing opens German automotive and French healthcare procurement channels. |
| Outcome-Based Pricing Model Implementation | Defect escape rate guarantees displace time-and-material contracts in United States federal healthcare. |
| Hardware-in-the-Loop Validation Partnership | Surgical robotics testing combines IEC 62304 functional safety with ISO 27001 cybersecurity certification. |
| Hybrid Deployment Infrastructure Investment | Split cloud-on-premises architectures satisfy FINMA and FCA data residency without sacrificing automation velocity. |
Research Methodology
A spread of perspectives from quality engineering directors, healthcare IT procurement officers, DevOps platform engineers, and regulatory compliance leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation across SEC 10-K filings, FDA 510(k) submission databases, EU MDR conformity assessment records, and hyperscaler partnership announcements. Bottom-up service line revenue analysis triangulated against top-down market sizing from automation tooling vendor disclosures.
Segmentation dimensions modeled span service type, deployment model, end-user vertical, and automation technology maturity across the projection horizon. CAGRs were derived from regression analysis of historical outsourcing contract values and forward-looking procurement pipeline indicators. Cloud migration velocity, DevOps pipeline adoption rates, and regulatory validation cycle frequency served as industry-specific forecast inputs.
Underlying assumptions cover sustained healthcare compliance outsourcing demand and cloud-native architecture replacement cycles, with deviation risk concentrated in automation engineer labor market tightening and geopolitical friction affecting India-based delivery mobility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Smartphone Market
Others
Latin America 3D Printing Construction Market
Others
Safety Critical Software Testing Market
Others
North America Machine Vision Systems Market
Others
Vo5g Market
Others
Rope Market
Others
North America Video Conferencing Hardware Market
Others
Space Cables Market
Others
Global Laser Defense Eyewear Market
Others
Drum Motor Market
Others
Chip Card Scanners Market
Others
Global Active Speaker Market
Others
Europe Meditation Market
Others
Global Hardware Acceleration Market
Others
Mexico 3D Printing Construction Market
Others
Japan Smart Home Market