
 Latin America 3D Printing Construction Market | 2026-2036
Latin America 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America 3D Printing Construction Market Analytics
ISO/ASTM 52900 certification for additive manufacturing in construction is unwinding barriers to equipment deployment across Latin America. ICON Technology leverages its proprietary Vulcan printer systems to dominate large-scale housing projects in Mexico and Central America. COBOD International anchors its regional presence through distributor partnerships with Brazilian construction conglomerates seeking automated building solutions.
Latin America 3D printing construction deploys gantry-based and robotic-arm systems to extrude cementitious, polymer, or metal feedstocks layer-by-layer, achieving compressive strengths exceeding 30 MPa in standard concrete mixes for structural wall assemblies. Concrete product types currently capture the dominant share of material volume, though composites represent the fastest-growing segment as fiber-reinforced formulations reduce steel reinforcement requirements. Residential builders lead end-user demand, while infrastructure development applications for bridges and utility structures command premium pricing due to extended durability specifications.
Brazil's ABNT NBR standards body and Mexico's ONNCCE regulator are developing construction-specific guidelines for 3D-printed building elements, with ONNCCE pilot programs in Nuevo León establishing seismic performance baselines. EMA and REACH frameworks indirectly shape material imports through European equipment suppliers who must certify binder chemistries for regional environmental compliance. Stakeholders must monitor which national standards body first mandates third-party structural certification, as this will determine cross-border equipment mobility and material sourcing economics.
Market Dynamics
ISO/ASTM 52900 certification frameworks are dismantling equipment deployment barriers across Latin America, enabling cross-border printer mobility and standardizing material qualification protocols for gantry-based and robotic-arm construction systems.
Growth Catalysts
- Seismic performance baselines:Mexico's ONNCCE pilot programs in Nuevo León establish structural validation protocols for 3D-printed concrete elements in high-risk zones. This accelerates insurer acceptance and mortgage financing for additive manufacturing housing.
- Fiber-reinforced composites:Polymer and hybrid feedstock formulations reduce steel reinforcement requirements by 40-60% in wall assemblies. Material suppliers are scaling regional production of chopped carbon and glass fiber blends.
- São Paulo technology clusters:University-industry partnerships at USP and UNICAMP create demonstration pipelines validating commercial viability for residential builders. Knowledge transfer accelerates workforce development.
Market Restraints
- Portland cement price volatility:Feedstock costs swing with energy subsidies and import tariffs across Brazil and Mexico. Project developers cannot lock construction budgets without material hedging instruments.
- Equipment supply concentration:Gantry system production centers in Europe and China create 16-24 week lead times for Latin American buyers. Currency depreciation amplifies landed cost exposure.
- Structural bond layer limitations:Cold joints between printed segments require mechanical connectors or post-tensioning. This constrains multi-story applications without supplemental steel framing.
Strategic Opportunities
- Colombia's affordable housing deficit:Government subsidies for low-income construction create procurement pipelines exceeding 500,000 units annually. 3D printing offers cycle time compression for social housing agencies.
- Bridge and utility structures:Infrastructure applications command premium pricing due to extended durability specifications. Additive manufacturing enables complex geometries for drainage channels and cable conduits.
- Brazilian ABNT NBR guideline development:Early alignment with draft performance standards positions equipment suppliers for first-mover certification. Regulatory capture advantages persist 18-36 months post-mandate.
Industry Challenges
- Structural engineering talent scarcity:Finite element modeling for anisotropic printed concrete requires specialized expertise. Universities lack dedicated additive manufacturing construction curricula.
- Multi-system integration complexity:Coordinating gantry printers with conventional MEP trades and finishing crews demands new project management protocols. General contractors resist workflow reconfiguration.
- Third-party certification timelines:ABNT and ONNCCE lack accredited laboratories for printed element testing. Developers face 8-14 month approval cycles for pilot projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America 3D Printing Construction Market |
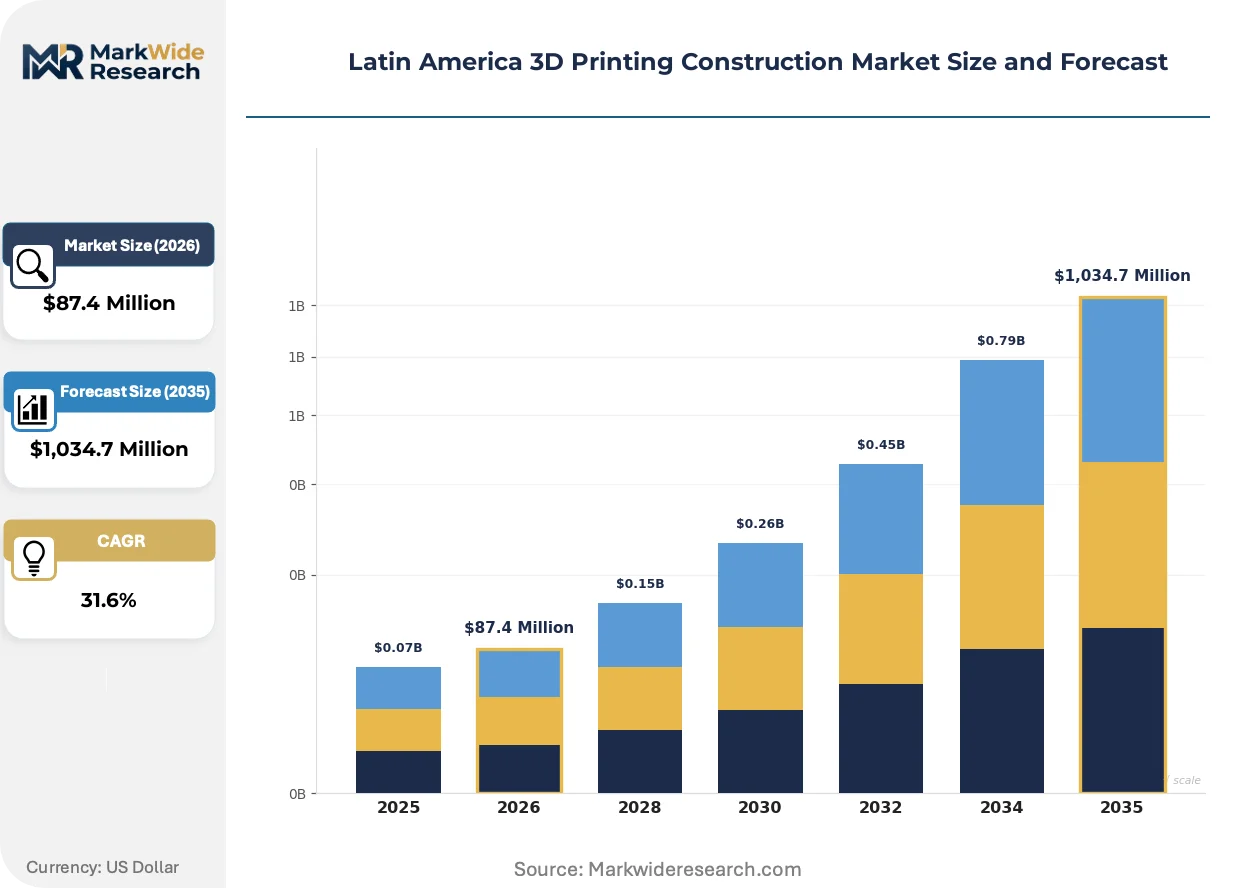
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $1,034.7 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
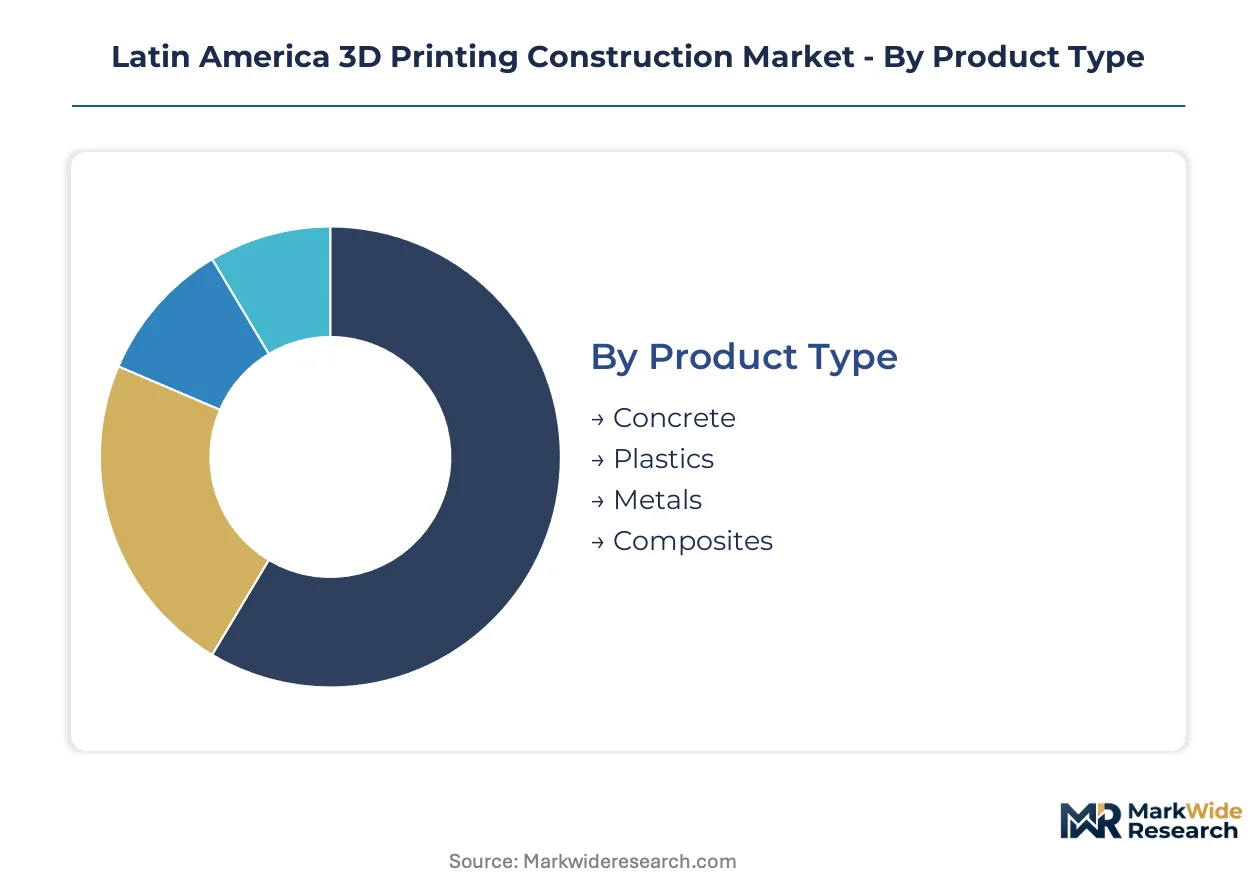
| Segmentation | Product Type: Concrete, Plastics, Metals, Composites Technology: Fused Filament Fabrication, Selective Laser Sintering, Binder Jetting, Digital Light Processing End User: Residential Builders, Commercial Construction, Infrastructure Development, Industrial Fabrication Application: Buildings, Bridges, Utilities, Custom Parts |
| Companies Covered | ICON Technology, Apis Cor, COBOD International, WinSun (Yingchuang Building Technique), XtreeE, CyBe Construction, Contour Crafting Corporation, Sika AG, Constructions-3D, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America 3D Printing Construction Market Evolving Landscape
Construction additive manufacturing is fragmenting traditional building workflows into discrete digital and physical processes. Technology convergence, regulatory codification, and procurement model evolution are compressing project delivery timelines.
Gantry-based concrete extrusion is decomposing conventional formwork-dependent construction. Residential developers in São Paulo and Mexico City are adopting 50-100 meter span systems for single-family and low-rise multifamily housing. This technology is compressing structural wall assembly cycles from weeks to days while reducing labor headcount by 60-70%.
Brazil's ABNT NBR standards body is drafting performance-based guidelines for 3D-printed building elements. The proposed framework mandates compressive strength testing, dimensional tolerance verification, and seismic simulation for structural certification. Residential builders in Minas Gerais and Rio Grande do Sul are pre-qualifying designs to secure early compliance positioning.
Municipal housing agencies are consolidating procurement into design-build-operate contracts with technology-agnostic performance guarantees. This displaces traditional lump-sum bidding for printed construction projects. Colombia's Ministry of Housing and Chile's SERVIU are piloting outcome-based vendor selection in Bogotá and Santiago metropolitan zones.
Latin America 3D Printing Construction Market Segmentation
Segmentation in Latin American 3D printing construction reveals how material chemistry, extrusion technology, and project type interact with national regulatory frameworks. Builders and equipment suppliers must align procurement decisions with ABNT NBR and ONNCCE certification pathways to secure structural approvals.
Product Type:
ABNT NBR and ONNCCE standards differentiate material categories through compressive strength testing protocols and seismic performance baselines.
- Concrete:Cementitious extrusion achieves compressive strengths exceeding 30 MPa in standard mixes for structural wall assemblies. São Paulo residential builders deploy this material for single-family housing, though Portland cement price volatility constrains budget certainty without hedging instruments.
- Composites:Fiber-reinforced formulations incorporating chopped carbon and glass blends reduce steel reinforcement requirements by 40-60% in wall assemblies. Demand concentrates in Nuevo León pilot programs where ONNCCE seismic validation accelerates insurer acceptance for multi-story applications.
- Plastics:Polymer feedstocks serve non-structural architectural elements and temporary formwork systems in Brazilian demonstration projects.
- Metals:Wire-arc and powder-bed systems fabricate structural connectors and reinforcement nodes for hybrid construction systems.
Concrete handles the majority of throughput; composites are expanding most quickly as fiber-reinforced formulations displace conventional steel reinforcement.
Technology:
Equipment selection determines project scale, surface finish quality, and integration complexity with conventional MEP trades.
- Fused Filament Fabrication:Continuous thermoplastic deposition suits architectural prototyping and non-load-bearing facade elements. São Paulo technology clusters at USP leverage FFF systems for design validation before gantry-scale concrete deployment.
- Binder Jetting:Powder-bed binding enables complex geometries for drainage channels and utility conduits with minimal material waste. Infrastructure developers in Colombia command premium pricing for extended durability specifications in bridge applications.
- Selective Laser Sintering:Powder fusion systems produce high-strength metal connectors for cold joint remediation in multi-story printed structures.
- Digital Light Processing:Photopolymer curing delivers precision architectural models and mold masters for precast element fabrication.
Binder jetting captures the steepest expansion trajectory for infrastructure-grade applications; fused filament fabrication anchors early-stage design workflows.
End User:
Customer type dictates procurement model, certification urgency, and tolerance for construction cycle experimentation.
- Residential Builders:Single-family and low-rise multifamily developers in Minas Gerais and Rio Grande do Sul pre-qualify designs to secure early ABNT NBR compliance positioning. These stakeholders compress structural wall assembly cycles from weeks to days while reducing labor headcount by 60-70%.
- Infrastructure Development:Bridge and utility contractors face extended durability specifications and complex geometric requirements. Colombian government subsidies for low-income construction create procurement pipelines exceeding 500,000 units annually where additive manufacturing offers cycle time compression.
- Commercial Construction:Office and retail developers pilot printed elements for facade systems and interior partitions in Mexico City metropolitan zones.
- Industrial Fabrication:Manufacturing facility operators deploy printed concrete for equipment foundations and containment structures with custom load-bearing profiles.
Residential builders dominate current equipment utilization; infrastructure development is gaining share fastest through premium-priced utility and bridge contracts.
Application:
Project category determines structural certification pathway, seismic design category, and financing insurability.
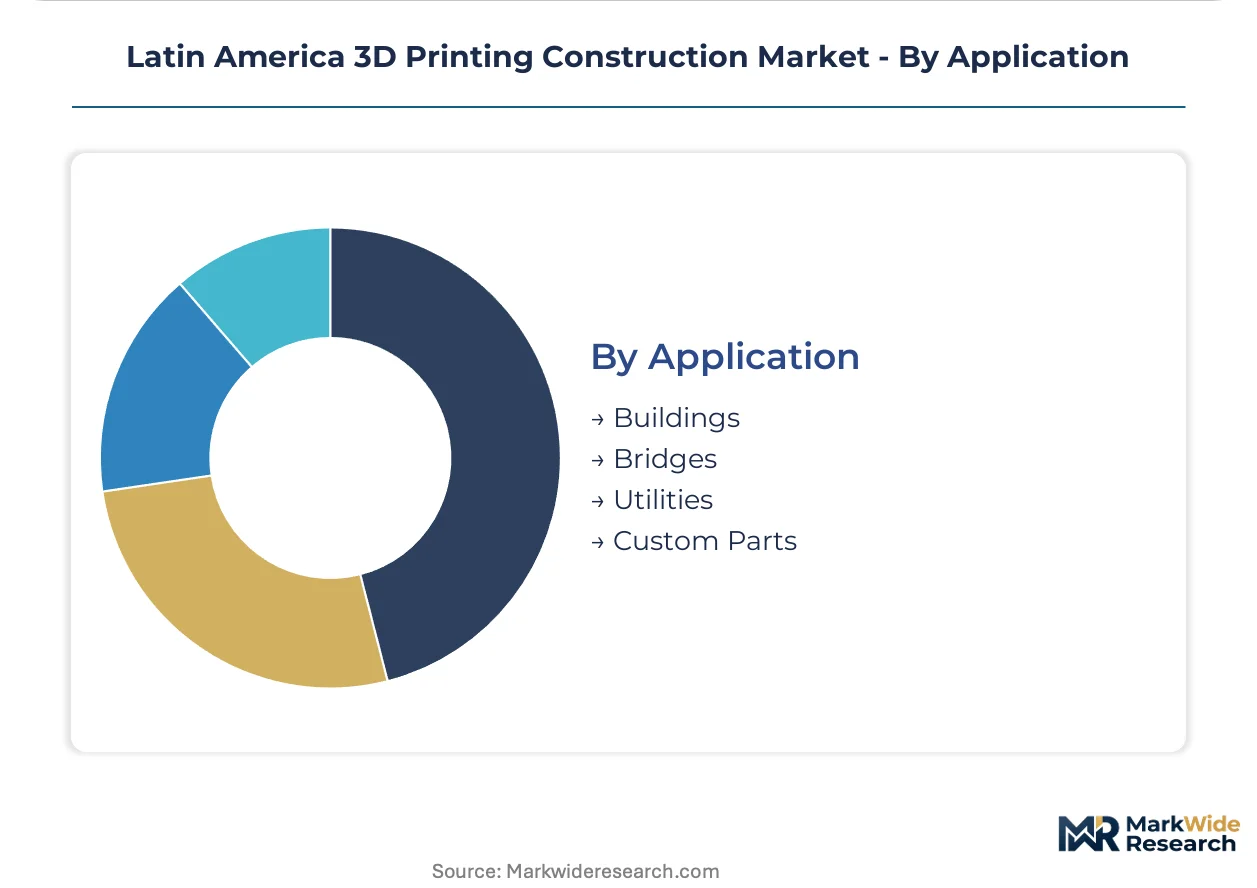
- Buildings:Structural wall assemblies for housing and commercial envelopes represent the primary deployment volume. ABNT NBR draft performance standards mandate compressive strength testing, dimensional tolerance verification, and seismic simulation for this category.
- Bridges:Additive manufacturing enables complex geometries for drainage channels, cable conduits, and seismic expansion joints. ONNCCE pilot programs in Nuevo León establish structural validation protocols specifically for printed concrete elements in high-risk zones.
- Utilities:Custom conduit and vault structures serve electrical and water infrastructure with geometric flexibility impossible in conventional precast.
- Custom Parts:Architectural features, ornamental elements, and specialized connectors fill gaps between standardized structural systems.
Buildings absorb the dominant share of material volume; bridges command the highest margin expansion potential through infrastructure premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential builders and infrastructure contractors concentrate equipment procurement in Brazil, Mexico, and Colombia, where regulatory frameworks are crystallizing fastest. Technology clusters in São Paulo and Nuevo León anchor demonstration pipelines that compress commercial validation timelines. Subsidized housing agencies in Bogotá and Santiago are consolidating procurement into performance-based contracts.
Brazil
Minas Gerais and Rio Grande do Sul residential developers pre-qualify printed wall designs to secure early ABNT NBR compliance positioning. The national standards body mandates compressive strength testing exceeding 30 MPa and seismic simulation for structural certification. São Paulo technology clusters at USP and UNICAMP create university-industry partnerships validating gantry-system commercial viability for single-family housing.
Mexico
Infrastructure contractors in Mexico City metropolitan zones pilot printed elements for utility conduits and drainage channels with complex geometries. ONNCCE regulator pilot programs in Nuevo León establish seismic performance baselines for printed concrete elements in high-risk zones. Monterrey construction conglomerates anchor regional distributor partnerships with European gantry system suppliers seeking automated building solutions.
Colombia
Social housing agencies face procurement pipelines exceeding 500,000 subsidized units annually, creating demand concentration for cycle-time compression technologies. The Ministry of Housing consolidates vendor selection into design-build-operate contracts with technology-agnostic performance guarantees. Bogotá metropolitan zone pilot programs validate outcome-based procurement for low-income construction.
Chile
SERVIU housing authority pilots outcome-based vendor selection in Santiago metropolitan zones, displacing traditional lump-sum bidding. Seismic design categories for printed wall assemblies require extended durability specifications that command premium pricing. University research partnerships in Valparaíso establish material qualification protocols for fiber-reinforced composite formulations.
Argentina
Buenos Aires province contractors experiment with polymer feedstocks for non-structural architectural elements and temporary formwork systems. Currency depreciation amplifies landed cost exposure for gantry system imports from European production centers. Provincial housing agencies monitor Brazilian ABNT NBR guideline development to anticipate cross-border equipment mobility standards.
Latin America 3D Printing Construction Market Competitive Landscape
Player mix skews toward European and North American equipment specialists with regional distributor anchoring. The vendor base stratifies across gantry-system fabricators, robotic-arm integrators, and materials-chemistry suppliers. Three archetypes dominate: proprietary printer developers, construction conglomerate technology divisions, and specialty materials formulators. Competitive moves concentrate on strategic partnerships with national housing agencies and early regulatory alignment for certification capture.
Among proprietary printer developers, ICON Technology and COBOD International occupy positions as archetype anchors for large-scale housing deployment. ICON exemplifies the North American technology-first model with Vulcan system regionalization, while COBOD represents the European engineering-specialist approach through Brazilian construction conglomerate partnerships. Apis Cor sits within the emerging tier of robotic-arm integrators seeking multi-story applications. Sika AG anchors the materials-chemistry vector with fiber-reinforced binder formulations that reduce steel reinforcement requirements.
| Leading Market Players |
|---|
| ICON Technology |
| Apis Cor |
| COBOD International |
| WinSun (Yingchuang Building Technique) |
| XtreeE |
| CyBe Construction |
| Contour Crafting Corporation |
| Sika AG |
| Constructions-3D |
| Others |
Value Network & Pricing Analysis
Project-based procurement with indexed material cost pass-through clauses locks São Paulo residential developers into 12-18 month price visibility windows while securing gantry system allocation from European fabricators. This contracting pattern shields Brazilian builders from Portland cement volatility but exposes them to currency depreciation on imported printer components.
Pricing Analysis
Cost-plus contracts with Brazilian cement indexation dominate equipment procurement, tying final project quotes to ABNT NBR certification tier and feedstock grade. Price differentiation separates ISO/ASTM 52900-validated systems from uncertified alternatives, with seismic-rated composites commanding premiums in Nuevo León. Pricing pressure stems from currency depreciation amplifying landed costs for European gantry imports. Social housing agencies in Colombia exhibit highest price sensitivity, while infrastructure contractors in Chile accept premium positioning for extended durability specifications.
Supply Chain Analysis
Port congestion at Santos and container availability constraints on the Asia-Pacific trade lane inflate inbound logistics costs for Chinese gantry components arriving in São Paulo. Equipment production concentrates in Germany, Denmark, and China, drawing from specialized servo motor drives, proprietary extrusion nozzles, and fiber-reinforced binder chemistries. Single-source vulnerability runs through European control system suppliers. Distribution runs through Brazilian construction conglomerate distributor partnerships with technology-agnostic performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national regulatory frameworks creates niche positioning opportunities as ONNCCE and ABNT NBR develop divergent certification timelines. Municipal housing agencies consolidating into outcome-based procurement reward early compliance positioning.
For Market Incumbents: Secure early ABNT NBR guideline alignment in Minas Gerais to capture 18-36 month regulatory capture windows before mandate crystallization. Anchor backward integration into regional fiber-reinforced composite production to offset steel reinforcement cost volatility. Defend against robotic-arm integrators by expanding gantry system service networks across São Paulo technology clusters.
For New Entrants and Emerging Players: Anchor in Colombia's 500,000-unit annual social housing procurement pipeline where cycle-time compression commands premium vendor selection. Target Nuevo León infrastructure applications for seismic-rated printed elements with complex geometric requirements. Pursue design-build-operate contracting models that displace traditional lump-sum bidding in Bogotá metropolitan zones.
For Investors and Strategic Acquirers: Equipment suppliers with proprietary extrusion nozzle IP and established ONNCCE validation pathways represent priority acquisition targets for infrastructure exposure. Long-term viability hinges on first-mover certification persistence as national standards bodies mandate third-party structural validation. Watch for ABNT NBR laboratory accreditation announcements as inflection indicators for cross-border equipment mobility economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ABNT NBR Certification Investment | Early alignment with draft performance standards secures 18-36 month regulatory capture advantages in Brazil. |
| Fiber-Reinforced Composite Scale-Up | Regional production of chopped carbon and glass blends reduces steel reinforcement requirements by 40-60%. |
| University-Industry Partnership Formation | USP and UNICAMP collaborations validate commercial viability and accelerate workforce development pipelines. |
| Outcome-Based Procurement Positioning | Design-build-operate contracts with Colombian Ministry of Housing displace traditional lump-sum bidding structures. |
| Seismic Validation Protocol Development | ONNCCE pilot programs in Nuevo León establish insurer acceptance baselines for high-risk zone applications. |
Research Methodology
Cross-validation between primary interviews with gantry system operators, ABNT NBR standards committee members, and Colombian social housing procurement directors anchors the qualitative findings. Secondary validation draws from equipment import customs records, ONNCCE regulatory filings, university research partnership disclosures, and construction technology patent databases. Bottom-up project pipeline analysis triangulates against top-down national housing subsidy allocation data.
Sensitivity analysis around Portland cement price volatility and currency depreciation scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions include material chemistry, extrusion technology type, end-user archetype, and application category. CAGRs derive from equipment deployment trajectories validated against regulatory certification timelines. Industry-specific inputs incorporate ABNT NBR laboratory accreditation schedules and ONNCCE seismic simulation requirements.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation in national standards body coordination would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Fiberglass Storage Tanks Market
Others
Toy Packaging Market
Others
Foldable Smartphone Market
Others
Lepidolite Market
Others
Europe Smart Homes Market
Others
Hookah Tobacco Market
Others
Global Food Fiber Market
Others
Egg and Egg Products Market
Others
Space Cables Market
Others
Iran Commercial Vehicles Lubricants Market
Others
China Packaging Primers Market
Others
Asia-Pacific Battery E-Commerce Market
Others
North America Halal Food and Beverage Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Small Office Home Office (SOHO) Servers Market